
 China Dairy Alternatives Market | 2026-2036
China Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
China Dairy Alternatives Market Insights
Multi-source procurement of raw materials is recalibrating how domestic brands secure oat and almond supplies. Hebei Yangyuan Zhihui leverages its walnut-processing heritage to dominate northern distribution corridors. Vitasoy International anchors its portfolio with soy-based formulations that sustain decades of brand recognition. Danone competes through specialized fermentation expertise applied to plant-based yogurt alternatives.
China dairy alternatives encompass non-beverage formulations derived from plant proteins, typically containing 2-8% protein content, homogenized at 150-200 bar to achieve mouthfeel parity with cow milk, serving both direct consumption and industrial food manufacturing applications. Plant-based milk occupies the largest volume position while oat sourcing demonstrates the fastest structural expansion. Foodservice channels concentrate premium margin pools as restaurants and cafés in tier-one cities drive format innovation.
SAMR enforces GB standards for plant protein beverage labeling while MEE implements dual carbon goals that constrain water-intensive almond cultivation. China's national health regulator scrutinizes additive thresholds in vegan cheese formulations. Stakeholders must monitor how evolving GB standard revisions and provincial carbon quotas reshape raw material sourcing economics and product certification pathways.
Market Dynamics
Dual carbon goals from MEE are compressing water-intensive supply chains while SAMR labeling mandates force ingredient transparency upgrades across domestic manufacturing bases.
Growth Catalysts
- Dual carbon policy enforcement:MEE carbon quotas accelerate oat sourcing substitution for water-heavy almond cultivation. Domestic brands pivot procurement toward northern Chinese oat cooperatives.
- Foodservice channel expansion:Tier-one city cafés and restaurant chains drive premium oat latte and almond milk tea formats. Shanghai barista competitions showcase plant-based foam stability as a competitive differentiator.
- Young urban consumer pivot:Beijing and Shanghai millennials reject lactose-heavy traditional diets. Social media wellness influencers amplify protein-fortified plant beverage visibility.
Market Restraints
- Input cost volatility:Imported almond prices fluctuate with California drought cycles and shipping lane congestion. Domestic processors face margin compression during water-scarce harvest seasons.
- Supply concentration risk:Premium oat varieties depend on limited Nordic and Canadian germplasm licensing. Chinese breeders lack proprietary high-beta-glucan cultivars for beverage-grade applications.
- Technical mouthfeel limitations:Homogenization at 150-200 bar fails to replicate dairy fat globule distribution. Clean-label emulsifier alternatives struggle with thermal stability in UHT processing.
Strategic Opportunities
- Underpenetrated inland cities:Chengdu and Xi'an foodservice channels show nascent oat beverage adoption. Early entrants capture premium positioning before competitive saturation.
- Industrial ingredient supply:Bakery and confectionery manufacturers seek standardized plant protein concentrates. B2B formulation services lock in multi-year supply contracts.
- GB standard revision tailwinds:SAMR plant protein beverage category definitions create certification pathways for novel legume and seed milk variants. First-movers secure label claim advantages.
Industry Challenges
- Food technologist scarcity:Formulation chemists with UHT plant protein stability expertise command premium salaries. Universities lack dedicated plant-based dairy curriculum pipelines.
- Clean-label certification timelines:Third-party vegan and non-GMO audits extend six to nine months. Product launch schedules compress against competitor speed-to-market pressures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Dairy Alternatives Market |
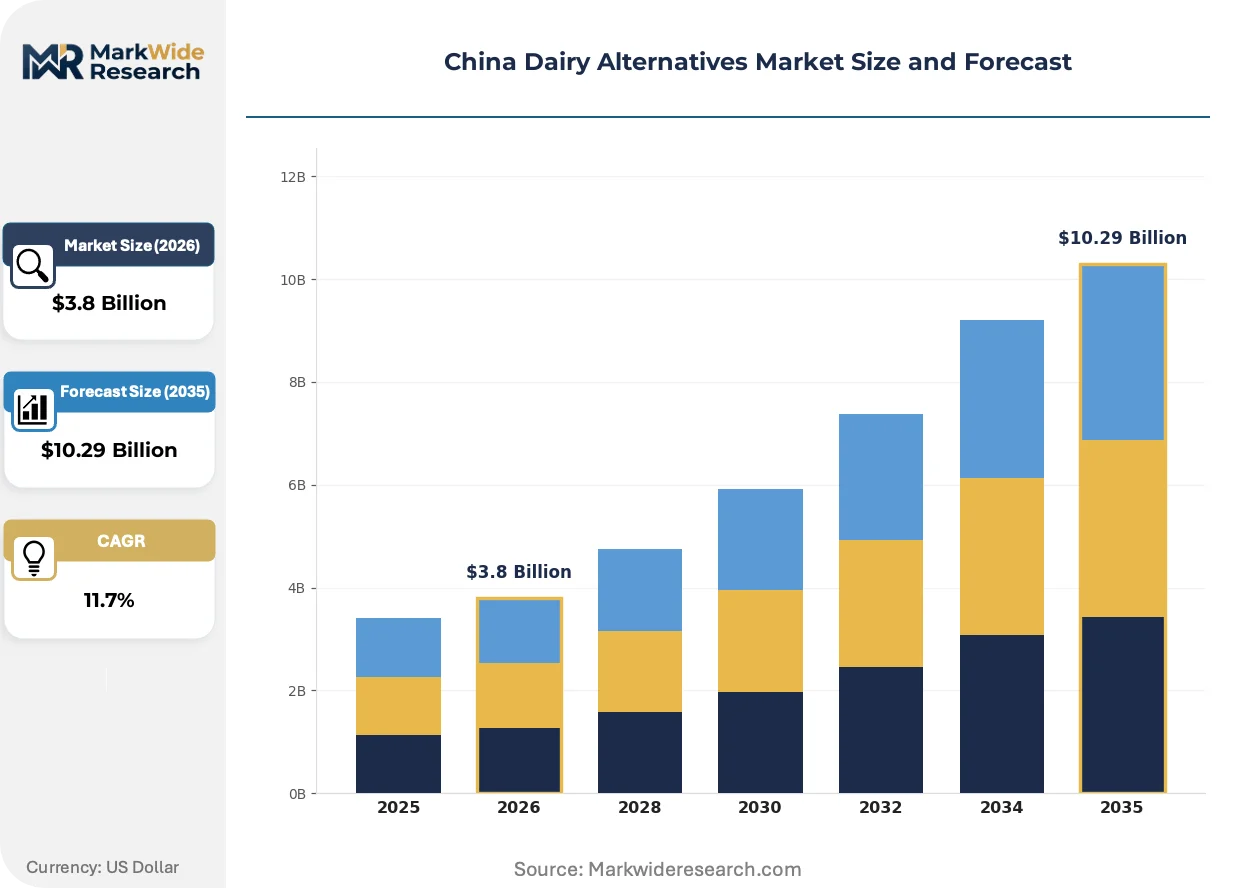
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Milk, Vegan Cheese, Yogurt Alternatives, Creamers Source: Almond, Soy, Coconut, Oat Distribution Channel: Online Retail, Supermarkets, Health Stores, Foodservice End User: Consumers, Restaurants, Cafés, Food Manufacturers |
| Companies Covered | Hebei Yangyuan Zhihui Beverage Co. Ltd, Vitasoy International Holdings Ltd, Danone S.A., Mengniu Dairy Company Limited, Inner Mongolia Yili Industrial Group Co. Ltd, Coconut Palm Group Co. Ltd, Dali Foods Group Co. Ltd, Nestlé S.A., Oatly Group AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Dairy Alternatives Market Trends and Innovations
Enzymatic processing breakthroughs and fermentation-derived precision proteins are collapsing traditional ingredient sourcing models while reshaping finished product texture benchmarks.
Precision fermentation for dairy-identical proteins is modularizing ingredient supply architecture. Biotech startups license recombinant casein and whey production to established beverage manufacturers. Foodservice chains in Shenzhen pilot hybrid formulations blending oat base with fermented dairy proteins to achieve superior foam structure and thermal stability without full dairy dependency.
SAMR GB standard revisions for plant protein beverage labeling impose stricter protein content minimums and additive disclosure thresholds. Domestic manufacturers reformulate legacy soy drink portfolios to meet elevated benchmarks or risk category reclassification. Northern Hebei processing facilities invest in inline protein standardization equipment to ensure batch compliance before packaging line entry.
Direct-to-café distribution models displace traditional multi-tier wholesale structures for premium oat and almond concentrates. Roasting equipment suppliers bundle plant milk dispensing systems with espresso machine leases. Shanghai specialty coffee clusters witness fastest adoption as baristas demand consistent steam performance without dairy cross-contamination protocols.
China Dairy Alternatives Market Segmentation
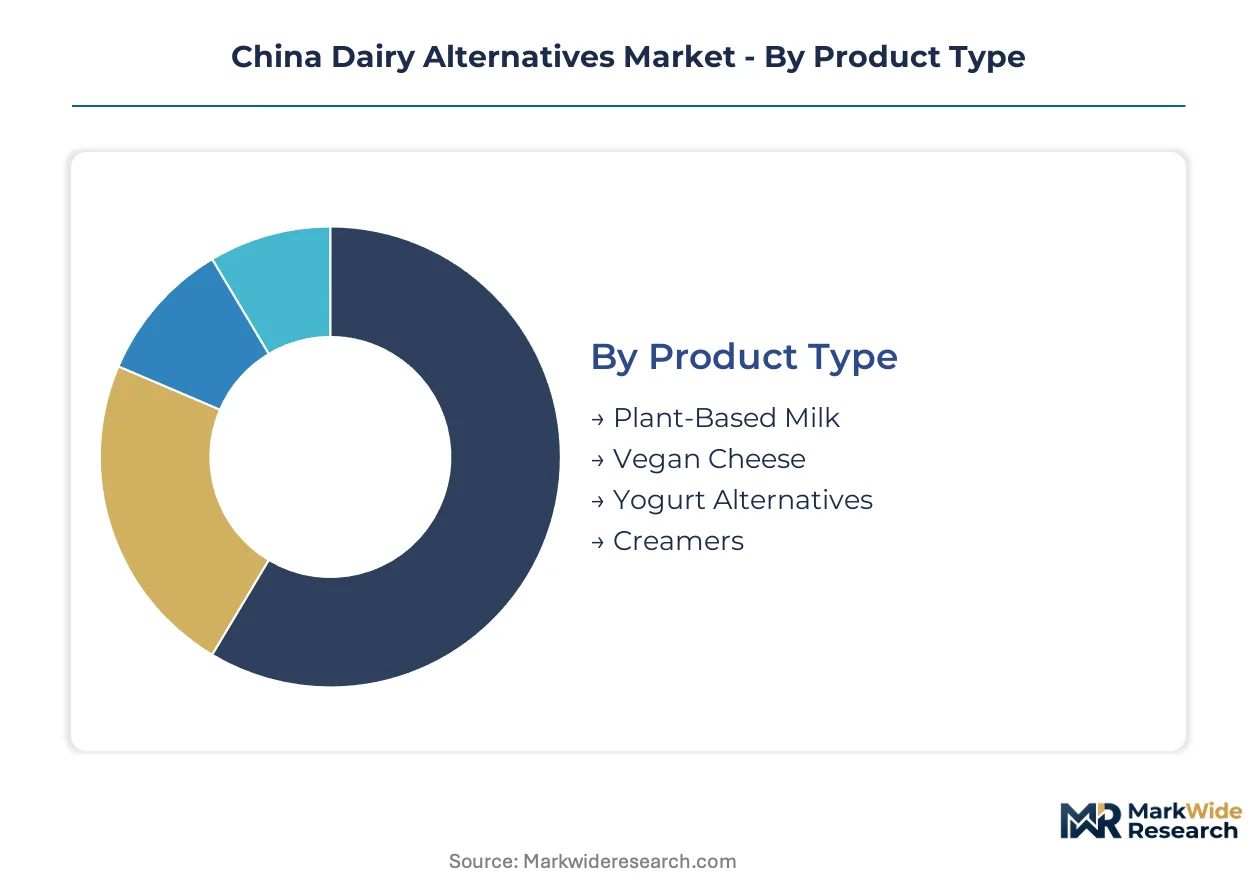
Product type and source material choices determine formulation complexity and margin structure for Chinese dairy alternative manufacturers. Distribution channel selection separates premium positioning from mass market penetration in this regulatory-intensive market.
Product Type:
Purchase decisions pivot on protein content thresholds and SAMR GB standard compliance requirements for plant protein beverage classification.
- Plant-Based Milk:Homogenized at 150-200 bar to achieve mouthfeel parity with cow milk, containing 2-8% protein content. Shanghai and Beijing cafés drive demand for barista-grade foam stability in oat latte applications.
- Vegan Cheese:Fermentation-derived precision proteins and starch-based texturizers replicate melt and stretch properties. SAMR scrutinizes additive thresholds, forcing reformulation of legacy portfolios to meet clean-label certification timelines.
- Yogurt Alternatives:Specialized fermentation expertise applied to plant-based bases with live culture stability challenges.
- Creamers:Industrial food manufacturing applications dominate, with bakery and confectionery manufacturers seeking standardized fat and protein concentrates.
Plant-Based Milk leads on scale; Vegan Cheese leads on momentum.
Source:
Raw material procurement economics shift with MEE dual carbon quotas and water scarcity constraints across northern Chinese growing regions.
- Oat:Northern Chinese oat cooperatives benefit from carbon quota advantages over water-intensive alternatives. Domestic brands pivot procurement toward Hebei and Inner Mongolia cultivation bases as Nordic germplasm licensing costs pressure margins.
- Almond:California drought cycles and shipping lane congestion create input cost volatility. Limited Chinese cultivation forces reliance on imported supply with compressed margins during water-scarce harvest seasons.
- Soy:Decades of domestic processing infrastructure and brand recognition sustain volume leadership despite consumer pivot toward novel bases.
- Coconut:Southeast Asian sourcing corridors face sustainability audit pressures under tightening carbon disclosure requirements.
Soy maintains volume dominance; Oat captures the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture and speed-to-market against competitor launch schedules.
- Foodservice:Tier-one city cafés and restaurant chains command premium positioning. Direct-to-café distribution models displace multi-tier wholesale structures, with roasting equipment suppliers bundling plant milk dispensing systems with espresso machine leases.
- Online Retail:Social media wellness influencers amplify protein-fortified plant beverage visibility among Beijing and Shanghai millennials.
- Supermarkets:Mass market penetration requires GB standard compliance and extended shelf-life stability.
- Health Stores:Clean-label certification and third-party vegan audits support premium pricing in specialized retail.
Foodservice concentrates margin pools; Online Retail expands most quickly.
End User:
Application requirements dictate formulation specifications and batch size economics.
- Cafés:Demand consistent steam performance and foam stability without dairy cross-contamination protocols. Shanghai barista competitions showcase plant-based foam structure as competitive differentiator.
- Restaurants:Format innovation in tier-one cities drives oat milk tea and dessert applications.
- Food Manufacturers:Seek multi-year supply contracts for standardized plant protein concentrates in bakery and confectionery applications.
- Consumers:Direct consumption preferences shift with social media wellness trends and lactose-free dietary pivots.
Food Manufacturers anchor contract volume; Cafés drive specification innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta manufacturing corridors anchor China's dairy alternatives production capacity, with Shanghai and Hangzhou processing facilities supplying foodservice channels nationwide. Provincial carbon quotas and GB standard enforcement create divergent operating conditions across Chinese sub-regions.
Beijing-Tianjin-Hebei
Hebei Yangyuan Zhihui leverages decades of walnut-processing heritage to dominate northern distribution corridors. SAMR's GB standards for plant protein beverage labeling force ingredient transparency upgrades across Shijiazhuang and Tianjin manufacturing bases. Beijing's specialty coffee clusters drive barista-grade oat latte specification innovation through direct-to-café distribution models.
Yangtze River Delta
Shanghai cafés and Hangzhou roasting equipment suppliers bundle plant milk dispensing systems with espresso machine leases. MEE dual carbon goals compress water-intensive almond supply chains while accelerating oat sourcing substitution. Suzhou and Ningbo processing facilities invest in inline protein standardization equipment to ensure GB standard compliance before packaging line entry.
Pearl River Delta
Shenzhen biotech startups license recombinant casein production to established beverage manufacturers for hybrid formulation pilots. Guangzhou foodservice chains pilot precision fermentation-derived proteins blended with oat bases. SAMR scrutinizes additive thresholds in vegan cheese formulations across Dongguan and Foshan industrial zones.
Sichuan-Chongqing
Chengdu foodservice channels show nascent oat beverage adoption with premium positioning opportunities before competitive saturation. Provincial health regulators align with national GB standard revisions while local café culture accelerates format innovation. Chongqing's restaurant chains drive oat milk tea applications through social media wellness influencer amplification.
Shandong Peninsula
Qingdao and Jinan soybean processing infrastructure sustains volume leadership despite consumer pivot toward novel bases. Domestic brands pivot procurement toward northern Chinese oat cooperatives as Nordic germplasm licensing costs pressure margins. Local universities lack dedicated plant-based dairy curriculum pipelines, constraining food technologist availability for UHT stability formulation.
China Dairy Alternatives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and hybrid formulation spaces. The vendor base stratifies across legacy beverage conglomerates, international specialty brands, and domestic regional champions with deep agricultural supply relationships. Three archetypes dominate: agricultural heritage processors leveraging captive raw material access, multinational dairy diversifiers applying fermentation expertise to plant bases, and oat-specialist entrants scaling barista-grade formats. Competitive intensity concentrates on direct-to-café distribution partnerships and GB standard certification speed.
Among domestic agricultural heritage processors, Hebei Yangyuan Zhihui Beverage Co. Ltd exemplifies the walnut-processing lineage archetype with established northern distribution control. Vitasoy International Holdings Ltd occupies a position representing decades of soy-based brand recognition sustained through formulation consistency. Danone S.A. anchors the multinational dairy diversifier tier, applying specialized fermentation expertise to plant-based yogurt alternatives. These three entities represent distinct strategic postures without implying specific market share positions or operational metrics.
| Leading Market Players |
|---|
| Hebei Yangyuan Zhihui Beverage Co. Ltd |
| Vitasoy International Holdings Ltd |
| Danone S.A. |
| Mengniu Dairy Company Limited |
| Inner Mongolia Yili Industrial Group Co. Ltd |
| Coconut Palm Group Co. Ltd |
| Dali Foods Group Co. Ltd |
| Nestlé S.A. |
| Oatly Group AB |
| Others |
Pricing and Supply Chain Analysis
Family-owned agricultural processors with decades of walnut and soy processing lineage anchor northern China's supply base, translating captive raw material access into pricing discipline that resists margin erosion even as imported oat germplasm licensing costs escalate. Their ownership structure enables long-term procurement contracts with Hebei and Inner Mongolia cooperatives, insulating barista-grade product tiers from the volatility that compresses margins for import-dependent competitors.
Pricing Analysis
Input-cost pass-through from California almond drought cycles and Nordic oat germplasm licensing fees concentrates pricing pressure on mid-tier brands lacking backward integration into northern Chinese cultivation bases. Three-tier pricing structure across premium, standard, and economy levels separates SAMR-certified barista formulations from commodity soy drinks, with foodservice channels showing least price sensitivity due to foam-stability specification requirements. Cost compression in economy-tier private-label segments is intensifying because domestic processors compete on shelf-life extension without premium emulsifier budgets.
Supply Chain Analysis
Single-source vulnerability sits with Canadian and Nordic high-beta-glucan oat varieties, forcing Chinese brands into licensing dependencies that inflate input costs when domestic breeding programs lack beverage-grade cultivars. Raw material procurement draws from California almonds, Southeast Asian coconut, and northern Chinese soy and oat cooperatives. Tariff exposure on imported germplasm and finished ingredient concentrates threatens margin structures for non-vertically integrated processors. Distribution runs through direct-to-café leasing partnerships in Shanghai and Beijing, displacing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's dairy alternatives market functions as a geographic-arbitrage play where MEE dual carbon quotas favor northern Chinese oat cultivation over water-intensive California almond sourcing, creating cost advantages for processors with Hebei and Inner Mongolia supply relationships.
For Market Incumbents: Acquire proprietary high-beta-glucan oat breeding programs to reduce Nordic germplasm licensing dependencies. Secure multi-year contracts with northern Chinese cooperatives before provincial carbon quotas tighten further. SAMR's evolving GB standards for protein content minimums threaten legacy soy portfolios with category reclassification, demanding inline standardization equipment investments. For New Entrants and Emerging Players: The gap between premium barista-grade oat formulations and economy soy drinks offers entry space for mid-tier hybrid products. Chengdu and Xi'an foodservice channels show nascent adoption with limited competitive saturation. Target industrial ingredient supply to bakery and confectionery manufacturers seeking standardized plant protein concentrates with multi-year contract lock-in. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic agricultural heritage processors with captive walnut and soy supply but limited oat diversification. Long-term viability hinges on carbon-compliant sourcing architectures and SAMR certification speed. Watch for MEE provincial carbon quota announcements as inflection indicators for oat substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Cultivation | Hebei and Inner Mongolia cooperatives reduce germplasm licensing exposure under MEE carbon quotas. |
| Direct-to-Café Equipment Leasing Partnerships | Shanghai roasting suppliers bundle dispensing systems to capture premium channel margins. |
| Inline Protein Standardization Investment | Suzhou and Ningbo facilities ensure SAMR GB compliance before packaging line entry. |
| Precision Fermentation Licensing | Shenzhen biotech startups supply recombinant casein for hybrid formulation stability. |
| Clean-Label Certification Acceleration | Third-party vegan audits compress six-to-nine-month timelines against competitor launches. |
Research Methodology
Direct dialogue with foodservice procurement managers, plant protein formulation chemists, SAMR regulatory affairs specialists, and northern Chinese agricultural cooperative directors grounded qualitative insights in operational reality. Secondary validation drew from SAMR GB standard filings, MEE carbon quota disclosures, customs import records for oat germplasm, and foodservice equipment leasing contracts. Bottom-up volume modeling triangulated against top-down category spend estimates.
Bottom-up demand modeling aggregated foodservice channel throughput, industrial ingredient contract volumes, and retail scanner data across the projection horizon. Segmentation dimensions included product type, source material, distribution channel, and end-user application with provincial regulatory cluster overlays. CAGRs were derived from installed base growth rates and per-capita consumption elasticity against dairy price benchmarks. Forecast inputs incorporated MEE dual carbon enforcement timelines and SAMR standard revision schedules.
Caveats apply where MEE provincial carbon quota allocations, SAMR protein content threshold adjustments, or California drought severity could materially shift the outlook. Forecasts reflect documented assumptions about oat cultivar licensing costs and foodservice adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
Soy Milk Powder Market
Dairy Alternatives
Australia Dairy Alternatives Market
Dairy Alternatives
Dry Cream Substitute Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
United States Non-Dairy Milk Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
Dairy-Free Chocolate Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Vegan Ice Cream Market
Dairy Alternatives
Cultured Dairy Blends Market
Dairy Alternatives
Coconut Cream Market
Dairy Alternatives
A2 Ice Cream Market