
 North America Non-Dairy Ice Cream Market | 2026-2036
North America Non-Dairy Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
North America Non-Dairy Ice Cream Market Insights
The capital-intensity divergence between multinational CPG infrastructure and artisan craft production is redrawing competitive boundaries in North America. Unilever Plc leverages its continental manufacturing footprint to sustain broad retail distribution, while Van Leeuwen Ice Cream anchors its position through premium ingredient sourcing and direct-to-consumer channel control. Oatly Group AB differentiates via specialized oat-base processing technology that commands dedicated freezer placement in upscale grocery accounts.
North America non-dairy ice cream comprises frozen dessert formulations manufactured without mammalian milk derivatives, typically employing emulsified plant lipid systems from coconut, almond, oat, or soy substrates with overrun controlled between 70% and 120% to achieve scoopable texture parity with conventional ice cream. The primary commercial purpose centers on serving lactose-intolerant consumers, vegan dietary adherents, and flexitarian households seeking indulgence formats aligned with reduced animal-product consumption. Almond milk and oat milk bases currently occupy the largest volume positions within product type segmentation, while coconut milk formulations retain the highest margin profile due to fat-content advantages that reduce reliance on stabilizer additives. Single-serve packaging is accelerating fastest within format segmentation, driven by convenience-store channel expansion and portion-control positioning among calorie-conscious buyers.
FDA enforcement of dairy identity standards alongside evolving USDA National Organic Program requirements shapes permissible label claims and ingredient sourcing verification across domestic production. Health Canada and the Canadian Food Inspection Agency impose parallel allergen disclosure mandates that influence cross-border formulation standardization for multinational suppliers. Stakeholders must monitor pending regulatory clarifications on precision-fermented protein inclusion within plant-based dairy alternative definitions, as these determinations will reshape acceptable ingredient technology pathways and associated capital allocation decisions.
Market Dynamics
Plant-based lipid emulsification technology is redrawing cost curves and texture benchmarks across North American frozen dessert manufacturing, forcing incumbent dairy-alternative suppliers to retool processing lines or cede shelf space to oat-base specialists.
Growth Catalysts
- FDA Dairy Identity Standards:Clarified labeling requirements for plant-based alternatives reduce consumer confusion and accelerate mainstream retail placement for compliant formulations.
- Quick-Service Restaurant Integration:Major fast-casual chains in the United States and Canada are adding dedicated non-dairy freezer sections to capture flexitarian household traffic.
- Pacific Northwest Consumer Concentration:California and Oregon households demonstrate disproportionate willingness to pay premium prices for clean-label oat and almond milk formulations.
Market Restraints
- Coconut Oil Price Volatility:Southeast Asian supply disruptions transmit directly to North American manufacturer margins, compressing the highest-margin coconut-base segment.
- Single-Supplier Oat Protein Concentration:Swedish and Canadian oat processing infrastructure limits qualified ingredient sourcing for domestic formulators.
- USDA Organic Certification Timelines:Extended verification periods for novel stabilizer additives delay product launch windows by 8-14 months.
Strategic Opportunities
- Canadian Market Underpenetration:Health Canada allergen disclosure alignment with FDA standards creates cross-border formulation efficiency for US suppliers expanding northward.
- Precision-Fermented Protein Inclusion:Pending regulatory determinations on microbial dairy protein analogs open formulation pathways beyond conventional plant lipids.
- Convenience-Store Channel Expansion:Single-serve packaging formats capture impulse purchase occasions previously dominated by conventional ice cream novelties.
Industry Challenges
- Food Science Talent Scarcity:Shortage of formulation chemists skilled in plant lipid emulsification and overrun control limits R&D throughput for mid-tier manufacturers.
- Legacy Cold Chain Integration:Existing dairy distributor freezer systems require retrofitting to maintain plant-based product integrity through temperature fluctuation zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Non-Dairy Ice Cream Market |
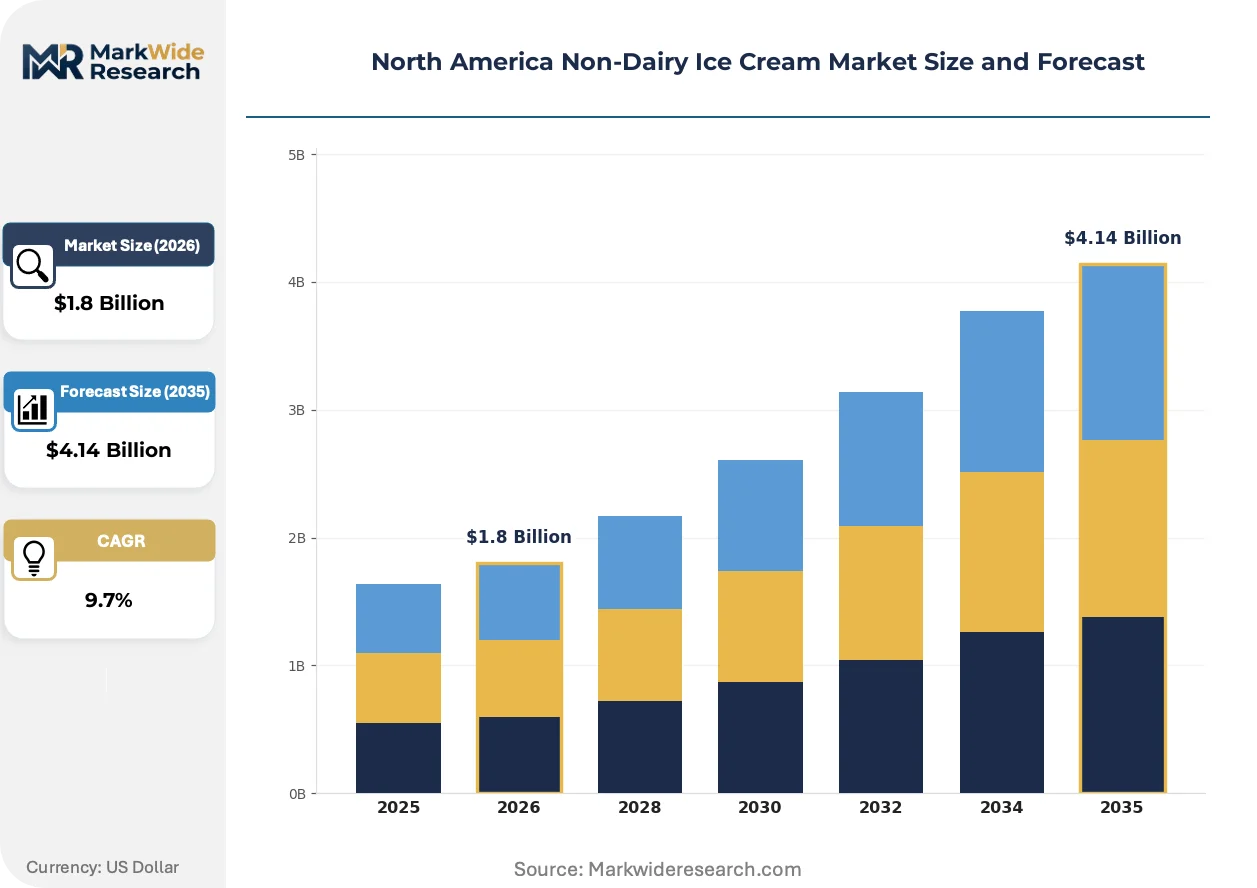
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Milk, Almond Milk, Soy Milk, Cashew Milk Flavor: Chocolate, Vanilla, Strawberry, Mint Chip Packaging Type: Pint, Quart, Single Serve, Tub Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Convenience Stores |
| Companies Covered | Danone SA, Oatly Group AB, Oregon Ice Cream Company, Unilever Plc, Van Leeuwen Ice Cream, Froneri International Limited, Arctic Zero Cssc Inc., NadaMoo, Tofutti Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Non-Dairy Ice Cream Market Trends and Innovations
Clean-label ingredient reduction is compressing stabilizer dependence while precision fermentation threatens to bypass conventional plant-base supply chains entirely. These forces are restructuring how North American manufacturers source proteins and achieve scoopable texture parity.
High-pressure processing of oat and almond bases is decomposing the traditional reliance on hydrocolloid stabilizers for texture maintenance. Premium craft producers in California and Oregon are adopting this technology to shorten ingredient decks. The structural consequence is margin compression for legacy stabilizer suppliers and accelerated shelf-space consolidation behind clean-label claims.
USDA National Organic Program updates to livestock feed and processing aid standards are tightening permissible inputs for certified organic non-dairy formulations. Manufacturers must requalify supplier networks or reformulate to maintain organic certification. Small-batch producers in Vermont and Quebec face disproportionate compliance burdens relative to multinational CPG infrastructure.
Direct-to-consumer subscription models are displacing traditional distributor relationships for premium-positioned brands. Specialty grocers in metropolitan California and Pacific Northwest clusters are responding with exclusive freezer placements and localized flavor collaborations. This channel shift concentrates marketing spend on digital acquisition rather than trade promotion allowances.
North America Non-Dairy Ice Cream Market Segmentation
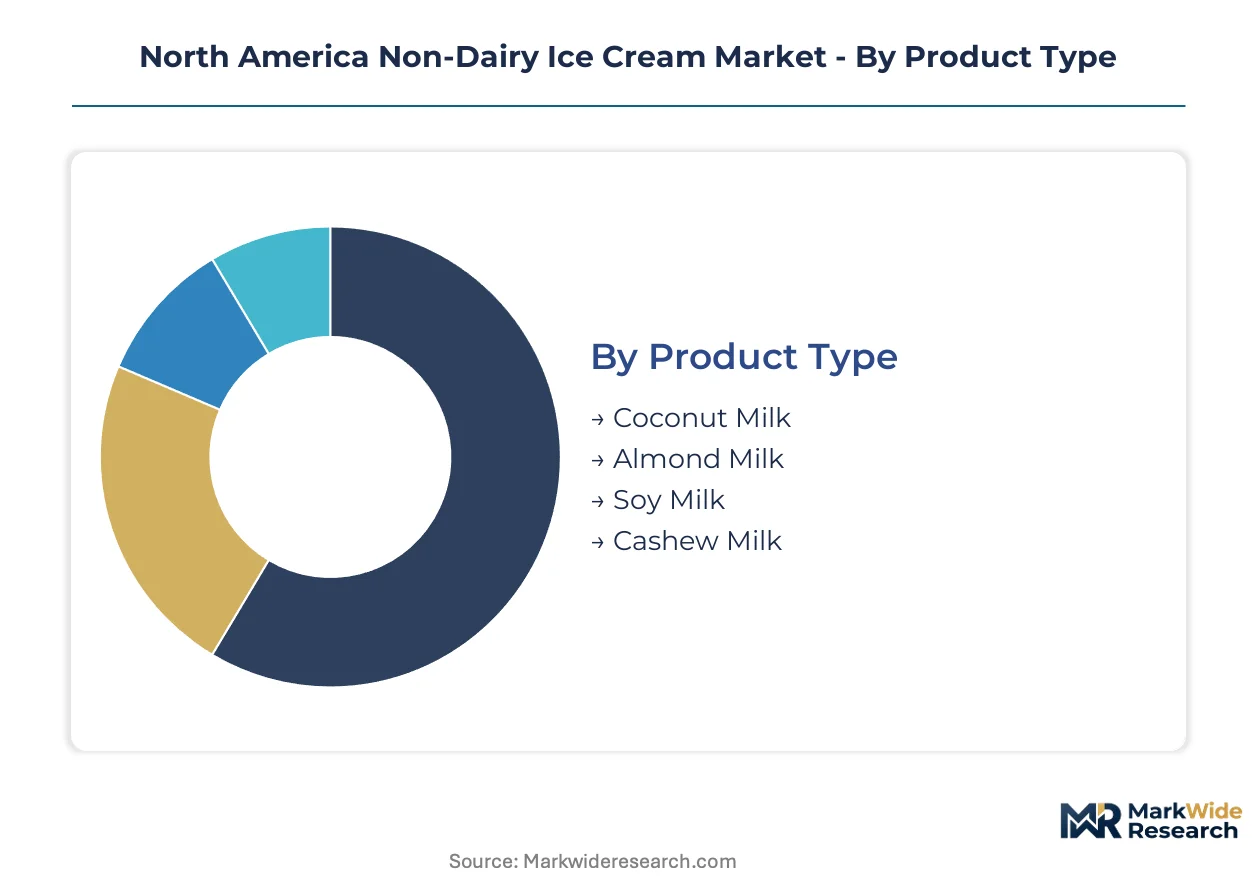
Segmentation in North American non-dairy ice cream reveals how substrate technology, portion formats, and channel access determine which manufacturers capture flexitarian household spending. Each dimension exposes different vulnerability to conventional dairy substitution and premium pricing power.
Product Type:
Substitution pressure from conventional ice cream concentrates in segments where fat-content parity remains hardest to achieve without coconut's saturated lipid profile.
- Almond Milk:Formulations rely on emulsified almond protein and vegetable oil blends to approximate butterfat mouthfeel. California and Pacific Northwest specialty grocers command disproportionate shelf space for these SKUs, driven by clean-label positioning and established consumer familiarity with almond milk beverage alternatives.
- Oat Milk:Oatly's proprietary enzymatic processing technology enables superior overrun control and scoopable texture without heavy stabilizer loads. Quick-service restaurant chains in the United States and Canada are standardizing oat-base soft serve, creating institutional demand concentration that almond formulations have not matched.
- Coconut Milk:Naturally high saturated fat content reduces additive dependence and commands premium pricing in craft channels.
- Soy Milk:Legacy substrate facing allergen-labeling headwinds and consumer preference shifts toward nut and oat alternatives.
Almond milk retains volume leadership; oat milk holds the steepest expansion curve.
Flavor:
Cost tier stratification separates commodity flavors from limited-edition rotational SKUs that justify price premiums in direct-to-consumer channels.
- Vanilla:The technical benchmark for base formulation quality, vanilla serves as the entry point for flexitarian trial. Unilever's continental manufacturing infrastructure optimizes vanilla production economics across broad retail distribution, while craft producers differentiate through Madagascar bourbon and Tahitian bean sourcing claims.
- Chocolate:Cocoa butter compatibility with coconut and oat lipid systems creates formulation flexibility that vanilla lacks. Premium craft producers in metropolitan California clusters are deploying single-origin chocolate partnerships to anchor direct-to-consumer subscription retention.
- Strawberry:Seasonal ingredient sourcing challenges limit year-round consistency for clean-label positioning.
- Mint Chip:Nostalgia-driven demand concentrates in convenience-store impulse purchase occasions.
Vanilla dominates unit economics at scale; chocolate commands the highest per-unit margins in premium channels.
Packaging Type:
Application context—home consumption versus on-premise indulgence—determines format preference and corresponding cold-chain requirements.
- Single Serve:Individually wrapped bars and sandwiches capture convenience-store traffic previously monopolized by conventional ice cream novelties. Portion-control positioning resonates with calorie-conscious buyers in urban California and Pacific Northwest markets.
- Pint:The standard craft producer format enabling flavor variety experimentation without inventory risk. Specialty grocers in Portland, Seattle, and San Francisco dedicate exclusive freezer placements to pint-dominant local brands.
- Quart:Family-size format concentrates in conventional supermarket channels with price-sensitive household penetration.
- Tub:Foodservice-scale packaging for quick-service restaurant soft-serve operations and institutional accounts.
Pint formats anchor craft brand identity; single-serve packaging is expanding most quickly through convenience-channel penetration.
Distribution Channel:
Geographic concentration of plant-forward consumer demographics creates channel-specific winners, with digital-native brands bypassing traditional distributor relationships entirely.
- Specialty Stores:Regional chains like Whole Foods Market and independent grocers in California and Oregon provide curated freezer placement and localized flavor collaboration opportunities. These outlets disproportionately influence early-adopter purchase decisions that subsequently diffuse to mainstream channels.
- Online Stores:Direct-to-consumer subscription models concentrate marketing spend on digital acquisition rather than trade promotion allowances. Cold-chain logistics investments by specialized frozen fulfillment providers have reduced the barrier to national shipping for small-batch producers.
- Supermarkets:Mass retail placement requires Unilever-scale manufacturing infrastructure and slotting fee capacity that excludes craft competitors.
- Convenience Stores:Impulse-driven traffic demands single-serve formats with extended shelf-life stability.
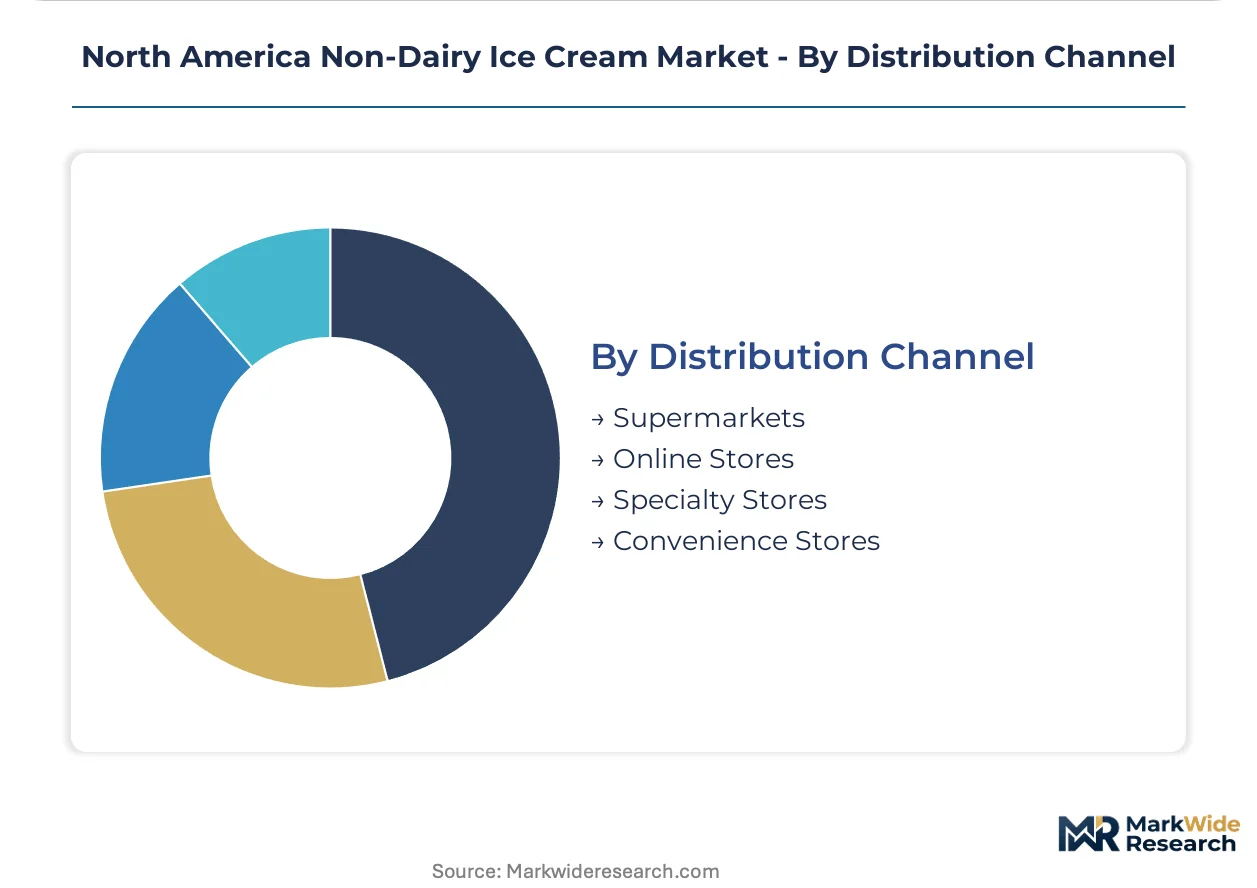
Specialty stores concentrate premium pricing power; online channels are gaining share fastest through subscription retention mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California households command premium pricing power that Canadian markets have yet to replicate, creating a transcontinental margin spread that shapes manufacturer expansion priorities. The Pacific Northwest and Northeast Corridor concentrate early-adopter demand, while Texas and Florida represent volume growth frontiers where conventional dairy substitution lags.
United States
FDA dairy identity standards and quick-service restaurant chain adoption drive institutional demand concentration. USDA National Organic Program updates force supplier network requalification for certified formulations. California's Bay Area and Los Angeles metro clusters anchor clean-label oat milk innovation, with Portland and Seattle specialty grocers providing exclusive freezer placement for craft producers.
Canada
Health Canada allergen disclosure alignment with FDA standards enables cross-border formulation efficiency for US suppliers. Canadian Food Inspection Agency enforcement tightens ingredient verification timelines for organic claims. Toronto and Vancouver metropolitan areas concentrate flexitarian household density, while Quebec's artisan dairy heritage creates distinctive positioning challenges for plant-based entrants.
Mexico
Expanding middle-class indulgence consumption and convenience-store channel modernization drive single-serve format penetration. Federal Commission for the Protection against Sanitary Risk (COFEPRIS) labeling requirements for dairy alternatives remain less prescriptive than FDA standards. Mexico City metro and Monterrey industrial corridors attract multinational manufacturing investment seeking nearshored supply chain advantages.
North America Non-Dairy Ice Cream Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure where multinational CPG infrastructure competes against craft-scale specialization. The market consolidates around three strategic tiers: continental-scale manufacturers with slotting fee capacity, regional craft producers with direct-to-consumer channel control, and oat-base technology specialists with proprietary processing advantages. Dominant competitive moves include strategic partnerships for freezer placement and portfolio diversification into precision-fermented protein pathways.
Among multinational CPG incumbents, Unilever Plc and Danone SA occupy positions defined by manufacturing scale and broad retail distribution reach. Oatly Group AB exemplifies the technology-specialist archetype through dedicated oat-base processing infrastructure. Van Leeuwen Ice Cream and Oregon Ice Cream Company represent craft-scale positioning anchored in premium ingredient sourcing and metropolitan market concentration.
| Leading Market Players |
|---|
| Danone SA |
| Oatly Group AB |
| Oregon Ice Cream Company |
| Unilever Plc |
| Van Leeuwen Ice Cream |
| Froneri International Limited |
| Arctic Zero Cssc Inc. |
| NadaMoo |
| Tofutti Brands Inc. |
| Others |
Pricing and Supply Chain Analysis
Oat milk's displacement of almond milk as the preferred plant lipid substrate simultaneously concentrates ingredient sourcing around Swedish and Canadian enzymatic processing infrastructure and compresses margin capture for manufacturers locked into legacy vegetable oil blending systems. This substitution dynamic redistributes pricing power toward oat-base technology specialists while exposing conventional formulators to raw material cost volatility from Southeast Asian coconut oil markets.
Pricing Analysis
The customization-premium spread between configured-to-order craft pints and standard supermarket quarts separates vanilla and chocolate formulations across three-tier pricing structure across premium, standard, and economy levels. Certification tier under USDA National Organic Program and FDA dairy identity compliance status drive price differentiation alongside brand heritage claims in metropolitan California clusters. Pricing pressure stems from coconut oil price volatility transmitting directly from Southeast Asian supply disruptions, compressing the highest-margin coconut-base segment. Mass retail buyers demonstrate acute price sensitivity through slotting fee negotiations, while direct-to-consumer subscribers accept premium positioning for clean-label ingredient decks.
Supply Chain Analysis
Sweden and Canada anchor qualified oat protein concentrate production for North American enzymatic processing infrastructure, while Southeast Asian suppliers feed coconut lipid dependencies. Raw material sourcing draws from Canadian prairie oat cultivation, Malaysian and Indonesian coconut plantations, and California almond orchards. Single-supplier concentration for enzymatic oat processing creates vulnerability to qualification bottlenecks and cross-border logistics friction. Distribution runs through retrofitted legacy dairy cold chains for conventional retail, with direct-to-consumer channels bypassing traditional distributor relationships entirely through specialized frozen fulfillment providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American non-dairy ice cream is recovering from ingredient cost cyclicality as oat-base processing capacity expands and precision-fermented protein pathways mature toward regulatory clarity.
For Market Incumbents: Fortify continental manufacturing footprints against oat-base technology specialists by securing captive supply agreements with Canadian oat processors and accelerating precision-fermented protein R&D ahead of FDA determinations on microbial dairy analogs. Invest in USDA National Organic Program certification maintenance to defend shelf-space positioning as clean-label requirements tighten. For New Entrants and Emerging Players: Differentiate on high-pressure processing technology adoption to achieve stabilizer-free texture parity, targeting underpenetrated Canadian metropolitan markets where Health Canada allergen disclosure alignment with FDA standards enables cross-border formulation efficiency. Pursue convenience-store single-serve placement through portion-control positioning and extended shelf-life stability claims. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors craft-scale specialists with proprietary processing advantages and direct-to-consumer channel control over mass retail-dependent incumbents. Long-term viability centers on precision-fermented protein integration capability and clean-label formulation expertise. Monitor FDA regulatory determinations on microbial dairy protein inclusion as the primary inflection signal for acceptable ingredient technology pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermented Protein Integration | FDA determinations on microbial dairy analogs will reshape acceptable formulation pathways and capital allocation priorities. |
| Canadian Market Expansion | Health Canada allergen disclosure alignment enables cross-border formulation efficiency for US suppliers seeking northward growth. |
| High-Pressure Processing Adoption | California and Oregon craft producers deploy this technology to compress stabilizer dependence and anchor clean-label claims. |
| Direct-to-Consumer Channel Buildout | Subscription models displace traditional distributor relationships and concentrate marketing spend on digital acquisition mechanics. |
| Convenience-Store Single-Serve Penetration | Impulse purchase occasions previously dominated by conventional ice cream novelties capture calorie-conscious urban buyers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers at multinational CPG manufacturers, category buyers at specialty grocers, plant managers at oat processing facilities, formulation chemists at craft producers, and channel sales heads at frozen distribution networks. Secondary validation incorporated FDA dairy identity standard filings, USDA National Organic Program certification databases, Nielsen retail audit data for frozen dessert categories, and customs records tracking coconut oil import flows. Bottom-up volume triangulation across substrate types, packaging formats, and regional consumption clusters was cross-checked against top-down manufacturer capacity assessments.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, flavor, packaging format, and distribution channel dimensions, with additional granularity on oat versus almond versus coconut substrate technology pathways. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for quick-service restaurant adoption curves and regulatory timeline impacts. Forecast inputs incorporated Pacific Northwest household willingness-to-pay premiums, Canadian cross-border formulation efficiency gains, and precision-fermented protein regulatory pathway probabilities.
Decision-makers should treat outputs as directional under base assumptions of continued oat-base technology diffusion and stable FDA dairy identity enforcement; material deviation in precision-fermented protein regulatory determinations or Southeast Asian coconut supply disruptions would warrant model refresh. Recalibration cycles align with material shifts in USDA National Organic Program standards, Health Canada allergen disclosure updates, and quick-service restaurant chain menu integration announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Coconut Cream Market
Dairy Alternatives
Walnut Milk Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
Cultured Dairy Blends Market
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
Flax Milk Market
Dairy Alternatives
Low Calorie Cream Cheese Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
Peanut Milk Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Non-Dairy Yogurt Market