
 United States Oat Milk Market | 2026-2036
United States Oat Milk Market Size, Share, and Industry Trends Forecast 2026-2036
United States Oat Milk Market Insights
The USDA's BioPreferred Program and emerging corporate sustainability procurement mandates from major foodservice operators is repositioning oat milk as a strategically sourced ingredient rather than a niche alternative. Oatly Group leverages its proprietary enzymatic production process to sustain premium positioning in coffee shop channels. Califia Farms anchors West Coast supply through integrated manufacturing in Bakersfield. Planet Oat competes aggressively on price in conventional grocery, while Chobani differentiates through Greek yogurt cross-brand loyalty and refrigerated distribution scale.
United States oat milk consists of an aqueous extraction from whole oat groats or oat flour, enzymatically treated to reduce viscosity and enhance sweetness through starch hydrolysis, then fortified with calcium, vitamin D, and vitamin B12 to approximate dairy nutritional profiles for commercial beverage and culinary applications. Barista Blend formulations command the highest margin pool due to specialized fat and protein structuring that delivers microfoam stability demanded by third-wave coffee culture. Organic certification within product type segments extracts a sustained price premium despite higher input costs. Carton packaging dominates volume through ambient distribution economics, though refrigerated bottles capture disproportionate shelf space in premium Northeast and California retail.
The FDA oversees plant-based beverage labeling standards, while USDA organic certification governs ingredient sourcing claims, and the EPA regulates water usage and effluent discharge from oat processing facilities, collectively elevating compliance costs but also creating barrier-to-entry protection for scaled producers. State-level dairy labeling disputes in Wisconsin and California add jurisdictional complexity that favors national brands with legal resources over regional entrants. Stakeholders must monitor whether pending FDA nutritional fortification guidance will mandate minimum protein or micronutrient thresholds that could force reformulation across the competitive set.
Market Dynamics
The enzymatic hydrolysis of oat starches into maltose is compressing production timelines and reshaping capital allocation across processing facilities. This single biochemical shift has redefined what constitutes premium positioning in coffee-service channels.
Growth Catalysts
- USDA BioPreferred Program:Federal procurement mandates now require plant-based alternatives in institutional foodservice contracts, expanding addressable volume for domestic oat milk producers.
- Third-wave coffee culture:Specialty roasters in Portland, Seattle, and Brooklyn have normalized oat milk as the default dairy alternative, embedding structural demand into café operations.
- Enzymatic viscosity reduction:Proprietary processing techniques eliminate the need for added oils while achieving mouthfeel parity with dairy, lowering input cost structures.
Market Restraints
- Input cost volatility:Drought cycles in the upper Midwest threaten oat grain supply stability, concentrating risk in Minnesota and North Dakota growing regions.
- Technical limitation:Current enzymatic processes cannot replicate the complete amino acid profile of dairy without expensive fortification, capping nutritional equivalence claims.
- Regulatory friction:Pending FDA protein threshold guidance for plant-based beverage labeling could force widespread reformulation, elevating compliance uncertainty.
Strategic Opportunities
- Underpenetrated geography:The Southeast and Mountain West remain below national per-capita consumption averages, offering expansion runway for refrigerated distribution networks.
- Regulatory tailwind:Corporate sustainability procurement mandates from major foodservice operators are repositioning oat milk as a strategically sourced ingredient.
- Technology convergence:Precision fermentation of oat-derived proteins combined with traditional aqueous extraction is opening hybrid formulation pathways for functional nutrition products.
Industry Challenges
- Specialized talent scarcity:Food biochemists with enzymatic processing expertise command premium compensation, constraining facility expansion timelines.
- Certification complexity:USDA organic certification timelines extend 18-24 months for new processing lines, delaying premium product launches.
- Supply chain reconfiguration:Ambient carton distribution requires distinct logistics infrastructure from refrigerated channels, fragmenting operational footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Oat Milk Market |
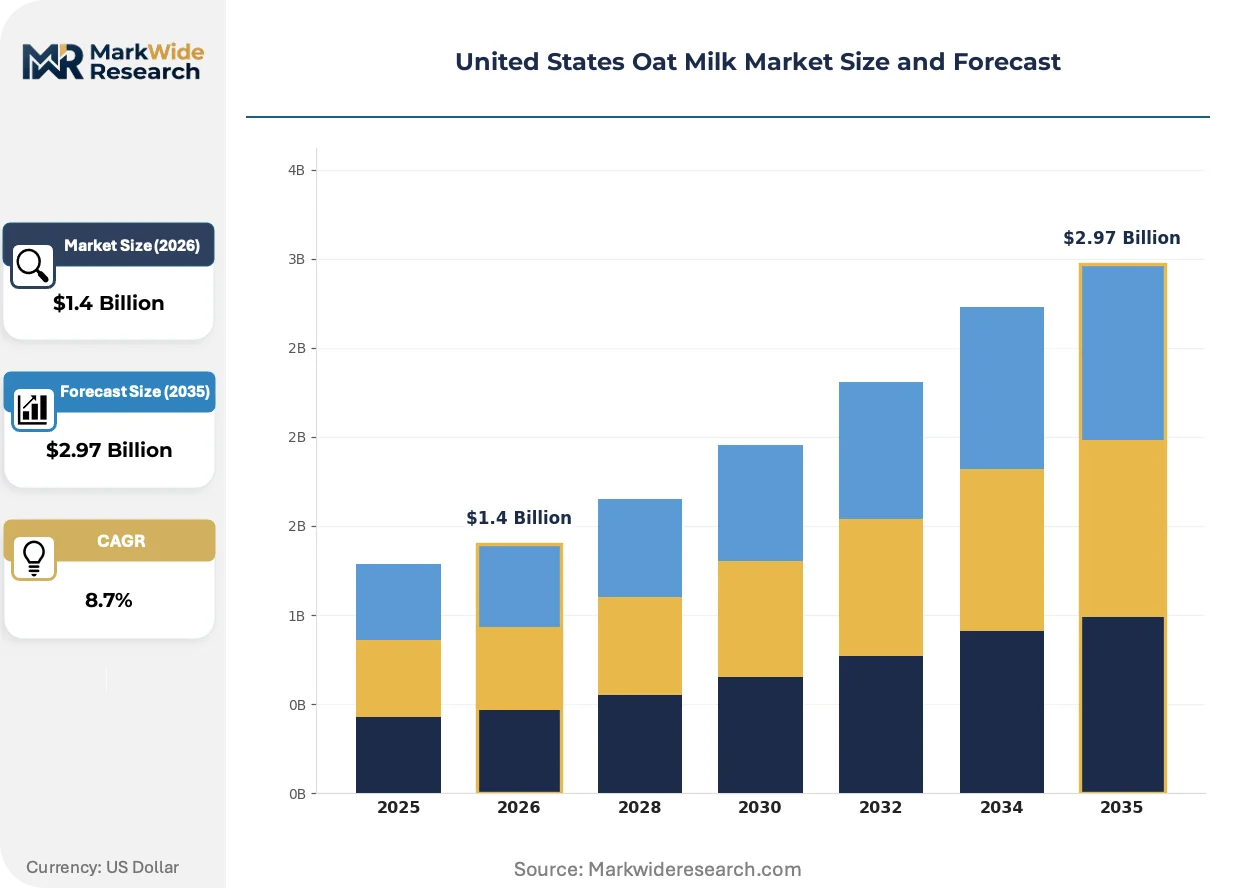
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barista Blend, Organic, Flavored, Unsweetened Packaging Type: Carton, Bottle, Tetra Pak, Can Distribution Channel: Supermarkets, Health Stores, Online Retailers, Specialty Stores End User: Individuals, Coffee Shops, Restaurants, Food Manufacturers |
| Companies Covered | Califia Farms, Campbell Soup Company, Chobani, Danone, Elmhurst, HP Hood, Oatly Group, Planet Oat, Ripple Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Oat Milk Market Trends and Innovations
Formulation science and channel-specific product architecture are actively fragmenting what was once a commoditized alternative dairy category into distinct performance tiers.
Distributed enzymatic processing systems are decentralizing production geography by enabling smaller-scale facilities to achieve viscosity and sweetness profiles previously requiring industrial-scale capital investment. Regional dairy cooperatives in Wisconsin and upstate New York are retrofitting idle processing lines with enzymatic skids to enter oat milk production. This capability diffusion is compressing the historical advantage of concentrated manufacturing footprints in California and the Pacific Northwest.
The FDA's updated labeling guidance for plant-based beverages is clarifying nutritional equivalence claims and reshaping formulation priorities across the competitive set. Manufacturers must now substantiate protein, calcium, and vitamin content comparisons against dairy benchmarks, elevating fortification costs. Barista Blend formulations face the most stringent scrutiny given their positioning as functional coffee ingredients rather than simple dairy substitutes.
Foodservice procurement teams are consolidating supplier relationships around vertically integrated producers capable of guaranteeing year-round volume and consistent microfoam performance. Large restaurant chains are displacing fragmented local distributor relationships with direct contracts to national oat milk brands. This concentration is most visible in the fast-casual segment, where standardized beverage programs span hundreds of locations and demand batch-to-batch consistency unavailable from regional entrants.
United States Oat Milk Market Segmentation
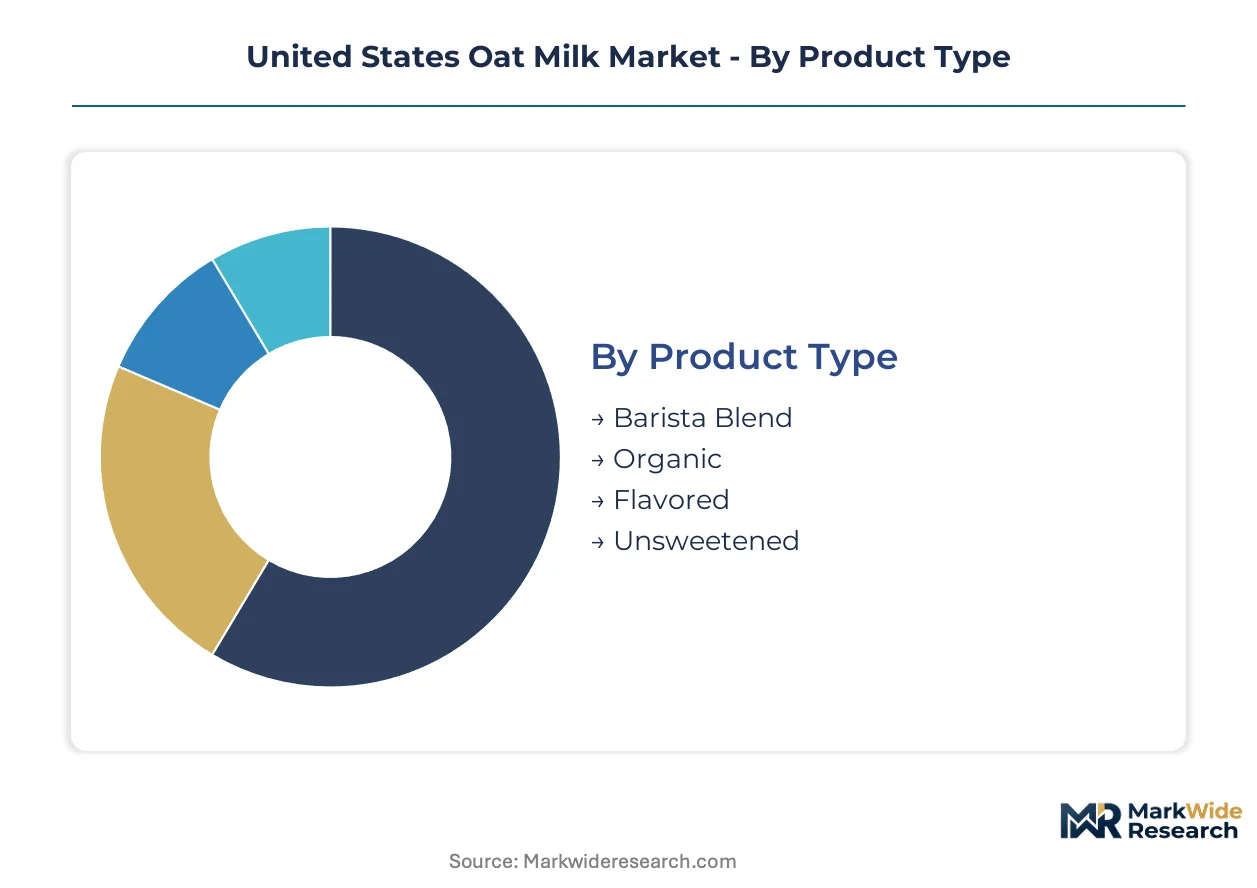
Enzymatic processing capabilities and channel-specific performance requirements fragment oat milk into distinct specification tiers. Each segment demands differentiated formulation, fortification, and logistics infrastructure.
Product Type:
Protein structuring and fat emulsion stability define competitive positioning across consumption occasions.
- Barista Blend:Specialized fat and protein matrices deliver microfoam stability under steam pressure. Third-wave coffee shops in Portland, Seattle, and Brooklyn specify this grade for latte art performance, with procurement teams demanding batch-to-batch consistency unavailable from commodity alternatives.
- Organic:USDA-certified ingredient sourcing extracts sustained price premiums despite 18-24 month certification timelines for new processing lines. California and Pacific Northwest consumers concentrate demand here, where environmental purchasing correlates with disposable income density.
- Flavored:Vanilla and chocolate variants target household consumption with added sweetness from natural or artificial sources.
- Unsweetened:Zero-added-sugar formulations appeal to diabetic consumers and ketogenic diet adherents seeking dairy alternatives without carbohydrate load.
Mature deployment sits with Barista Blend. Newer deployment is concentrated in Unsweetened.
Packaging Type:
Temperature control requirements and shelf-life economics determine logistics infrastructure investment.
- Carton:Aseptic carton technology enables ambient distribution with 9-12 month shelf stability. Supermarket chains in the Midwest and Southeast prioritize this format for inventory turns and reduced refrigeration capital.
- Bottle:Refrigerated PET or glass containers capture disproportionate shelf space in premium Northeast and California retail. The format signals freshness and commands 30-40% price premiums over ambient alternatives.
- Tetra Pak:Multilayer laminate construction suits foodservice bulk procurement with extended ambient storage.
- Can:Aluminum packaging targets single-serve convenience and on-premise consumption in fitness and hospitality channels.
Volume concentrates in Carton. Margin expansion is climbing the fastest in Bottle.
Distribution Channel:
Channel selection dictates certification requirements, promotional spend, and working capital intensity.
- Supermarkets:Conventional grocery placement demands slotting fees and promotional calendars that favor scaled producers with trade marketing budgets. Kroger, Albertsons, and Safeway banners drive volume through weekly circular placement.
- Health Stores:Whole Foods Market and Sprouts Farmers Market emphasize organic certification and clean-label positioning, with regional buyers controlling assortment at store-cluster level.
- Online Retailers:Amazon and Thrive Market enable subscription models with direct-to-consumer fulfillment bypassing traditional distributor margins.
- Specialty Stores:Independent natural grocers and co-ops sustain regional brand presence with localized merchandising.
Consolidation is advancing fastest in Supermarkets. Fragmentation persists in Specialty Stores.
End User:
Application-specific performance requirements separate commodity supply from premium positioning.
- Individuals:Household consumption spans breakfast cereal, smoothies, and direct drinking with formulation preferences varying by dietary restriction and taste preference.
- Coffee Shops:Specialty café operations require Barista Blend specifications with guaranteed microfoam performance, direct supplier relationships, and technical training support.
- Restaurants:Fast-casual and full-service chains specify oat milk for standardized beverage programs spanning hundreds of locations.
- Food Manufacturers:Industrial buyers incorporate oat milk into ice cream, yogurt, and baked goods formulations requiring specific viscosity and protein content.
Procurement sophistication is highest in Coffee Shops. Volume scale is largest in Food Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles and San Francisco anchor the highest per-capita oat milk consumption nationally, with specialty coffee density and disposable income concentration driving procurement intensity beyond any other metro cluster.
California
Los Angeles and San Francisco metro areas sustain the country's densest oat milk consumption per capita, with third-wave coffee chains specifying Barista Blend formulations as operational defaults. The state's CDFA enforces agricultural sourcing transparency for organic certification claims. Integrated manufacturing in Bakersfield supplies West Coast retail and foodservice channels with refrigerated distribution reach.
Pacific Northwest
Portland and Seattle coffee cultures normalized oat milk as the default dairy alternative, embedding structural demand into café operations. Washington State Department of Agriculture oversees organic processor certification timelines extending 18-24 months. Regional dairy cooperatives retrofit idle processing lines with enzymatic skids to enter production.
Northeast Corridor
Brooklyn specialty roasters and Manhattan fast-casual chains consolidate supplier relationships around vertically integrated producers. New York Department of Agriculture and Markets regulates plant-based beverage labeling compliance. Refrigerated bottles capture disproportionate shelf space in premium retail across Boston, New York, and Philadelphia metros.
Upper Midwest
Minnesota and North Dakota oat growing regions concentrate grain supply risk from drought cycle exposure. USDA's BioPreferred Program mandates plant-based alternatives in federal institutional foodservice contracts. Minneapolis-St. Paul processing facilities leverage proximity to raw material sourcing for cost-competitive ambient carton production.
Southeast
Florida and Georgia metros remain below national per-capita consumption averages, offering expansion runway for refrigerated distribution networks. FDA labeling guidance reshapes formulation priorities for products entering these markets. Atlanta and Miami foodservice procurement teams are consolidating around national brands with guaranteed year-round volume.
United States Oat Milk Market Competitive Landscape
Premium-margin players sit above commodity-margin players across enzymatic processing capability and coffee-channel certification. The competitive set fragments into three tiers: proprietary technology holders, integrated West Coast manufacturers, and price-competitive conventional grocery suppliers. Strategic moves concentrate on direct foodservice contract consolidation and enzymatic processing capacity expansion.
Within the proprietary technology tier, Oatly Group and Califia Farms exemplify divergent geographic anchoring strategies. Oatly Group occupies a position representing enzymatic production process differentiation for coffee-service channels. Califia Farms exemplifies integrated manufacturing proximity to raw material and demand clusters. Planet Oat sits within the price-competitive conventional grocery tier, representing volume-scale positioning against premium alternatives.
| Leading Market Players |
|---|
| Califia Farms |
| Campbell Soup Company |
| Chobani |
| Danone |
| Elmhurst |
| HP Hood |
| Oatly Group |
| Planet Oat |
| Ripple Foods |
| Others |
Pricing and Supply Chain Analysis
USDA BioPreferred Program mandates for federal institutional foodservice contracts gate qualified supply access and premium-tier pricing power, concentrating procurement relationships around certified producers capable of meeting sustainability documentation requirements while commanding 15-25% price premiums over uncertified alternatives.
Pricing Analysis
Microfoam performance in steam-pressure applications anchors value-based pricing for Barista Blend formulations, with third-wave coffee shops in Portland, Seattle, and Brooklyn paying substantial premiums for batch-to-batch consistency. Price differentiation separates organic-certified products from conventional alternatives, with the former extracting sustained premiums despite higher input costs. Cost compression in conventional grocery tiers is intensifying as Planet Oat and private-label alternatives compete on shelf price. Food manufacturers represent the most price-sensitive buyer segment, while specialty coffee chains demonstrate lowest sensitivity due to operational dependency on functional performance.
Supply Chain Analysis
Dual-sourcing requirements from large restaurant chains mandate multi-supplier qualification for national beverage programs, fragmenting volume across Oatly Group, Califia Farms, and Chobani to mitigate batch-variability risk. Geographic supply concentration centers on California's Bakersfield manufacturing cluster and Pacific Northwest processing facilities, with Minnesota and North Dakota oat growing regions feeding raw material inputs. Single-source vulnerability sits with proprietary enzymatic processing expertise concentrated among three scaled producers. Distribution runs through distinct refrigerated and ambient channels, with the former capturing premium retail placement in Northeast and California markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic processing capacity scarcity props pricing across premium tiers, with 18-24 month certification timelines for new USDA organic processing lines constraining qualified supply expansion and sustaining margin pools for incumbent certificate holders.
For Market Incumbents: Deploy backward integration into Minnesota and North Dakota oat grain sourcing to secure supply stability against drought cycle exposure. Incumbent producers should consolidate direct foodservice contracts with fast-casual chains before precision fermentation entrants achieve commercial scale, while expanding Bakersfield manufacturing footprint to capture Southeast distribution expansion.
For New Entrants and Emerging Players: Precision fermentation of oat-derived proteins offers a technology-first wedge for functional nutrition positioning beyond commodity beverage applications. New entrants should target Southeast and Mountain West metros below national per-capita consumption averages, entering through refrigerated bottle formats in premium retail before scaling to conventional grocery.
For Investors and Strategic Acquirers: FDA protein threshold guidance finalization is the leading indicator that reformulation compliance costs will consolidate the competitive set around scaled fortification capabilities. Long-term viability favors producers with integrated manufacturing and certified organic processing lines. Investors should monitor corporate sustainability procurement mandate adoption rates among Fortune 500 foodservice operators as the signal for demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Capacity Expansion | Proprietary viscosity reduction technology secures coffee-channel certification and premium positioning. |
| USDA Organic Certification Investment | Eighteen-month approval timelines create barrier-to-entry protection for scaled producers. |
| Direct Foodservice Contract Consolidation | National chain procurement teams displace fragmented distributor relationships for volume guarantees. |
| Refrigerated Distribution Network Buildout | Bottle format shelf space capture in Northeast and California retail commands 30-40% price premiums. |
| Precision Fermentation R&D Partnership | Hybrid formulation pathways open functional nutrition applications beyond commodity beverage positioning. |
Research Methodology
SEC 10-K filings, USDA organic processor certification databases, and FDA labeling guidance documents formed the secondary backbone, supplemented by Nielsen retail audit data and customs records for oat grain import flows. Primary interviews with enzymatic processing engineers, specialty coffee procurement directors, fast-casual chain beverage program managers, and USDA BioPreferred Program administrators validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled facility capacity estimates against channel-level volume flows.
Bottom-up modeling anchored volume projections to enzymatic processing line throughput and certification-constrained capacity expansion timelines across the analysis window. Segmentation dimensions included product type tier, packaging temperature requirement, distribution channel, and end-use application sophistication. CAGRs derived from facility investment pipelines and procurement contract renewal cycles. Industry-specific forecast inputs incorporated drought cycle frequency in upper Midwest growing regions and FDA guidance implementation timelines.
Several conditions sit outside the modeled scope, including pending protein threshold regulatory finalization, precision fermentation commercialization acceleration, and corporate sustainability mandate adoption velocity. Deviation in FDA nutritional equivalence enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Dairy-Free Spreads Market
Dairy Alternatives
Dairy Whiteners Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
Canada Dairy Alternatives Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
Dairy-Free Creams Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
South Korea Dairy Alternatives Market
Dairy Alternatives
Hazelnut Milk Market