
 Dairy Alternatives Market | 2026-2036
Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Alternatives Market Analysis
Specialty cafés and third-wave coffee chains is collapsing the traditional household-centric demand model for dairy alternatives. Oatly Group AB leverages its barista-series formulation to dominate café supply relationships across Nordic and North American markets. Danone S.A. anchors its position through backward integration into organic soy sourcing and European manufacturing scale. Blue Diamond Growers competes on almond cultivation control in California's Central Valley, sustaining raw material cost advantages.
Dairy alternatives comprise plant-derived beverages formulated from nuts, legumes, cereals, or seeds through aqueous extraction, enzymatic treatment, and homogenization to achieve protein content ranging from 0.5% to 8% and fat profiles mimicking bovine milk. These products serve commercial and retail channels requiring functional foaming, neutral flavor bases, or allergen-free formulations for direct consumption and foodservice applications. Oat milk leads growth velocity within product type segmentation due to superior foaming stability and lower environmental water intensity compared to almond. Distribution channel dynamics reveal supermarkets occupying volume leadership while online retail captures the fastest expansion trajectory through subscription replenishment models.
EU Green Deal sustainability criteria and REACH chemical safety standards govern ingredient sourcing and packaging recyclability across European dairy alternative supply chains. FDA nutritional labeling mandates and USDA organic certification requirements shape product positioning and market access thresholds in the United States. Stakeholders must monitor evolving protein content equivalence standards and carbon footprint disclosure obligations as regulators tighten comparative claims against conventional dairy.
Market Dynamics
Café-grade oat milk procurement is concentrating demand among third-wave coffee chains, collapsing the traditional retail-first distribution hierarchy and forcing reformulation priorities around foaming stability and neutral flavor bases.
Growth Catalysts
- EU Green Deal sustainability criteria:Mandatory carbon footprint disclosure and packaging recyclability standards accelerate investment in oat and pea protein sourcing with lower water intensity than almond.
- Specialty coffee channel expansion:Barista-series formulations now anchor supply relationships across Seoul, Berlin, and São Paulo, creating pull-through effects into retail shelf placement.
- Enzymatic treatment advances:Novel beta-glucanase applications improve mouthfeel and reduce viscosity separation, enabling clean-label positioning without stabilizer additives.
Market Restraints
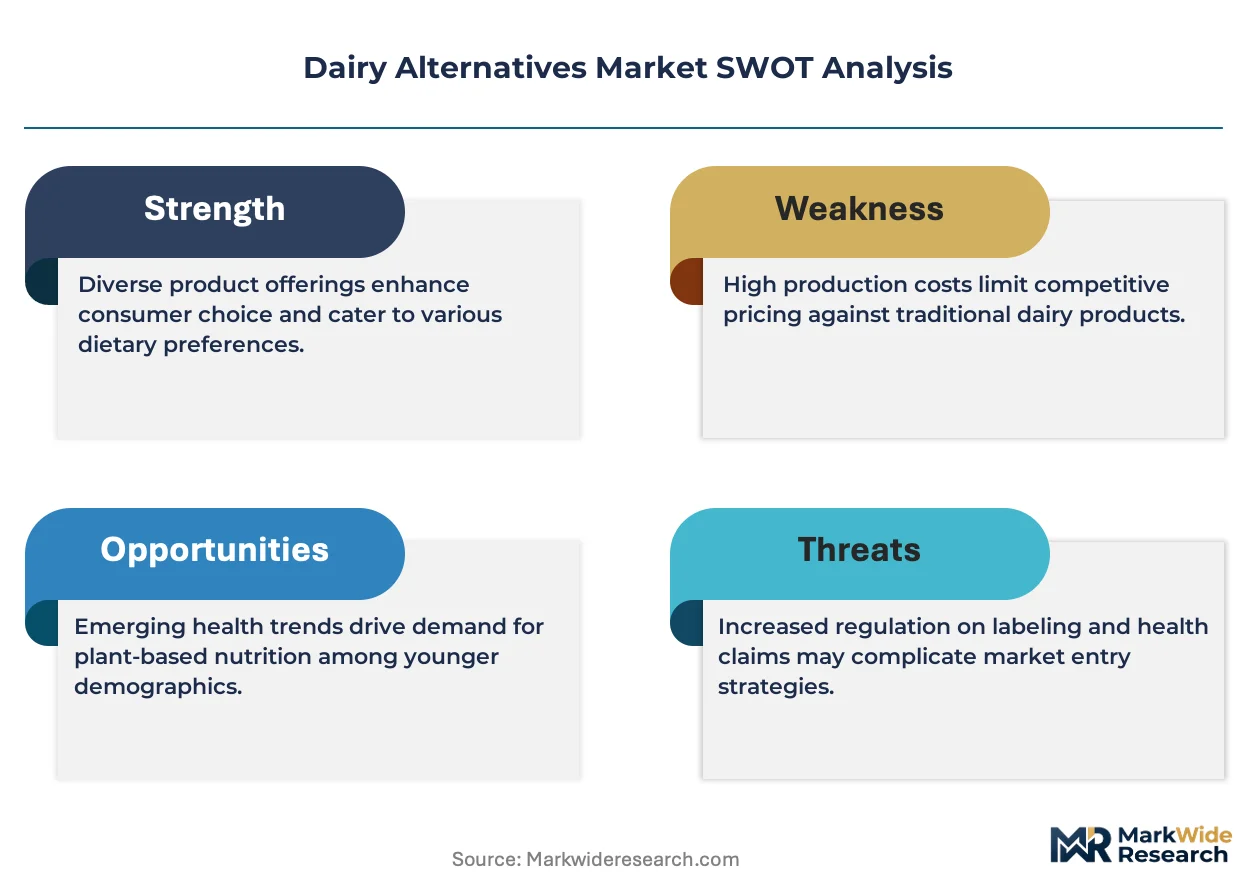
- Almond cultivation concentration:California's Central Valley supplies over 80% of global almond milk feedstock, exposing processors to drought-driven price volatility and pollinator colony collapse risks.
- Protein equivalence shortfalls:Most cereal and nut milks deliver 1-2% protein versus 3.4% in bovine milk, limiting nutritional claim parity and school nutrition program eligibility.
- REACH chemical safety compliance:ECHA scrutiny of processing aids and enzymatic residues creates reformulation costs and timeline uncertainty for European market entry.
Strategic Opportunities
- Fermentation-derived precision proteins:Microbial biomass cultivation enables complete amino acid profiles without agricultural land use, opening premium positioning above plant-extracted alternatives.
- Subscription replenishment models:Direct-to-consumer platforms capture recurring household demand with flavor rotation and carbon-offset bundling, bypassing slotting fee barriers in conventional retail.
- China tier-two city penetration:Soy milk cultural familiarity in Shanghai and Beijing creates brand equity transfer potential into Hangzhou, Chengdu, and Wuhan retail expansion.
Industry Challenges
- Barista training and equipment calibration:Oat milk's distinct thermal behavior demands steam wand technique modification and espresso machine pressure adjustments, creating foodservice onboarding friction.
- Organic certification timeline compression:USDA organic and EU organic conversion periods for new oat and pea suppliers extend 24-36 months, constraining rapid scaling of certified product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Alternatives Market |
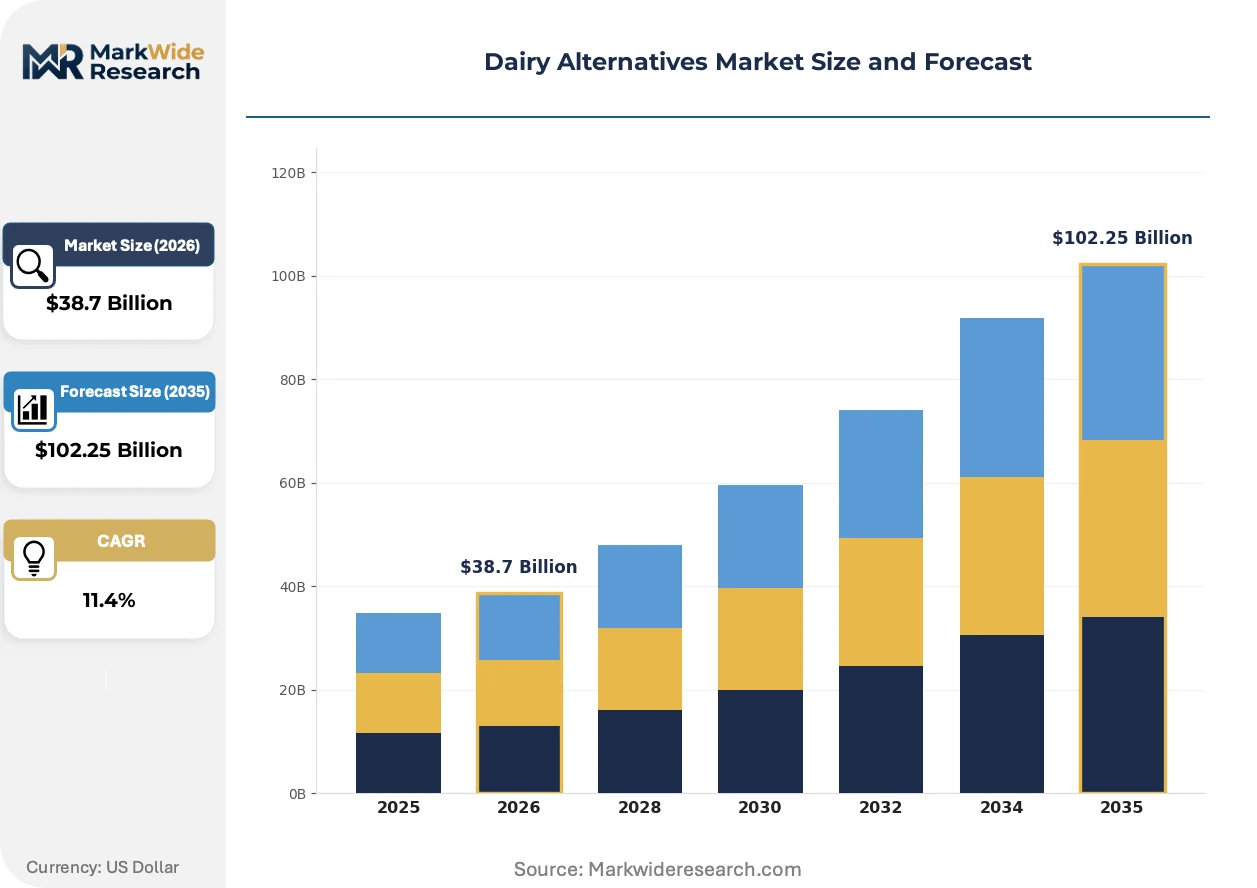
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk End User: Households, Restaurants, Cafés, Bakeries Packaging Type: Cartons, Glass Bottles, Tetra Packs, Pouches Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Shops |
| Companies Covered | Danone S.A., Blue Diamond Growers, Oatly Group AB, The Hain Celestial Group, Inc., SunOpta, Inc., Califia Farms, Vitasoy International Holdings Limited, Daiya Foods, Ripple Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Alternatives Market Emerging Trajectories
Formulation science and regulatory disclosure mandates are splitting product development paths between clean-label minimalism and functional fortification, with divergent capital allocation and channel targeting for each trajectory.
Enzymatic hydrolysis of oat beta-glucans is bifurcating the texture-performance segment. Barista-focused suppliers adopt high-viscosity formulations for latte art stability, while beverage manufacturers prioritize low-viscosity bases for flavored ready-to-drink lines. This technical divergence is compressing shared ingredient sourcing economies and forcing separate production line investments.
CSRD corporate sustainability reporting requirements and EU Green Deal carbon border adjustments are mandating scope 3 agricultural emissions disclosure. Ingredient suppliers must now document cultivation energy use and transport refrigeration footprints. Oat processors with Nordic sourcing contracts hold structural advantage over almond-dependent competitors facing California irrigation intensity scrutiny.
Third-wave coffee chains now specify exclusive oat milk supply agreements with volume commitments and technical service support, displacing multi-brand distributor relationships. This buyer concentration compresses supplier margins while locking in formulation stability requirements. São Paulo and Seoul café clusters demonstrate the procurement model's geographic transferability beyond its Nordic origins.
Dairy Alternatives Market Segmentation
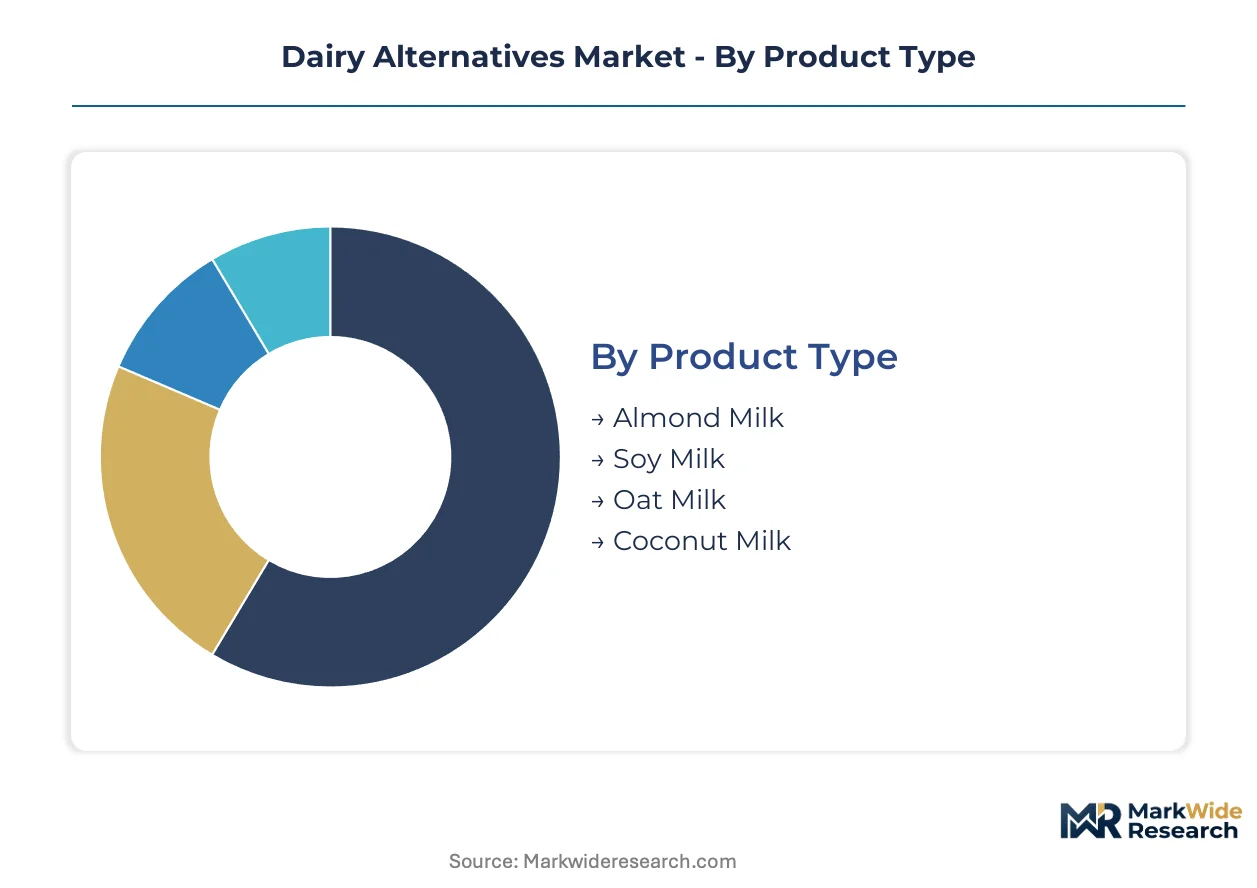
Dairy alternatives fragment across formulation bases, consumption contexts, and route-to-market economics. Understanding margin concentration by segment reveals where formulation investments and channel partnerships yield sustainable returns.
Product Type:
Premium margin pools concentrate in oat and almond formulations where café-grade specifications command supply premiums and retail shelf positioning fees.
- Almond Milk:Formulated from California Central Valley almonds through aqueous extraction and homogenization, delivering 1-2% protein with neutral flavor profiles. Demand concentrates in US retail channels where almond milk anchors the plant-based refrigerated case, though drought-driven feedstock volatility compresses processor margins during water-scarce growing seasons.
- Oat Milk:Produced via enzymatic hydrolysis of Nordic-sourced oats, achieving superior beta-glucan stability for barista-grade foaming at 2-4% fat content. Specialty cafés in Seoul, Berlin, and São Paulo now specify exclusive oat milk supply agreements, creating pull-through effects into retail placement and locking in formulation stability requirements across Nordic and North American manufacturing bases.
- Soy Milk:Traditional aqueous extraction of East Asian soybean varieties yields 3-4% protein, the highest among plant-derived alternatives. China's tier-one cities retain soy milk's cultural dominance despite almond and oat encroachment.
- Coconut Milk:High-fat emulsion from Southeast Asian coconut cream, typically 15-25% fat content, serving culinary and beverage applications requiring tropical flavor profiles. Southeast Asian sourcing contracts dominate feedstock procurement.
Almond milk holds installed capacity across California processing infrastructure. Oat milk is rotating up the share rankings through café channel specification.
End User:
Volume concentration has shifted from household retail toward foodservice procurement, collapsing the traditional retail-first distribution hierarchy.
- Cafés:Third-wave coffee chains now drive oat milk procurement volumes through barista-series formulation requirements, demanding technical service support and exclusive supply agreements that compress supplier margins while ensuring formulation consistency.
- Restaurants:Full-service dining operations require neutral-flavor bases for recipe integration across sauces, soups, and desserts, with procurement decisions centralized through broadline distributors.
- Households:Traditional retail-centric demand now follows foodservice trial, with consumers replicating café experiences through supermarket and online replenishment channels.
- Bakeries:Specialized applications requiring specific protein content and fat profiles for dough conditioning and cream fillings, with regional artisanal bakeries driving niche formulation requests.
Cafés command specification authority. Households represent the steepest expansion trajectory through subscription replenishment models.
Packaging Type:
EU Green Deal recyclability mandates and FDA nutritional labeling requirements are bifurcating packaging investment between sustainable materials and functional barrier properties.
- Tetra Packs:Aseptic carton systems with aluminum-polyethylene barrier layers enabling ambient distribution and extended shelf stability. European regulators scrutinize multi-material recyclability under CSRD disclosure requirements.
- Cartons:Refrigerated gable-top containers for short-shelf-life products, dominating US supermarket dairy cases with lower unit economics than aseptic alternatives.
- Glass Bottles:Premium positioning through reusable and returnable systems, concentrated in European deposit-return schemes and specialty health food channels.
- Pouches:Flexible film formats for single-serve and on-the-go consumption, gaining traction in Asian convenience retail with lower shipping weight and shelf space requirements.
Tetra Packs hold installed capacity across European and North American aseptic filling lines. Pouches are climbing the fastest in Asian convenience channel penetration.
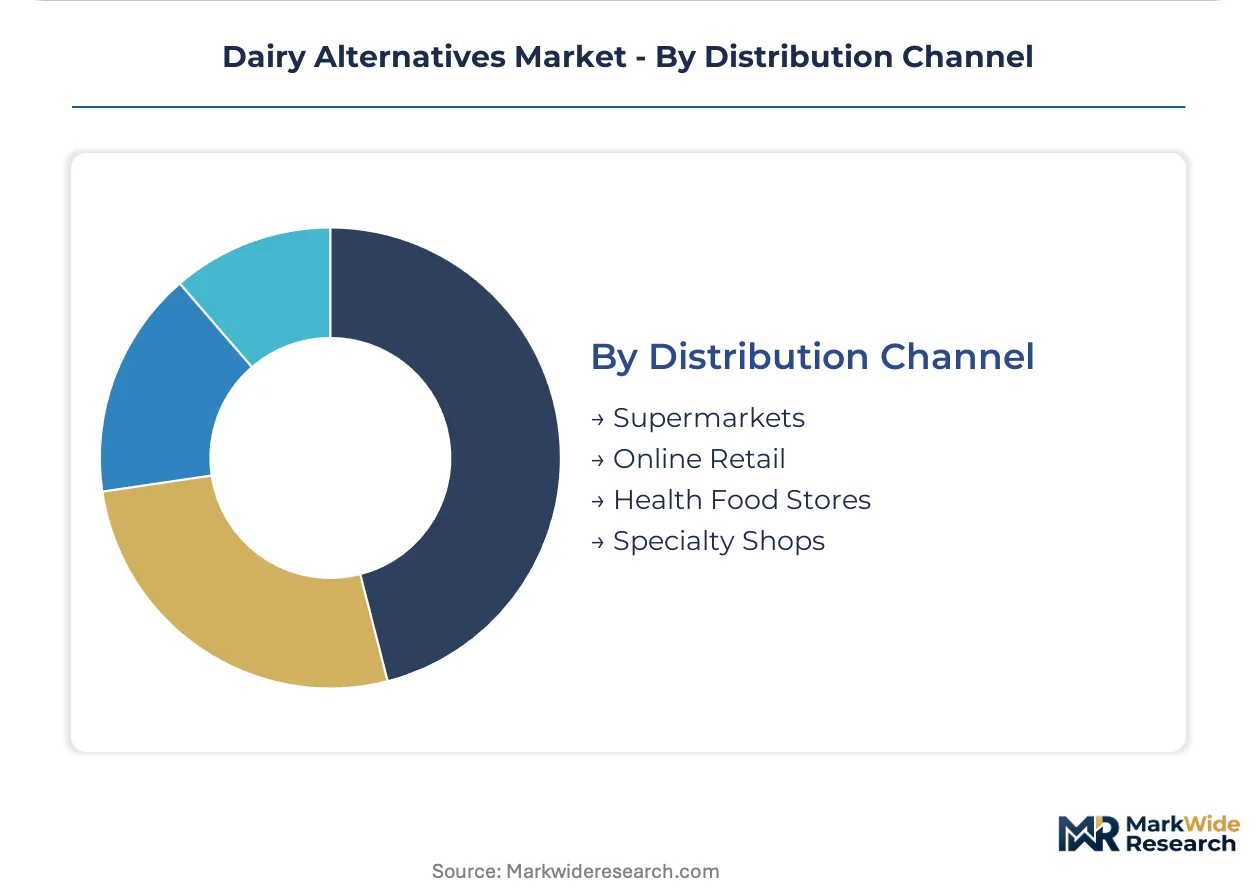
Distribution Channel:
Slotting fee structures and direct-to-consumer economics are splitting capital allocation between conventional retail scale and subscription platform development.
- Supermarkets:Volume leadership through refrigerated and ambient shelf placement, with slotting fees and promotional spending requirements favoring processors with Danone-scale manufacturing economics.
- Online Retail:Subscription replenishment models bypass slotting barriers through direct-to-consumer platforms, capturing recurring household demand with flavor rotation and carbon-offset bundling.
- Health Food Stores:Curated assortment of organic-certified and clean-label formulations, serving as trial channels for novel protein bases before mainstream retail expansion.
- Specialty Shops:Independent retailers and regional chains emphasizing local sourcing and artisanal production, with limited scale but high-margin positioning for premium formulations.
Supermarkets anchor volume throughput. Online retail is gaining share fastest through subscription platform economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Europe's role as the primary entry point for Nordic oat feedstock, while California's Central Valley irrigation networks anchor almond milk's raw material base.
United States
Third-wave coffee chains in Portland and Brooklyn drive oat milk procurement through exclusive supply agreements. FDA nutritional labeling mandates and USDA organic certification requirements shape formulation standards. California's Central Valley concentrates almond cultivation, exposing processors to drought-driven price volatility and pollinator colony collapse risks.
Germany
Berlin's specialty café cluster specifies barista-grade oat milk formulations with technical service support requirements. EU Green Deal sustainability criteria and REACH chemical safety standards govern ingredient sourcing and packaging recyclability. Hamburg's port facilities enable Nordic oat import logistics for Central European processing operations.
China
Tier-one cities Shanghai and Beijing retain soy milk's cultural dominance while almond and oat formats gain retail shelf space. SAMR food safety regulations and GB standards for plant-based beverages establish market access thresholds. Hangzhou's e-commerce platforms drive subscription replenishment model adoption for dairy alternative distribution.
Brazil
São Paulo's café culture replicates Nordic oat milk procurement models through third-wave coffee chain expansion. ANVISA nutritional labeling requirements govern product positioning in Latin America's largest consumer market. Minas Gerais soybean cultivation supports domestic soy milk processing infrastructure.
South Korea
Seoul's specialty café density drives oat milk volume procurement through exclusive supply relationships. MFDS food additive regulations and organic certification standards shape import requirements. Busan's port infrastructure handles Nordic and Australian oat feedstock arrivals for domestic formulation operations.
Dairy Alternatives Market Vendor Landscape
Concentration sits with multinational food conglomerates and specialized plant-based challengers competing across café supply relationships and retail shelf positioning. The vendor base spans three tiers: diversified dairy majors with backward integration into organic sourcing, oat-focused specialists leveraging barista-series formulations, and nut-milk processors controlling California cultivation assets. Competitive moves center on exclusive café supply agreements with volume commitments and enzymatic treatment licensing for texture-performance differentiation.
Within the diversified conglomerate tier, Danone S.A. and Blue Diamond Growers exemplify contrasting sourcing strategies—Danone through European organic soy supply chain control, Blue Diamond through captive almond cultivation in California's Central Valley. Oatly Group AB occupies the specialist position, representing the barista-grade formulation archetype that third-wave coffee chains specify across Nordic and North American markets.
| Leading Market Players |
|---|
| Danone S.A. |
| Blue Diamond Growers |
| Oatly Group AB |
| The Hain Celestial Group, Inc. |
| SunOpta, Inc. |
| Califia Farms |
| Vitasoy International Holdings Limited |
| Daiya Foods |
| Ripple Foods |
| Others |
Supply Flow & Price Mechanics
Oat milk's displacement of almond milk in café supply contracts simultaneously rotates sourcing geography toward Nordic oat cultivation and compresses pricing premiums previously sustained by California almond dependency. This substitution dynamic restructures procurement economics as third-wave coffee chains consolidate volume commitments around enzymatically treated oat bases.
Pricing Analysis
Volume-discount tiering structures separate barista-grade formulations from retail commodity alternatives, with café-exclusive supply agreements commanding 15-30% premiums over supermarket SKUs. Price differentiation rests on enzymatic treatment licensing and organic certification status rather than raw material costs alone. Pricing pressure stems from buyer concentration among third-wave coffee chains extracting technical service concessions. Household subscribers through direct-to-consumer platforms exhibit lowest price sensitivity, while conventional retail slotting fees force margin compression on standard-tier products.
Supply Chain Analysis
Inventory lead times for Nordic oat feedstock extend 8-12 weeks versus 4-6 weeks for California almonds, creating working capital intensity differentials across processor balance sheets. Geographic supply concentration centers on Sweden and Finland for oat cultivation, California's Central Valley for almonds, and China's Northeast Plain for soybeans. Raw material dependencies include beta-glucanase enzymes, aseptic packaging films, and organic certification audit services. Single-source vulnerability concentrates in California irrigation networks facing drought-driven yield volatility. Distribution runs through Rotterdam's cold chain infrastructure for European formulation, Long Beach port clusters for North American processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dairy alternatives market tracks a cyclical recovery pattern as foodservice channel normalization follows pandemic-era retail stockpiling distortions. Café procurement volumes now anchor demand forecasting with greater predictability than household replenishment patterns.
For Market Incumbents: Consolidate backward integration into Nordic oat sourcing contracts before EU Green Deal carbon border adjustments tighten feedstock traceability requirements. Lock in exclusive barista-series formulation agreements with Seoul and São Paulo café clusters to preempt specialist challengers from establishing technical service relationships. Capacity additions in Hamburg and Busan processing hubs will defend margin position against freight cost inflation on transoceanic oat shipments.
For New Entrants and Emerging Players: Differentiate on fermentation-derived precision proteins to bypass agricultural land-use constraints and command premium positioning above plant-extracted alternatives. White-space targets include China's tier-two cities where soy milk brand equity transfers incompletely, and subscription replenishment platforms lacking flavor rotation capabilities. A direct-to-consumer launch with carbon-offset bundling bypasses slotting fee barriers while capturing recurring household demand.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed oat specialists holding barista-grade formulation IP but lacking retail distribution scale. Long-term viability over a 5-10 year horizon hinges on enzymatic treatment licensing revenue streams rather than commodity processing margins. Acquisition targets should demonstrate exclusive café supply relationships in at least two of Seoul, Berlin, and São Paulo. The signal to watch is FDA protein equivalence standard tightening that would disqualify low-protein cereal milks from school nutrition program eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Café Supply Agreement | Locks in volume commitments with third-wave coffee chains in Seoul, Berlin, and São Paulo. |
| Backward Integration into Organic Oat Sourcing | Secures Nordic cultivation contracts ahead of EU Green Deal carbon disclosure mandates. |
| Enzymatic Treatment Licensing | Monetizes beta-glucanase IP for texture-performance differentiation in barista formulations. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees through recurring household replenishment with flavor rotation. |
| Fermentation-Derived Protein Development | Opens premium positioning above plant-extracted alternatives via microbial biomass cultivation. |
Methodological Framework
Initial hypotheses were tested against primary input from café procurement managers, enzymatic treatment suppliers, organic certification auditors, and refrigerated logistics operators, then refined through secondary validation. Bottom-up triangulation combined Nielsen retail audit data, EU import statistics for oat feedstock, FDA nutritional labeling filings, and SEC disclosures from publicly traded processors. Top-down cross-checks applied macroeconomic consumption elasticity models to foodservice channel recovery patterns.
Variance-decomposition across the projection horizon isolates volume drivers by formulation base, end-use channel, and regional regulatory cluster. Segmentation dimensions modeled include product type, packaging format, distribution channel, and café versus household consumption context. CAGRs were derived from logistic diffusion curves fitted to foodservice adoption patterns and subscription platform penetration rates. Industry-specific inputs incorporated EU Green Deal compliance cost trajectories and enzymatic hydrolysis yield improvements.
The analysis sits within stated boundaries; outcomes outside sustained café channel expansion or accelerated FDA protein equivalence standard revision would require recalibration. Forecasts reflect assumptions regarding Nordic oat harvest stability and California irrigation allocation policy. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Oat Milk Market
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Rice Milk Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Australia Dairy Alternatives Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Vegan Ice Cream Market
Dairy Alternatives
North America Non-Dairy Yogurt Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Dairy-Free Ice Creams Market