
 Asia-Pacific Sour Milk Drinks Market | 2026-2036
Asia-Pacific Sour Milk Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sour Milk Drinks Market Outlook
Dairy microbiologist availability across the Asia-Pacific region is redrawing where fermentation capacity can expand. Yakult Honsha Co Ltd leverages its proprietary strain libraries to dominate probiotic drink segments in Japan and export markets. Gujarat Cooperative Milk Marketing Federation Ltd anchors India's curd and buttermilk supply through its Amul cooperative network, while Yili Group sustains large-scale yogurt production across China's northern dairy corridor.
Asia-Pacific sour milk drinks comprise fermented dairy beverages produced through controlled bacterial culture action on lactose, typically achieving pH ranges of 4.0 to 4.6 and viable probiotic counts exceeding 10^6 CFU per milliliter for functional claims. These products serve digestive health positioning, meal accompaniment, and refreshment purposes across diverse consumption occasions. Yogurt commands the largest revenue pool due to established breakfast and snacking rituals, while kefir represents the fastest-expanding category as consumers seek higher probiotic density. Distribution through supermarkets captures the dominant volume share, though online retail is accelerating fastest where cold-chain logistics have matured.
FSSAI in India, SAMR in China, and Japan's Food Sanitation Act collectively govern probiotic strain approvals, label claims, and maximum permissible additive levels across the region. These frameworks shape R&D priorities, as manufacturers reformulate to meet divergent national standards for live culture counts and health assertions. Stakeholders must monitor evolving strain registration pathways and cold-chain compliance costs as regulatory divergence between major markets intensifies.
Market Dynamics
FSSAI clean-label mandates and SAMR dairy safety protocols are compressing formulation timelines across the Asia-Pacific region, forcing manufacturers to rebuild supply chains around probiotic strain verification and additive transparency.
Growth Catalysts
- Functional beverage positioning:Health-conscious adults in urban India and Southeast Asia are integrating probiotic drinks into daily routines for digestive wellness claims, expanding addressable occasions beyond traditional meal accompaniment.
- Cooperative processing infrastructure:Maharashtra and Gujarat dairy belts in India leverage Amul's established cold-chain networks to achieve volume scale in curd and buttermilk distribution with minimal capital duplication.
- FSSAI strain registration pathways:India's streamlined approval framework for documented probiotic cultures accelerates product launch cycles compared to multi-year registration timelines in adjacent markets.
Market Restraints
- Live culture cold-chain dependency:Viable probiotic counts exceeding 10^6 CFU per milliliter require uninterrupted refrigeration from production through retail, elevating logistics costs in tropical climates with unreliable electricity infrastructure.
- Dairy microbiologist scarcity:Fermentation capacity expansion faces hard constraints from limited specialist availability across Vietnam, Indonesia, and Philippines, concentrating technical expertise in Japan and select Indian clusters.
- Regulatory divergence friction:Divergent strain approval requirements between Japan's Food Sanitation Act and China's SAMR protocols block standardized product portfolios, forcing market-specific reformulation investments.
Strategic Opportunities
- E-commerce cold-chain maturation:Online retail channels in tier-2 Chinese cities and Indian metros are achieving same-day refrigerated delivery, unlocking direct-to-consumer subscription models for kefir and drinkable yogurt.
- Kefir category white space:Higher probiotic density positioning in Australia's urban centers and South Korea's Seoul metropolitan area targets consumers dissatisfied with conventional yogurt's microbial load.
- PLI scheme alignment:India's production-linked incentive schemes for food processing infrastructure subsidize fermentation vessel capacity additions in Madhya Pradesh and Rajasthan, extending cooperative reach beyond traditional dairy belts.
Industry Challenges
- pH stability validation:Maintaining 4.0 to 4.6 pH ranges through shelf life requires real-time monitoring systems that many mid-scale processors in Thailand and Malaysia lack technical capacity to implement.
- Clean-label reformulation timelines:Removing permitted additives to meet FSSAI tightening standards while preserving taste and texture profiles demands extended R&D cycles that compress margin recovery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sour Milk Drinks Market |
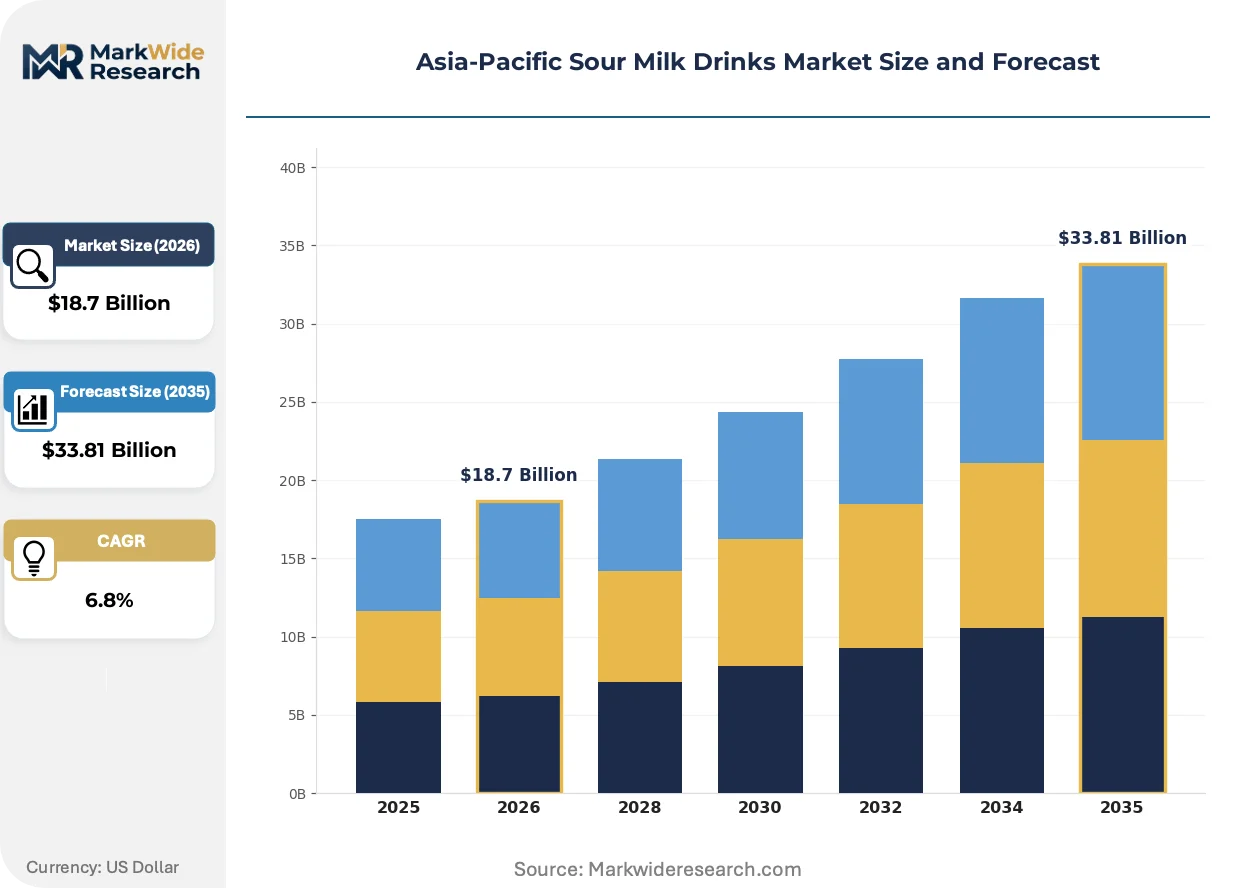
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt, Kefir, Buttermilk, Curd Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores Consumer Age Group: Children, Adults, Seniors, Teenagers Flavor Profile: Plain, Fruit Flavored, Spiced, Herbal |
| Companies Covered | Meiji Holdings Co Ltd, Mother Dairy Fruit & Vegetable Pvt Ltd, Nestle SA, Lion Dairy & Drinks, Karnataka Co-operative Milk Producers Federation Ltd, Yili Group, Gujarat Cooperative Milk Marketing Federation Ltd (GCMMF), Yakult Honsha Co Ltd, Danone SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sour Milk Drinks Market Strategic Shifts
Controlled fermentation technologies and distribution infrastructure investments are redrawing competitive boundaries across the Asia-Pacific sour milk drinks landscape, with probiotic density claims and transparency mandates driving product architecture decisions.
Aseptic fermentation systems with integrated pH monitoring is bifurcating production economics across the region. Large-scale processors in China's Hebei and Shandong provinces are deploying continuous-flow bioreactors that reduce batch-to-batch variability, while smaller traditional producers in India's unorganized sector remain tethered to static tank methods with higher spoilage rates. This equipment gap is compressing mid-tier manufacturer margins and accelerating consolidation toward technology-capable facilities.
Japan's Food Sanitation Act amendments regarding specified health use labeling are tightening probiotic strain documentation requirements for functional claims. Manufacturers must now submit culture viability data across simulated shelf-life conditions, extending pre-market preparation phases. Drinkable yogurt segments targeting elderly consumers with gut health positioning face the steepest compliance burden, with several domestic players reformulating to generic fermented milk classifications to bypass functional claim scrutiny.
Urban Indian households are fragmenting bulk dairy purchases into single-serve probiotic drink formats through quick-commerce platforms. Swiggy Instamart and Blinkit in Mumbai and Bangalore are prioritizing refrigerated dark store placement for buttermilk and lassi SKUs, displacing traditional kirana store weekly stocking patterns. This channel shift concentrates demand volatility in metropolitan fulfillment networks while reducing brand loyalty stickiness through algorithmic substitution suggestions.
Asia-Pacific Sour Milk Drinks Market Segmentation
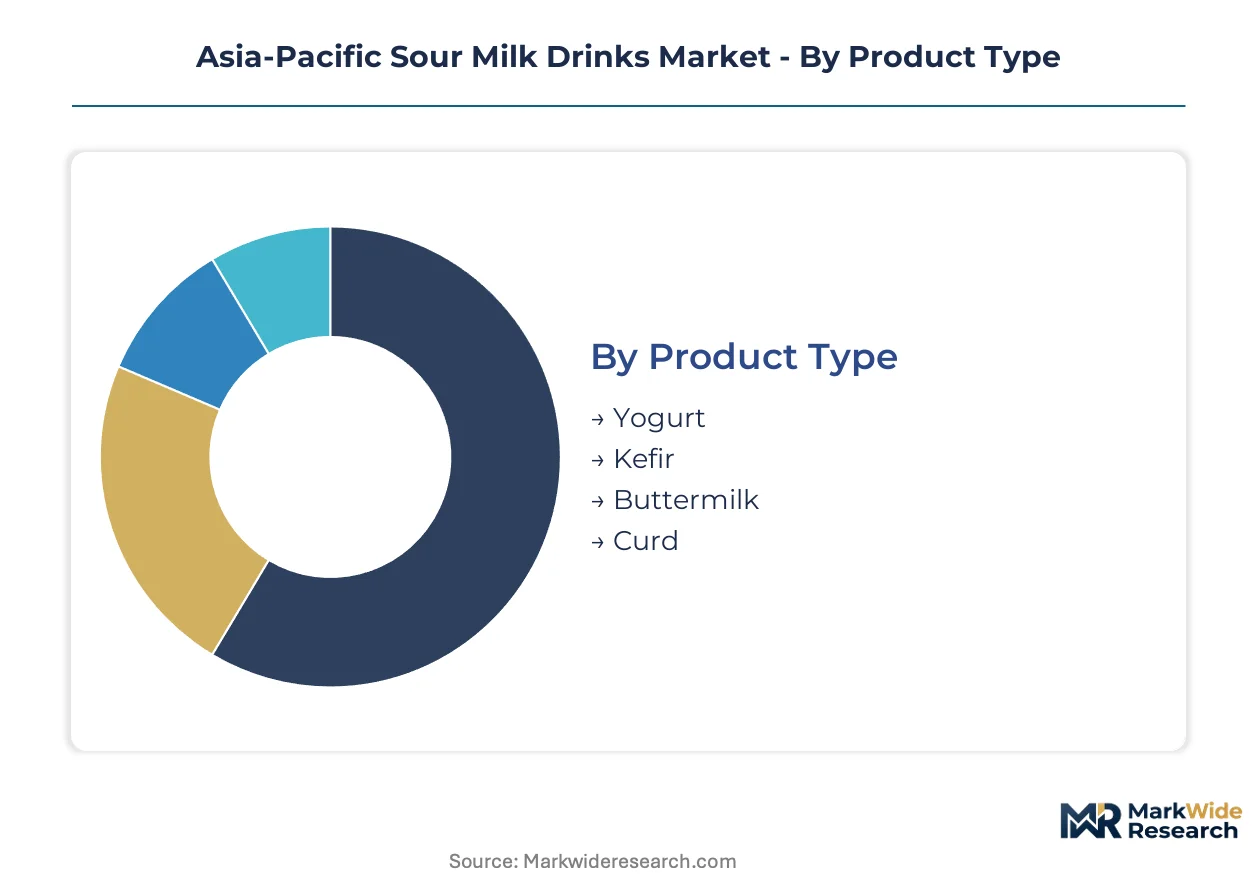
Asia-Pacific sour milk drinks fragment across four structural dimensions that determine formulation priorities, cold-chain investments, and channel economics. Product architecture decisions hinge on probiotic density claims and pH stability requirements, while distribution choices reflect urban infrastructure maturity and electricity reliability.
Product Type:
Domestic consumption anchors yogurt and curd production across India and China, whereas kefir exports from Australia and South Korea target premium positioning in Japan and Southeast Asian metros.
- Yogurt:Fermented dairy achieving pH 4.0-4.6 with standardized culture blends dominates breakfast and snacking rituals. Demand concentrates in China's northern dairy corridor and India's Maharashtra cooperative belt, where established cold chains support viable 10^6 CFU/ml counts through retail.
- Kefir:Higher probiotic density beverages using kefir grains rather than single-strain cultures attract health-conscious adults seeking digestive wellness beyond conventional yogurt. Australia's urban centers and Seoul metropolitan area drive category expansion as consumers trade up for microbial load transparency.
- Buttermilk:Traditional churned-byproduct drinks serve meal accompaniment functions across South India and Gujarat, distributed through Amul's cooperative networks with minimal additive profiles.
- Curd:Set-fermented dairy with firm texture anchors daily consumption in Indian households, produced through static tank methods in both organized dairy cooperatives and unorganized regional processors.
Yogurt commands the established base. The steepest expansion runs through kefir.
Distribution Channel:
Channel selection stratifies by refrigeration infrastructure investment, with supermarkets and online retail absorbing capital-heavy cold-chain requirements while convenience stores serve ambient-stable formats.
- Supermarkets:Dominant volume capture occurs through refrigerated aisle placement in tier-1 Chinese cities and Indian metros, where hourly temperature monitoring validates probiotic viability claims. FSSAI and SAMR compliance documentation accompanies shelf placement negotiations.
- Online Retail:Same-day refrigerated delivery models in Bangalore, Mumbai, and tier-2 Chinese cities enable subscription-based kefir and drinkable yogurt purchases. Quick-commerce platforms prioritize dark store refrigeration investments to displace traditional kirana stocking patterns.
- Convenience Stores:Ambient-stable UHT yogurt drinks and long-life buttermilk SKUs penetrate transit-oriented consumption in Tokyo, Bangkok, and Jakarta where cold-chain continuity remains unreliable.
- Health Food Stores:Premium probiotic positioning targets elderly consumers in Japan and fitness-oriented adults in Australian cities, with strain-specific labeling and organic certification commanding price premiums.
Supermarkets retain volume leadership. Online retail climbs fastest where logistics infrastructure matures.
Consumer Age Group:
Demand concentration shifts toward adult wellness positioning as pediatric dairy consumption faces added-sugar scrutiny and senior gut-health claims encounter Japan's tightened functional labeling requirements.
- Adults:Health-conscious urban professionals in Southeast Asian metros and Indian tier-1 cities integrate probiotic drinks into daily routines, expanding occasions beyond traditional meal accompaniment.
- Seniors:Japan's elderly population drives drinkable yogurt demand with digestive health positioning, though Food Sanitation Act amendments force reformulation toward generic fermented milk classifications to bypass documentation burdens.
- Children:Flavored yogurt pouches and probiotic milk beverages face FSSAI sugar-content restrictions in India, compressing formulation flexibility for pediatric SKUs.
- Teenagers:Single-serve formats through quick-commerce platforms capture fragmented purchasing in Seoul, Tokyo, and Mumbai metropolitan areas with algorithmic substitution reducing brand loyalty stickiness.
Adult segments anchor current revenue. Senior-targeted functional claims face regulatory headwinds.
Flavor Profile:
Clean-label mandates from India's FSSAI and China's SAMR are compressing artificial flavor and additive tolerance, favoring plain and fruit-derived profiles over synthetic compounded alternatives.
- Plain:Unflavored yogurt and kefir serve recipe integration and health-purist positioning, dominating cooperative-branded curd and buttermilk distribution across Gujarat and Maharashtra.
- Fruit Flavored:Mango, strawberry, and mixed berry profiles capture children's and teenager segments in urban Indian and Southeast Asian markets, with natural extract reformulation replacing artificial compounds under tightening additive regulations.
- Spiced:Traditional masala buttermilk and cumin-laced lassi variants penetrate South Indian and North Indian regional markets through heritage brand recognition.
- Herbal:Ashwagandha, turmeric, and tulsi infusions target Ayurveda-aligned wellness consumers in Kerala, Karnataka, and metropolitan Indian markets with functional positioning beyond basic probiotic claims.
Plain formulations hold the volume core. Fruit-flavored variants adapt fastest to clean-label reformulation pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI clean-label mandates anchor India's regulatory influence across the Asia-Pacific sour milk drinks landscape, while SAMR protocols and Japan's Food Sanitation Act create divergent compliance pathways that reshape cross-border product strategies.
India
Maharashtra and Gujarat dairy belts drive volume through Amul's cooperative networks, with urban households fragmenting purchases into single-serve formats via quick-commerce platforms. FSSAI strain registration pathways accelerate launch cycles compared to multi-year timelines elsewhere. Madhya Pradesh and Rajasthan fermentation capacity expands under PLI scheme subsidies.
China
Yili Group sustains large-scale yogurt production across Hebei and Shandong provinces, deploying continuous-flow bioreactors that reduce batch variability. SAMR dairy safety protocols force reformulation investments for probiotic viability claims. Tier-2 cities achieve same-day refrigerated delivery, unlocking subscription models.
Japan
Tokyo and Osaka metropolitan areas consume drinkable yogurt targeting elderly gut-health positioning. Food Sanitation Act amendments tighten strain documentation requirements, forcing several domestic players toward generic fermented milk classifications. Yakult Honsha leverages proprietary strain libraries to dominate functional segments.
South Korea
Seoul metropolitan area consumers trade up to kefir for higher probiotic density beyond conventional yogurt offerings. MFDS regulations govern live culture count assertions on functional beverages. Domestic processors face technical constraints from dairy microbiologist scarcity relative to Japanese clusters.
Australia
Sydney and Melbourne urban centers anchor kefir category expansion targeting wellness-oriented adults dissatisfied with standard yogurt microbial loads. TGA oversight applies to therapeutic probiotic claims, though most products navigate standard food regulations. Export-oriented production supplies premium positioning in Japanese and Southeast Asian metros.
Asia-Pacific Sour Milk Drinks Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific sour milk drinks market. Cooperative networks achieve cost efficiency through shared infrastructure, while proprietary strain developers command premium positioning through R&D differentiation. The competitive landscape fragments across three strategic archetypes: multinational dairy conglomerates with diversified beverage portfolios, domestic cooperative federations leveraging regional milk sourcing, and specialized probiotic culture companies with strain IP advantages. Dominant competitive moves include fermentation capacity expansion in emerging dairy belts and technology licensing partnerships to bypass microbiologist scarcity constraints.
Among Japanese specialists, Yakult Honsha Co Ltd exemplifies the proprietary strain archetype, while China's Yili Group represents scale-driven production integration across northern dairy corridors. Gujarat Cooperative Milk Marketing Federation Ltd anchors India's cooperative model through Amul's established distribution networks. These three occupy distinct competitive positions without direct overlap in core capabilities or geographic dominance.
| Leading Market Players |
|---|
| Meiji Holdings Co Ltd |
| Mother Dairy Fruit & Vegetable Pvt Ltd |
| Nestle SA |
| Lion Dairy & Drinks |
| Karnataka Co-operative Milk Producers Federation Ltd |
| Yili Group |
| Gujarat Cooperative Milk Marketing Federation Ltd (GCMMF) |
| Yakult Honsha Co Ltd |
| Danone SA |
| Others |
Value Chain & Pricing Dynamics
Seven-to-fourteen-day fermentation batch cycles constrain working capital efficiency and concentrate pricing power among processors with continuous-flow bioreactor capacity in China's Hebei corridor and India's Gujarat cooperative belt. This lead-time rigidity amplifies margin pressure when FSSAI clean-label mandates force additive reformulation investments.
Pricing Analysis
Price spreads between Japanese metropolitan markets and Indian tier-2 cities exceed threefold for comparable kefir SKUs, reflecting cold-chain infrastructure gaps and strain registration cost differentials. Three-tier pricing structure across premium functional claims, standard probiotic positioning, and economy curd segments stratifies by certification level and viable culture count verification. Cost compression in the economy tier intensifies because Amul's cooperative scale and Yili's bioreactor automation squeeze mid-tier static-tank processors. Quick-commerce buyers in Mumbai and Seoul exhibit highest price sensitivity through algorithmic substitution, while health food store channels in Tokyo sustain lowest sensitivity via strain-specific loyalty.
Supply Chain Analysis
Just-in-time live culture replenishment dominates Japanese and South Korean processing, whereas Indian cooperatives maintain strategic buffer stocks of freeze-dried starter cultures against monsoon logistics disruption. Supply concentrates in India, China, and Japan, with Australia's kefir production feeding premium export positioning. Raw material dependencies center on lactose powder, food-grade nitrogen for aseptic packaging, and cold-chain refrigerants. Single-source vulnerability runs through proprietary strain libraries held by Yakult Honsha and select Japanese specialists. Distribution runs through supermarket refrigerated aisles in tier-1 cities, with quick-commerce dark stores displacing traditional kirana weekly stocking in Indian metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific sour milk drinks market sits in a cyclical recovery phase as post-pandemic digestive wellness positioning normalizes and cooperative infrastructure investments mature across India's emerging dairy belts.
For Market Incumbents: Shield margin structures by accelerating backward integration into captive starter culture production, reducing dependency on Yakult-licensed strain imports. Prioritize fermentation vessel capacity additions in Madhya Pradesh and Rajasthan under PLI scheme subsidies before microbiologist scarcity hardens in those corridors. Defend against quick-commerce algorithmic substitution by securing exclusive refrigerated dark store placements in Bangalore and Mumbai. For New Entrants and Emerging Players: Lead with kefir's higher probiotic density positioning in Australia's Sydney-Melbourne corridor and South Korea's Seoul metropolitan area, where consumer willingness to trade up exceeds established yogurt markets. Target the herbal-infused segment in Kerala and Karnataka, where Ayurveda-aligned wellness commands price premiums beyond basic functional claims. Deploy subscription-based direct-to-consumer models leveraging same-day refrigerated delivery maturation in tier-2 Chinese cities. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cooperative network scale advantages and proprietary strain IP are concentrating competitive returns in fewer hands. Target acquisition archetypes include mid-tier Indian processors with FSSAI-compliant clean-label portfolios but lacking bioreactor technology. Watch for inflection when China's SAMR announces streamlined strain registration reciprocity with Japan's Food Sanitation Act, signaling cross-border portfolio standardization feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Bioreactor Deployment | Yili Group's Hebei installations reduce batch-to-batch pH variability below 0.2 units. |
| Proprietary Strain Library Expansion | Yakult Honsha's culture collections block competitor functional claim parity in Japanese markets. |
| Quick-Commerce Dark Store Refrigeration | Swiggy Instamart's Mumbai placement secures algorithmic priority for Amul buttermilk SKUs. |
| Clean-Label Reformulation Investment | FSSAI additive tightening forces 18-month R&D cycles for texture-preserving alternatives. |
| PLI-Aligned Fermentation Capacity Buildout | India's subsidy schemes extend cooperative reach into Madhya Pradesh milk shed zones. |
Study Parameters
A spread of perspectives from dairy cooperative procurement heads, fermentation technology vendors, FSSAI compliance officers, and quick-commerce category managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SAMR dairy safety protocol filings, FSSAI strain registration databases, and cold-chain logistics operator disclosures. Bottom-up volume modeling triangulated against top-down category spend estimates from retail audit data.
Segmentation dimensions modeled include product type, distribution channel, consumer age group, and flavor profile across the analysis window. CAGRs derived from trend-line extrapolation of historical volume trajectories adjusted for regulatory intervention timing and infrastructure investment cycles. Forecast inputs incorporated cooperative processing capacity expansion schedules and e-commerce cold-chain maturity indices.
Forecasts assume regulatory continuity in India's FSSAI, China's SAMR, and Japan's Food Sanitation Act regimes; material policy shifts would require re-modeling. Strain approval pathway divergence, electricity infrastructure reliability in tropical climates, and dairy microbiologist availability constraints constitute specific revision triggers. Revision becomes warranted when kefir category penetration in Australian and South Korean metros crosses thresholds that signal mainstream adoption acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Dairy Whiteners Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
Legumes Plant-Based Milk Market
Dairy Alternatives
United States Non-Dairy Milk Market
Dairy Alternatives
Middle East Dairy Alternatives Market
Dairy Alternatives
Dairy-Free Chocolate Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
Cashew Milk Market
Dairy Alternatives
Germany Dairy Alternatives Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
A2 Ice Cream Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
Non-Dairy Creamer Powder Market