
 Breast Milk Substitutes Market | 2026-2036
Breast Milk Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Milk Substitutes Market Analysis
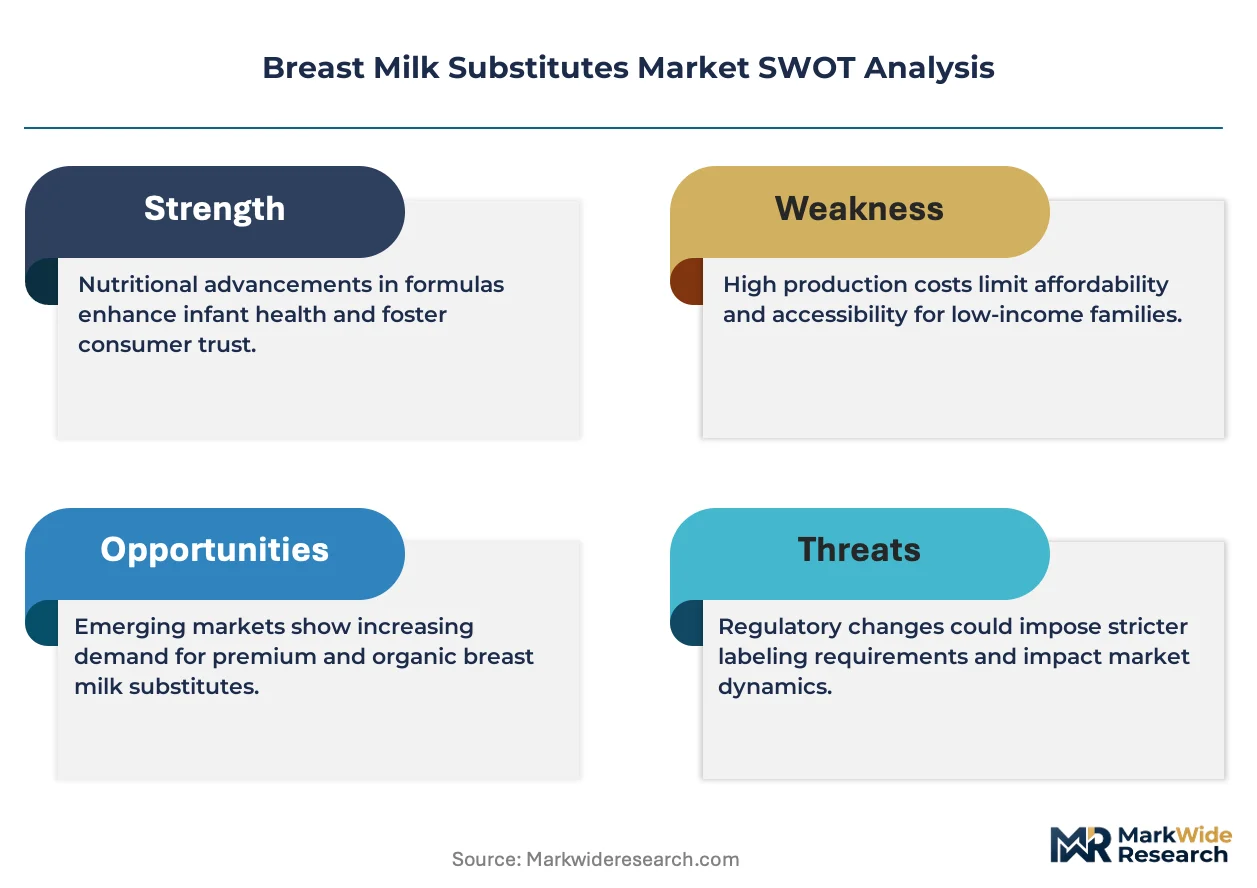
Pediatric nutritionist shortages across developed markets is bifurcating the competitive landscape into science-led and brand-led camps. Nestlé S.A. leverages its clinical research infrastructure to anchor premium positioning in specialty formula segments. Danone S.A. competes through extensive healthcare channel partnerships that sustain prescription-linked distribution in European markets. Abbott Laboratories differentiates via its metabolic and allergy-focused product lines that dominate hospital procurement protocols.
Breast milk substitutes comprise nutritionally engineered liquid or powdered formulations designed to replicate the macronutrient profile of human milk, typically containing demineralized whey, vegetable oils, lactose, and supplemented with docosahexaenoic acid and arachidonic acid to support infant neurodevelopment. These products serve as sole or supplementary nutrition for infants from birth through twelve months when breastfeeding is contraindicated, unavailable, or insufficient. Infant formula occupies the dominant value share within product type segmentation, though specialty formula commands disproportionate margin pools due to clinical validation requirements and restricted distribution. Powdered packaging leads volume throughput across distribution channels, while ready-to-feed liquid formats concentrate in hospital and pediatric clinic end-user segments where sterility and convenience override cost sensitivity.
FDA nutrient specifications under the Infant Formula Act, EFSA novel food approvals for probiotic-enriched formulations, and China's SAMR registration requirements for imported brands collectively elevate compliance costs while restricting market entry for unvalidated suppliers. These frameworks compel manufacturers to maintain dedicated regulatory affairs teams in each major jurisdiction, embedding compliance overhead into pricing architecture. Stakeholders must monitor evolving WHO Code interpretations and national implementation variations that periodically restrict marketing claims, promotional channels, and product positioning.
Market Dynamics
Dual-income household expansion is compressing breastfeeding duration windows and redirecting infant nutrition decisions toward clinically validated substitutes with documented neurodevelopmental benefits.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined approvals for probiotic-enriched formulations accelerate specialty product pipelines across European markets, reducing time-to-clinical-validation.
- Urban Clinic Network Density:China's tier-1 and tier-2 city hospital procurement protocols standardize prescription-linked formula distribution, embedding products into postnatal care workflows.
- Demineralized Whey Processing Advances:Membrane filtration improvements reduce protein denaturation during manufacturing, tightening macronutrient matching to human milk composition profiles.
Market Restraints
- DHA/ARA Raw Material Concentration:Marine and algal oil supply chains cluster in specific coastal processing regions, exposing formulation costs to fishery yield volatility and climate disruption.
- SAMR Registration Burden:China's imported brand approval requirements demand extensive clinical trials and facility inspections, extending market entry timelines and freezing capital in compliance overhead.
- Breastfeeding Promotion Mandates:WHO Code implementation variations restrict point-of-sale visibility and healthcare professional engagement in multiple jurisdictions, constraining traditional marketing channels.
Strategic Opportunities
- Metabolic Disorder Segmentation:Phenylketonuria and galactosemia-focused formulations command restricted distribution premiums through hospital pharmacy networks in North American and European markets.
- Ready-to-Feed Liquid Expansion:Sterile single-serve packaging formats penetrate neonatal intensive care and travel-use occasions where powder preparation fails sterility or convenience requirements.
- IRA Healthcare Subsidy Alignment:US tax-advantaged dependent care structures indirectly expand discretionary spending capacity for premium-positioned specialty nutrition products.
Industry Challenges
- Pediatric Nutritionist Pipeline Collapse:Specialized clinical training programs fail to match demand growth across developed markets, forcing manufacturers to internalize education and counseling functions.
- Cross-Jurisdictional Label Harmonization:Divergent FDA, EFSA, and SAMR nutrient claim specifications require region-specific packaging runs, fragmenting production scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Milk Substitutes Market |
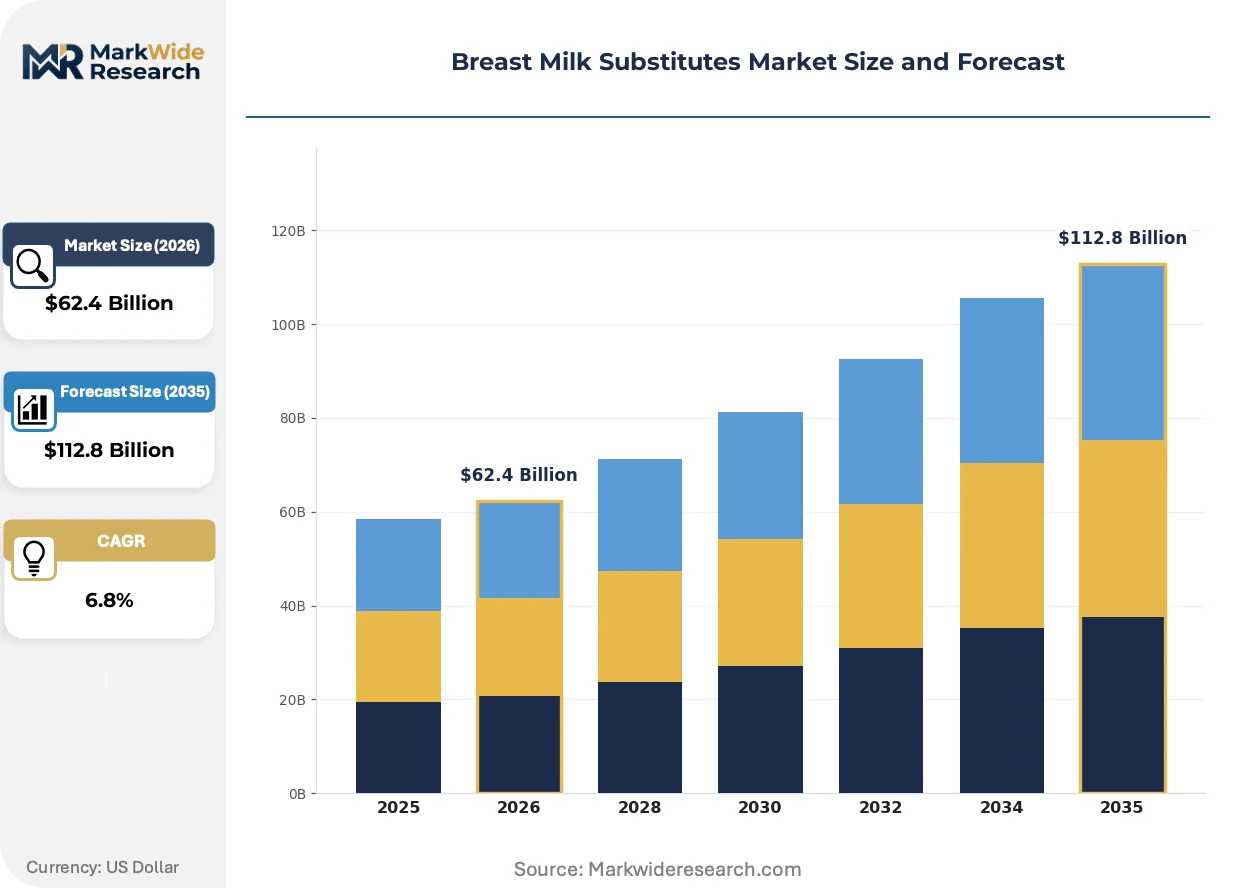
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Formula, Toddler Formula, Specialty Formula, Organic Formula Packaging Type: Powdered, Liquid, Ready-to-Feed, Concentrated Distribution Channel: Supermarkets, Pharmacies, Online Retail, Specialty Stores End User: Parents, Pediatric Clinics, Hospitals, Childcare Centers |
| Companies Covered | Reckitt Benckiser Group plc, The Kraft Heinz Company, Nestlé S.A., Arla Foods Amba, Koninklijke FrieslandCampina N.V., Abbott Laboratories, Pfizer Inc., Fonterra Co-operative Group Limited, Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Milk Substitutes Market Emerging Trajectories
Product development trajectories center on bioactive component preservation, regulatory pre-certification strategies, and channel-specific formulation differentiation that separates clinical from retail positioning.
Precision fermentation-derived human milk oligosaccharides are entering commercial-scale production, enabling oligosaccharide profiles that match human milk complexity rather than relying on plant-based prebiotic proxies. Specialty formula manufacturers in European and North American markets are integrating these ingredients into premium lines ahead of broader cost curves. This biotechnology is miniaturizing the functional gap between engineered substitutes and biological milk, compressing the clinical justification threshold for formula selection.
EFSA's tightening of novel food safety dossier requirements for microbiome-targeting ingredients is extending development timelines and elevating toxicology study burdens for probiotic-enriched entrants. Manufacturers now front-load clinical endpoint trials before formulation finalization to preempt regulatory query cycles. European specialty segments bear the highest compliance cost inflation, prompting some suppliers to deprioritize microbiome claims in favor of established nutrient positioning.
Hospital procurement consolidation is displacing fragmented retail pharmacy purchasing for post-discharge infant nutrition, particularly in Chinese urban clusters and US integrated delivery networks. Buyers now negotiate multi-year sole-source agreements that bundle metabolic, allergy-focused, and standard formulas under volume commitments. This concentration is most visible in Shanghai and Beijing hospital system tenders, where procurement committees weight clinical validation depth above brand recognition in award criteria.
Breast Milk Substitutes Market Segmentation
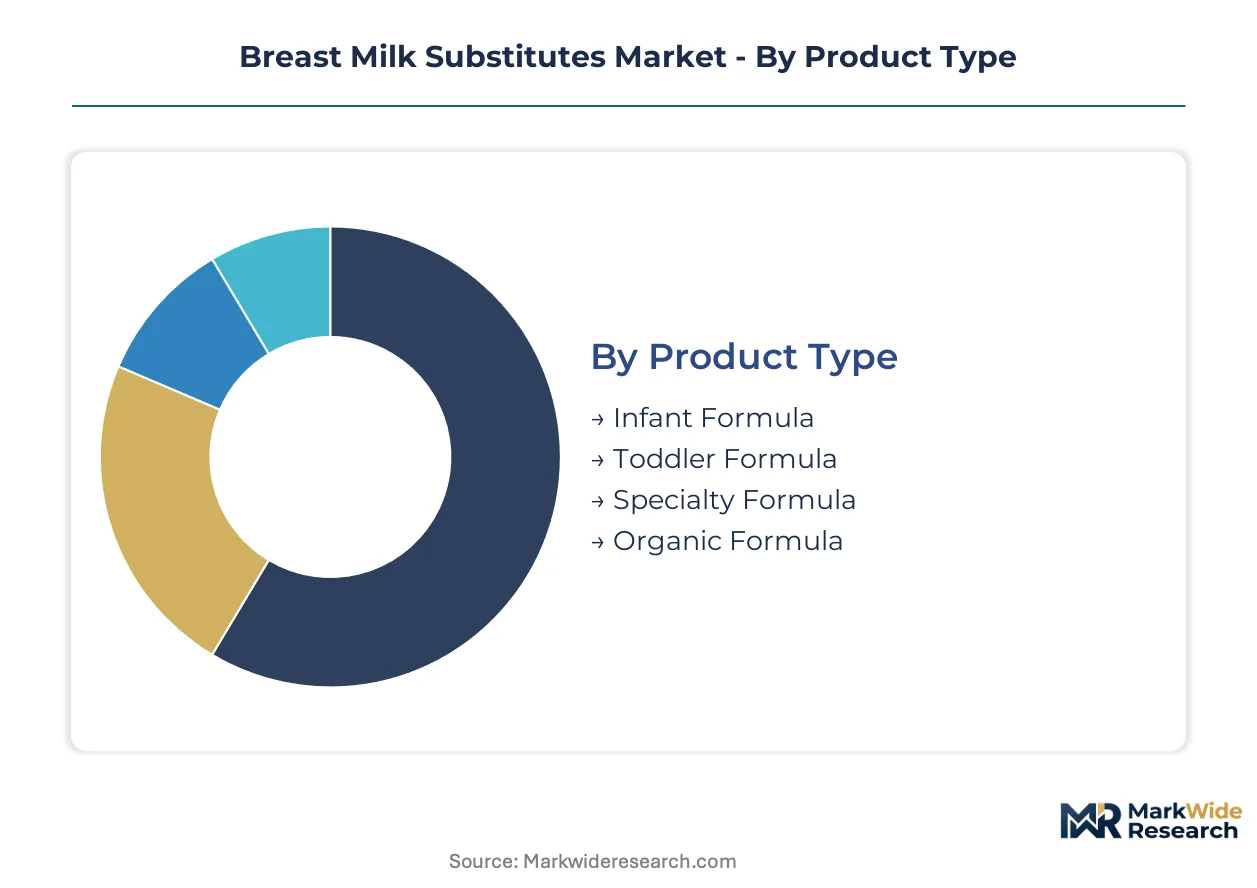
Segmentation in breast milk substitutes reveals how clinical validation requirements, sterility protocols, and channel access permissions fragment purchasing authority across distinct buyer groups. Manufacturers must align formulation complexity, packaging format, and distribution strategy to match the decision-making logic of each segment.
Product Type:
Substitution pressure from donor milk banks and lactation support programs falls unevenly across formula categories, with standard infant nutrition facing the strongest displacement risk while metabolic disorder formulations remain insulated.
- Infant Formula:Standard macronutrient formulations designed for healthy term infants from birth through twelve months, containing demineralized whey, vegetable oils, and lactose as primary energy substrates. Demand concentrates in Chinese urban households where SAMR-registered imported brands dominate tier-1 city retail pharmacy networks, though birth-rate stabilization policies create demand volatility.
- Specialty Formula:Clinically validated formulations targeting phenylketonuria, galactosemia, cow's milk protein allergy, and premature infant nutritional requirements with restricted amino acid profiles or hydrolyzed protein structures. Hospital procurement committees in Shanghai and Beijing weight clinical validation depth above brand recognition in sole-source tender awards, embedding these products into post-discharge care workflows.
- Toddler Formula:Nutritionally modified formulations for children twelve to thirty-six months with adjusted protein-to-energy ratios and micronutrient fortification levels.
- Organic Formula:Products manufactured under certified organic supply chain protocols with restrictions on synthetic pesticide residues and GMO-derived ingredients.
Infant Formula retains volume leadership; Specialty Formula holds the steepest expansion curve.
Packaging Type:
Cost tier stratification separates hospital-grade sterile formats from retail-accessible powder economics, with liquid intermediates capturing travel and convenience occasions.
- Powdered:Dehydrated formulations packaged in metal cans or flexible pouches requiring reconstitution with potable water, offering lowest per-ounce cost and longest ambient shelf stability. Volume concentrates in supermarket and online retail channels across US and European markets where price-sensitive dual-income households prioritize unit economics over preparation convenience.
- Ready-to-Feed:Sterile liquid formulations in single-serve bottles or tetra-pak cartons requiring no dilution or mixing, manufactured under aseptic filling protocols. Neonatal intensive care units in US integrated delivery networks and Chinese tier-1 hospital systems specify these formats exclusively where sterility assurance overrides cost sensitivity.
- Liquid:Concentrated or ready-to-drink formulations in multi-serve containers requiring refrigeration post-opening.
- Concentrated:Liquid formulations requiring dilution with equal parts water prior to feeding, occupying intermediate cost and convenience positioning.
Powdered packaging dominates absolute volume throughput; Ready-to-Feed liquid climbs fastest as hospital procurement consolidation accelerates.
Distribution Channel:
Channel access permissions determine which formulations reach which end-users, with prescription-linked pharmacy networks restricting specialty products while supermarkets and online retail democratize standard nutrition access.
- Pharmacies:Licensed retail and hospital-affiliated dispensaries handling prescription-linked specialty formulas and premium positioned standard nutrition products. European markets sustain this channel through Danone's healthcare partnerships that embed metabolic and allergy-focused lines into pediatrician-directed distribution.
- Supermarkets:Mass-market retail environments with open-shelf access to standard infant and toddler formulations, constrained by WHO Code implementation variations that restrict point-of-sale visibility in multiple jurisdictions.
- Online Retail:E-commerce platforms enabling direct-to-consumer distribution with subscription replenishment models, particularly significant in Chinese markets where cross-border import channels bypass SAMR registration timelines for gray-market access.
- Specialty Stores:Boutique retail environments emphasizing organic certification, premium positioning, and personalized consultation services.
Pharmacies anchor specialty formula distribution; Online Retail gains share fastest as subscription models capture replenishment loyalty.
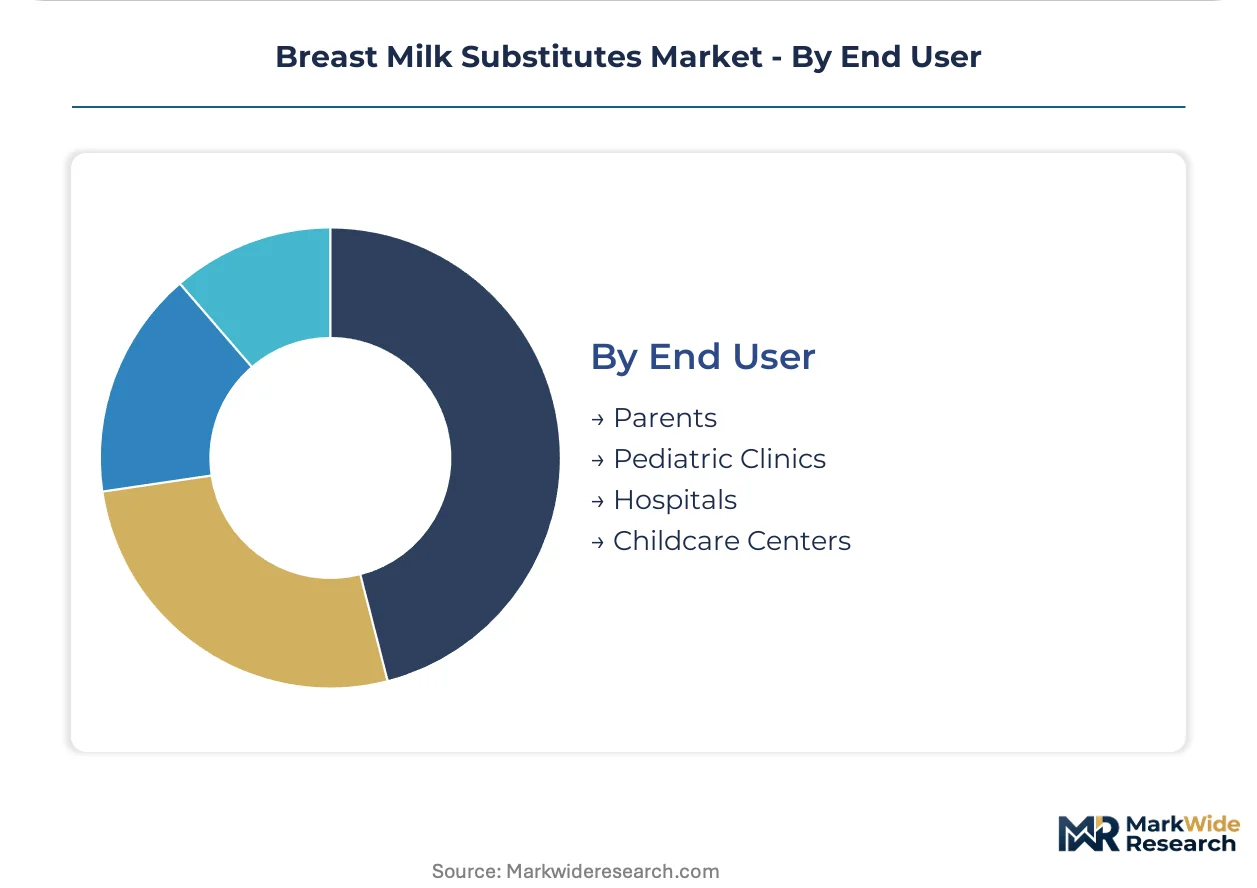
End User:
Decision-making authority fragments between parent-led retail selection and clinician-directed institutional procurement, with hospital committees exercising concentrated purchasing power over metabolic and premature infant formulations.
- Hospitals:Acute care and integrated delivery network procurement committees negotiating multi-year sole-source agreements that bundle metabolic, allergy-focused, and standard formulas under volume commitments. US hospital systems increasingly consolidate post-discharge infant nutrition purchasing alongside inpatient formulary decisions.
- Parents:Individual purchasers making retail or online selections based on pediatrician recommendation, brand familiarity, and price positioning, with dual-income household time constraints compressing breastfeeding duration windows.
- Pediatric Clinics:Outpatient healthcare settings providing formula samples and prescription-linked distribution for specialty formulations.
- Childcare Centers:Institutional early childhood education facilities requiring bulk formula procurement with regulatory compliance documentation.
Parents drive absolute volume consumption; Hospitals command the steepest expansion trajectory as procurement consolidation displaces fragmented retail pharmacy purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: Chinese households prioritize imported specialty formulations through hospital channels, while US and European markets fragment between retail-accessible standard nutrition and prescription-linked metabolic products.
United States
Dual-income household expansion compresses breastfeeding duration, redirecting demand toward clinically validated substitutes. FDA Infant Formula Act enforcement maintains stringent nutrient-composition thresholds that elevate compliance costs for entrants. Hospital procurement consolidation in integrated delivery networks across Texas and California bundles metabolic and allergy-focused formulations under multi-year sole-source agreements.
China
SAMR registration requirements for imported brands extend market entry timelines while urban clinic network density expands formula access in tier-1 cities. Birth-rate stabilization policies generate demand volatility that manufacturers must navigate through flexible production planning. Shanghai and Beijing hospital procurement committees weight clinical validation depth above brand recognition in tender awards for specialty formulations.
Germany
EFSA novel food pathways accelerate probiotic-enriched specialty product pipelines, reducing time-to-clinical-validation for compliant manufacturers. Healthcare channel partnerships sustain prescription-linked distribution of metabolic formulations through pediatrician-directed pharmacy networks. The North Rhine-Westphalia industrial cluster concentrates demineralized whey processing infrastructure that supplies formulation manufacturers across the European market.
France
WHO Code implementation restricts point-of-sale visibility and healthcare professional engagement, constraining traditional marketing channels for standard infant nutrition. Danone S.A.'s healthcare partnerships embed allergy-focused lines into hospital procurement protocols. The Paris metropolitan area anchors clinical research infrastructure that supports specialty formula validation studies for EFSA submission.
Australia
TGA regulatory frameworks align with international standards while maintaining independent assessment pathways for novel ingredients. Fonterra Co-operative Group Limited's upstream dairy processing infrastructure supplies demineralized whey to Asia-Pacific formulation manufacturers. Sydney and Melbourne pediatric clinic networks increasingly coordinate post-discharge infant nutrition recommendations with hospital formulary decisions.
Breast Milk Substitutes Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer commanding hospital procurement relationships and clinical validation infrastructure while mid-tier players compete on retail shelf presence and price positioning. The market structure concentrates around science-led multinationals with dedicated regulatory affairs capabilities in each major jurisdiction. Three archetypes dominate: diversified nutrition conglomerates with metabolic research pipelines, dairy cooperative processors with captive whey supply, and pharmaceutical-origin entrants with hospital channel access. Competitive moves center on backward integration into bioactive ingredient production and geographic expansion through SAMR registration acquisition.
Among diversified nutrition conglomerates, Nestlé S.A. and Danone S.A. exemplify the science-led archetype through clinical research infrastructure and healthcare channel partnerships respectively. Abbott Laboratories anchors the pharmaceutical-origin segment with metabolic and allergy-focused positioning. Reckitt Benckiser Group plc occupies a position within the consumer health tier, while Koninklijke FrieslandCampina N.V. represents dairy cooperative processors with upstream whey processing control. These named entities collectively illustrate how regulatory pre-certification capabilities and hospital procurement access separate market tiers.
| Leading Market Players |
|---|
| Reckitt Benckiser Group plc |
| The Kraft Heinz Company |
| Nestlé S.A. |
| Arla Foods Amba |
| Koninklijke FrieslandCampina N.V. |
| Abbott Laboratories |
| Pfizer Inc. |
| Fonterra Co-operative Group Limited |
| Danone S.A. |
| Others |
Supply Flow & Price Mechanics
Demineralized whey processing capacity utilization above eighty-five percent in Germany's North Rhine-Westphalia cluster tightens protein concentrate availability and elevates base ingredient price floors for formulation manufacturers. This scale concentration grants incumbent processors outsized leverage in contract negotiations with downstream blenders.
Pricing Analysis
Long-term offtake contracts dominate hospital procurement, with Shanghai and Beijing health systems locking three-year sole-source agreements that bundle metabolic, allergy-focused, and standard formulas under volume commitments. Price differentiation separates clinical-grade specialty formulations from retail-accessible standard nutrition based on EFSA novel food certification depth and SAMR registration status. Cost compression in standard infant formula intensifies as Chinese gray-market imports bypass official registration timelines and undercut registered brands. Dual-income households in US supermarket channels exhibit highest price sensitivity, while neonatal intensive care units accept premium positioning where sterility assurance overrides unit economics.
Supply Chain Analysis
Port congestion on Rotterdam-Singapore lanes and container availability constraints on Asia-Europe trade routes elevate inbound logistics costs for algal oil and marine-derived DHA concentrates. Raw material sourcing draws from New Zealand dairy cooperatives for demineralized whey, Chinese coastal processors for algal oil fermentation, and North Sea fisheries for marine lipid extraction. Single-source vulnerability concentrates in algal oil supply chains where fermentation capacity clusters in specific coastal zones. Distribution runs through hospital pharmacy networks for specialty formulations and supermarket retail for standard nutrition, with Chinese online retail capturing gray-market replenishment flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where SAMR registration requirements and EFSA novel food pathways create switching costs that freeze out unvalidated suppliers. Network effects concentrate in hospital procurement committees that standardize sole-source agreements around clinically validated incumbents.
For Market Incumbents: Shield market position by deepening captive supply of precision-fermentation-derived human milk oligosaccharides before cost curves democratize access. Accelerate SAMR registration acquisition for specialty formulation portfolios to preempt emerging entrant challenges in Chinese tier-1 hospital networks. Prioritize backward integration into bioactive ingredient production to defend margin structure against raw material volatility. For New Entrants and Emerging Players: Anchor in metabolic disorder segmentation where phenylketonuria and galactosemia formulations command restricted distribution premiums through hospital pharmacy networks in North American and European markets. Target ready-to-feed liquid formats for neonatal intensive care and travel-use occasions where sterility requirements create barrier-to-entry protection. Pursue EFSA novel food pre-certification strategies that front-load clinical endpoint trials before formulation finalization. For Investors and Strategic Acquirers: Clinical research infrastructure owners with established hospital procurement relationships represent the highest-conviction acquisition archetype for long-term viability across the analysis window. Monitor WHO Code implementation variations as the critical signal for marketing channel restriction severity that reshapes customer acquisition economics. Prioritize targets with dedicated regulatory affairs teams in each major jurisdiction to minimize compliance overhead drag on valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Human milk oligosaccharide production at commercial scale compresses the functional gap with biological milk. |
| SAMR Registration Acquisition | Imported brand approval in China extends market entry timelines and freezes capital in compliance infrastructure. |
| Hospital System Partnership | Multi-year sole-source agreements in Shanghai and Beijing embed products into postnatal care workflows. |
| EFSA Novel Food Pre-Certification | Front-loaded clinical endpoint trials preempt regulatory query cycles and accelerate specialty product pipelines. |
| Backward Integration into Whey Processing | Membrane filtration control tightens macronutrient matching to human milk composition profiles. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric nutritionists, hospital procurement committee members, regulatory affairs directors at formulation manufacturers, and pharmacy category managers across US, Chinese, and European markets. Secondary validation drew from FDA Infant Formula Act filings, EFSA novel food safety dossiers, SAMR registration databases, and hospital tender documentation. Bottom-up volume modeling triangulated against top-down market sizing from trade flow analysis.
Across the analysis window, the forecasting framework segmented volume and value outputs by product type, packaging format, distribution channel, and end-user decision authority. CAGRs derived from regression analysis against birth-rate trajectories, dual-income household expansion rates, and hospital procurement consolidation indices. Modeled inputs incorporated demineralized whey processing capacity utilization, algal oil fermentation yield assumptions, and regulatory approval timeline distributions.
Material uncertainties — birth-rate volatility from policy shifts, fishery yield disruption from climate patterns, and WHO Code interpretation variations — sit outside the modeled envelope. Forecasts reflect documented assumptions about SAMR registration throughput rates and EFSA toxicology study burden trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Europe Non-Dairy Cheese Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Lactose-Free Milk Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Pea Milk Market
Dairy Alternatives
A2 Ice Cream Market