
 A2 Ice Cream Market | 2026-2036
A2 Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
A2 Ice Cream Market Insights
EU Green Deal compliance is consolidating the cost-of-entry calculus for A2 ice cream manufacturers exporting into European retail channels. The a2 Milk Company leverages its proprietary herd certification program to sustain premium positioning across Australasia and North America. Braum's anchors its competitive stance through captive dairy farm operations in Oklahoma, controlling raw A2 milk supply from cow to cone. Alec's Ice Cream differentiates via small-batch production with explicit A2 beta-casein labeling that navigates California's stringent dairy disclosure standards.
A2 ice cream denotes frozen dessert formulations manufactured exclusively from milk containing the A2 variant of beta-casein protein, excluding the A1 variant associated with digestive discomfort in sensitive consumers; production requires segregated A2-certified dairy herds and specialized testing protocols to verify protein composition prior to pasteurization and homogenization. Regular ice cream dominates current value generation due to established consumer familiarity and broader retail distribution, while dairy-free alternatives represent the fastest-growing structural category as lactose-intolerant demographics seek comparable indulgence profiles. Family pack packaging commands disproportionate margin pools in North American club retail, whereas single serve cups lead velocity in European convenience channels.
FDA dairy identity standards and EFSA nutrition and health claims regulation jointly govern permissible A2 protein marketing assertions, with both agencies intensifying scrutiny of digestive health benefit substantiation. BIS certification requirements in India and FSSAI labeling mandates create additional compliance layers for brands targeting emerging South Asian premium segments. Stakeholders must monitor evolving beta-casein testing methodology standards and preemptive regulatory positioning in jurisdictions where A2 claims remain legally undefined.
Market Dynamics
The A2 Ice Cream Market is undergoing structural reconfiguration as herd certification costs and clean-label compliance requirements compress margin pools for non-integrated producers while rewarding captive supply networks.
Growth Catalysts
- EU Green Deal compliance mandates:Carbon footprint disclosure requirements under the EU Green Deal are accelerating retailer preference for A2-certified supply chains with verified environmental credentials.
- Digestive wellness positioning:Consumer willingness to pay premium prices for A2 beta-casein formulations is expanding the addressable market among lactose-sensitive demographics seeking indulgent alternatives.
- PCR-based protein testing protocols:Advanced beta-casein verification methods are reducing batch rejection rates and enabling scaled production without compromising A1 exclusion standards.
Market Restraints
- A2-certified herd scarcity:Limited availability of genetically verified dairy cattle concentrates raw milk supply among a small pool of specialized breeders in Australia and the United States.
- FDA identity standard friction:Strict dairy labeling requirements prevent explicit digestive health claims, forcing manufacturers to rely on implicit A2 protein differentiation rather than functional marketing.
- Oat and coconut milk substitution:Plant-based frozen dessert formulations are capturing price-sensitive consumers who prioritize lactose avoidance over protein specificity.
Strategic Opportunities
- South Asian premium segment penetration:India's FSSAI labeling framework is stabilizing, creating entry pathways for imported A2 ice cream targeting affluent urban consumers in Mumbai and Bangalore.
- Direct-to-subscription channel development:Recurring delivery models for family pack formats are bypassing traditional retail slotting fee structures and capturing lifetime value from repeat purchasers.
- Blockchain-enabled provenance tracking:Integration of distributed ledger technology with herd certification records is enabling real-time supply chain transparency that commands shelf price premiums.
Industry Challenges
- Genetic testing technician shortage:Specialized laboratory capacity for beta-casein verification is concentrated among third-party providers, creating bottlenecks during seasonal demand spikes.
- Cross-contamination prevention capex:Segregated processing lines and dedicated storage infrastructure require substantial capital deployment that strains emerging brand balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | A2 Ice Cream Market |
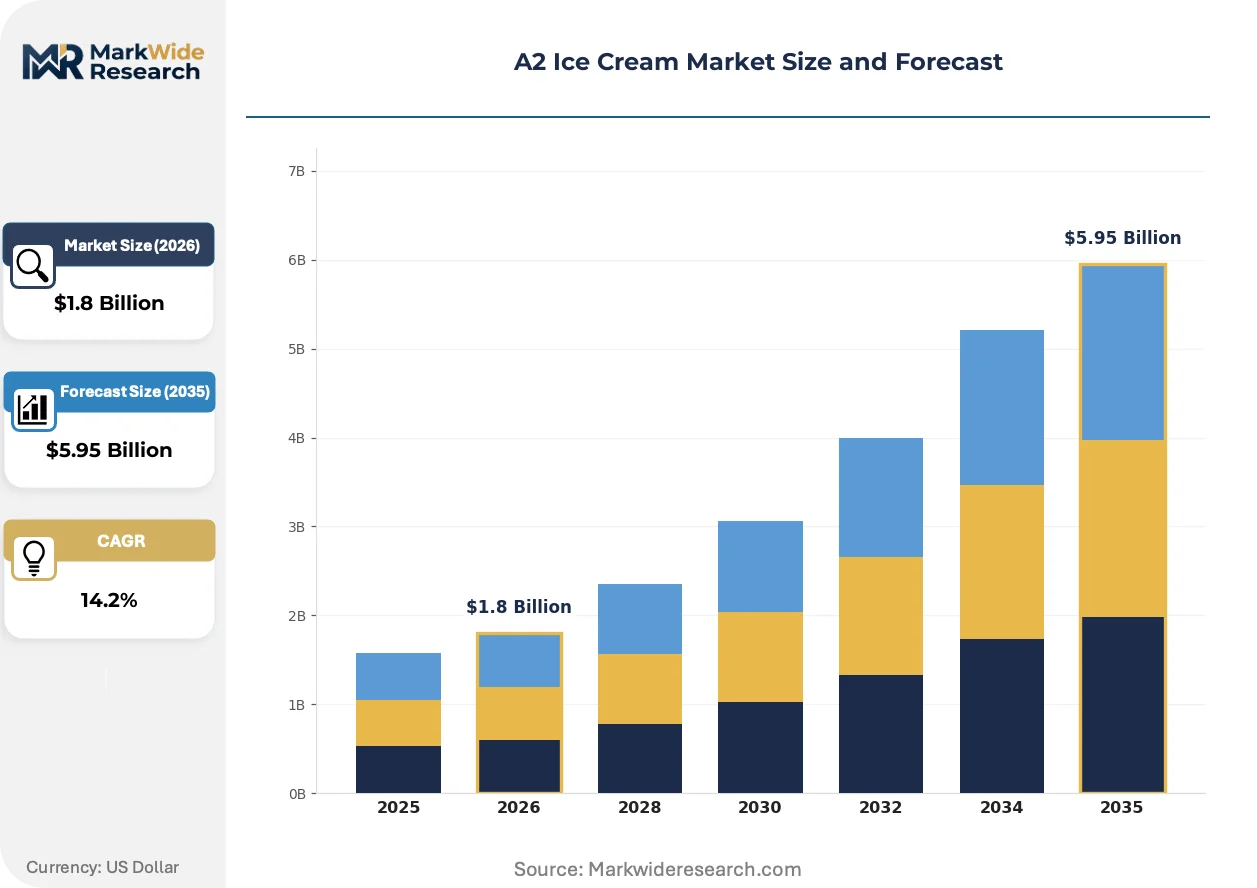
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Ice Cream, Frozen Yogurt, Sorbet, Gelato, Dairy-Free Flavor: Vanilla, Chocolate, Strawberry, Mango, Coffee, Mint Packaging Type: Single Serve Cup, Family Pack, Cone, Multipack, Tub Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Convenience Stores, Foodservice |
| Companies Covered | The a2 Milk Company, Braum's, Alec's Ice Cream, GoDesi Milk, Re:THINK, Miller's Bio Farm, United Farmers Creamery, Appleby Farms Ice Cream, MOO-ville Creamery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
A2 Ice Cream Market Trends and Innovations
Clean-label verification technologies and regulatory disclosure frameworks are compressing competitive differentiation timelines while reshaping how A2 protein claims reach retail shelves.
Mass spectrometry-based beta-casein analysis is consolidating quality control workflows across A2 ice cream manufacturing facilities. Premium dairy processors in California and Victoria are adopting this technology to replace slower ELISA testing methods. The acceleration is compressing batch release cycles from days to hours, enabling just-in-time production scheduling that reduces cold storage requirements.
EFSA nutrition and health claims regulation is tightening substantiation requirements for digestive comfort assertions linked to A2 protein. Manufacturers must now submit peer-reviewed clinical evidence before marketing materials can reference gut health benefits. European brands are responding by pivoting toward neutral "A2 protein" labeling that avoids explicit health claims while maintaining consumer recognition.
Club retail buyer concentration is consolidating procurement leverage over A2 ice cream suppliers. Costco and Sam's Club volume commitments now dictate minimum production runs that exclude smaller craft producers from shelf access. This shift is most visible in Texas and Florida markets where family pack velocity determines category reset decisions.
A2 Ice Cream Market Segmentation
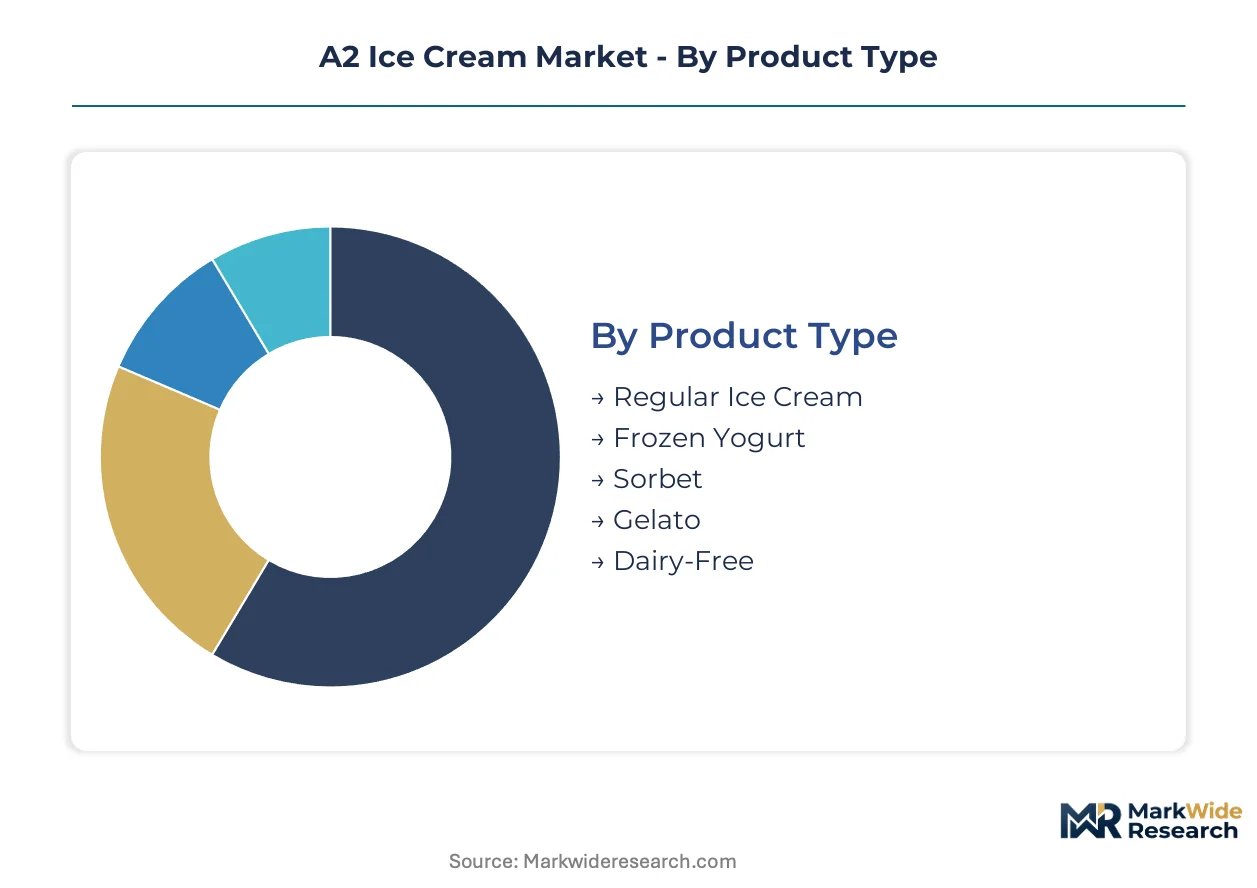
A2 ice cream segmentation reflects divergent consumer priorities around digestive tolerance, occasion-based consumption, and retail access economics. Manufacturers configure product portfolios across these dimensions to capture premium pricing while managing the operational complexity of segregated A2-certified supply chains.
Product Type:
Purchase frequency and price sensitivity separate buyers across frozen dessert formats, with protein specificity commanding variable premiums.
- Regular Ice Cream:Formulations containing A2 beta-casein milkfat at 10-16% concentration dominate current revenue pools. United States club retail channels drive volume through family-oriented repeat purchases where digestive wellness claims justify shelf price elevation.
- Dairy-Free:Oat, coconut, and almond milk bases exclude all dairy proteins entirely, expanding most quickly among lactose-intolerant consumers who reject both A1 and A2 variants. Australian metropolitan markets show disproportionate trial rates for these alternatives.
- Frozen Yogurt:Live culture fermentation combined with A2 milk base targets probiotic-conscious segments in California and New York specialty retail.
- Sorbet:Fruit-puree formulations without dairy appeal to vegan demographics seeking indulgence without protein complexity.
- Gelato:Dense, lower-air-content Italian-style preparation commands artisan positioning in Melbourne and Sydney premium food halls.
Volume sits with Regular Ice Cream; growth tilts toward Dairy-Free.
Flavor:
Flavor selection signals consumer risk tolerance, with familiar profiles anchoring trial conversion and exotic variants driving brand differentiation.
- Vanilla:Clean-label benchmark flavor with minimal ingredient complexity enables A2 protein purity messaging. United States mass retail buyers specify vanilla as mandatory entry SKU for distribution authorization.
- Chocolate:Cocoa butter and A2 milkfat combinations concentrate in European markets where EFSA labeling scrutiny demands transparent supply chain documentation.
- Strawberry:Fruit-inclusion formulations require segregated processing lines to prevent cross-contamination, elevating manufacturing cost structures.
- Mango:Tropical flavor profiles gain traction in Indian urban premium segments under FSSAI import framework stabilization.
- Coffee:Caffeine-fortified positioning targets adult indulgence occasions in Australian convenience channels.
- Mint:Seasonal velocity spikes concentrate in North American summer periods with limited year-round distribution commitment.
Vanilla and Chocolate together capture dominant shelf space; Mango exhibits the steepest expansion trajectory in emerging markets.
Packaging Type:
Packaging economics determine channel access, with format selection directly constraining viable retail partnerships and margin structures.
- Family Pack:Multi-liter containers at 1.5-4 liter capacity concentrate in Costco and Sam's Club procurement specifications. Texas and Florida markets generate disproportionate velocity through this format.
- Single Serve Cup:Individual portion control aligns with European convenience store channel requirements where on-premise consumption dominates.
- Cone:Pre-filled wafer formats require specialized filling equipment that excludes smaller craft producers from viable production economics.
- Multipack:Four-to-six unit configurations balance household consumption with per-unit price accessibility in Australian supermarket reset cycles.
- Tub:Reusable rigid containers support premium positioning in specialty retail channels with extended consumption windows.
Family Pack commands absolute volume; Single Serve Cup climbs fastest in European convenience expansion.
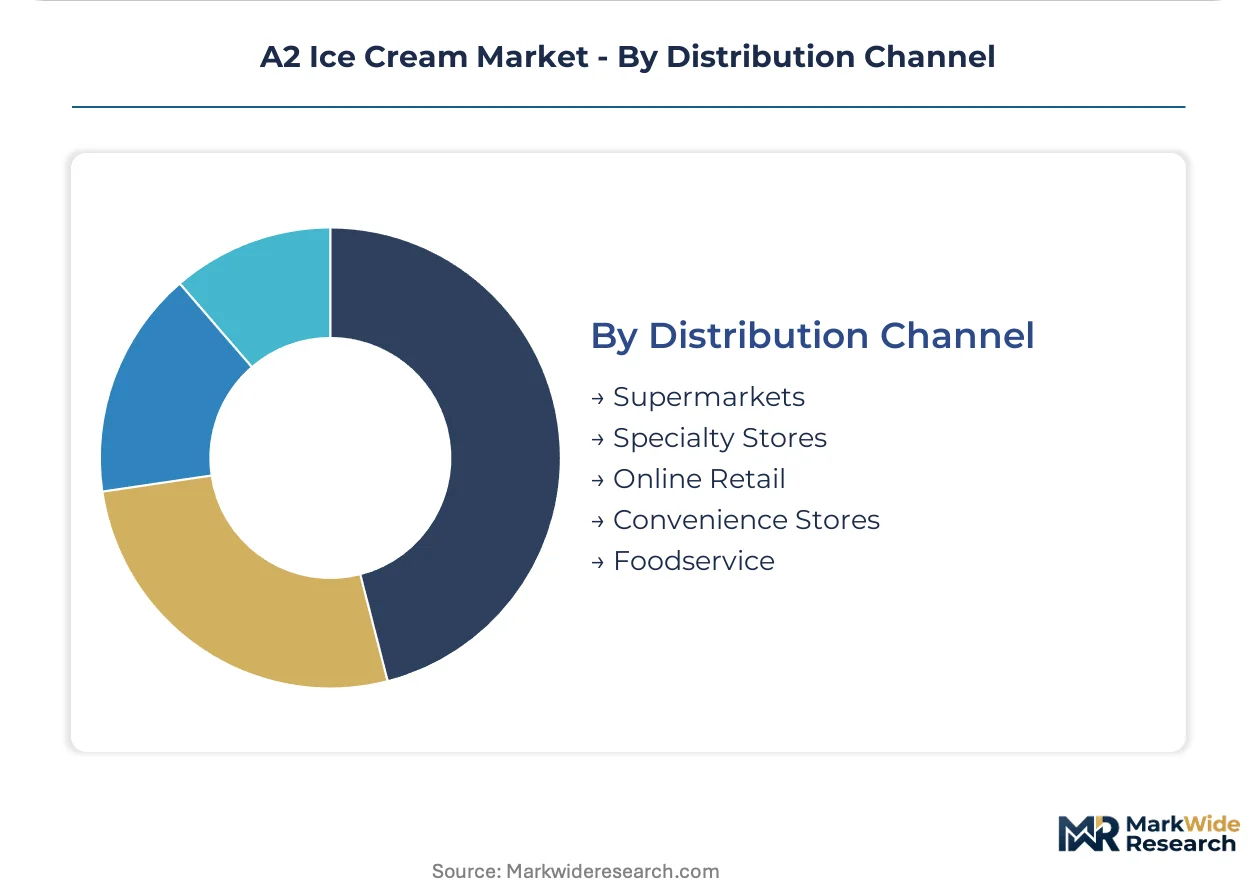
Distribution Channel:
Channel selection determines regulatory exposure and working capital intensity, with each pathway imposing distinct compliance and payment term structures.
- Supermarkets:Kroger, Woolworths, and Tesco tiered shelf placement programs require substantial slotting fee commitments that filter producer viability. United States and Australian mass retail resets occur on 12-18 month cycles.
- Online Retail:Direct-to-consumer subscription models bypass traditional retail margin stacking while enabling cold-chain logistics investment recovery through recurring revenue structures.
- Specialty Stores:Independent natural food retailers in California and Victoria provide brand building platforms with educated consumer bases receptive to A2 protein differentiation.
- Convenience Stores:7-Eleven and Circle K impulse purchase environments favor single-serve formats with immediate consumption positioning.
- Foodservice:Restaurant and café bulk procurement contracts concentrate in metropolitan clusters with established A2 milk supply relationships.
Supermarkets retain volume concentration; Online Retail gains share fastest through subscription mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium grocery channels in the United States, Australia, and select Western European markets concentrate current A2 ice cream demand. Health-conscious consumer segments in these geographies justify shelf price premiums through digestive wellness positioning. Regulatory frameworks across multiple jurisdictions are reshaping ingredient sourcing protocols and marketing claim substantiation.
United States
Club retail buyer concentration at Costco and Sam's Club dictates minimum production runs for family pack formats. FDA dairy identity standards prevent explicit digestive health claims, forcing implicit A2 protein differentiation. Texas and Florida markets generate disproportionate velocity through multi-liter family pack configurations in suburban retail clusters.
Australia
Metropolitan consumers in Melbourne and Sydney demonstrate disproportionate trial rates for dairy-free alternatives alongside A2 formulations. TGA oversight of nutrition claims requires clinical substantiation for gut health marketing. Victoria's premium dairy processors are adopting mass spectrometry-based beta-casein analysis to compress batch release cycles.
Germany
EFSA nutrition and health claims regulation tightens substantiation requirements for A2 protein digestive comfort assertions. Clean-label verification technologies are consolidating quality control workflows across manufacturing facilities. Bavarian specialty food halls command artisan positioning for dense Italian-style gelato preparations.
India
Affluent urban consumers in Mumbai and Bangalore drive premium segment penetration under stabilizing FSSAI labeling frameworks. BIS certification requirements create additional compliance layers for imported brands. The country's national food safety regulator is clarifying import pathways for A2-certified dairy desserts.
United Kingdom
EFSA-aligned domestic regulations govern permissible A2 protein marketing assertions through the Food Standards Agency. London and Southeast England specialty retailers provide brand building platforms with educated consumer bases. Independent natural food channels in these clusters demonstrate particular receptivity to A2 protein differentiation.
A2 Ice Cream Market Competitive Landscape
United States producers anchor one tier; Australasian specialists hold premium positioning through proprietary herd certification. The vendor base fragments across integrated dairy operations and craft-scale artisan producers. Three strategic archetypes dominate: captive supply network operators, small-batch craft differentiators, and emerging plant-based hybrid innovators. Capacity expansion and direct-to-subscription channel development constitute the dominant competitive moves.
Within the captive supply tier, Braum's exemplifies vertical control through Oklahoma-based dairy farm operations. The a2 Milk Company occupies a position as the proprietary herd certification standard-setter across Australasia and North America. Alec's Ice Cream represents small-batch differentiation through explicit A2 beta-casein labeling that navigates California's stringent disclosure standards.
| Leading Market Players |
|---|
| The a2 Milk Company |
| Braum's |
| Alec's Ice Cream |
| GoDesi Milk |
| Re:THINK |
| Miller's Bio Farm |
| United Farmers Creamery |
| Appleby Farms Ice Cream |
| MOO-ville Creamery |
| Others |
Pricing and Supply Chain Analysis
A2-certified raw milk premiums flow from Oklahoma and Victoria dairy operations through three-tier pricing structures that separate artisan small-batch positioning from club retail volume tiers and emerging private-label economy offerings.
Pricing Analysis
Short lead-time premiums for just-in-time A2 beta-casein verification command shelf price elevation at specialty retailers, while spot inventory discounts concentrate in club retail family pack commitments. Pricing stratifies across premium artisan, standard mass retail, and economy private-label tiers based on herd certification depth and batch testing documentation. Cost compression in the economy tier is intensifying because oat milk substitutes capture price-sensitive lactose avoiders. Club retail buyers exhibit lowest price sensitivity due to volume guarantees, whereas convenience channel operators demand maximum margin flexibility.
Supply Chain Analysis
Dual-sourcing mandates from Kroger and Woolworths procurement teams require A2 ice cream manufacturers to qualify genetically verified dairy herds across both Australia and the United States. Production draws from A2-certified cattle populations, specialized beta-casein testing laboratory capacity, and segregated cold-chain logistics infrastructure. Single-source vulnerability concentrates in third-party genetic testing providers where technician scarcity creates seasonal bottlenecks. Distribution runs through club retail consolidation points in Texas and Florida, specialty natural food channels in California and Victoria, and direct-to-consumer subscription cold-chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as FDA identity standard friction and herd certification capital requirements force non-integrated craft producers toward acquisition or exit.
For Market Incumbents: Extend captive supply network control through backward integration into A2-certified dairy herd operations in Oklahoma or Victoria, insulating against raw material scarcity and genetic testing bottlenecks. Deepen mass spectrometry quality control investment to compress batch release cycles below competitor ELISA timelines. Oat milk substitution technology poses the dominant substitution threat requiring preemptive A2 protein purity messaging. For New Entrants and Emerging Players: Direct-to-subscription channel development offers the most penetrable entry vector, bypassing Kroger and Costco slotting fee barriers while capturing lifetime value through recurring family pack delivery. Target Indian urban premium segments in Mumbai and Bangalore where FSSAI import pathway clarification creates first-mover positioning before multinational brand saturation. Explicit A2 beta-casein labeling that navigates California disclosure standards provides differentiated go-to-market positioning against implicit protein claims. For Investors and Strategic Acquirers: Mass spectrometry adoption rates among Victoria and California processors are the leading indicator that quality control consolidation is accelerating competitive differentiation timelines. The five-to-ten-year viability window favors vertically integrated mid-cap specialists with captive herd operations and direct-to-subscription revenue foundations over non-integrated craft brands facing capital constraints. Watch for blockchain-enabled provenance tracking integration as the signal that supply chain transparency premiums are becoming table stakes rather than differentiators.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Herd Certification Expansion | Backward integration into Oklahoma or Victoria dairy operations secures raw A2 milk supply against genetic cattle scarcity. |
| Mass Spectrometry Quality Control Deployment | California and Victoria processors adopting this technology compress batch release cycles from days to hours. |
| Direct-to-Subscription Channel Launch | Recurring delivery models bypass Costco and Sam's Club slotting fees while capturing repeat purchaser lifetime value. |
| Blockchain Provenance Tracking Integration | Distributed ledger verification of herd certification records commands shelf price premiums in European retail channels. |
| South Asian Import Pathway Establishment | FSSAI labeling framework stabilization in India creates entry corridors for Mumbai and Bangalore premium segment penetration. |
Research Methodology
SEC filings from publicly traded dairy processors, EFSA nutrition claim substantiation databases, and FDA dairy identity standard guidance documents formed the secondary backbone, cross-referenced with primary interviews involving A2 herd certification program managers, club retail category buyers at Costco and Sam's Club, specialty channel procurement leads at California natural food retailers, and cold-chain logistics operators. Bottom-up volume modeling from individual SKU velocity data and top-down market sizing from customs import records were triangulated to establish segment boundaries.
Bottom-up demand estimation across product type, flavor profile, packaging format, and distribution channel dimensions were synthesized with top-down macroeconomic anchoring over the projection horizon. CAGRs were derived from regression analysis of historical premium dairy dessert velocity patterns and projected A2 protein claim penetration curves. Modeled inputs included herd certification program expansion timelines, mass spectrometry equipment adoption rates among dairy processors, and FSSAI import framework clarification schedules.
Inputs from EFSA claim substantiation records and FDA labeling guidance were available through the study window; gaps in proprietary herd certification program enrollment data introduce uncertainty bands around supply-side capacity assumptions. Deviation in EU Green Deal carbon disclosure implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Cultured Dairy Blends Market
Dairy Alternatives
Legumes Plant-Based Milk Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Dairy-Free Chocolate Market