
 North America Dehydrated Food Market | 2026-2036
North America Dehydrated Food Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dehydrated Food Market Analytics
Premium-grade freeze-dried specifications is collapsing the gap between dehydrated products and fresh-equivalent sensory profiles. Van Drunen Farms anchors its position through backward integration into contract farming across the Midwest. Thrive Foods, LLC specializes in direct-to-consumer channels with shelf-stable meal kits. General Mills leverages its cereal manufacturing infrastructure to achieve scale in fruit flake production.
Dehydrated food encompasses products from which moisture content has been reduced to levels below ten percent through thermal, vacuum, or freeze-drying processes, typically yielding water activity values under 0.6 to inhibit microbial proliferation. These products serve commercial buyers seeking extended shelf stability, reduced shipping weights, and minimized cold-chain dependency across institutional foodservice and emergency preparedness applications. Powder and flake forms command the widest industrial uptake due to their reconstitution efficiency in beverage and sauce formulations. Pouch packaging is displacing rigid formats among outdoor recreation and military segments where weight reduction determines procurement decisions.
The FDA's Food Safety Modernization Act preventive controls rule governs low-moisture food processing facilities throughout the United States, while Health Canada's Safe Food for Canadians Regulations establish parallel standards for cross-border suppliers. The USDA's National Organic Program certification creates premium access tiers for dehydrated fruit and vegetable suppliers meeting specified agricultural input restrictions. Stakeholders must monitor evolving sodium reduction mandates from both FDA draft guidance and Health Canada front-of-package labeling proposals that could reformulate seasoning-intensive dehydrated meal portfolios.
Market Dynamics
Freeze-drying technology is compressing quality differentials between dehydrated and fresh-equivalent products, forcing processors to upgrade thermal dehydration lines or exit premium segments entirely. The FDA's Food Safety Modernization Act traceability mandates are simultaneously raising capital barriers for smaller operators.
Growth Catalysts
- Backcountry recreation demand:Backpackers and outdoor enthusiasts are expanding purchases of lightweight meal solutions as participation rates in long-distance hiking and camping climb across the United States and Canada.
- FSMA traceability compliance:The FDA's Food Safety Modernization Act preventive controls rule is accelerating facility consolidation among low-moisture food processors seeking scale economies for compliance investments.
- California agricultural proximity:Demand concentrates in California's Central Valley where integrated dehydration operations exploit direct access to fruit and vegetable supply chains.
Market Restraints
- Energy cost volatility:Thermal dehydration requires sustained heat input; natural gas price swings directly compress processor margins in natural-gas-dependent Midwest operations.
- Supply concentration risk:Contract farming relationships for specialty crops cluster among a limited set of Midwest growers, creating vulnerability to regional weather disruptions.
- Freeze-drying substitution threat:Premium freeze-dried formats are capturing price-insensitive segments that previously accepted conventional dehydrated alternatives.
Strategic Opportunities
- Canadian market underpenetration:Health Canada's Safe Food for Canadians Regulations create parallel certification pathways that favor early entrants establishing compliant cross-border supply chains.
- Emergency preparedness applications:Institutional buyers in federal and state emergency management are expanding shelf-stable stockpile procurement beyond traditional military channels.
- Direct-to-consumer channel innovation:Subscription meal-kit platforms are displacing conventional retail distribution for household-scale dehydrated vegetable and protein offerings.
Industry Challenges
- Process engineering talent scarcity:Facility operators face acute shortages of technicians trained in low-moisture food safety validation and automated drying system maintenance.
- USDA organic certification timelines:The National Organic Program's multi-year transition requirements for agricultural inputs delay premium positioning for suppliers converting conventional supply chains.
- Legacy equipment integration friction:Retrofitting existing thermal lines with real-time moisture monitoring and automated HACCP documentation systems demands capital outlays that strain mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dehydrated Food Market |
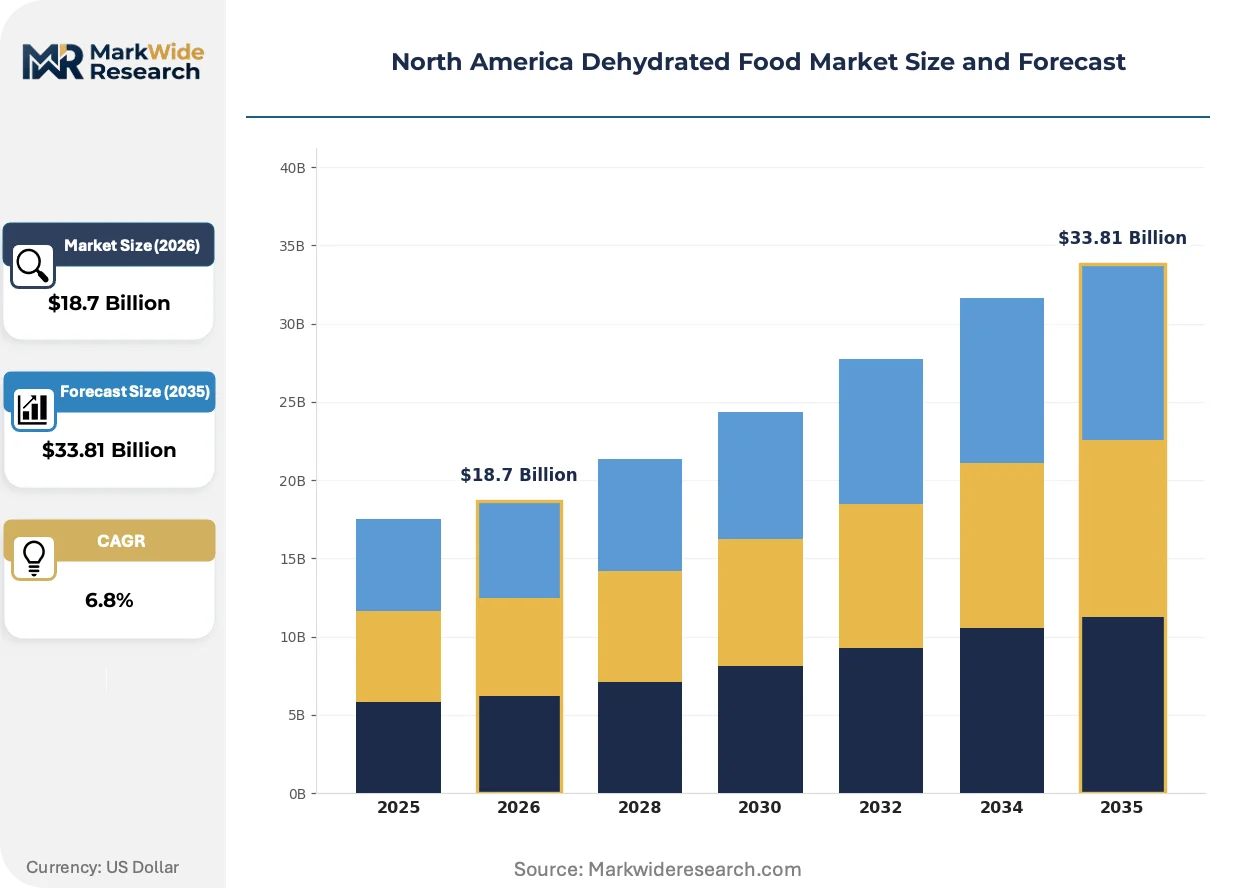
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Meat, Snacks End User: Retail, Food Service, Household, Industrial Form: Powder, Flakes, Granules, Slices Packaging Type: Bags, Cans, Pouches, Jars |
| Companies Covered | Thrive Foods, LLC, Campbell Soup Company, Van Drunen Farms, General Mills, Conagra Brands, Harmony House Foods Inc., The Kraft Heinz Company, B&G Foods, Mother Earth Products, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dehydrated Food Market Evolving Landscape
Advanced drying technologies and packaging formats are compressing the sensory gap between reconstituted and fresh products. Regulatory pressure on sodium content is forcing formulation reformulation across seasoning-intensive categories.
Vacuum-microwave hybrid drying is displacing conventional hot-air systems in premium fruit and vegetable processing. California processors are adopting these systems to preserve volatile aromatic compounds and color stability. The technology is displacing established thermal methods in applications where rehydration quality determines contract renewals with foodservice distributors.
The FDA's draft sodium reduction guidance and Health Canada's front-of-package labeling proposals are tightening formulation constraints on dehydrated meal portfolios. Processors must reformulate seasoning blends or risk exclusion from institutional procurement channels. Military and outdoor recreation segments are most affected, with suppliers accelerating clean-label development programs to maintain shelf placement.
Outdoor enthusiasts are rotating purchases toward complete meal systems rather than ingredient components. Direct-to-consumer brands are capturing this shift through subscription platforms that displace traditional sporting-goods retail. The United States Pacific Northwest and Rocky Mountain corridor show the strongest concentration of this behavioral pivot, driving pouch-format innovation and single-serve portion engineering.
North America Dehydrated Food Market Segmentation
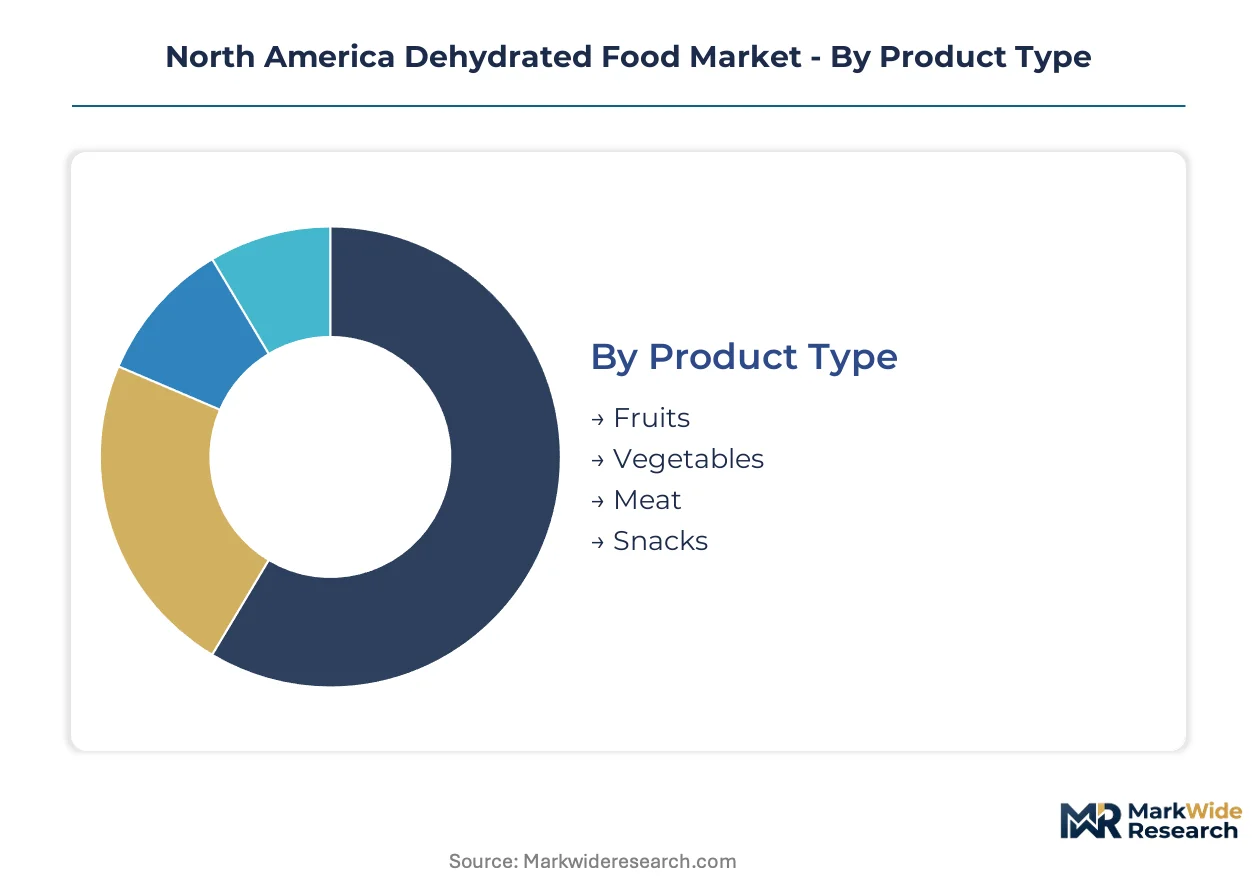
Dehydrated food market segmentation reveals where freeze-drying substitution pressure concentrates most acutely. Understanding these fault lines helps processors allocate capital between defending volume positions and capturing premium migration.
Product Type:
Freeze-dried alternatives pose the sharpest substitution threat to segments where sensory fidelity commands price premiums.
- Fruits:Apples, berries, and tropical varieties dominate thermal dehydration output, with California's Central Valley processors supplying bulk ingredients to cereal manufacturers and snack compounders. Strawberry and mango segments face the strongest freeze-dried encroachment in premium trail-mix and breakfast applications across the Pacific Northwest.
- Vegetables:Onions, tomatoes, and peppers constitute the largest volume category, anchoring soup base and sauce formulations for institutional foodservice buyers. Midwest contract farming clusters supply raw material to integrated dehydration facilities in Illinois and Wisconsin.
- Meat:Beef and poultry jerky segments retain defensible positions against freeze-drying through established texture expectations and lower price points. Military and emergency preparedness procurement channels sustain demand for shelf-stable protein formats.
- Snacks:Fruit leather and vegetable chip formats compete directly with fresh-cut alternatives, constraining pricing power in conventional retail. Direct-to-consumer subscription platforms are displacing traditional sporting-goods distribution for backcountry-focused offerings.
Vegetables anchor the volume base while fruits gain share at the steepest rate.
End User:
Procurement patterns diverge sharply between price-sensitive institutional buyers and convenience-seeking household purchasers.
- Retail:Supermarket and mass-merchant channels concentrate demand for conventional dehydrated ingredients in private-label soup and side-dish portfolios. Front-of-package sodium labeling proposals from FDA and Health Canada are forcing reformulation investments across seasoning-intensive product lines.
- Food Service:Restaurant chains and contract caterers prioritize reconstitution speed and lot-to-lot consistency in bulk vegetable and protein procurement. Powder and flake formats command preference for back-of-house efficiency in high-throughput kitchen environments.
- Household:Camping and emergency preparedness consumers drive pouch-format innovation, with subscription meal-kit platforms capturing share from conventional sporting-goods retail. The Rocky Mountain corridor shows the strongest concentration of complete-meal-system purchasing behavior.
- Industrial:Beverage manufacturers and sauce compounders constitute the most technically demanding buyer segment, specifying moisture content tolerances and microbial specifications that exclude smaller dehydration operators.
Food service anchors the volume base while household gains share through channel innovation.
Form:
Reconstitution efficiency determines form selection across application categories, with particle engineering investments separating tier-one suppliers from commodity processors.
- Powder:Fine-milled vegetable and protein powders serve beverage fortification and sauce thickening applications where complete solubility is mandatory. California processors dominate supply to West Coast beverage manufacturers.
- Flakes:Potato and onion flakes retain structural integrity in hot-water reconstitution, anchoring institutional mashed potato and soup base formulations. General Mills leverages cereal manufacturing infrastructure to achieve scale in fruit flake production.
- Granules:Intermediate particle sizes suit seasoning blend applications where dispersion rate and visual particulate matter both influence procurement decisions. Midwest dehydration facilities supply bulk granules to spice compounders.
- Slices:Whole-fruit and vegetable slices command premium positioning in snack and baking applications where visual identity supports brand differentiation. Vacuum-microwave hybrid drying systems preserve color stability and volatile aromatic compounds.
Powder anchors the volume base while slices expand most quickly through premium snack positioning.
Packaging Type:
Weight reduction imperatives in outdoor recreation and military procurement are compressing demand for rigid formats.
- Bags:Multi-layer barrier films with oxygen scavengers protect conventional dehydrated ingredients in retail and foodservice bulk distribution. Midwest processors favor bag formats for cost-efficient shipment to institutional buyers.
- Cans:Metal containers retain relevance for long-duration emergency stockpiles and military specifications requiring multi-decade shelf stability. Federal and state emergency management agencies specify can formats for strategic reserves.
- Pouches:Flexible stand-up pouches with resealable closures are displacing rigid formats among backpackers and outdoor enthusiasts where gram-level weight reduction determines purchase decisions. Pacific Northwest brands lead portion-engineering innovation for single-serve meal systems.
- Jars:Glass containers serve niche premium positioning in specialty retail where visual product inspection supports purchase intent. Limited growth trajectory reflects shipping weight penalties and breakage risk.
Bags anchor the volume base while pouches climb the fastest through outdoor recreation channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American dehydrated food sector operates as a net exporter of processed agricultural commodities, with cross-border supply chains linking Canadian raw material flows to U.S. dehydration infrastructure and Mexican ingredient processing.
United States
California's Central Valley anchors integrated dehydration operations through direct agricultural proximity, while Illinois and Wisconsin house Midwest contract farming clusters supplying bulk vegetable inputs. The FDA's Food Safety Modernization Act preventive controls rule governs facility compliance across all low-moisture food processors. The Pacific Northwest corridor shows the strongest concentration of outdoor recreation demand, driving pouch-format innovation for backpacking meal systems.
Canada
Health Canada's Safe Food for Canadians Regulations establish parallel certification pathways that favor early entrants building compliant cross-border supply chains. Prairie Provinces supply grain and pulse inputs to integrated dehydration facilities serving both domestic and export markets. Ontario processors concentrate on institutional foodservice contracts, leveraging proximity to major urban centers in the Toronto-Waterloo corridor.
Mexico
The Bajío Region and Northern Border States supply tropical and specialty crop inputs to U.S. dehydration facilities under integrated North American supply chain arrangements. Mexican processors face alignment pressure with FDA traceability mandates for exports targeting the U.S. institutional market. Jalisco and Nuevo León are developing dehydration capacity to capture value-added processing currently performed north of the border.
North America Dehydrated Food Market Competitive Landscape
Concentration sits with diversified food conglomerates possessing cereal manufacturing infrastructure and established retail distribution networks. The vendor base spans three tiers: multinational packaged food corporations with dehydration as a vertical segment, regional processors integrated into contract farming relationships, and direct-to-consumer specialists exploiting subscription channel innovation. Competitive moves center on backward integration into agricultural supply chains and technology licensing for vacuum-microwave hybrid drying systems.
Within the diversified conglomerate tier, General Mills and Conagra Brands occupy positions leveraging scale infrastructure for fruit flake and ingredient production. Van Drunen Farms exemplifies the contract farming-integrated processor archetype through its Midwest agricultural relationships. Thrive Foods, LLC represents the direct-to-consumer specialist model, anchoring subscription meal-kit distribution channels that bypass conventional retail.
| Leading Market Players |
|---|
| Thrive Foods, LLC |
| Campbell Soup Company |
| Van Drunen Farms |
| General Mills |
| Conagra Brands |
| Harmony House Foods Inc. |
| The Kraft Heinz Company |
| B&G Foods |
| Mother Earth Products |
| Others |
Value Network & Pricing Analysis
USDA National Organic Program certification gates both supply qualification and price differentiation simultaneously, segmenting dehydrated food markets into premium tiers where organic transition timelines delay competitive entry while conventional processors absorb margin compression from energy-intensive thermal operations.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across powder and flake formats, with pricing stratifying across premium, standard, and economy tiers based on moisture specification tolerance and USDA organic certification status. Price differentiation stems from reconstitution speed performance and lot-to-lot consistency guarantees demanded by high-throughput foodservice kitchens. Cost compression in conventional thermal dehydration is intensifying because natural gas price volatility directly impacts Midwest operations without renewable energy hedging. Emergency preparedness procurement channels show lowest price sensitivity, while retail private-label buyers drive hardest bargain on volume commitments.
Supply Chain Analysis
Just-in-time inventory preferences dominate foodservice and industrial beverage channels, whereas strategic stockpile mandates govern military and federal emergency management procurement with multi-year forward commitments. Geographic supply concentration centers on the United States, Canada, and Mexico, with California's Central Valley, Midwest contract farming clusters, and Mexican Bajío Region feeding integrated dehydration infrastructure. Raw material dependencies rest on specialty crop contracts for berries and tropical fruits, grain inputs for protein fortification powders, and natural gas for thermal processing energy. Single-source vulnerability concentrates in Midwest onion and tomato supply clusters exposed to regional drought patterns. Distribution runs through institutional foodservice distributors, direct-to-consumer subscription platforms, and sporting-goods retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American dehydrated food markets are entering cyclical recovery as backcountry recreation participation rebounds from pandemic-era disruptions, with hiking and camping equipment sales serving as the leading indicator for meal-system demand inflection.
For Market Incumbents: Compound defensive positioning through backward integration into California Central Valley and Midwest contract farming relationships to secure captive supply of strawberry and mango inputs facing freeze-dried substitution pressure. Accelerate vacuum-microwave hybrid drying technology licensing to preserve sensory fidelity in premium fruit segments where rehydration quality determines contract renewals. Prioritize FSMA traceability compliance infrastructure investments that raise capital barriers for smaller competitors. For New Entrants and Emerging Players: Differentiate on direct-to-consumer subscription channel control, exploiting white-space in Canadian market underpenetration where Health Canada certification pathways favor early entrants building compliant cross-border supply chains. Target household emergency preparedness segments in Ontario and Prairie Provinces with shelf-stable meal kits displacing conventional sporting-goods retail. Anchor go-to-market through platform-native brands bypassing established distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vacuum-microwave hybrid drying system deployments, favoring acquisition targets possessing installed premium technology capacity or exclusive agricultural supply contracts. Long-term viability over the coming decade rests on defensible input sourcing and regulatory compliance infrastructure rather than brand equity alone. Watch freeze-drying substitution rates in premium fruit segments as the signal indicating whether thermal dehydration incumbents can sustain margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Van Drunen Farms exemplifies captive supply control securing strawberry and mango inputs against freeze-dried competition. |
| Vacuum-Microwave Hybrid Drying Adoption | California processors preserve volatile aromatic compounds to meet foodservice distributor rehydration quality specifications. |
| Direct-to-Consumer Channel Launch | Thrive Foods, LLC demonstrates subscription platform displacement of conventional sporting-goods retail distribution. |
| Cross-Border Supply Chain Certification | Early Health Canada compliance investment opens Prairie Provinces and Ontario institutional procurement channels. |
| Emergency Preparedness Stockpile Contracting | Federal and state agencies expand shelf-stable procurement beyond traditional military specifications into civilian resilience programs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA enforcement discretion letters, USDA National Organic Program certification databases, and Health Canada guidance documents. Interviews with dehydration facility operators, contract farming coordinators, foodservice procurement directors, and outdoor recreation retail buyers inform operational constraint assessment. Secondary validation draws from customs trade data, cereal manufacturer SEC filings, and backcountry recreation participation surveys. Bottom-up capacity modeling triangulates against top-down demand segmentation across product type, end user, form, and packaging dimensions.
Segmentation dimensions modeled include product type hierarchy, procurement channel structure, reconstitution form requirements, and packaging weight specifications across the projection horizon. CAGRs derive from installed capacity utilization rates, agricultural input price trajectories, and regulatory compliance cost absorption curves. Forecast inputs incorporate freeze-drying technology substitution elasticities and emergency preparedness stockpile rotation schedules.
Forecasts assume regulatory continuity in FDA FSMA preventive controls and Health Canada Safe Food for Canadians Regulations; material policy shifts would require re-modeling. Energy price volatility, agricultural input availability disruptions, and freeze-drying capital cost declines represent specific revision triggers. Revision becomes warranted when freeze-dried format market penetration crosses thresholds that collapse premium pricing power in conventional dehydrated fruit segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Commercial Walk in Freezer Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
Frozen Dumplings Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Frozen Food and Snacks Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
Chilled Processed Food Market
Processed and Frozen Foods
Individual Quick Frozen Cheese Market