
 Dairy Whiteners Market | 2026-2036
Dairy Whiteners Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Whiteners Market Analysis
Food service procurement is broadening across tea and coffee chains, quick-service restaurants, and institutional catering, reshaping how dairy whiteners move through distribution channels. Nestlé SA leverages its manufacturing scale and brand architecture to dominate retail shelf presence in emerging economies. Gujarat Cooperative Milk Marketing Federation Ltd anchors its competitive position through backward integration into cooperative milk collection networks. Britannia Industries Ltd competes on price-accessible formulations targeting mass-market households.
Dairy whiteners are spray-dried or roller-dried emulsions containing milk solids, vegetable fat, and stabilizers, engineered to dissolve rapidly in hot beverages while resisting feathering and oil separation. Powdered formulations command the largest volume share due to extended shelf stability and lower logistics costs, though liquid creamers generate superior margins in food service accounts. The beverage industry application concentrates demand around coffee and tea preparation, where consistent whitening performance and neutral flavor profiles determine supplier selection.
FSSAI in India, EFSA in Europe, and FDA in the United States each enforce distinct compositional standards for milk fat replacement ratios and additive permissibility, fragmenting formulation requirements across export destinations. Codex Alimentarius guidelines provide a baseline for international trade, but national regulators impose additional labeling and nutritional disclosure obligations that complicate cross-border product standardization. Stakeholders must monitor evolving fat-content thresholds and clean-label demands to align R&D pipelines with jurisdiction-specific compliance architectures.
Market Dynamics
Food service procurement concentration around tea and coffee chains is restructuring dairy whitener distribution, as quick-service restaurants and institutional buyers consolidate supplier relationships around performance-specified, long-shelf-life formulations.
Growth Catalysts
- India's FSSAI milk solids mandates:Tightening compositional standards are forcing manufacturing upgrades that favor organized producers with quality-assured spray-drying infrastructure, accelerating formalization of the supply base.
- Quick-service restaurant expansion:Beverage menu standardization across QSR networks is creating predictable, high-volume demand for liquid creamer formats with consistent whitening performance.
- Urban household convenience preference:Time-compressed consumption patterns in Indian metropolitan areas are displacing fresh milk preparation with instant-dissolve powdered whiteners.
Market Restraints
- Vegetable fat input volatility:Palm oil and coconut oil price swings compress formulation margins and complicate long-term contract pricing with food service accounts.
- Export destination fragmentation:Divergent EFSA, FDA, and Codex Alimentarius standards on fat replacement ratios and additive permissibility force redundant product-line engineering.
- Fresh milk substitution in premium channels:Specialty coffee shops and artisan tea houses in Tier-1 Indian cities are reverting to whole milk for perceived authenticity.
Strategic Opportunities
- Clean-label formulation whitespace:EFSA and FDA scrutiny of synthetic stabilizers is creating first-mover advantage for brands developing label-friendly emulsifier systems.
- Rural Indian distribution penetration:Kirana store and cooperative society networks remain undersupplied with branded whitener options relative to urban modern trade saturation.
- Plant-based hybrid positioning:Convergence of oat protein extraction with traditional dairy solids processing enables dual-identity products targeting flexitarian beverage consumers.
Industry Challenges
- Spray-drying energy intensity:Natural gas and electricity cost escalation is straining capital allocation for capacity expansion, particularly for mid-scale manufacturers.
- Multi-jurisdiction label compliance:Synchronized FSSAI, EFSA, and FDA nutritional disclosure timelines strain regulatory affairs teams and delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Whiteners Market |
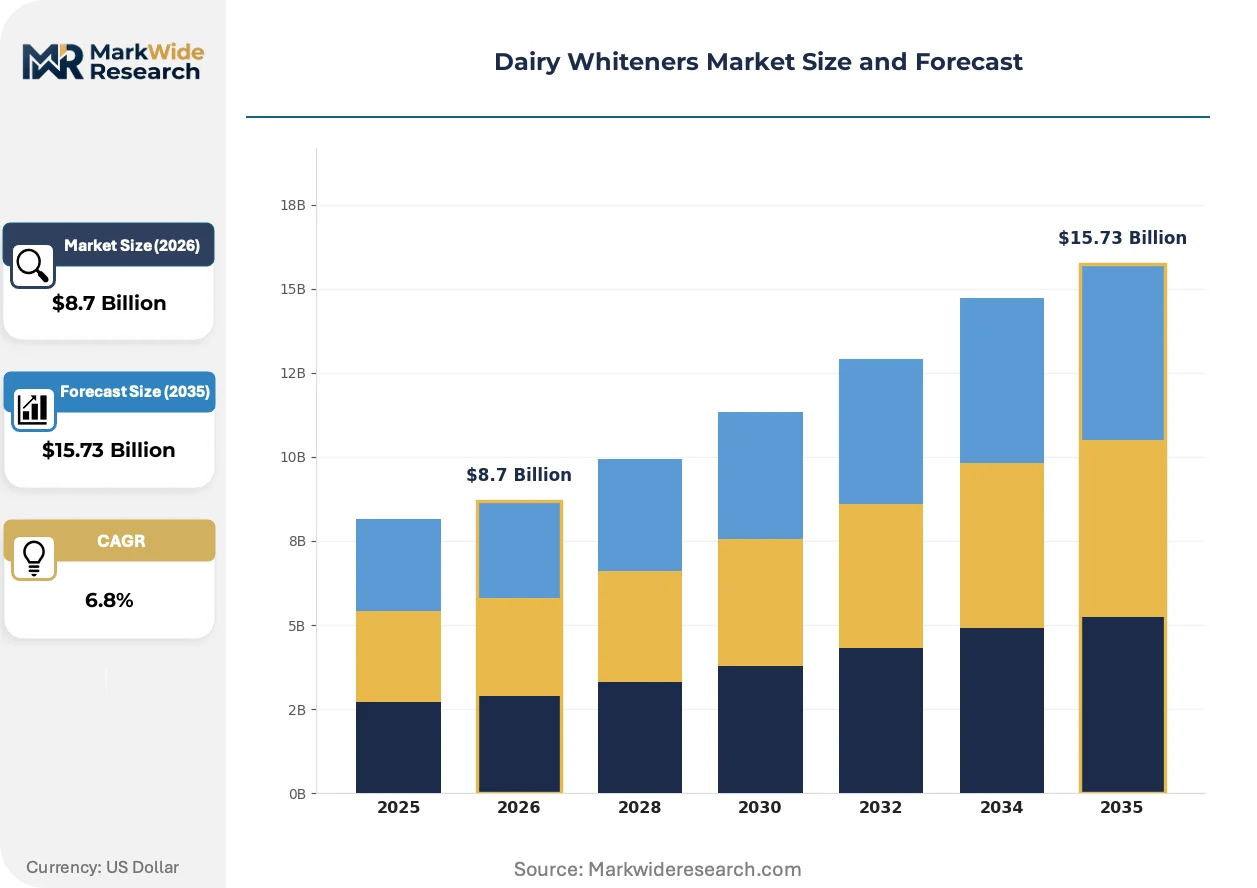
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Liquid, Creamer, Specialty End User: Households, Food Service, Beverage Industry, Dairy Manufacturers Application: Coffee, Tea, Culinary, Baking Packaging Type: Bags, Bottles, Tetra Packs, Canisters |
| Companies Covered | Nestlé SA, Gujarat Cooperative Milk Marketing Federation Ltd, Britannia Industries Ltd, Mother Dairy Fruit & Vegetable Private Limited, Fonterra Co-operative Group Limited, Danone, Arla Foods, Dairy Farmers of America, Saputo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Whiteners Market Emerging Trajectories
Formulation science and procurement specification are converging to redefine competitive advantage, with performance metrics displacing price in supplier selection across institutional channels.
Encapsulation technology for flavor masking and oxidative stability is modularizing product architecture, enabling food service buyers to specify customized particle-size distributions for their equipment profiles. Tea and coffee chains with proprietary brewing systems are adopting these configurable inputs at accelerating pace. The technology is modularizing what had been commoditized bulk supply into engineered ingredient relationships.
REACH and F-Gas Regulation in Europe are tightening scrutiny on processing aids and packaging materials used in dairy analog production, forcing reformulation of stabilizer systems and migration-resistant laminates. Manufacturers serving EU export markets are rebuilding supply chains around certified-clean input streams. Powdered whitener lines destined for European distribution bear the highest compliance burden, with some Indian producers bifurcating their facilities to isolate EU-dedicated production.
Specification-based vendor consolidation is compressing supplier lists at large food service accounts, with technical service capabilities and lot-traceability systems becoming gatekeeping criteria. Tea and coffee chains with national footprints are displacing fragmented local sourcing with centralized procurement contracts tied to performance guarantees. This pattern is most visible in India's metropolitan QSR networks, where consistency audits and failure-rate penalties now structure supplier relationships.
Dairy Whiteners Market Segmentation
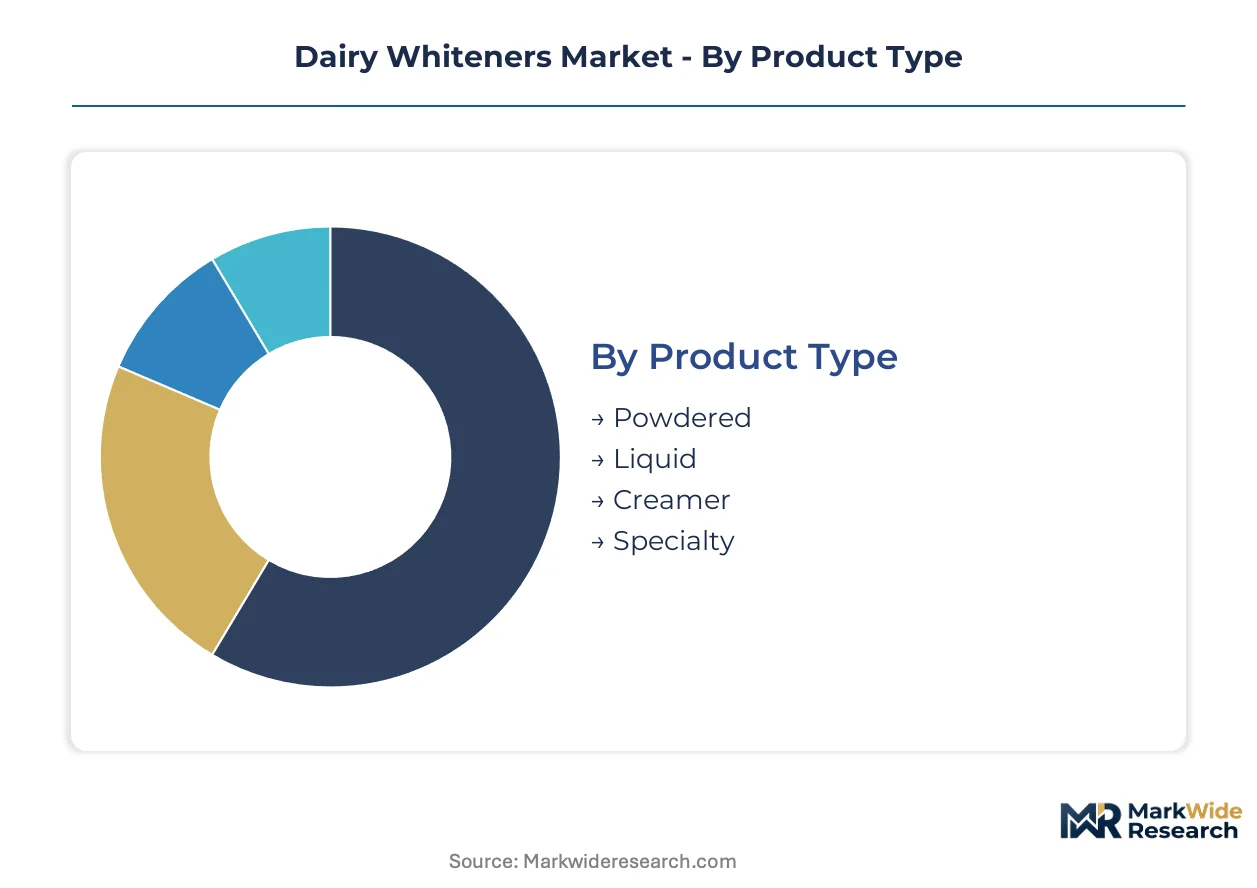
Dairy whitener segmentation reveals how supply-side capabilities align with divergent channel requirements. Product form, end-user procurement power, and packaging logistics each create distinct competitive battlegrounds where manufacturing scale or formulation agility determines winner selection.
Product Type:
Spray-drying and liquid emulsion infrastructure concentrates among organized producers with captive vegetable fat supply chains.
- Powdered:Spray-dried or roller-dried emulsions containing milk solids, vegetable fat, and stabilizers engineered for rapid hot-beverage dissolution. Demand concentrates in Indian urban households and quick-service restaurants where extended shelf stability and lower logistics costs override fresh milk preparation time.
- Liquid:Ready-to-pour creamer formats with consistent whitening performance and superior margins. Food service accounts in metropolitan Indian tea and coffee chains drive procurement concentration around performance-specified, long-shelf-life formulations.
- Creamer:Higher-fat emulsion systems targeting beverage industry formulation standards.
- Specialty:Encapsulation-enabled variants with customized particle-size distributions for proprietary brewing equipment.
Today's leader: Powdered. Tomorrow's challenger: Liquid.
End User:
Procurement specification intensity varies sharply across buyer categories, with institutional accounts imposing performance guarantees that retail channels rarely demand.
- Households:Price-sensitive mass-market consumers in Indian metropolitan areas favoring instant-dissolve convenience over fresh milk preparation. Time-compressed consumption patterns displace traditional dairy procurement.
- Food Service:Tea and coffee chains, quick-service restaurants, and institutional catering consolidating supplier relationships around technical service capabilities and lot-traceability systems. Centralized procurement contracts with consistency audits and failure-rate penalties now structure supplier relationships.
- Beverage Industry:Coffee and tea preparation applications where neutral flavor profiles and consistent whitening performance determine supplier selection.
- Dairy Manufacturers:Industrial ingredient buyers requiring bulk supply with formulation standardization for downstream product integration.
Food Service commands specification power. Households represent volume scale.
Application:
Beverage whitening dominates volume offtake while culinary and baking applications impose distinct functional requirements on emulsion stability.
- Coffee:The largest application segment by volume, with hot-beverage dissolution performance and resistance to feathering and oil separation as critical selection criteria.
- Tea:Rapidly expanding demand driver in Indian food service channels where chai preparation standardization creates predictable high-volume requirements.
- Culinary:Sauce and gravy applications requiring heat-stable emulsion systems.
- Baking:Ingredient integration demanding specific fat replacement ratios and moisture control properties.
Coffee anchors current revenue. Tea is gaining share fastest.
Packaging Type:
Logistics economics and shelf-life requirements fragment packaging preferences across retail modern trade versus traditional kirana distribution.
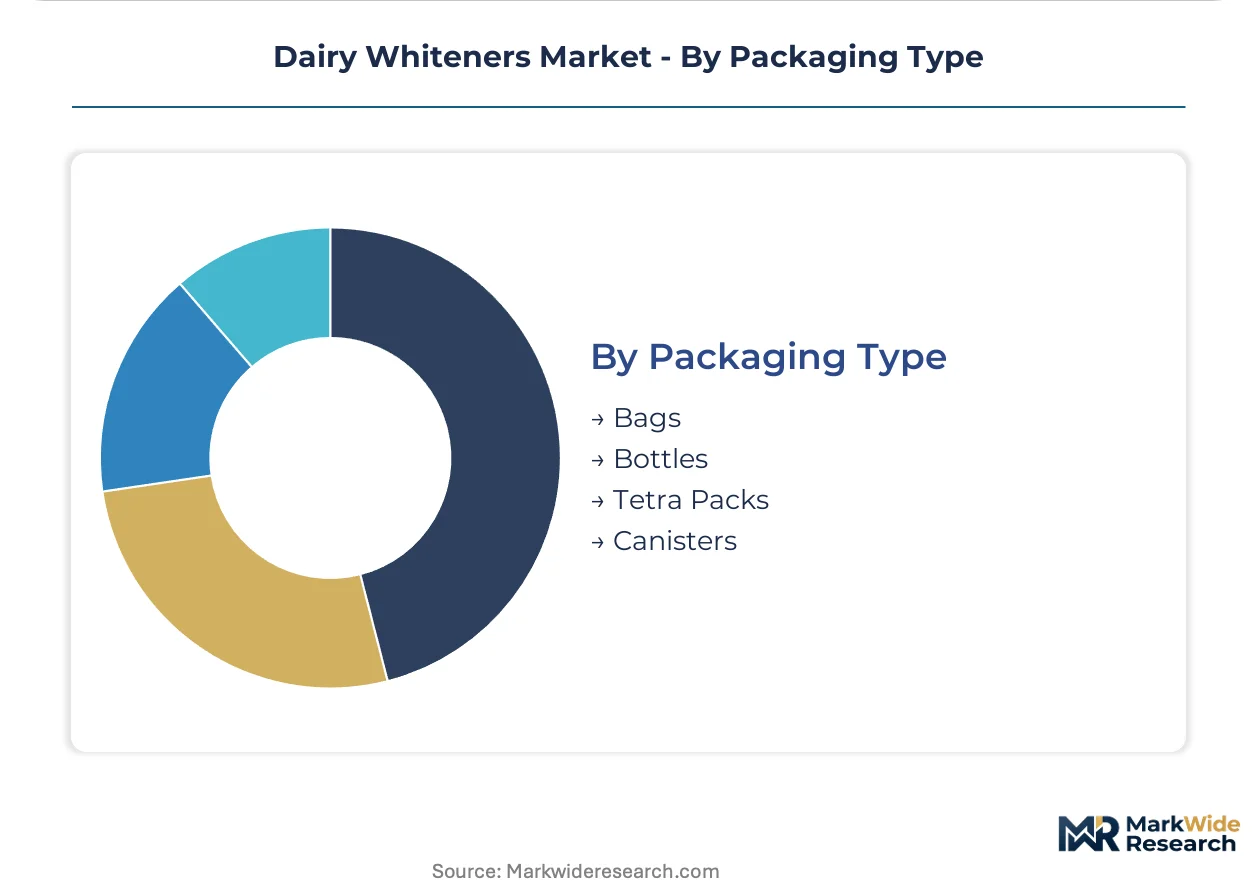
- Bags:Flexible packaging dominating bulk household and small food service procurement with cost-efficient material usage.
- Bottles:Liquid creamer formats preferred by quick-service restaurants for controlled dispensing and portion management.
- Tetra Packs:Aseptic liquid formats with extended ambient stability for institutional catering accounts.
- Canisters:Premium-positioned powdered formats targeting urban modern trade shelf presence.
Bags capture rural penetration. Canisters defend urban premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers migrate toward jurisdictions with favorable fat-replacement standards and lower energy costs for spray-drying operations. Compliance-cost gaps between FSSAI, EFSA, and FDA jurisdictions are accelerating facility location decisions.
India
Urban household convenience preferences and quick-service restaurant expansion drive volume concentration in Maharashtra and Gujarat. FSSAI mandates on milk solids content and labeling requirements tighten product specifications across manufacturing facilities. The Anand-Gujarat milk cooperative cluster anchors backward-integrated supply chains serving both domestic retail and export markets.
United States
Food service procurement concentration around tea and coffee chains creates predictable demand for liquid creamer formats with consistent whitening performance. FDA standards on additive permissibility and nutritional disclosure shape formulation requirements distinct from other jurisdictions. Wisconsin and California dairy processing corridors host spray-drying infrastructure serving institutional catering accounts.
Germany
EFSA scrutiny of synthetic stabilizers and REACH compliance requirements elevate clean-label formulation priorities among beverage industry buyers. The F-Gas Regulation tightens processing aid specifications for EU-bound production lines. Bavaria's food technology corridor concentrates R&D activity around encapsulation-enabled particle customization for proprietary brewing equipment.
China
Tea culture penetration and coffee chain expansion generate whitening-product demand in metropolitan tier-one cities. SAMR and GB standards on dairy analog composition create distinct domestic formulation requirements versus export specifications. The Yangtze River Delta manufacturing belt hosts spray-drying capacity serving both domestic beverage industry accounts and re-export markets.
Brazil
Coffee preparation traditions and quick-service restaurant network expansion support powdered whitener consumption in São Paulo and Minas Gerais. ANVISA regulations on milk fat replacement ratios and additive labeling impose compliance architectures distinct from North American or European standards. The São Paulo industrial corridor concentrates dairy processing infrastructure serving Mercosur distribution networks.
Dairy Whiteners Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with organized producers commanding retail shelf presence while regional dairies serve fragmented food service accounts. Three tiers structure competitive positioning: multinational CPG conglomerates with captive vegetable fat supply chains, cooperative federations with backward-integrated milk collection networks, and regional processors competing on price-accessible formulations. Dominant competitive moves include specification-based vendor consolidation at large food service accounts and bifurcated facility engineering to isolate EU-dedicated production lines.
Within the multinational tier, Nestlé SA and Danone occupy positions defined by manufacturing scale and brand architecture across emerging economies. Among cooperative structures, Gujarat Cooperative Milk Marketing Federation Ltd exemplifies backward integration into milk collection networks. Britannia Industries Ltd sits within the price-competitive tier targeting mass-market households. These three anchors illustrate how geographic origin and organizational structure map onto distinct competitive vectors without converging on identical capabilities.
| Leading Market Players |
|---|
| Nestlé SA |
| Gujarat Cooperative Milk Marketing Federation Ltd |
| Britannia Industries Ltd |
| Mother Dairy Fruit & Vegetable Private Limited |
| Fonterra Co-operative Group Limited |
| Danone |
| Arla Foods |
| Dairy Farmers of America |
| Saputo |
| Others |
Supply Flow & Price Mechanics
Spray-drying technician concentrations in Gujarat and Maharashtra create labor-cost differentials that widen pricing-tier spreads between premium canister formats and economy bag packaging. FSSAI compliance investments at organized facilities further separate cost structures from informal producers.
Pricing Analysis
Distributor margin layers absorb 12-18 percentage points before retail markup, compressing manufacturer netbacks on economy-tier powdered formats. Pricing stratifies across premium canister, standard bag, and economy bulk tiers based on certification grade and volume scale. Cost compression in liquid creamer segments is intensifying because vegetable fat input volatility erodes formulation margins. Quick-service restaurants exhibit lowest price sensitivity due to menu-standardization requirements, while rural kirana store channels remain highly price-elastic.
Supply Chain Analysis
FSSAI domestic-content mandates on milk solids sourcing are reshaping procurement toward cooperative collection networks within India. Manufacturing gravity centers on India, Germany, and the United States for spray-drying infrastructure serving distinct regulatory jurisdictions. Raw material dependencies rest on palm oil, coconut oil, and milk powder feedstocks. Single-source vulnerability concentrates in Malaysian and Indonesian palm oil supply corridors. Distribution runs through modern trade and kirana networks domestically, with institutional catering accounts served through direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dairy whiteners function as a stable compounder anchored by irreversible convenience substitution in Indian metropolitan consumption patterns. Food service procurement standardization provides predictable volume foundations resistant to cyclical fluctuation.
For Market Incumbents: Anticipate specification-based vendor consolidation at tea and coffee chains by deepening technical service capabilities and lot-traceability systems. Invest in bifurcated facility engineering to isolate EU-dedicated production lines before REACH and F-Gas Regulation enforcement tightens. Capacity expansion in the Anand-Gujarat cluster secures backward-integrated milk supply against cooperative competition.
For New Entrants and Emerging Players: Encapsulation-enabled particle customization offers technology-first wedge opportunity into specialty segments serving proprietary brewing equipment manufacturers. Rural Indian kirana networks present the most penetrable geography with branded supply gaps relative to urban saturation. Direct-to-food-service sales models bypass modern trade listing fees that entrench incumbent shelf presence.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale spray-drying specialists with FSSAI compliance infrastructure but limited brand equity. Long-term viability frames around 5-10 year convenience substitution trajectories in South Asian beverage preparation. Watch tea chain expansion rates as the inflection signal indicating food service procurement volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Stabilizer Reformulation | EFSA and FDA scrutiny of synthetic emulsifiers creates first-mover positioning in European and North American export channels. |
| Rural Distribution Network Expansion | Kirana store and cooperative society penetration captures volume underserved by urban modern trade concentration. |
| Encapsulation Technology Investment | Modular particle-size customization enables specification contracts with tea and coffee chains deploying proprietary brewing systems. |
| Backward Integration into Milk Collection | Cooperative network anchoring secures feedstock quality and FSSAI compliance cost advantages against commodity milk powder sourcing. |
| EU-Dedicated Production Line Isolation | Bifurcated facility engineering separates REACH-compliant output from domestic formulations, preventing cross-contamination liability. |
Methodological Framework
Coverage spans India, the United States, Germany, China, and Brazil, with primary inputs from each market cluster. Interviews with spray-drying plant managers, food service procurement leads at tea and coffee chains, FSSAI regulatory affairs officers, and cooperative milk collection network administrators combined with secondary validation from customs trade data, FSSAI compliance filings, SEC 10-K disclosures, and EFSA additive safety assessments. Bottom-up volume triangulation against top-down market sizing anchored analytical integrity.
Rate-of-change decomposition separated volume growth from price-mix effects across the modeling period. Segmentation dimensions modeled include product form, end-user procurement intensity, application functional requirements, and packaging logistics economics. CAGRs derived from trend-line extrapolation of food service expansion rates, urban household convenience substitution elasticities, and regulatory compliance cost trajectories. Vegetable fat price volatility and spray-drying energy cost escalation served as scenario-weighted inputs.
The model holds under stable FSSAI enforcement intensity and continued quick-service restaurant network expansion; deviation in palm oil supply disruption or fresh milk substitution reversal in premium channels would shift trajectory bounds. Forecasts reflect documented assumptions on channel mix evolution and regulatory timeline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Walnut Milk Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
Low Calorie Cream Cheese Market
Dairy Alternatives
Dairy Alternatives Market
Dairy Alternatives
Non-Dairy Ice Cream Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
North America Non-Dairy Yogurt Market
Dairy Alternatives
Lactose-Free Milk Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Asia-Pacific Dairy Alternatives Market
Dairy Alternatives
Fat Free Yogurt Market
Dairy Alternatives
Middle East Dairy Alternatives Market
Dairy Alternatives
Dry Cream Substitute Market
Dairy Alternatives
Dairy-Free Smoothies Market