
 Chocolate Ice Cream Market | 2026-2036
Chocolate Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Ice Cream Market Analysis
Precision fermentation for dairy protein replication is rewriting how manufacturers approach chocolate ice cream formulation without conventional milk solids. Unilever PLC leverages its global R&D network to scale precision-fermented bases across multiple continents. Mars anchors its portfolio through proprietary cocoa sourcing programs that secure bean-to-bar traceability. Nestlé SA competes by integrating in-house chocolate liquor production with regional dairy collection networks.
Chocolate ice cream consists of milk fat, sugar, cocoa solids, and stabilizers churned below freezing to incorporate controlled air content, typically delivering 10-16% butterfat for premium grades and 4-8% for reduced-fat variants. Its primary commercial purpose centers on delivering indulgent frozen desserts through retail and foodservice channels. The premium segment commands disproportionate margin pools as consumers trade up to single-origin cocoa and artisanal dairy blends, while dairy-free formulations represent the fastest-expanding product type as oat and pea protein bases achieve sensory parity. Pint packaging dominates e-commerce velocity, whereas tub formats sustain volume in supermarket freezer cases.
The FDA governs standard-of-identity rules for chocolate ice cream in the United States, mandating minimum milk fat thresholds that constrain reformulation flexibility. The European Food Safety Authority enforces stringent cocoa contaminant limits under EU food safety frameworks, elevating testing costs for exporters. India's FSSAI implements progressive dairy hygiene certifications that determine factory licensing for frozen confection production. Stakeholders must monitor evolving plant-based labeling disputes as regulators on three continents deliberate whether precision-fermented proteins qualify for dairy-identical nomenclature.
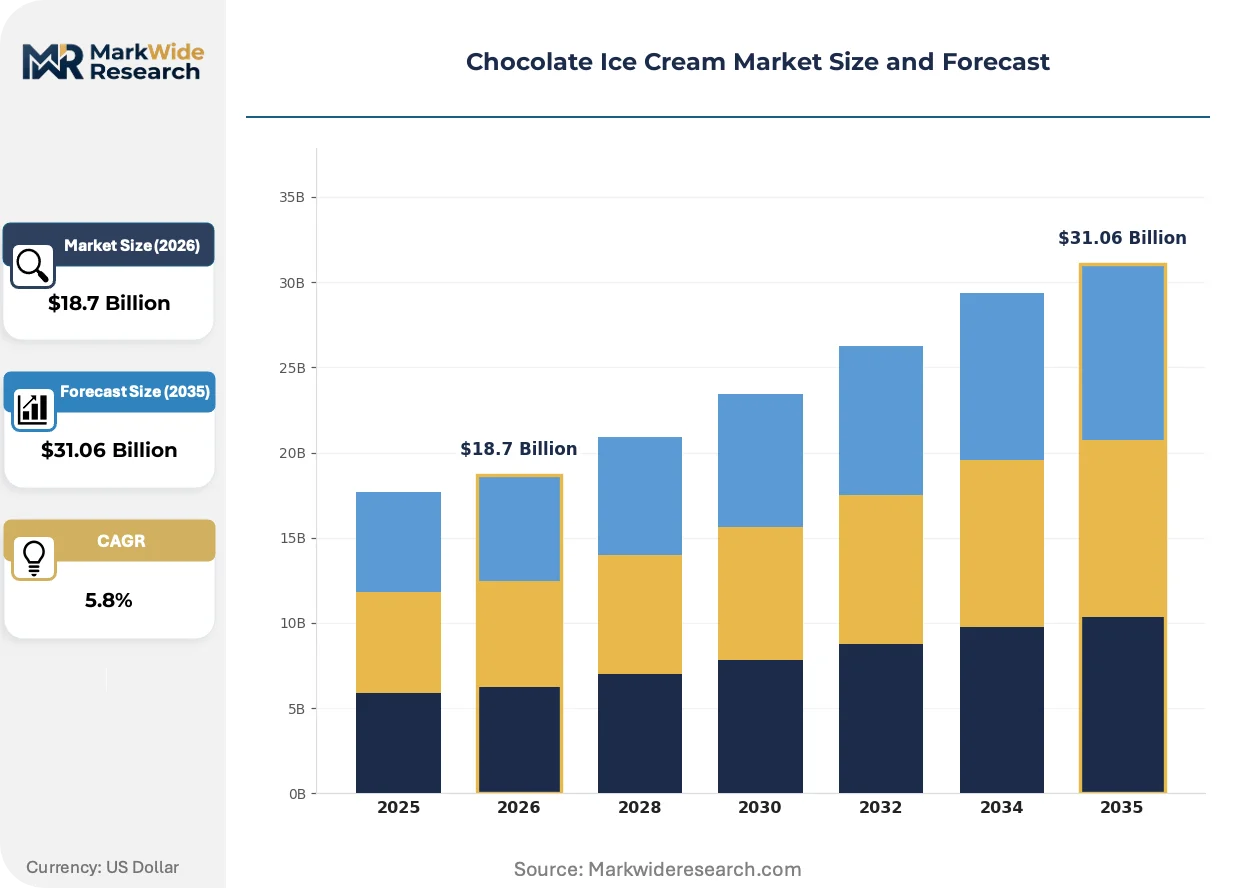
Market Dynamics
Precision fermentation for dairy protein replication is restructuring chocolate ice cream formulation economics, enabling manufacturers to bypass conventional milk solids procurement while meeting clean-label standards tightening across multiple jurisdictions.
Growth Catalysts
- EU Clean-Label Mandates:EFSA contaminant limits for cocoa solids are compelling manufacturers to upgrade testing protocols, creating premium positioning opportunities for compliant producers.
- India Cold-Chain Expansion:Dairy infrastructure modernization in tier-two cities is unlocking frozen confection distribution to previously unreachable household segments.
- Precision Fermentation Scale-Up:Laboratory-cultured dairy proteins are achieving cost parity with conventional milk solids, removing price barriers to animal-free premium formulations.
Market Restraints
- Cocoa Supply Concentration:West African bean sourcing dominates input procurement, exposing manufacturers to harvest volatility and political risk in origin markets.
- FDA Standard-of-Identity Rigidity:Minimum milk fat thresholds constrain reformulation flexibility for hybrid dairy-plant blends seeking retail placement.
- Stabilizer Cost Volatility:Locust bean gum and guar gum prices fluctuate with agricultural yields, compressing margin predictability for texture-critical premium lines.
Strategic Opportunities
- Precision-Fermented Protein Labeling:Pending determinations by FDA, EFSA, and FSSAI on dairy-identical nomenclature create first-mover advantage for regulatory clearance holders.
- Pint-Format E-Commerce Velocity:Direct-to-consumer frozen shipping infrastructure is maturing, enabling subscription models bypassing traditional supermarket slotting fees.
- Single-Origin Cocoa Provenance:Bean-to-bar traceability programs command retail price premiums as ethical sourcing becomes a discernible purchase driver in premium channels.
Industry Challenges
- Refrigerated Logistics Talent Scarcity:Cold-chain engineering expertise lags behind network expansion needs, particularly in emerging market tier-two distribution.
- Dual Certification Burden:Simultaneous compliance with FDA identity standards and EU contaminant protocols requires redundant testing infrastructure for exporters.
- Legacy Dairy Integration Complexity:Precision-fermented protein incorporation demands retooling of conventional churning equipment calibrated for animal fat crystallization behavior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Ice Cream Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Premium, Standard, Low-Fat, Dairy-Free Packaging Type: Tubs, Bars, Cups, Pints Distribution Channel: Supermarkets, Online, Convenience Stores, Specialty Shops Customer Type: Families, Singles, Kids, Health-Conscious Consumers |
| Companies Covered | Mars, Blue Bell Creameries, Unilever PLC, Tillamook County Creamery Association, Wells Enterprises, Nestlé SA, Froneri, Turkey Hill Dairy, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Ice Cream Market Emerging Trajectories
Biotechnology, regulatory stringency, and channel fragmentation are converging to reshape how chocolate ice cream is formulated, certified, and purchased across retail and foodservice environments.
Precision fermentation for whey and casein replication is rendering obsolete the traditional dependency on concentrated animal feeding operations for dairy protein supply. Artisanal and premium manufacturers are adopting these ingredients fastest, driven by carbon footprint reduction commitments and supply security concerns. The structural consequence is a bifurcation in procurement strategy between precision-fermented early adopters and conventional dairy-dependent cost leaders.
EFSA cocoa contaminant limits under EU food safety frameworks are elevating laboratory testing costs for all exporters seeking continental market access. Manufacturers must now implement dual-phase screening for heavy metals and mycotoxins prior to shipment, compressing batch release timelines. Premium single-origin producers with integrated bean-to-bar control are responding by investing in origin-site testing infrastructure to preempt rejection at port of entry.
Subscription-based frozen dessert delivery is displacing impulse freezer-case purchases among urban households with reliable cold-chain residential access. Direct-to-consumer pint formats are capturing recurring revenue streams previously monopolized by supermarket quarterly stock-up trips. This behavioral shift is most visible in North American metropolitan corridors where insulated packaging economics have achieved viability at household delivery scale.
Chocolate Ice Cream Market Segmentation
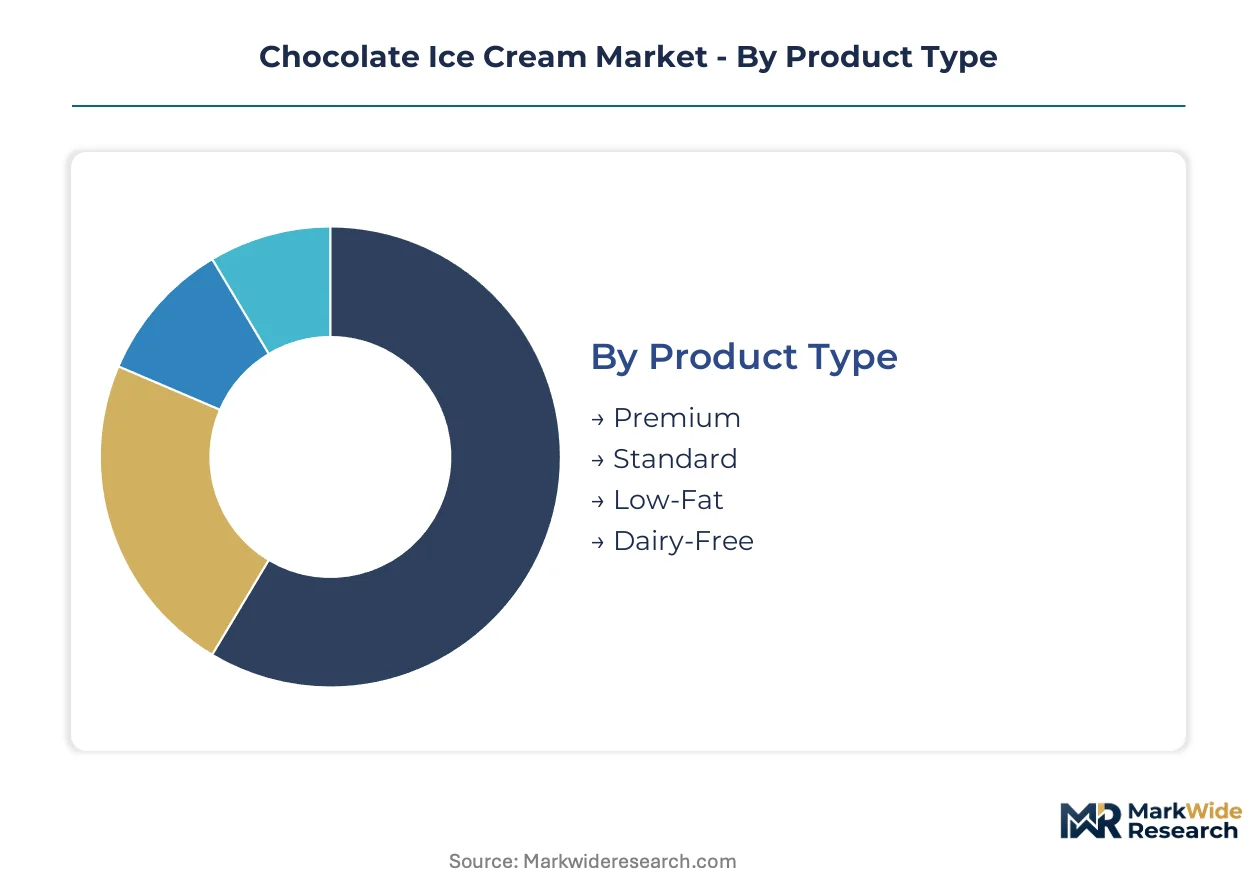
Chocolate ice cream segmentation reveals how formulation innovation, packaging logistics, and channel economics fragment demand across distinct buyer missions. Manufacturers must align production assets with specific consumption occasions rather than treating frozen dessert as a uniform category.
Product Type:
The use-case spectrum spans indulgent celebration to daily permissible treat, with butterfat content and ingredient provenance determining price positioning and regulatory classification.
- Premium:Single-origin cocoa and artisanal dairy blends deliver 14-18% butterfat content for occasion-based consumption. Demand concentrates in metropolitan households with disposable income elasticity, driven by bean-to-bar traceability programs that command retail price premiums.
- Dairy-Free:Oat, pea, and precision-fermented protein bases achieve sensory parity with conventional formulations while bypassing concentrated animal feeding operations. This segment is expanding most quickly in North American and European urban markets where lactose intolerance and carbon footprint concerns overlap.
- Standard:Mid-tier butterfat formulations balance cost efficiency with acceptable mouthfeel for routine household purchase.
- Low-Fat:Reduced butterfat variants (3-5%) rely on stabilizer systems to compensate for compromised texture, appealing to restricted-diet protocols.
Established volume favors Standard; emerging adoption favors Dairy-Free.
Packaging Type:
Cost tier determines capital intensity and cold-chain requirements, with format selection directly constraining distribution channel access and inventory velocity.
- Pints:Single-serve and small-household formats dominate direct-to-consumer subscription velocity, with insulated shipping economics now viable at residential delivery scale. Demand concentrates in e-commerce channels where recurring revenue models bypass supermarket slotting fees.
- Tubs:Multi-serve containers sustain volume in supermarket freezer cases through quarterly stock-up purchase patterns. Family-oriented buyers in suburban and tier-two Indian markets drive procurement, supported by expanding cold-chain penetration into previously unreachable distribution nodes.
- Bars:Individual stick formats optimize for impulse convenience store placement and on-premise foodservice dispensing.
- Cups:Single-serve portion control appeals to institutional foodservice and controlled-indulgence household segments.
Legacy infrastructure favors Tubs; channel disruption favors Pints.
Distribution Channel:
Volume concentration varies by geography, with modern trade formats expanding fastest where cold-chain reliability permits frozen inventory holding.
- Supermarkets:Broad freezer case placement captures planned purchase missions through promotional pricing and family-size formats. Tier-two Indian cities and Southeast Asian metropolitan corridors are witnessing accelerated penetration as dairy infrastructure modernizes.
- Online:Direct-to-consumer platforms with subscription mechanics are displacing impulse freezer-case purchases among urban households with reliable residential cold-chain access. Insulated packaging economics have achieved viability at household delivery scale in North American corridors.
- Convenience Stores:Impulse-oriented single-serve formats target immediate consumption occasions with limited freezer footprint.
- Specialty Shops:Artisanal and premium formulations with provenance narratives command price premiums through experiential retail environments.
Mass volume runs through Supermarkets; steepest expansion trajectory belongs to Online.
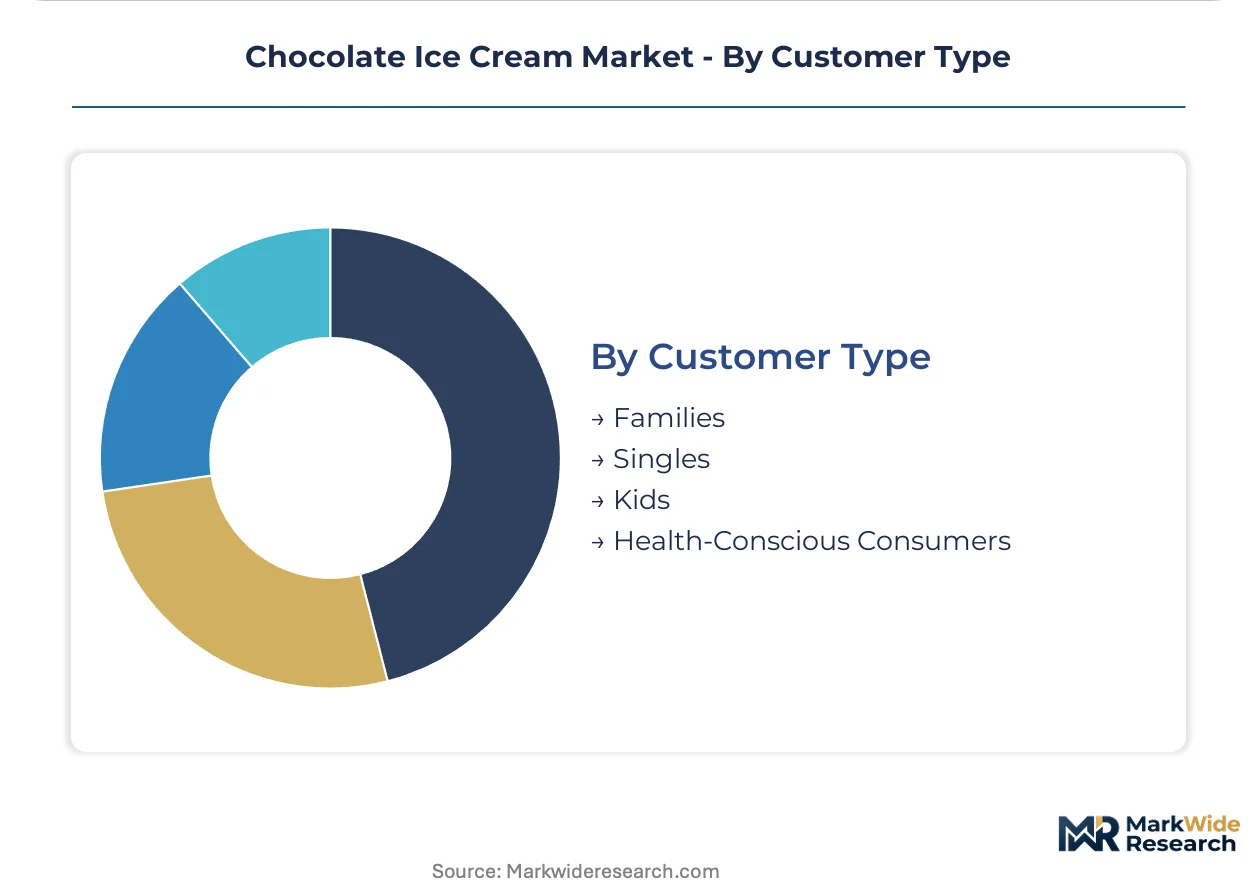
Customer Type:
Margin structure diverges sharply across demographic missions, with health-positioned variants capturing disproportionate price realization despite formulation cost compression.
- Health-Conscious Consumers:Clean-label scrutiny and macronutrient tracking drive preference for reduced-sugar, high-protein, or precision-fermented formulations. EU clean-label mandates and EFSA contaminant limits are compelling manufacturers to upgrade testing protocols, creating premium positioning opportunities for compliant producers.
- Families:Multi-serve procurement with price sensitivity and child-palatability requirements sustains volume in traditional retail channels. Indian market demand is concentrating here as cold-chain logistics penetrate tier-two cities and dairy infrastructure modernization unlocks frozen confection distribution.
- Singles:Small-format, single-serve purchase patterns align with urban household structures and convenience-oriented channel preferences.
- Kids:Novelty-driven flavor innovation and licensed character marketing dominate this mission, with parental gatekeeping on ingredient transparency intensifying.
Household penetration anchors Families; value-per-unit premium concentrates in Health-Conscious Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
West African cocoa shipments supply European and North American processing facilities, while Indian dairy output increasingly feeds domestic frozen confection manufacturing as cold-chain infrastructure matures.
United States
Supermarket freezer consolidation and direct-to-subscription pint velocity drive channel bifurcation. FDA standard-of-identity rules constrain hybrid formulation innovation. Chicago and Minneapolis-St. Paul host concentrated dairy processing and frozen dessert manufacturing clusters serving national distribution networks.
Germany
Clean-label scrutiny and precision-fermented protein adoption accelerate among metropolitan consumers. EFSA cocoa contaminant limits elevate laboratory testing costs for all market entrants. Bavaria anchors artisanal dairy processing capacity with integrated bean-to-bar chocolate operations supplying premium private-label programs.
India
Dairy infrastructure modernization and tier-two cold-chain penetration unlock frozen confection access for family-oriented buyers. FSSAI dairy hygiene certifications determine factory licensing eligibility. Maharashtra and Gujarat concentrate manufacturing investment as cooperative dairy networks integrate with urban retail distribution.
United Kingdom
Premium single-origin positioning and subscription-channel experimentation reshape purchase patterns among urban households. EFSA-aligned contaminant protocols apply through retained EU regulatory alignment. London and the Southeast corridor concentrate artisanal manufacturing and direct-to-consumer fulfillment infrastructure.
Brazil
Cocoa processing integration and dairy cooperative expansion support regional frozen dessert manufacturing growth. National dairy hygiene regulations govern production licensing through the national agricultural ministry. São Paulo state concentrates industrial dairy processing with port access for ingredient import and product export.
Chocolate Ice Cream Market Vendor Landscape
Channel-controlling players compete with product-specialist players across supermarket, foodservice, and direct-to-consumer vectors. The market structure consolidates around multinational conglomerates with integrated cocoa procurement and dairy supply networks, while regional creameries occupy defended local positions through provenance narratives. Two strategic archetypes dominate: scale-driven global manufacturers with precision-fermentation R&D pipelines, and heritage-rooted cooperatives with captive regional dairy supply. Competitive moves concentrate on precision-fermentation scale-up partnerships and single-origin cocoa traceability program development.
Within the multinational conglomerate tier, Unilever PLC and Nestlé SA occupy positions defined by integrated global R&D networks and captive chocolate liquor production capabilities. Mars anchors the cocoa-forward specialist archetype through proprietary bean-to-bar sourcing programs. Among North American heritage creameries, Blue Bell Creameries and Tillamook County Creamery Association exemplify the cooperative-rooted regional defender model with concentrated geographic manufacturing footprints.
| Leading Market Players |
|---|
| Mars |
| Blue Bell Creameries |
| Unilever PLC |
| Tillamook County Creamery Association |
| Wells Enterprises |
| Nestlé SA |
| Froneri |
| Turkey Hill Dairy |
| General Mills |
| Others |
Supply Flow & Price Mechanics
West African cocoa processing clusters in Abidjan and San Pedro anchor global butterfat-equivalent input costs, with their harvest volatility transmitting directly into premium-tier pricing power for manufacturers with integrated bean-to-bar control. Precision-fermented protein scale-up in European and North American biotechnology hubs is compressing mid-tier pricing spreads as laboratory-cultured dairy achieves cost parity with conventional milk solids procurement.
Pricing Analysis
Current-generation precision-fermented formulations command 15-40% premiums over prior-generation oat and pea protein bases, while next-generation hybrid blends promise further compression. Three-tier pricing structure across premium, standard, and economy levels stratifies by butterfat content and cocoa provenance certification, with EFSA contaminant compliance and single-origin traceability as primary price differentiation drivers. Pricing pressure stems from stabilizer cost volatility in locust bean gum and guar gum markets, squeezing margin predictability for texture-critical lines. Family-oriented buyers in supermarket channels exhibit highest price sensitivity, while health-conscious urban subscribers demonstrate lowest elasticity for clean-label and precision-fermented variants.
Supply Chain Analysis
Upstream feedstock dynamics center on West African cocoa bean concentration in Côte d'Ivoire and Ghana, Brazilian dairy cooperative output, and Indian buffalo milk collection networks. Raw material dependencies span cocoa solids procurement, milk fat sourcing, and precision-fermented protein cultivation infrastructure. Single-source vulnerability in West African bean supply exposes manufacturers to harvest volatility and political risk in origin markets. Distribution runs through supermarket freezer consolidation for family stock-up missions, direct-to-consumer insulated shipping for urban subscription velocity, and foodservice dispensing for impulse occasions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer frozen dessert platforms are redefining channel economics, with subscription interoperability between e-commerce fulfillment and supermarket loyalty programs creating winner-take-most dynamics in metropolitan cold-chain corridors.
For Market Incumbents: Build precision-fermentation R&D moats through captive biotechnology partnerships and scaled laboratory capacity in European and North American hubs. Consolidate defensive position by securing exclusive single-origin cocoa offtake agreements in Côte d'Ivoire and Ghana, insulating against harvest volatility while commanding traceability premiums. Accelerate certification investment for EFSA contaminant compliance and pending FDA dairy-identical nomenclature clearance to preempt regulatory arbitrage by emerging competitors.
For New Entrants and Emerging Players: Tier-two Indian cities with nascent cold-chain penetration represent the most penetrable entry point for family-format tub distribution, leveraging cooperative dairy network integration and FSSAI licensing pathways. Precision-fermented protein formulations targeting health-conscious urban subscribers in North American metropolitan corridors offer second white-space opportunity, with direct-to-consumer pint subscription as primary go-to-market angle bypassing supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a platform-rollup play because cold-chain infrastructure and precision-fermentation biotechnology are concentrating competitive advantage among scaled operators with integrated R&D and distribution control. Acquisition target archetype: regional creameries with captive dairy supply and provenance narratives, or precision-fermentation startups with regulatory clearance progress. Signal to watch: FDA, EFSA, and FSSAI determinations on dairy-identical protein labeling, which will restructure valuation multiples across animal-free formulation portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Scale-Up Partnership | Laboratory-cultured dairy protein cost parity removes price barriers to premium animal-free formulations. |
| Single-Origin Cocoa Traceability Program | Bean-to-bar provenance commands retail price premiums as ethical sourcing becomes discernible purchase driver. |
| Direct-to-Consumer Subscription Launch | Insulated shipping economics at household delivery scale bypass supermarket slotting fees and capture recurring revenue. |
| EFSA Contaminant Compliance Certification | Dual-phase heavy metals and mycotoxins screening preempts rejection at EU port of entry for exporters. |
| Tier-Two Cold-Chain Distribution Expansion | Indian dairy infrastructure modernization unlocks frozen confection access to previously unreachable family household segments. |
Methodological Framework
Initial hypotheses were tested against primary input from frozen dessert brand managers, supermarket category buyers, cold-chain logistics engineers, and precision-fermentation R&D directors, and refined through secondary validation against FSSAI dairy hygiene certification records, EFSA contaminant limit documentation, Nielsen retail audit data, and customs trade statistics for cocoa bean imports. Bottom-up demand modeling across product type, packaging format, distribution channel, and customer mission segments was triangulated with top-down market sizing from manufacturer production disclosures and cooperative dairy output reports.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning butterfat content tier, cocoa provenance grade, packaging cold-chain intensity, and regional regulatory cluster. CAGRs were derived from slope analysis of historical volume trajectories and elasticity-adjusted adoption curves for precision-fermented protein substitution. Forecast inputs incorporated cold-chain penetration rates in Indian tier-two cities, EFSA laboratory testing cost inflation, and precision-fermentation scale-up timelines from biotechnology partner disclosures.
Stress conditions across West African harvest volatility, stabilizer commodity price spikes, and regulatory labeling determination delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cold-chain infrastructure buildout pacing and precision-fermentation cost reduction curves. Cross-checking against Nielsen retail velocity data and cooperative dairy production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
GCC Frozen Fruits and Vegetables Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Cambodia Frozen Food Market
Processed and Frozen Foods
Freeze Dried Vegetables Market
Processed and Frozen Foods
Frozen Pork Belly Market
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
Germany Frozen Snack Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market