
 Middle East and Africa Dairy Alternatives Market | 2026-2036
Middle East and Africa Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Dairy Alternatives Market Foresight
Oat protein is shifting from niche ingredient to mainstream dairy replacement across Middle East and Africa formulation labs, cutting unit costs in barista-grade beverages. Almarai Company leverages its Gulf dairy distribution network to secure shelf space for plant-based lines in Saudi supermarkets. Danone SA anchors its regional position through fermented almond and soy drink portfolios tailored to North African taste profiles. Blue Diamond Growers competes on almond concentrate supply, sourcing California kernels for reconstitution in Egyptian and Moroccan processing facilities.
Middle East and Africa dairy alternatives comprise formulated beverages, cultured products, and frozen desserts engineered from oilseed, cereal, or nut extracts to replicate the functional and sensory properties of cow milk, typically achieving protein contents between 0.5 and 3.5 grams per 100 milliliters depending on base material and fortification. These products serve lactose-intolerant consumers, vegan populations, and institutional buyers seeking extended ambient shelf stability in hot-climate supply chains. Almond milk occupies the premium tier in Gulf retail channels, while soy milk dominates Egyptian and Sudanese household penetration due to lower price points and established local crushing infrastructure. Oat milk is expanding fastest within cafe and restaurant end user segments, capitalizing on frothing performance that satisfies specialty coffee preparation standards.
Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology govern product identity standards, fortification limits, and allergen labeling for plant-based beverages across the Gulf, while South Africa's Department of Health enforces compositional requirements that shape import eligibility and local manufacturing investment. Compliance with these frameworks determines market access velocity and reformulation costs for new entrants. Stakeholders must monitor evolving protein content thresholds and front-of-pack labeling mandates that will determine which formulations retain retail authorization.
Market Dynamics
Oat protein extraction technology is compressing formulation costs across Middle East and Africa beverage labs, forcing incumbents to reformulate barista-grade lines or surrender food service contracts to lower-cost entrants.
Growth Catalysts
- SFDA fortification mandates:Saudi Food and Drug Authority protein threshold requirements for plant-based beverages are accelerating R&D investment in concentrated almond and oat bases.
- Specialty coffee preparation standards:Frothing performance specifications from Dubai and Riyadh cafe chains are pulling oat milk into mainstream food service procurement.
- Sudanese soy crushing infrastructure:Established oilseed processing capacity along the Nile is supplying cost-competitive soy milk base to Egyptian and Ethiopian bottlers.
Market Restraints
- California almond concentrate dependency:Kernel supply concentration on the US West Coast exposes Egyptian and Moroccan reconstitution facilities to water-policy-driven price volatility.
- Emirates Authority for Standardization and Metrology allergen thresholds:Strict labeling mandates for nut-derived beverages are constraining formulation flexibility in UAE retail channels.
- Cow milk powder subsidies:Government-supported dairy programs in North Africa are undercutting plant-based price positioning in price-sensitive household segments.
Strategic Opportunities
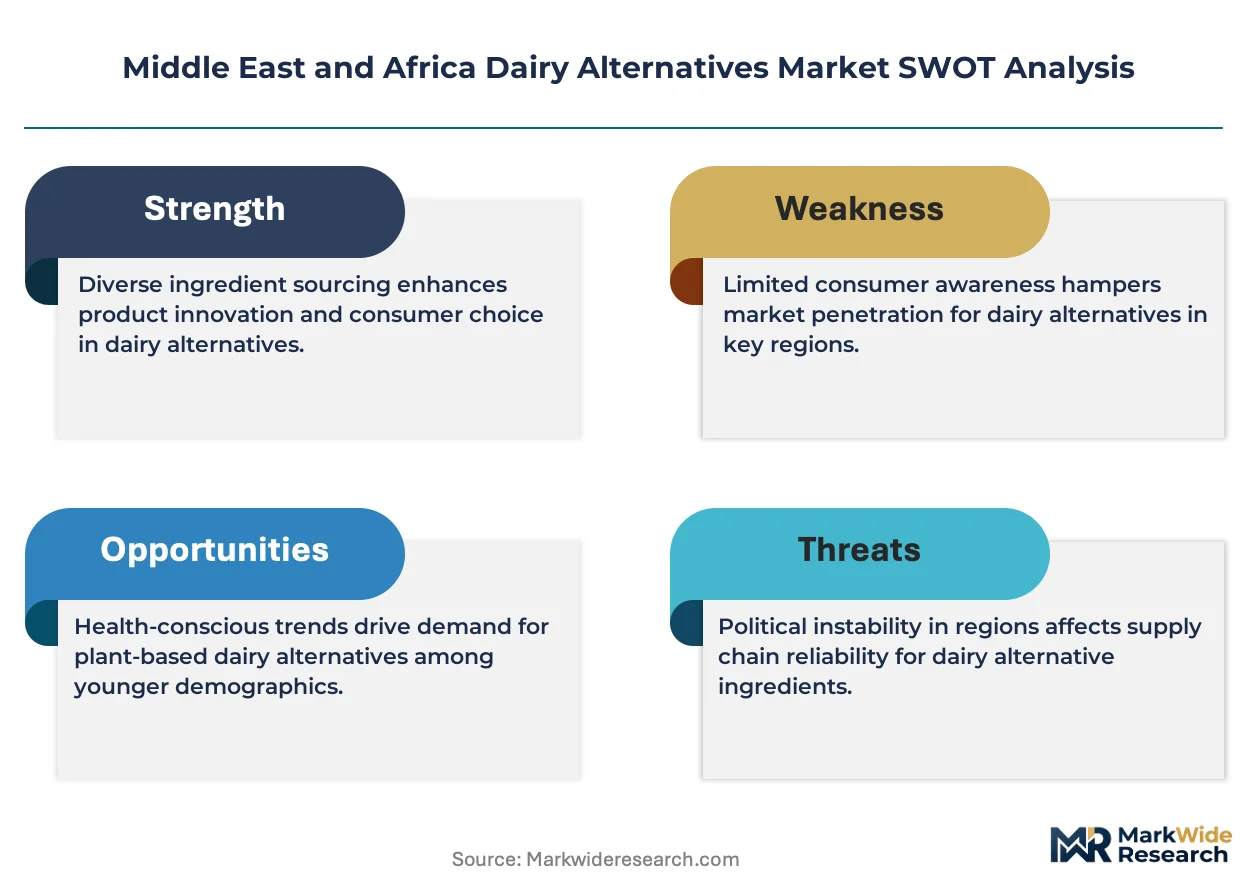
- South African Department of Health disclosure standards:Tightening nutritional labeling requirements are creating first-mover advantage for fortified oat and almond lines that exceed minimum protein thresholds.
- Hotel food service channels in the United Arab Emirates:Premium hospitality procurement is opening volume contracts for barista-certified almond milk with extended ambient shelf stability.
- Fermentation technology convergence:Precision fermentation of oat proteins combined with traditional lactic acid cultures is enabling cultured plant-based yogurt formats tailored to North African taste profiles.
Industry Challenges
- Food technologist scarcity:Formulation expertise for heat-stable oat emulsions is concentrated in European and North American talent pools, delaying product launch timelines for Gulf-based manufacturers.
- Halal certification complexity:Multi-country supply chains for almond concentrate require separate approvals from Emirates Authority for Standardization and Metrology and Saudi Food and Drug Authority, extending time-to-shelf by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Dairy Alternatives Market |
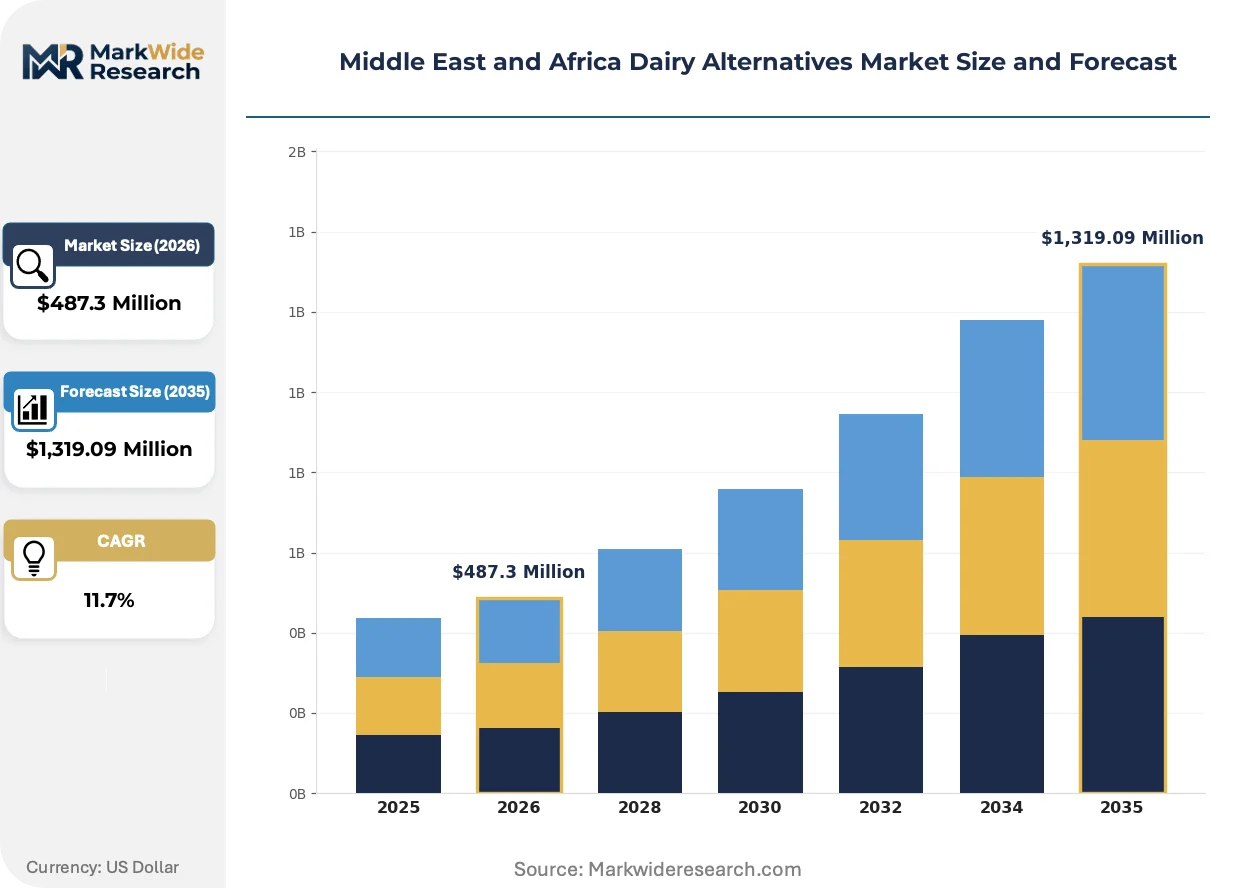
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Formulation: Organic, Gluten-Free, Flavored, Plain Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores End User: Households, Restaurants, Cafes, Food Service Providers |
| Companies Covered | Alpro Middle East, Almarai Company, SADAFCO, Juhayna Food Industries, Danone SA, Oatly Group AB, Blue Diamond Growers, SunOpta Inc., The Hain Celestial Group Inc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Dairy Alternatives Market Shifts & Advancements
Enzymatic oat processing is collapsing the cost gap between cereal-based and nut-based dairy alternatives, redrawing competitive boundaries across Middle East and Africa formulation labs.
High-pressure processing of oat base is unifying pasteurization and texture modification into single-unit operations, cutting capital requirements for Egyptian and Moroccan entrants. Regional contract manufacturers in Casablanca and Cairo are adopting these systems to serve European export markets and domestic retail simultaneously. This technology is unifying previously separate equipment lines, compressing facility footprints by thirty to forty percent and enabling mid-scale players to achieve unit economics previously reserved for integrated multinationals.
South Africa's Department of Health front-of-pack labeling regulations are mandating protein content disclosure and sugar warning icons on plant-based beverages, forcing reformulation across imported and locally manufactured lines. Manufacturers are responding by fortifying soy and oat bases with pea protein isolates to hit threshold claims. The regulation is most acute in mass retail channels where shelf placement depends on compliance scoring, disadvantaging smaller importers lacking technical reformulation capacity.
Cafe chain procurement consolidation across Gulf Cooperation Council states is compressing supplier rosters from five-plus vendors to two or three approved partners per beverage category. Procurement teams in Dubai and Riyadh are imposing unified frothing performance specifications and quarterly volume commitments, disqualifying regional blenders lacking consistent barista-grade output. This concentration is most visible in the United Arab Emirates, where hotel food service contracts now specify oat milk suppliers by name, locking out unapproved alternatives from premium channels.
Middle East and Africa Dairy Alternatives Market Segmentation
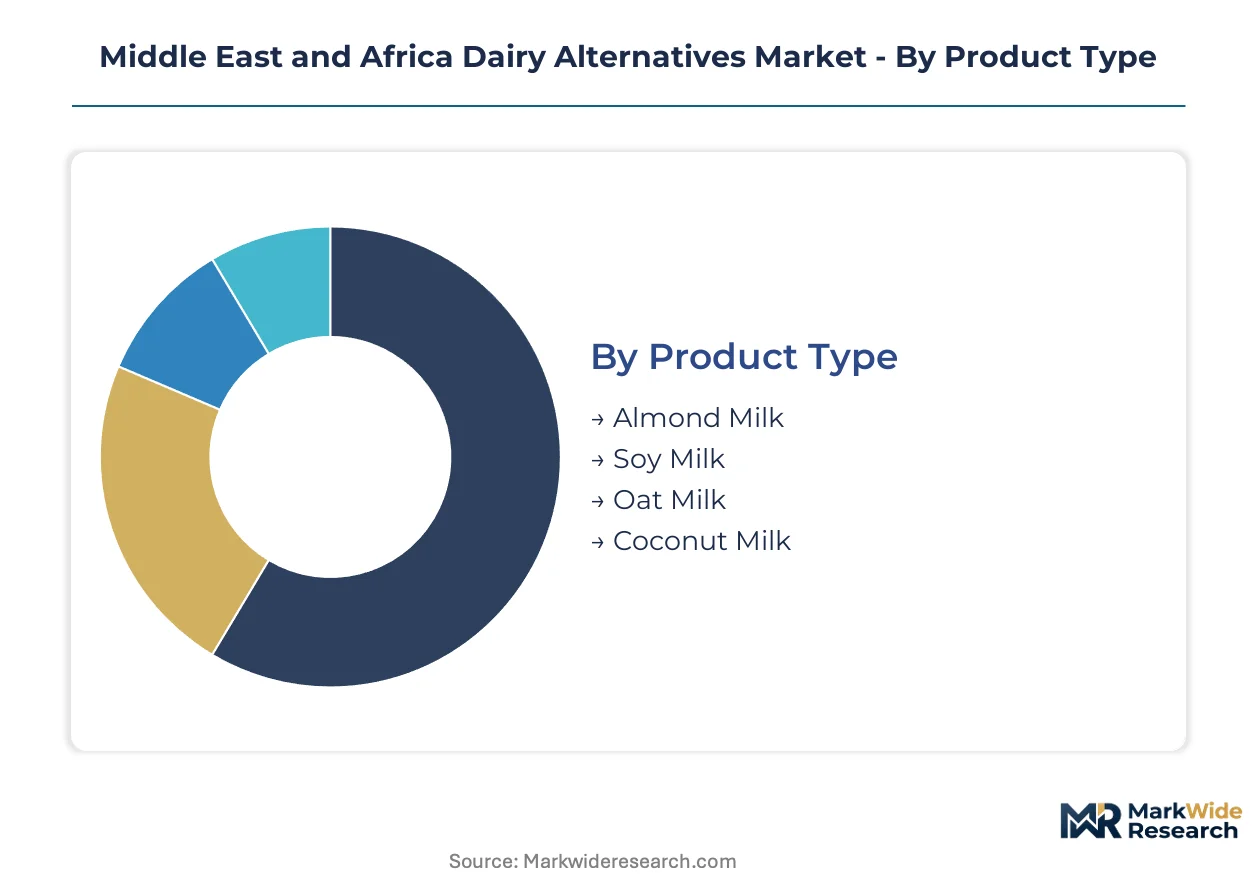
Product differentiation in Middle East and Africa dairy alternatives hinges on climate stability, protein fortification mandates, and channel-specific performance standards. Segmentation reveals where formulation investment concentrates and which supply chains command premium positioning.
Product Type:
Supply concentration for raw materials determines margin structures and reformulation flexibility across the four base categories.
- Almond Milk:Reconstituted from California kernel concentrate in Egyptian and Moroccan facilities. Premium positioning in UAE hotel food service channels depends on ambient shelf stability and barista frothing certification.
- Oat Milk:Enzymatic processing advances are compressing unit costs below nut-based alternatives. Dubai and Riyadh cafe chains specify oat bases for specialty coffee preparation, pulling volume from traditional soy procurement.
- Soy Milk:Nile-based crushing infrastructure supplies cost-competitive base to Egyptian and Sudanese bottlers.
- Coconut Milk:Southeast Asian copra sourcing serves North African cultured product formulations.
Today's leader: Almond Milk. Tomorrow's challenger: Oat Milk.
Formulation:
Regulatory thresholds and price positioning split manufacturing investment across four certification and composition tiers.
- Organic:Certified supply chains command shelf placement premiums in UAE and Saudi supermarkets. SFDA traceability requirements extend procurement timelines by four to six months.
- Gluten-Free:Oat base processing with proprietary enzyme protocols eliminates cross-contamination risk. South African Department of Health disclosure standards mandate front-of-pack labeling for gluten content.
- Flavored:Vanilla and date variants dominate Gulf retail trial purchases.
- Plain:Unsweetened lines anchor Egyptian and Sudanese household volume due to lower price points.
Organic certification captures current premium allocation. Gluten-free positioning gains fastest as oat milk expands.
Distribution Channel:
Channel concentration reflects urbanization patterns and cold-chain infrastructure maturity across the region.
- Supermarkets:Saudi and UAE hypermarket chains consolidate shelf space for ambient-stable tetrapak formats. Almarai Company leverages existing dairy distribution networks to secure placement for plant-based lines.
- Online Retail:Direct-to-consumer platforms bypass import bottlenecks for specialty fermented products. Subscription models target expatriate vegan populations in Dubai and Johannesburg.
- Health Food Stores:Organic and fortified lines concentrate in South African urban centers.
- Specialty Stores:Barista-grade oat and almond milks supply independent coffee roasters.
Supermarkets dominate volume. Online Retail climbs fastest as logistics networks mature.
End User:
Customer type determines packaging format, protein fortification levels, and certification requirements.
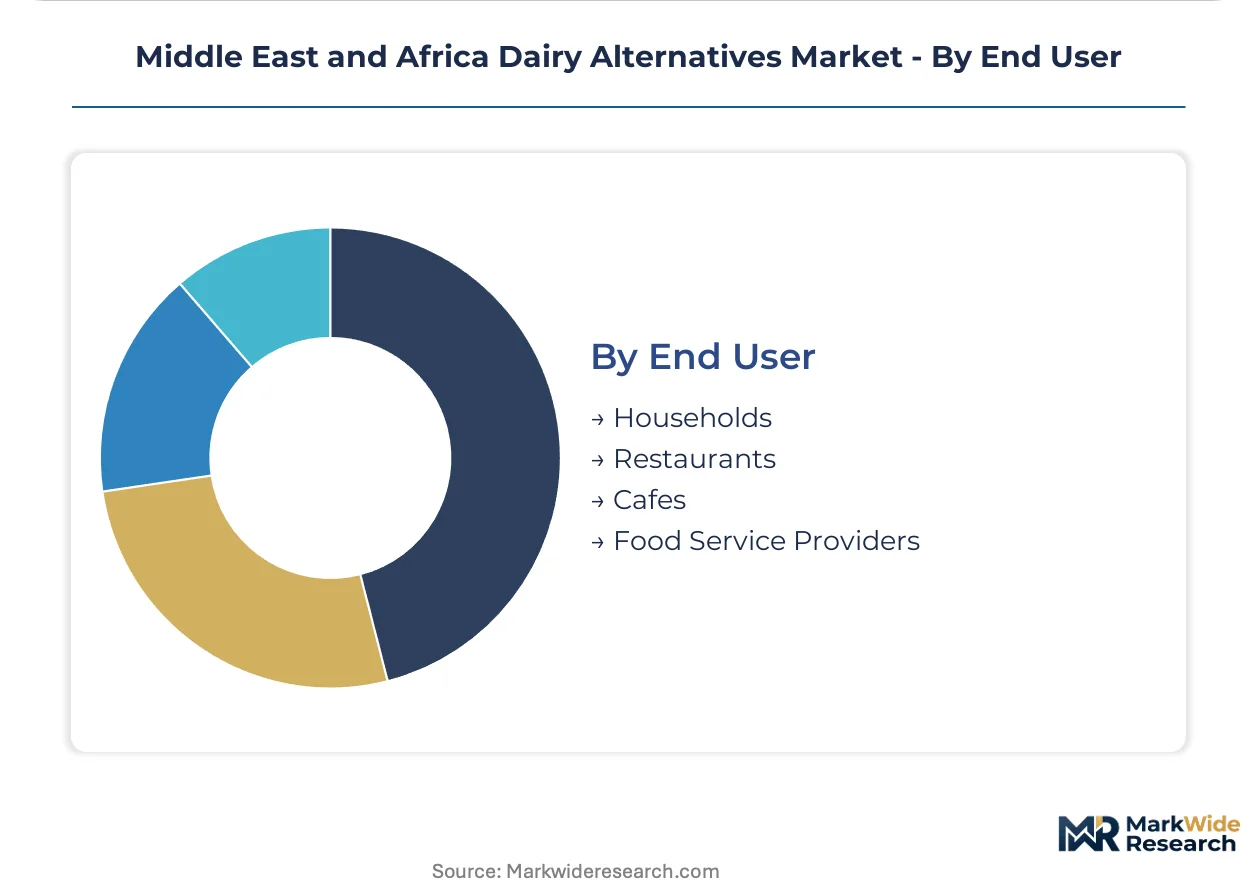
- Cafes:Frothing performance specifications from Dubai and Riyadh chains mandate barista-grade oat milk with minimum protein thresholds. Procurement consolidation reduces approved suppliers to two or three per beverage category.
- Food Service Providers:UAE hotel contracts specify almond milk suppliers by name, locking out unapproved alternatives from premium hospitality channels. Extended ambient shelf stability reduces refrigeration capital requirements.
- Households:Price-sensitive segments in Egypt and Sudan favor soy milk from local crushing operations.
- Restaurants:Casual dining chains in Casablanca and Cairo adopt high-pressure processed oat base for dual export and domestic supply.
Food Service Providers anchor premium volume. Cafes expand most quickly as specialty coffee culture deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's hospitality procurement networks command premium almond milk volumes across Gulf food service channels. Saudi Food and Drug Authority fortification mandates reshape formulation requirements from Riyadh to Jeddah. South Africa's Department of Health labeling standards trigger protein disclosure investments across Cape Town and Johannesburg retail corridors.
United Arab Emirates
Hotel food service contracts in Dubai specify oat and almond milk suppliers by name, locking procurement to approved vendors. Emirates Authority for Standardization and Metrology allergen thresholds constrain nut-derived beverage formulation flexibility. Abu Dhabi-based distribution hubs coordinate ambient-stable tetrapak logistics across Gulf Cooperation Council states.
Saudi Arabia
Almarai Company leverages existing dairy distribution networks to secure supermarket shelf space for plant-based lines. SFDA protein threshold requirements accelerate concentrated almond and oat base research investment. Riyadh cafe chains impose unified frothing performance specifications that compress supplier rosters.
South Africa
Urban health food stores in Cape Town and Johannesburg concentrate organic and fortified oat milk lines. Department of Health front-of-pack labeling regulations mandate protein content disclosure and sugar warning icons. Contract manufacturers adopt high-pressure processing systems to serve European export markets simultaneously.
Egypt
Nile-based soy crushing infrastructure supplies cost-competitive base to domestic bottlers and Ethiopian exporters. Sudanese oilseed processing capacity along the river extends supply reach into North African markets. Cairo formulation labs reconstitute California almond concentrate for regional distribution.
Morocco
Casablanca contract manufacturers process coconut milk from Southeast Asian copra for cultured product formulations. Reconstitution facilities import California kernel concentrate for regional almond beverage production. Rabat regulatory alignment with Gulf standards facilitates cross-border tetrapak distribution.
Middle East and Africa Dairy Alternatives Market Competitive Landscape
Global majors compete with regional champions across distribution infrastructure and formulation certification tiers. Market structure concentrates around dairy incumbents diversifying into plant-based portfolios and specialized oat protein extractors. Three archetypes dominate: Gulf dairy conglomerates with captive retail networks, European oat technology licensors, and California almond concentrate suppliers. Competitive moves center on backward integration into raw material sourcing and exclusive food service procurement contracts.
Within the dairy incumbent tier, Almarai Company and Danone SA exemplify distribution-led expansion strategies. Almarai leverages its Saudi supermarket shelf relationships to anchor plant-based line placement. Danone occupies a position as the fermented beverage specialist with North African taste profile adaptation. Among oat protein technology providers, Oatly Group AB and Blue Diamond Growers represent contrasting sourcing models—Nordic enzymatic processing versus California kernel concentrate supply.
| Leading Market Players |
|---|
| Alpro Middle East |
| Almarai Company |
| SADAFCO |
| Juhayna Food Industries |
| Danone SA |
| Oatly Group AB |
| Blue Diamond Growers |
| SunOpta Inc. |
| The Hain Celestial Group Inc |
| Others |
Supply & Pricing Matrix
SFDA fortification mandates governing protein thresholds in plant-based beverages gate qualified supply access and premium-tier pricing authorization across Gulf retail channels. Compliance investment separates shelf-stable tetrapak formats commanding hospitality procurement premiums from undifferentiated imports facing margin compression.
Pricing Analysis
Input-cost pass-through from California almond kernel concentrate and Nordic oat protein extract governs margin structures across Egyptian and Moroccan reconstitution facilities. Three-tier pricing structure across premium barista-certified, standard retail, and economy household tiers reflects certification grade and volume scale differentiation. Pricing pressure stems from Sudanese soy crushing infrastructure delivering cost-competitive base to price-sensitive North African segments. Household buyers in Egypt and Sudan exhibit highest price sensitivity, while UAE hotel food service providers accept premium positioning for named-supplier almond milk with extended ambient stability.
Supply Chain Analysis
Saudi Food and Drug Authority local-content alignment requirements and Emirates Authority for Standardization and Metrology traceability protocols are reshaping sourcing toward Gulf-adjacent processing hubs. Supply concentration centers on California for almond kernel concentrate, Nordic regions for enzymatic oat processing technology, and Sudan-Egypt Nile corridor for soy crushing infrastructure. Raw material dependencies encompass US West Coast almond orchards, Southeast Asian coconut copra, and European enzyme suppliers. Single-source vulnerability to California water-policy-driven kernel price volatility threatens Egyptian and Moroccan reconstitution economics. Distribution runs through Almarai's Saudi supermarket networks and Abu Dhabi-based ambient logistics hubs coordinating Gulf Cooperation Council tetrapak movement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between SFDA-compliant Gulf premium channels and Nile-based cost-optimized supply creates margin capture opportunities for players bridging both ecosystems.
For Market Incumbents: Extend barista-grade oat milk certification coverage to preempt food service procurement consolidation in Dubai and Riyadh cafe chains. Deepen backward integration into Sudanese soy crushing capacity to defend margin position against Nile-based cost competitors. Secure exclusive hotel food service contracts in the United Arab Emirates before supplier rosters compress to two approved vendors per beverage category. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms targeting expatriate vegan populations in Dubai and Johannesburg bypass supermarket shelf space barriers controlled by Almarai and Danone distribution networks. White-space concentration exists in precision-fermented oat yogurt formats tailored to North African taste profiles, where fermentation technology convergence has not yet scaled. Target South African urban health food stores with gluten-free oat lines ahead of Department of Health disclosure mandate enforcement. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Egyptian and Moroccan contract manufacturers because high-pressure processing technology adoption compresses facility footprints and enables dual export-domestic supply qualification. Five-to-ten-year viability hinges on capturing Gulf hospitality procurement contracts before channel consolidation completes. Target acquisition archetype: Casablanca or Cairo-based processors with SFDA-aligned certification pathways and existing European export relationships. Signal to watch: Emirates Authority for Standardization and Metrology protein threshold revisions that would disqualify unfortified imports and accelerate local manufacturing investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sudanese Soy Crushing | Nile-based oilseed processing anchors cost-competitive base supply for Egyptian and Ethiopian bottlers. |
| Barista-Grade Oat Milk Certification Investment | Frothing performance specifications from Dubai and Riyadh chains mandate qualified supplier status for volume access. |
| Precision Fermentation Technology Licensing | Oat protein fermentation combined with lactic acid cultures enables cultured yogurt formats for North African palates. |
| Direct-to-Consumer Platform Launch | Subscription models bypass import bottlenecks and Almarai-controlled supermarket shelf allocation for specialty fermented products. |
| High-Pressure Processing System Adoption | Casablanca and Cairo contract manufacturers unify pasteurization and texture modification to serve European export markets simultaneously. |
Research Methodology
Coverage spans Gulf Cooperation Council states, North Africa, and South Africa, with primary inputs from each region combining interviews with beverage formulation technologists, hotel food service procurement directors, supermarket category buyers, and regulatory affairs specialists at SFDA and Emirates Authority for Standardization and Metrology with secondary validation. Secondary sources include Saudi Food and Drug Authority fortification guidelines, South Africa Department of Health labeling regulations, customs records for almond kernel concentrate imports, and hospitality procurement contract disclosures. Bottom-up volume modeling triangulates against top-down market sizing across ingredient supply chains.
Granularity-level framing models product type at almond-oat-soy-coconut base resolution, formulation at organic-gluten-free-flavored-plain certification tiers, distribution channel at supermarket-online-health food-specialty store structure, and end user at cafe-food service-household-restaurant segmentation. CAGRs derive from volume trajectory analysis across the projection horizon. Industry-specific forecast inputs encompass cafe chain procurement consolidation timelines and SFDA protein threshold implementation schedules.
The model assumes a particular technology adoption path for enzymatic oat processing; alternative pathways for precision fermentation scale-up would alter the competitive outlook for cultured product formats. Forecasts reflect assumptions regarding SFDA enforcement consistency, California almond orchard water allocation stability, and Gulf hospitality sector procurement centralization velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
Non-Dairy Creamer Powder Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Yogurt Alternative Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Vegan Butter Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
United States Non-Dairy Milk Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
Non-Dairy Ice Cream Market