
 North America Food Fortifying Agents Market | 2026-2036
North America Food Fortifying Agents Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Fortifying Agents Market Analytics
Subscription-based micronutrient premix services is repositioning how fortifying agents reach mid-sized food manufacturers. Cargill Inc. leverages its integrated supply chain from crop sourcing to premix formulation to dominate bulk vitamin distribution. DSM Nutritional Products anchors the high-potency custom blend segment through specialized R&D facilities in North America. BASF SE differentiates via controlled-release microencapsulation technology that extends nutrient stability in processed foods.
Food fortifying agents comprise vitamins, minerals, amino acids, and probiotics added to processed foods to restore nutrients lost in manufacturing or enhance nutritional profiles beyond baseline levels; manufacturers typically achieve fortification through spray-drying, microencapsulation, or direct powder blending at concentrations governed by FDA food additive regulations. The vitamins segment leads in revenue contribution due to widespread incorporation into dairy and beverage applications, while probiotics represents the fastest-growing category driven by gut-health positioning in snacks and functional drinks. Powder formulations occupy the largest share of delivery formats, though liquid fortificants are gaining ground in ready-to-drink beverages where homogeneous dispersion proves critical.
The FDA governs nutrient content claims and fortification levels through 21 CFR standards, while Health Canada and PMRA coordinate cross-border ingredient approvals that shape product formulations for North American distribution. USDA dietary guidelines and the FDA's voluntary sodium reduction targets indirectly stimulate reformulation activity that incorporates potassium and magnesium fortificants. Stakeholders must monitor evolving bioequivalence standards for novel nutrient forms and prepare for potential harmonization pressures between US and Canadian regulatory frameworks.
Market Dynamics
Biofortification technology advances and FDA's updated Nutrition Facts labeling requirements are compressing product development cycles while forcing manufacturers to reformulate across dairy and beverage portfolios simultaneously.
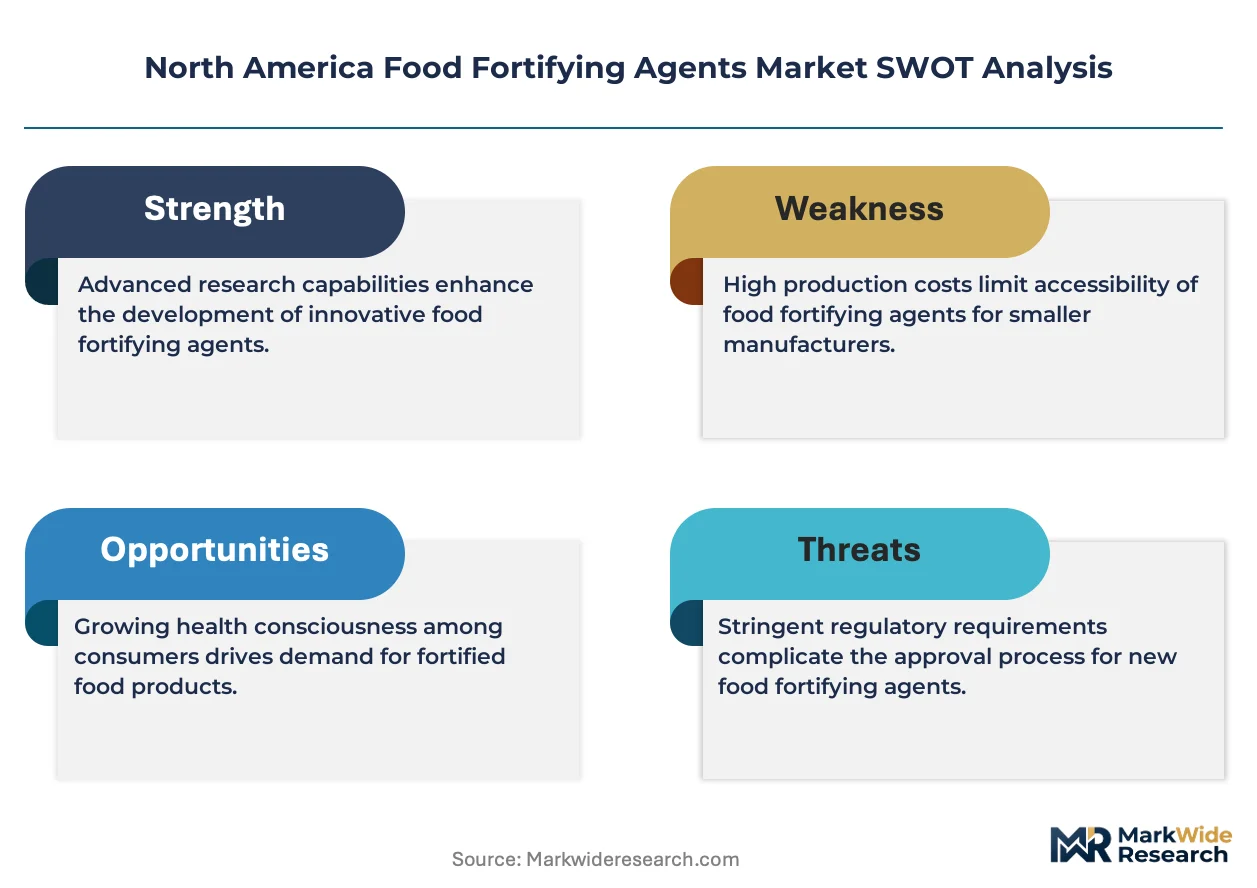
Growth Catalysts
- USDA Dietary Guidelines:Voluntary sodium reduction targets indirectly stimulate potassium and magnesium fortificant incorporation into processed foods.
- California Functional Food Cluster:Concentrated R&D infrastructure accelerates probiotic strain development for gut-health positioning in snacks.
- Microencapsulation:Controlled-release nutrient stability technology enables extended shelf-life claims in ready-to-drink beverages.
Market Restraints
- Input Cost Volatility:Vitamin premix raw material prices fluctuate with global feedstock markets, squeezing mid-sized manufacturer margins.
- Supply Concentration Risk:Bulk vitamin distribution concentrates among integrated agribusiness conglomerates with captive crop sourcing.
- Regulatory Friction:Cross-border ingredient approval coordination between FDA and Health Canada delays unified North American product launches.
Strategic Opportunities
- Midwest Grain-Processing Corridor:Underexploited amino acid fortification capacity exists across wheat and corn derivative facilities.
- Subscription Premix Services:Direct-to-manufacturer micronutrient delivery models bypass traditional distributor markups for regional processors.
- Canadian Regulatory Tailwind:Potential US-Canada harmonization pressures could streamline dual-approval pathways for novel nutrient forms.
Industry Challenges
- Bioequivalence Validation:Novel nutrient forms require expensive clinical substantiation before FDA food additive approval.
- Homogeneous Dispersion Engineering:Liquid fortificant integration demands capital-intensive mixing infrastructure upgrades at beverage plants.
- Microbiome Strain IP:Proprietary probiotic licensing complexity fragments supplier relationships and inflates royalty burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Fortifying Agents Market |
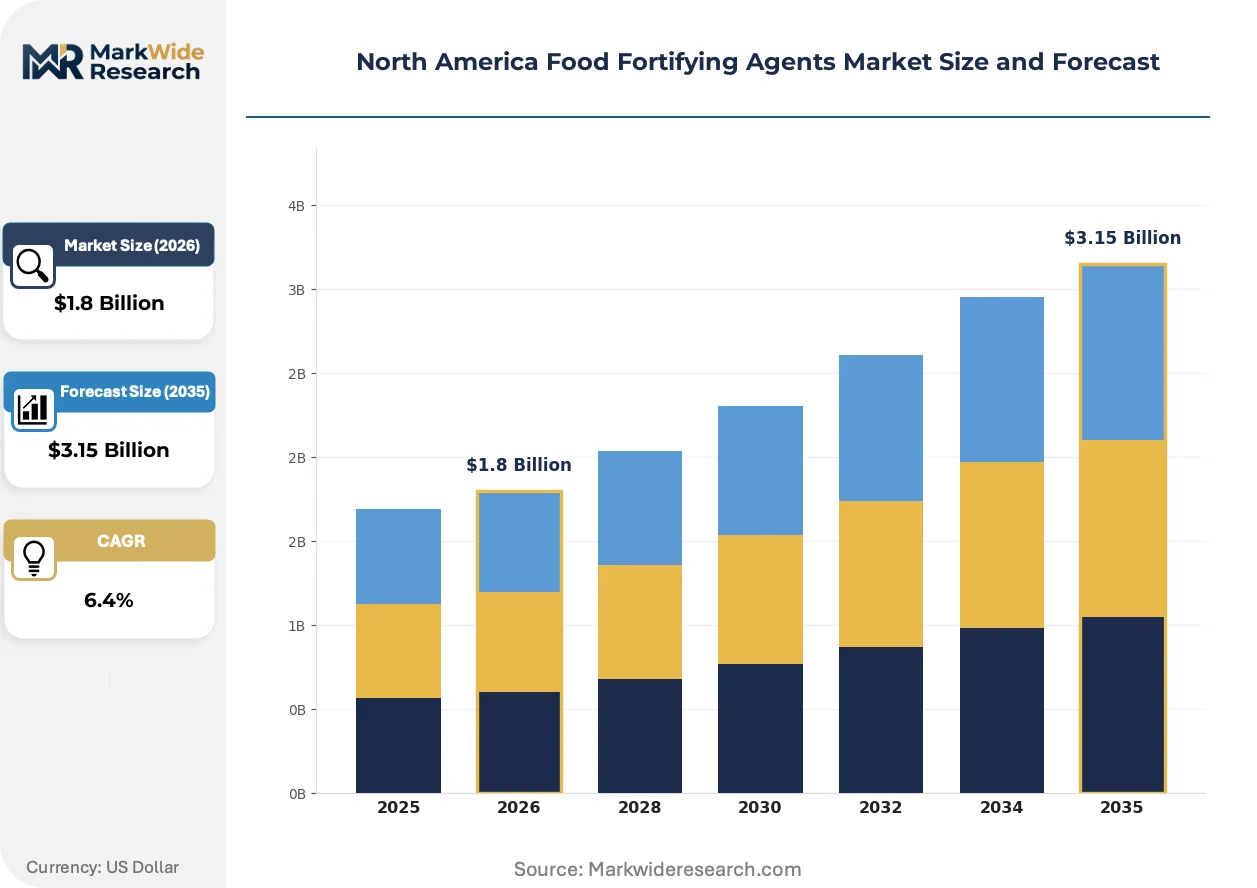
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Probiotics Application: Dairy Products, Beverages, Baked Goods, Snacks End User: Household, Food Industry, Healthcare, Fitness Centers Form: Powders, Liquids, Granules, Tablets |
| Companies Covered | Cargill Inc., DuPont de Nemours, Inc., Archer Daniels Midland Company, Chr. Hansen Holding A/S, Ingredion Inc., BASF SE, DSM Nutritional Products, Kerry Group, Tate & Lyle, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Fortifying Agents Market Evolving Landscape
Automation of nutrient delivery systems and evolving claims frameworks are compressing the gap between formulation science and commercial deployment across North American food manufacturing.
Robotic precision dosing systems are automating microencapsulated vitamin dispersion in high-speed dairy processing lines. Mid-sized cheese and yogurt manufacturers in Wisconsin and New York are adopting these systems faster than national brands. This automation is automating batch-to-batch consistency verification while reducing labor-dependent quality control checkpoints.
Health Canada's coordinated ingredient approval protocols with PMRA are tightening novel nutrient form substantiation requirements. The industrial consequence forces simultaneous US-Canada dossier preparation, extending pre-market timelines by 8-14 months. Probiotic and bioactive peptide categories face the heaviest documentation burdens, with applicants consolidating regulatory affairs functions in Toronto.
Health-conscious consumers now prioritize clean-label fortification with recognizable ingredient sources over synthetic vitamin complexes. Direct-to-consumer functional beverage brands in Colorado and Oregon exploit this preference, displacing legacy CPG loyalty. This shift concentrates demand pull in Pacific Coast metropolitan corridors before diffusing inland.
North America Food Fortifying Agents Market Segmentation
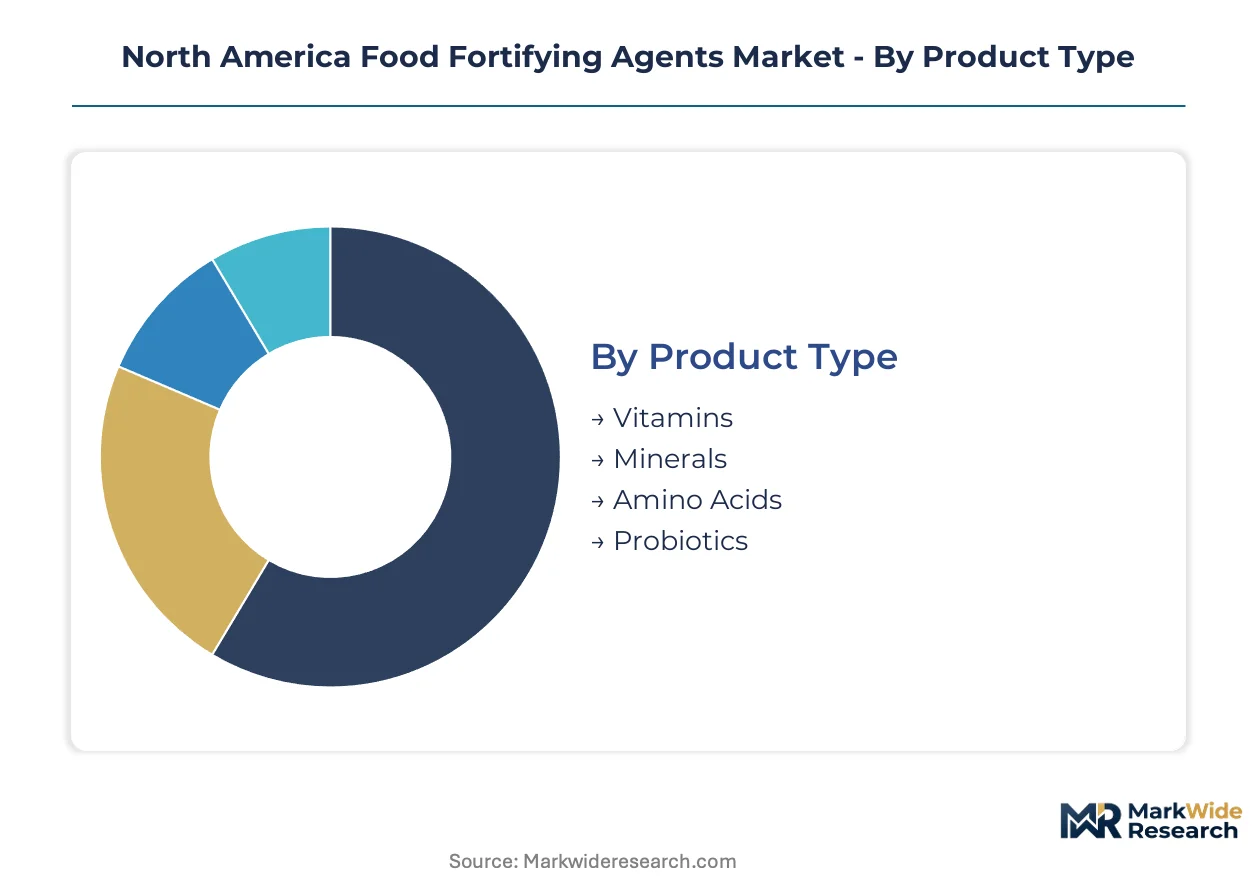
Segmentation in the North America Food Fortifying Agents Market reveals divergent margin profiles between commodity premix bulk buyers and precision-dose specialty formulators. Understanding these splits enables suppliers to calibrate R&D investment and distribution channel strategy.
Product Type:
Vitamins dominate tonnage flows while probiotics command per-kilogram premiums that reshape portfolio economics.
- Vitamins:Encompass retinol, ascorbic acid, tocopherols, and B-complex compounds standardized for thermal stability in UHT dairy processing. Demand concentrates across Wisconsin cheese manufacturing corridors where robotic dosing systems verify homogeneous dispersion in high-speed production lines.
- Probiotics:Live microbial cultures including Lactobacillus and Bifidobacterium strains require cold-chain integrity and microencapsulation for gastric survival. California functional food clusters drive strain development investment as gut-health positioning displaces legacy synthetic vitamin claims in Pacific Coast metropolitan markets.
- Minerals:Iron, zinc, calcium, and magnesium salts restore micronutrient density in refined grain derivatives.
- Amino Acids:Lysine, methionine, and tryptophan fortification addresses protein quality gaps in plant-forward formulations.
Today's leader: Vitamins. Tomorrow's challenger: Probiotics.
Application:
Dairy and beverage channels absorb the highest fortificant volumes, though snack applications exhibit steepest expansion trajectory as clean-label positioning penetrates convenience food categories.
- Dairy Products:Milk, yogurt, and cheese matrices leverage fat-soluble vitamin dispersion and probiotic fermentation integration. FDA's updated Nutrition Facts labeling requirements compress reformulation cycles across California and Midwest processing facilities simultaneously.
- Beverages:Ready-to-drink functional drinks demand liquid fortificant formats with homogeneous suspension engineering. Colorado and Oregon direct-to-consumer brands exploit clean-label preferences before demand diffuses inland from Pacific Coast corridors.
- Baked Goods:Flour enrichment and bread fortification restore thiamine, riboflavin, niacin, and folic acid lost in milling.
- Snacks:Extruded and puffed products incorporate vitamin-mineral premixes for child nutrition positioning.
Dairy anchors current procurement volumes. Beverages reshape supplier specifications fastest.
End User:
Food industry buyers drive bulk premix economics while healthcare channel specifications elevate bioequivalence documentation burdens.
- Food Industry:Processed food manufacturers purchase standardized vitamin-mineral premixes through subscription delivery models that bypass traditional distributor markups. Mid-sized regional processors in the Midwest grain-processing corridor adopt these services faster than national brands.
- Healthcare:Clinical nutrition and medical food applications require FDA food additive approval with expensive substantiation for novel nutrient forms. Toronto-based regulatory affairs functions consolidate to manage simultaneous US-Canada dossier preparation.
- Household:Direct consumer purchases of fortified staples and supplements.
- Fitness Centers:Sports nutrition and recovery beverage dispensing drives concentrated amino acid demand.
Food industry procurement sets baseline pricing. Healthcare compliance costs filter supplier participation.
Form:
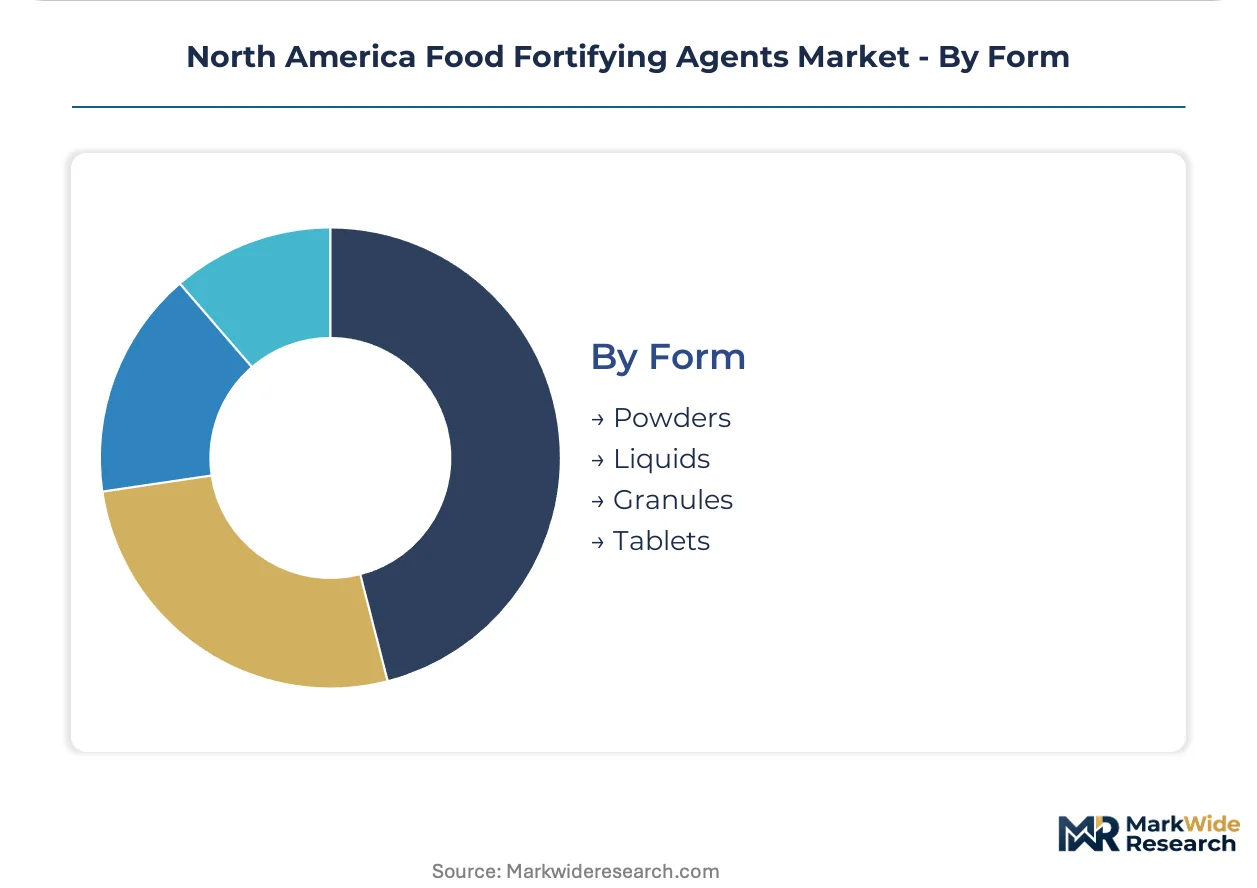
Powder formulations dominate current manufacturing infrastructure while liquid fortificants force capital-intensive mixing upgrades.
- Powders:Spray-dried and agglomerated formats enable direct blending into dry mixes with established dispersion protocols. Wisconsin and New York mid-sized cheese and yogurt manufacturers automate batch-to-batch consistency verification through robotic precision dosing systems.
- Liquids:Oil-soluble vitamin suspensions and aqueous probiotic concentrates require homogeneous dispersion engineering in ready-to-drink beverage plants. Capital-intensive mixing infrastructure upgrades constrain adoption to national brands with balance sheet capacity.
- Granules:Intermediate particle size for controlled-release applications in baked goods.
- Tablets:Compressed nutrient formats for healthcare and fitness center dispensing channels.
Powder retains manufacturing share. Liquid gains ground where dispersion technology investments amortize across volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's regulatory coordination with the United States creates faster approval pathways than Mexico's fragmented oversight, though all three North American markets concentrate fortificant demand in distinct industrial corridors.
United States
FDA's updated Nutrition Facts labeling requirements and voluntary sodium reduction targets drive potassium and magnesium fortificant incorporation. USDA dietary guidelines indirectly stimulate reformulation across dairy and grain-processing facilities. California's functional food cluster anchors probiotic strain development, while Wisconsin's cheese manufacturing corridors deploy robotic precision dosing systems for vitamin dispersion.
Canada
Health Canada coordinates ingredient approvals with PMRA, tightening novel nutrient form substantiation requirements for cross-border product launches. Simultaneous US-Canada dossier preparation extends pre-market timelines by 8-14 months. Toronto-based regulatory affairs functions consolidate to manage documentation burdens for probiotic and bioactive peptide categories.
Mexico
NOM-051 labeling regulations and PROFECO consumer protection standards shape fortification compliance for imported processed foods. Domestic wheat and corn derivative facilities underexploit amino acid fortification capacity. The Bajío Region's grain-processing infrastructure remains concentrated in traditional milling without precision nutrient integration.
North America Food Fortifying Agents Market Competitive Landscape
Top-tier vendors anchor bulk vitamin distribution through integrated supply chains, while mid-sized regional processors access fortificants via subscription premix services that bypass traditional distributor markups. The vendor base stratifies across three tiers: integrated agribusiness conglomerates with captive crop sourcing, specialized R&D-driven custom blenders, and regional premix formulators serving niche applications. Dominant competitive moves include backward integration into raw material sourcing and technology licensing for controlled-release microencapsulation.
Among integrated agribusiness conglomerates, Cargill Inc. exemplifies upstream control over supply chains from crop sourcing to premix formulation. DSM Nutritional Products and BASF SE occupy positions within the high-potency custom blend and microencapsulation technology archetypes respectively. These three anchors represent divergent strategic vectors: captive supply integration, specialized R&D facility investment, and controlled-release nutrient stability engineering.
| Leading Market Players |
|---|
| Cargill Inc. |
| DuPont de Nemours, Inc. |
| Archer Daniels Midland Company |
| Chr. Hansen Holding A/S |
| Ingredion Inc. |
| BASF SE |
| DSM Nutritional Products |
| Kerry Group |
| Tate & Lyle |
| Others |
Value Network & Pricing Analysis
Mid-sized regional processors in the Midwest grain-processing corridor concentrate procurement volume through subscription premix services, compressing traditional distributor markups and forcing a shift toward contract-based long-term offtake pricing with volume-tier discounts.
Pricing Analysis
Capacity additions in Canada's prairie provinces are reshaping price floors for amino acid fortificants as domestic wheat derivative facilities expand precision nutrient integration. Three-tier pricing structure across premium custom blends, standard premixes, and economy bulk vitamins differentiates by certification grade and R&D customization level. Cost compression in economy vitamin tiers is intensifying because global feedstock volatility squeezes raw material costs. National brands with captive supply chains exhibit lowest price sensitivity, while mid-sized dairy processors in Wisconsin and New York face acute margin pressure from input cost swings.
Supply Chain Analysis
FDA food additive approval and Health Canada-PMRA coordination requirements gate supplier participation, extending qualification timelines for novel nutrient forms. Supply concentrates in the United States, Canada, and select European sources for high-potency custom blends. Raw material dependencies include corn-derived feedstocks for vitamin precursors, specialized probiotic culture banks, and marine-sourced omega-3 concentrates. Single-source vulnerability in bulk vitamin distribution among integrated agribusiness conglomerates creates concentration risk. Distribution runs through direct-to-manufacturer subscription models and traditional chemical distributor networks serving regional processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on automation-driven cost reduction in precision dosing systems and the ongoing premium-tier shift toward microencapsulated probiotics with extended stability claims.
For Market Incumbents: To counter subscription-based premix services eroding traditional distributor relationships, Cargill and DSM should deepen backward integration into captive crop sourcing for vitamin precursors while deploying robotic precision dosing technology licensing to lock in mid-sized processor switching costs. For New Entrants and Emerging Players: Capture the underexploited amino acid fortification capacity across Mexico's Bajío Region grain-processing infrastructure, where NOM-051 compliance requirements for imported foods create demand for localized premix formulation services with cross-border regulatory expertise. For Investors and Strategic Acquirers: Integrated agribusiness conglomerates are the most active acquirer in this space, targeting specialized microencapsulation technology firms and probiotic strain libraries. Long-term viability favors assets with dual US-Canada regulatory dossier capabilities. The signal to watch is Health Canada-PMRA harmonization momentum accelerating novel nutrient form approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Crop Sourcing | Cargill's control over corn and soybean supply secures vitamin precursor cost stability against feedstock volatility. |
| Microencapsulation Technology Licensing | BASF's controlled-release nutrient stability patents extend shelf-life claims in California functional beverage applications. |
| Subscription Premix Service Launch | Direct-to-manufacturer models bypass traditional distributor markups for Midwest grain-processing corridor clients. |
| Robotic Precision Dosing Deployment | Wisconsin cheese manufacturers automate batch-to-batch consistency verification in high-speed production lines. |
| Dual US-Canada Regulatory Dossier Consolidation | Toronto-based regulatory affairs functions manage simultaneous FDA and Health Canada approval pathways for probiotics. |
Research Methodology
Multiple input streams — executive interviews with premix formulation directors, procurement leads at Midwest dairy processors, regulatory affairs specialists managing Health Canada-PMRA coordination, and distribution channel partners — were reconciled against FDA 21 CFR filings, USDA dietary guideline documentation, and customs trade data for vitamin and amino acid imports. Bottom-up volume estimates from facility-level production data and top-down market sizing from trade flow analysis were cross-validated.
Data-stream reconciliation across product type, application channel, end-user vertical, and geographic production cluster dimensions produced volume and value trajectories across the projection horizon. CAGRs were derived from trend extrapolation of robotic automation adoption rates, probiotic strain development investment flows, and reformulation cycle compression under FDA labeling updates. Industry-specific forecast inputs incorporated biofortification technology maturity curves and subscription service penetration rates among mid-sized processors.
Regulatory harmonization delays, probiotic strain IP fragmentation, and feedstock commodity volatility are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about approval timeline standardization and automation capex amortization schedules. A model refresh is warranted upon material change in FDA-Health Canada coordination protocols or breakthrough bioequivalence validation methods for novel nutrient forms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Tocopherols Market
Vitamin Fortified
Fortified Juices Market
Vitamin Fortified
Essential Micronutrients Market
Vitamin Fortified
Pantothenic Acid Market
Vitamin Fortified
Esterified Vitamins Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Food Fortification Market
Vitamin Fortified
Global Quercetin Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Vitamin B Complex Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Calcium-Fortified Cereals Market