
 Almond Milk Market | 2026-2036
Almond Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Almond Milk Market Intelligence
EU Green Deal nutrition-labeling standards is rebalancing the cost-of-entry calculus for European almond milk suppliers, forcing reformulation investments that smaller brands struggle to fund. Blue Diamond Growers anchors its position through captive almond orchards in California's Central Valley. Danone S.A. leverages its refrigerated distribution network to dominate European retail channels. Califia Farms LLC differentiates through barista-specific formulations that command premium placement in specialty coffee.
Almond milk is an aqueous emulsion produced by blending blanched almonds with water, typically containing two to twelve percent almond solids, followed by homogenization and ultra-high temperature pasteurization to achieve microbiological stability and shelf life extension. Its primary commercial purpose is to serve as a dairy milk alternative in beverages, cereals, and food manufacturing where lactose intolerance, vegan dietary preferences, or sustainability concerns drive substitution. Unsweetened variants now lead volume in North American supermarkets as sugar-reduction mandates from health regulators reshape formulation priorities. Tetra Packs sustain the largest packaging share due to ambient distribution economics, though glass bottles capture disproportionate margin in premium health store channels. Online distribution is accelerating fastest among direct-to-consumer subscription models targeting repeat pantry replenishment.
FDA nutrition-labeling requirements and USDA organic certification standards govern product claims and market access in the United States, while EFSA health claim regulations shape permissible marketing language across European Union member states. These frameworks elevate compliance spending but simultaneously create defensible moats for certified incumbents against unverified imports. Stakeholders must monitor evolving protein-fortification standards that could redefine nutritional parity claims between plant-based and dairy categories.
Market Dynamics
Almond milk supply chains cluster around California's Central Valley processing infrastructure, where captive orchard ownership and co-located manufacturing create cost advantages that reshape competitive entry barriers for new suppliers.
Growth Catalysts
- EU Green Deal nutrition-labeling standards:Mandatory front-of-pack labeling reforms in European Union member states accelerate reformulation toward unsweetened variants, expanding addressable consumer base for compliant brands.
- Specialty coffee channel expansion:North American cafe chains now standardize almond milk as default dairy alternative, embedding the ingredient in beverage preparation workflows and training protocols.
- Ultra-high temperature pasteurization:This processing technology extends ambient shelf stability without refrigeration infrastructure, unlocking distribution into convenience retail and foodservice channels previously inaccessible to chilled alternatives.
Market Restraints
- California water allocation volatility:Almond cultivation depends on Central Valley surface water rights subject to drought-driven curtailments, creating input cost instability that propagates through processing contracts.
- Protein fortification technical ceiling:Current enzymatic hydrolysis and blending methods cannot achieve dairy-equivalent protein concentrations without sensory degradation, limiting nutritional parity claims in regulated jurisdictions.
- Single-origin supply concentration:Eighty percent of global almond supply originates from California's Central Valley, exposing downstream manufacturers to geographic climate risk and pollinator colony collapse pressures.
Strategic Opportunities
- Australian almond cultivation expansion:Riverina and Sunraysia regions offer untapped orchard development with lower water stress profiles, enabling supply diversification for brands seeking provenance differentiation.
- Direct-to-consumer subscription replenishment:Pantry-automation platforms bypass traditional retail slotting fees, capturing recurring revenue streams and first-party consumption data for formulation optimization.
- USDA organic certification acceleration:Federal organic standards create premium price realization in mass retail channels where conventional almond milk faces commoditization pressure.
Industry Challenges
- Almond processing engineer talent scarcity:Specialized expertise in emulsion stability and aseptic packaging design concentrates among legacy dairy equipment suppliers, constraining capacity expansion timelines.
- Multi-jurisdiction label compliance synchronization:Simultaneous FDA, EFSA, and Health Canada claim substantiation requires parallel regulatory submissions that delay product launches by 8-14 months.
- Homogenization equipment lead times:High-pressure processing unit manufacturers face order backlogs extending 18-24 months, freezing capacity decisions for mid-scale entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Almond Milk Market |
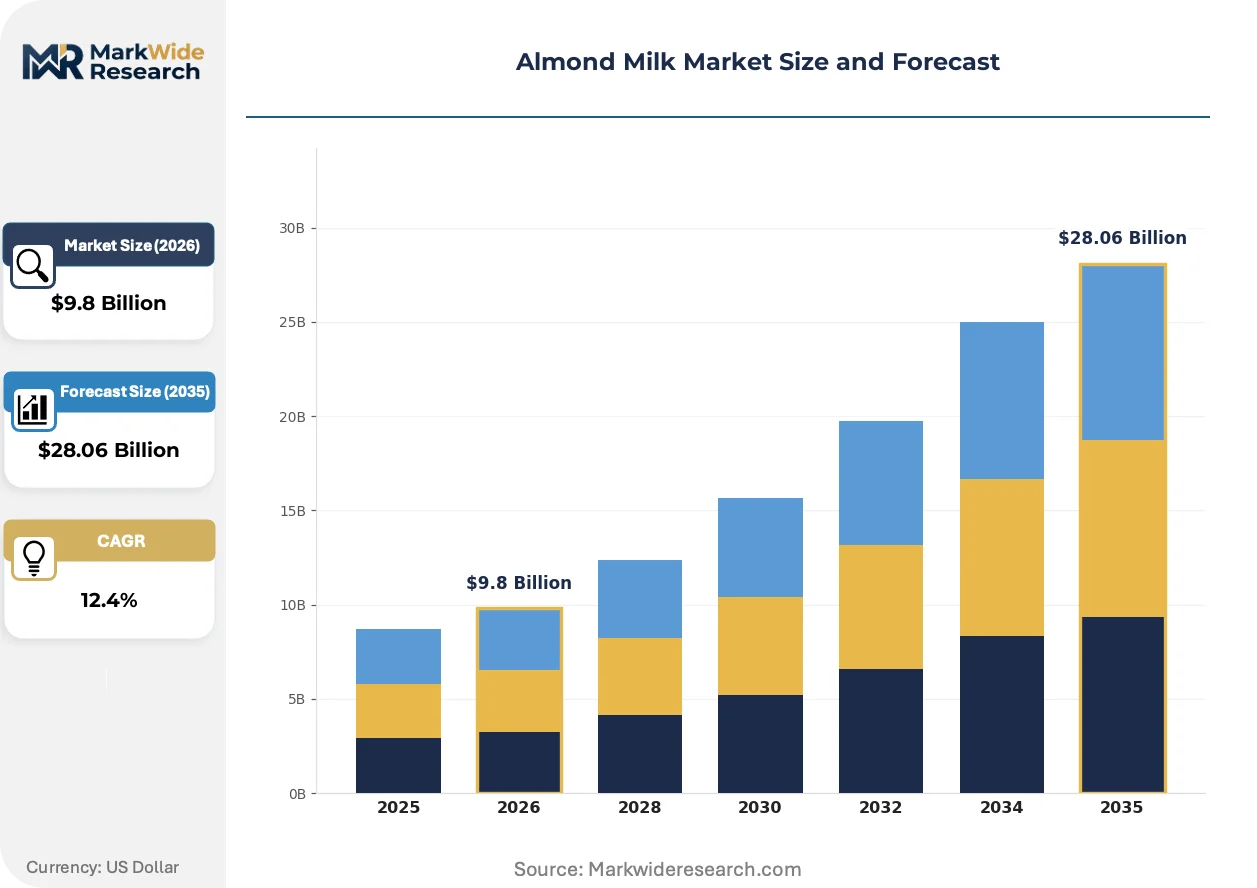
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $28.06 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsweetened, Sweetened, Vanilla-flavored, Chocolate Packaging Type: Tetra Packs, Glass Bottles, Boxes, Pouches Distribution Channel: Online, Supermarkets, Health Stores, Specialty Stores End User: Retail Consumers, Food Service, Bakeries, Cafes |
| Companies Covered | Nestlé S.A., SunOpta, Inc., Blue Diamond Growers, Vitasoy International Holdings Limited, Oatly Group AB, Califia Farms LLC, Hain Celestial Group, Inc., Campbell Soup Company, Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Almond Milk Market Strategic Shifts & Innovations
Formulation science and packaging engineering are converging to extend shelf life while compressing clean-label ingredient lists, reshaping how almond milk competes against oat and soy alternatives in retail and foodservice channels.
High-pressure homogenization is consolidating control over emulsion stability in premium almond milk production. Barista-focused brands adopt this equipment to achieve microfoam performance matching dairy, compressing the quality gap that previously limited specialty coffee penetration. The technology enables reduction of stabilizer additives, supporting clean-label positioning in European markets where EFSA scrutiny of hydrocolloids is intensifying.
REACH chemical safety registrations now govern food-contact materials in Tetra Pack laminates across European Union distribution, forcing suppliers to reformulate barrier layers or face market exclusion. This regulatory pressure accelerates migration toward aseptic glass and recyclable PET alternatives in German and French retail channels. Brands with pre-validated packaging portfolios capture shelf space as competitors await compliance certification.
Coffee shop procurement committees now mandate almond milk with specific protein content and foaming performance metrics, displacing undifferentiated commodity suppliers from specialty beverage programs. This specification-driven purchasing concentrates volume among three to four formulation specialists with dedicated barista training support. The shift is most visible in Pacific Northwest and Nordic markets where latte art competitions drive ingredient standardization.
Almond Milk Market Segmentation
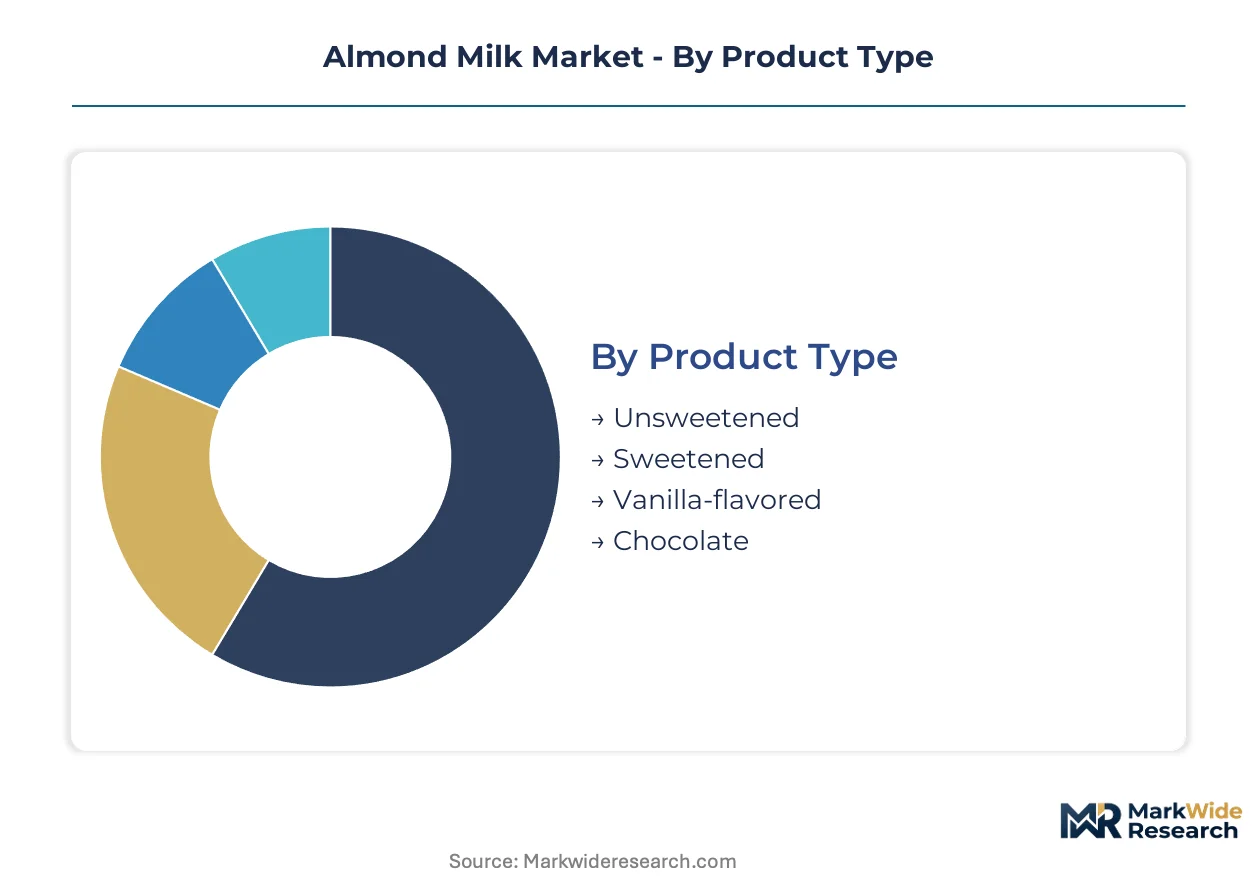
Almond milk segmentation reveals how formulation specifications, packaging engineering, and channel economics partition value capture across the dairy alternatives value chain. Product type and packaging format decisions cascade through manufacturing equipment requirements, cold chain investments, and retail margin structures.
Product Type:
Formulation science distinguishes segments through sugar content, flavor systems, and clean-label positioning that reshape procurement criteria for retail buyers and foodservice operators.
- Unsweetened:Zero-added-sugar formulations containing two to twelve percent almond solids with no caloric sweeteners. North American supermarket chains now mandate this specification as default placement following FDA nutrition-labeling guidance and state-level sugar-reduction mandates. EFSA health claim regulations in European Union member states accelerate comparable reformulation timelines.
- Sweetened:Cane sugar or agave-sweetened variants typically carrying eight to twelve grams added sugar per serving. Demand concentrates in conventional grocery channels serving price-sensitive households and older demographic segments with persistent taste preferences for dairy milk sweetness profiles.
- Vanilla-flavored:Natural or artificial vanilla extract additions targeting breakfast cereal pairing occasions and smoothie preparation. This segment captures premium shelf positioning in health store channels where flavor differentiation justifies price markup over plain variants.
- Chocolate:Cocoa powder or chocolate flavor systems positioned as post-workout recovery beverages and children's lunchbox alternatives. Formulation complexity around emulsion stability with cocoa lipids constrains supplier participation to processors with dedicated flavor application expertise.
Unsweetened leads on scale; vanilla-flavored gains share fastest as specialty coffee channel specifications proliferate.
Packaging Type:
Material selection and aseptic engineering determine distribution reach, shelf life extension, and sustainability credentials that increasingly gate retail access in regulated European markets.
- Tetra Packs:Multilayer carton laminates with aluminum oxygen barriers enabling twelve-month ambient shelf stability without refrigeration. REACH chemical safety registrations now govern food-contact materials across European Union distribution, forcing barrier layer reformulation or market exclusion for non-compliant suppliers.
- Glass Bottles:Returnable and recyclable formats capturing disproportionate margin in premium health store channels and zero-waste retail concepts. German and French retail channels accelerate migration toward aseptic glass alternatives as Tetra Pack compliance certification timelines extend.
- Boxes:Gable-top cartons for chilled distribution with shorter shelf life and lower barrier protection. This format concentrates in private-label programs and economy-tier positioning where packaging cost minimization outweighs shelf stability requirements.
- Pouches:Flexible film formats for single-serve and on-the-go consumption occasions. Limited adoption due to inferior emulsion protection and consumer perception challenges around premium positioning for plant-based alternatives.
Tetra Packs dominate volume throughput; glass bottles command the steepest expansion trajectory in sustainability-regulated European markets.
Distribution Channel:
Channel economics separate recurring pantry replenishment models from impulse-driven trial purchases, with diverging margin structures and data capture capabilities.
- Online:Direct-to-consumer subscription platforms and third-party marketplace fulfillment. Pantry-automation platforms bypass traditional retail slotting fees, capturing recurring revenue streams and first-party consumption data for formulation optimization.
- Supermarkets:Mass retail chains with refrigerated dairy case and ambient shelf placement. Unsweetened variants now lead volume in North American supermarkets as sugar-reduction mandates from health regulators reshape formulation priorities.
- Health Stores:Specialty retailers with curated clean-label assortments and premium price realization. Glass bottles capture disproportionate margin in this channel where packaging sustainability and ingredient transparency command shopper loyalty.
- Specialty Stores:Gourmet food retailers and ethnic grocery formats with imported or artisan-positioned offerings. Limited penetration due to price positioning challenges against established dairy alternatives and oat milk incumbents.
Supermarkets anchor volume concentration; online subscription models expand most quickly as replenishment automation penetrates household purchasing patterns.
End User:
Application-specific performance requirements create specification-driven purchasing that concentrates volume among formulation specialists with technical service capabilities.
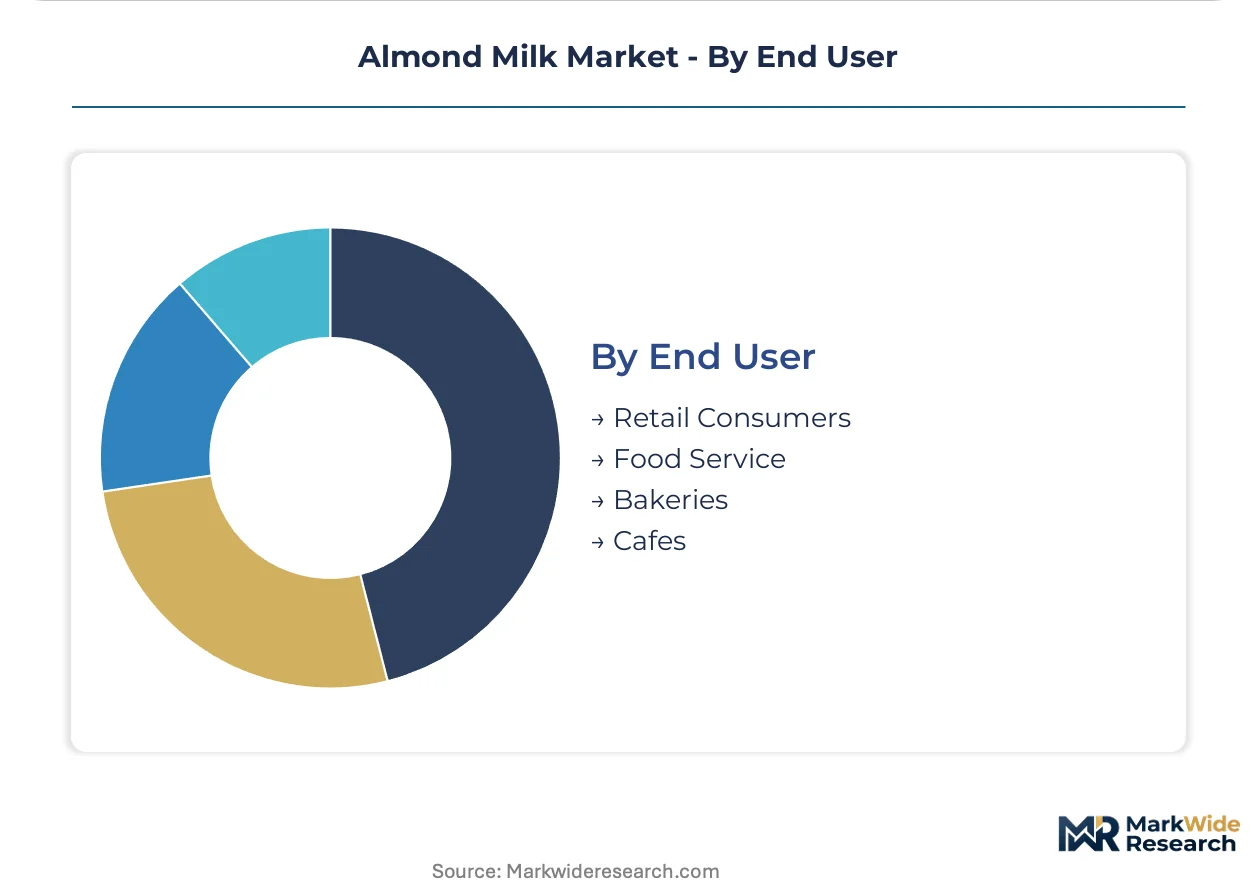
- Retail Consumers:Household purchasers for beverage consumption, cereal preparation, and home cooking applications. This segment concentrates demand in unsweetened variants as sugar-reduction mandates reshape formulation priorities across North American and European regulatory jurisdictions.
- Food Service:Institutional catering and restaurant chains with bulk procurement and standardized recipe requirements. Ultra-high temperature pasteurization extends ambient shelf stability without refrigeration infrastructure, unlocking distribution into convenience retail and foodservice channels previously inaccessible to chilled alternatives.
- Bakeries:Commercial baking operations requiring specific fat content and emulsion behavior for dough conditioning and moisture retention. Technical specification requirements limit supplier qualification to processors with dedicated foodservice technical service teams.
- Cafes:Specialty coffee shops and cafe chains with barista-specific foaming and microfoam performance requirements. Coffee shop procurement committees now mandate almond milk with specific protein content and foaming performance metrics, displacing undifferentiated commodity suppliers from specialty beverage programs.
Retail consumers generate absolute volume; cafes drive the fastest specification evolution as latte art competitions and specialty coffee culture standardize ingredient requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley employs the largest concentration of almond processing engineers and aseptic packaging specialists in the global dairy alternatives industry. This talent density anchors formulation innovation and equipment optimization for plant-based beverage manufacturing. Regional supply chains benefit from co-located orchard operations and manufacturing infrastructure.
United States
FDA nutrition-labeling requirements and USDA organic certification standards govern product claims and market access. California's Central Valley processing clusters sit adjacent to major dairy alternatives manufacturing facilities, creating cost advantages that reshape competitive entry barriers. Water allocation volatility from drought-driven curtailments propagates input cost instability through processing contracts.
Germany
REACH chemical safety registrations now govern food-contact materials in Tetra Pack laminates across European Union distribution. German retail channels accelerate migration toward aseptic glass and recyclable PET alternatives as compliance certification timelines extend. Berlin-Brandenburg logistics hubs coordinate distribution into Nordic and Eastern European markets.
France
EFSA health claim regulations shape permissible marketing language and accelerate reformulation toward unsweetened variants. Parisian specialty coffee chains now standardize almond milk as default dairy alternative, embedding the ingredient in beverage preparation workflows. Île-de-France retail consolidation concentrates procurement among three to four formulation specialists.
Australia
Riverina and Sunraysia regions offer untapped orchard development with lower water stress profiles than California. The country's national food safety regulator enforces strict import substitution policies that favor domestic processing investment. Melbourne and Sydney cafe cultures drive specification evolution through latte art competitions and barista training standardization.
United Kingdom
Sugar-reduction mandates from health regulators reshape formulation priorities across supermarket chains. London's specialty coffee density embeds almond milk in beverage preparation protocols at scale. Midlands distribution infrastructure supports ambient shelf-stable product penetration into convenience retail channels previously inaccessible to chilled alternatives.
Almond Milk Market Key Industry Players
The competitive structure tilts toward orchard-integrated processors with captive supply control. Three to four formulation specialists concentrate volume through barista-specific technical service capabilities. Strategic moves center on Australian supply diversification and direct-to-consumer subscription platform development. Equipment order backlogs extending 18-24 months freeze capacity decisions for mid-scale entrants.
Among orchard-integrated processors, Blue Diamond Growers anchors the captive supply archetype through Central Valley orchard ownership. Danone S.A. exemplifies the refrigerated distribution specialist leveraging European retail channel dominance. Califia Farms LLC occupies the barista-focused formulation tier with premium placement in specialty coffee channels. These three represent distinct competitive vectors rather than overlapping market contestation.
| Leading Market Players |
|---|
| Nestlé S.A. |
| SunOpta, Inc. |
| Blue Diamond Growers |
| Vitasoy International Holdings Limited |
| Oatly Group AB |
| Califia Farms LLC |
| Hain Celestial Group, Inc. |
| Campbell Soup Company |
| Danone S.A. |
| Others |
Cost & Logistics Intelligence
EU Green Deal nutrition-labeling standards are forcing European almond milk suppliers into costly reformulation investments that smaller brands cannot fund, compressing margins and concentrating pricing power among certified incumbents with compliant portfolios.
Pricing Analysis
Barista-specific technical service bundles command premium positioning against commodity base products. Three-tier pricing structure across premium, standard, and economy levels separates formulation specialists with foaming performance guarantees from private-label alternatives. Price differentiation hinges on USDA organic certification and refrigerated distribution network access. Cost compression in economy tiers is intensifying because Central Valley water allocation volatility propagates through processing contracts.
Supply Chain Analysis
Direct-to-retail channels handle subscription replenishment demand while foodservice distributors manage bulk institutional procurement. Eighty percent of global almond supply draws from California's Central Valley, with secondary sourcing from Australia's Riverina and Sunraysia regions. Raw material dependencies center on blanched almond solids, high-pressure homogenization equipment, and aseptic packaging laminates. Single-origin geographic concentration creates pollinator colony collapse exposure that manufacturers hedge through Australian orchard development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California water stress against Australian supply stability creates a geographic-arbitrage foundation where downstream brands can secure cost-advantaged input streams while European regulatory compliance costs erect defensive moats.
For Market Incumbents:Acquire captive almond orchard assets in Australia's lower-water-stress regions to diversify supply concentration risk from California drought curtailments. Secure USDA organic certification acceleration to defend premium shelf positioning against commodity private-label erosion. Backward integration into high-pressure homogenization equipment partnerships mitigates 18-24 month order backlogs freezing competitor capacity expansion.
For New Entrants and Emerging Players:Specialty coffee procurement committees with specification-driven purchasing represent the most penetrable buyer archetype for technical service-capable entrants. Direct-to-consumer subscription platforms bypass retail slotting fees while capturing recurring revenue and first-party formulation data. Lead with barista training support programs to displace undifferentiated commodity suppliers from Pacific Northwest and Nordic latte art competition circuits.
For Investors and Strategic Acquirers:Asymmetric upside sits with orchard-integrated processors with proven EFSA-compliant packaging portfolios as REACH chemical safety registrations force Tetra Pack barrier layer reformulation. Long-term viability favors Australian supply diversification plays over pure California exposure given climate volatility trajectories. Watch FDA protein-fortification standard evolution as the signal indicating when nutritional parity claims will redefine competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Australian Orchard Development | Supply diversification mitigates California water allocation volatility for downstream manufacturers. |
| Barista-Specific Formulation Investment | Technical service capabilities capture premium placement in specialty coffee procurement committees. |
| Direct-to-Consumer Subscription Launch | Pantry automation bypasses retail slotting fees while generating recurring revenue streams. |
| USDA Organic Certification Acceleration | Federal standards create premium price realization in mass retail channels facing commoditization. |
| High-Pressure Homogenization Partnership | Equipment access constraints competitor capacity expansion amid 18-24 month manufacturer backlogs. |
Research Approach
Multiple input streams — primary interviews with almond processing engineers, foodservice procurement directors, and specialty coffee chain operators, plus secondary validation against FDA nutrition-labeling guidance, EFSA health claim regulations, and USDA organic certification databases — were reconciled through bottom-up volume triangulation and top-down value estimation.
Data-stream reconciliation across product type, packaging format, distribution channel, and end-user application dimensions anchored CAGR derivation through historical growth pattern analysis and regulatory impact assessment. Modeled variables included EU Green Deal compliance timelines, Central Valley water allocation scenarios, and high-pressure homogenization equipment deployment rates.
Inputs from orchard operators, processing facility managers, and retail category buyers were available through the study window; gaps in forward-looking water rights auction data introduce uncertainty bands around California supply cost projections. Forecasts reflect documented assumptions regarding regulatory implementation pacing and technology adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
Dairy-Free Ice Creams Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
Dairy-Free Spreads Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
Vegan Milk Alternatives Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
United States Non-Dairy Milk Market