
 Gelatin Substitutes Market | 2026-2036
Gelatin Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Gelatin Substitutes Market Intelligence
A divergence in capital intensity for raw material sourcing and processing is bifurcating the competitive landscape. Large-scale ingredient suppliers like Cargill, Incorporated and Ingredion Incorporated leverage their extensive manufacturing footprints for starch-based and carrageenan products. In contrast, specialized firms such as Java Biocolloid differentiate through a focus on specific seaweed-derived ingredients like high-purity agar. This creates distinct competitive arenas based on industrial scale versus niche specialization.
Gelatin substitutes are hydrocolloids, primarily complex polysaccharides, sourced from plants, seaweed, or microbes. These ingredients are engineered to replicate the gelling, thickening, and stabilizing functions of animal-based gelatin in various industrial formulations. From a product standpoint, pectin and carrageenan command significant volume, driven by their extensive use in confectionery and dairy products. Agar and gelatinized starch are gaining traction in high-value applications like meat alternatives and nutraceuticals, where specific textural properties are required.
Market access depends on compliance with food additive regulations set by bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). National standards, such as China's GB standards for food ingredients, also dictate formulation and labeling requirements for imported and domestic products. Stakeholders must decide between direct, single-ingredient substitution and developing complex, multi-hydrocolloid systems to achieve desired sensory profiles and cost targets.
Market Dynamics
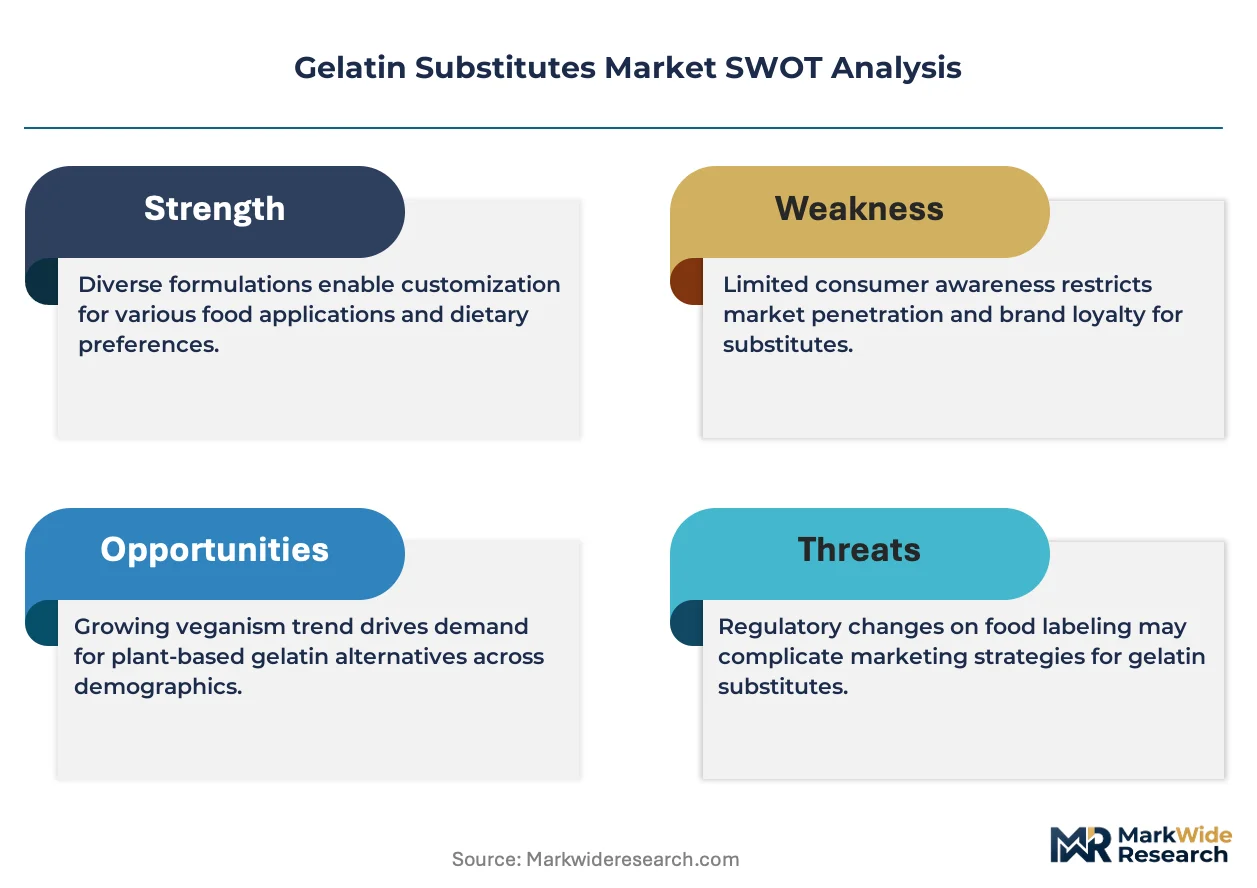
A fundamental shift in consumer values toward vegan, clean-label, and ethically sourced products is the central force restructuring the gelatin substitutes market. This demand pattern compels food manufacturers to reformulate entire product lines, moving beyond simple substitution toward functional ingredient systems.
Growth Catalysts
- Regulatory Mandates:European Union food labeling laws, enforced by bodies like EFSA, require transparent sourcing declarations, compelling manufacturers to adopt plant-based hydrocolloids to meet clean-label demands from consumers.
- Dietary Shifts:The mainstream adoption of plant-based diets, particularly concentrated in European markets like Germany and the United Kingdom, directly fuels volume demand for gelatin alternatives in confectionery and dairy-free products.
- Application-Specific Demand:The meat alternatives sector requires hydrocolloids like agar and gelatinized starch that can create specific textures, such as a firm bite or succulence, driving innovation in high-value ingredient formulation.
Market Restraints
- Input Cost Volatility:The price and availability of raw materials, particularly specific seaweed species for agar and carrageenan production, are subject to environmental conditions and geopolitical factors, creating cost instability for processors.
- Functional Gaps:No single plant-based hydrocolloid perfectly replicates all of gelatin's functional properties, especially its unique melt-in-the-mouth sensory profile, requiring complex and costly multi-ingredient blends for many applications.
- Supply Chain Concentration:The cultivation and harvesting of key raw materials like acacia gum are concentrated in specific regions, such as the African Sahel, creating significant vulnerability to localized supply chain disruptions.
Strategic Opportunities
- Novel Applications:Development of sophisticated multi-hydrocolloid systems can unlock new markets in high-tech food production, including providing scaffolding for cell-based meats or creating intricate structures in 3D-printed food products.
- Geographic Expansion:Untapped demand exists in regions like Latin America and the Middle East, where rising disposable incomes and nascent health and wellness trends create white-space opportunities for plant-based food ingredients.
- Fermentation Technology:Microbial fermentation presents an opportunity to produce novel hydrocolloids with highly customized functionalities, bypassing agricultural supply chain volatility and enabling precise control over gelling, thickening, and stabilizing properties.
Industry Challenges
- Regulatory Approval Cycles:Securing food additive approvals for novel or modified hydrocolloids from agencies like the US FDA and EFSA is a time-intensive and costly process, creating a significant barrier to market entry for new innovations.
- Standardization Deficits:A lack of universally accepted quality and performance standards for certain substitutes leads to batch-to-batch inconsistency, complicating formulation for industrial food producers and risking product quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gelatin Substitutes Market |
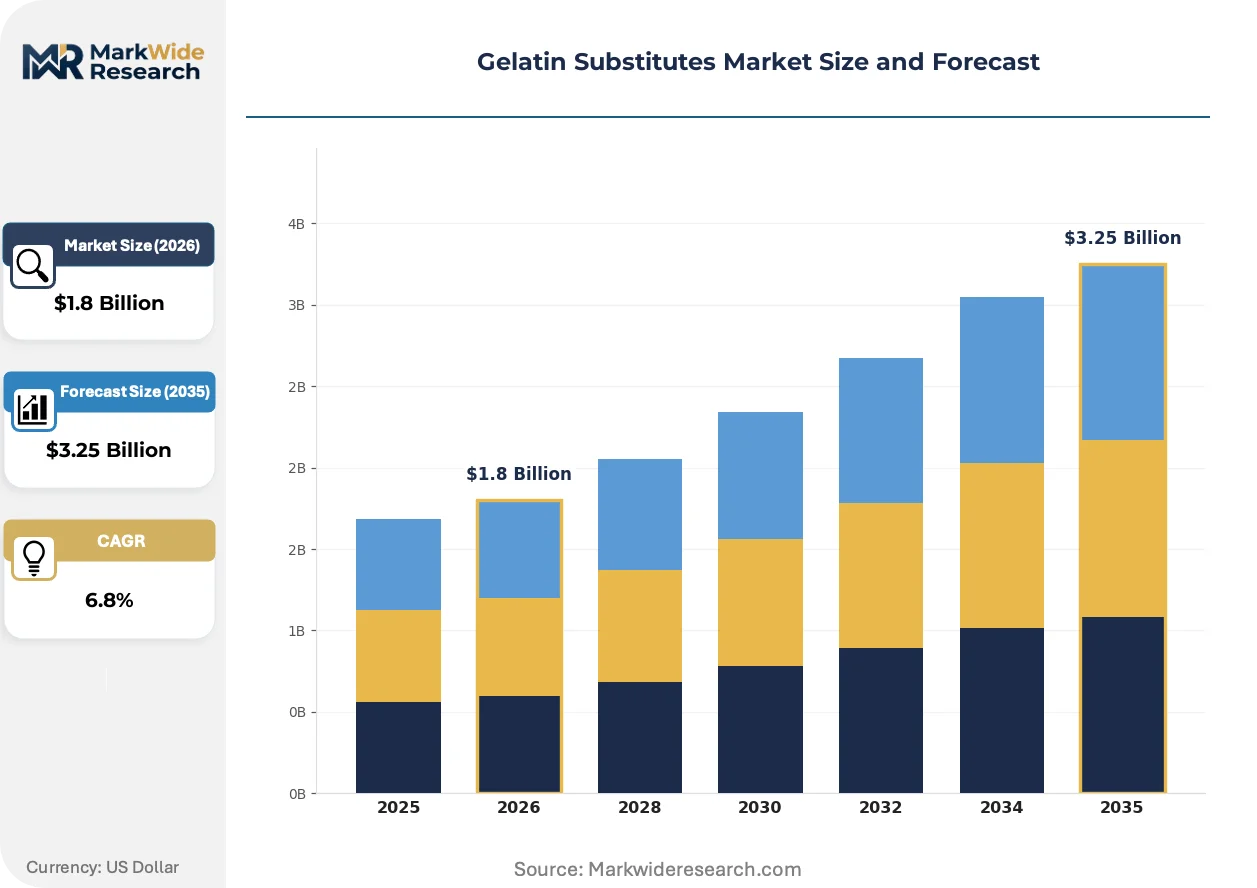
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agar, Pectin, Carrageenan, Gelatinized Starch Source Type: Plant-based, Seaweed, Microbial, Animal-derived Application: Confectionery, Dairy Products, Meat Alternatives, Nutraceuticals End User: Food Industry, Cosmetics, Pharmaceuticals, Dietary Supplements |
| Companies Covered | CP Kelco, Archer Daniels Midland Company, Cargill, Incorporated, Java Biocolloid, Koninklijke DSM N.V., Ingredion Incorporated, GELITA AG, NOW Foods, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gelatin Substitutes Market Strategic Shifts & Innovations
The market is evolving from a focus on one-to-one ingredient replacement toward the design of sophisticated textural systems. This shift prioritizes achieving specific sensory outcomes and functional performance in complex food matrices, driving innovation in ingredient synergy and processing technology.
Precision fermentation is an emerging production method for creating highly pure and functional hydrocolloids. Food technology firms and ingredient specialists are adopting this process to engineer microbes that produce specific polysaccharides with tailored properties. This technology is displacing conventional agricultural and extractive sourcing for high-value ingredients, offering superior consistency and supply chain stability for nutraceutical and premium food applications.
China's national GB standards for food additives are imposing stricter requirements for ingredient purity, labeling, and origin traceability. This regulatory pressure compels both domestic manufacturers and global exporters to invest in advanced quality control and documentation systems to maintain market access. The confectionery and processed dairy segments are most impacted, prompting reformulation efforts to ensure full compliance with the updated Chinese regulations.
Consumer packaged goods manufacturers are altering their procurement patterns, moving from transactional, single-ingredient purchasing to collaborative co-development partnerships with hydrocolloid suppliers. This change disrupts the traditional ingredient sales model, embedding suppliers into the customer's R&D process to design custom textural solutions. This collaborative approach is most visible within the North American and European plant-based food sectors, especially for meat and dairy alternatives.
Gelatin Substitutes Market Segmentation
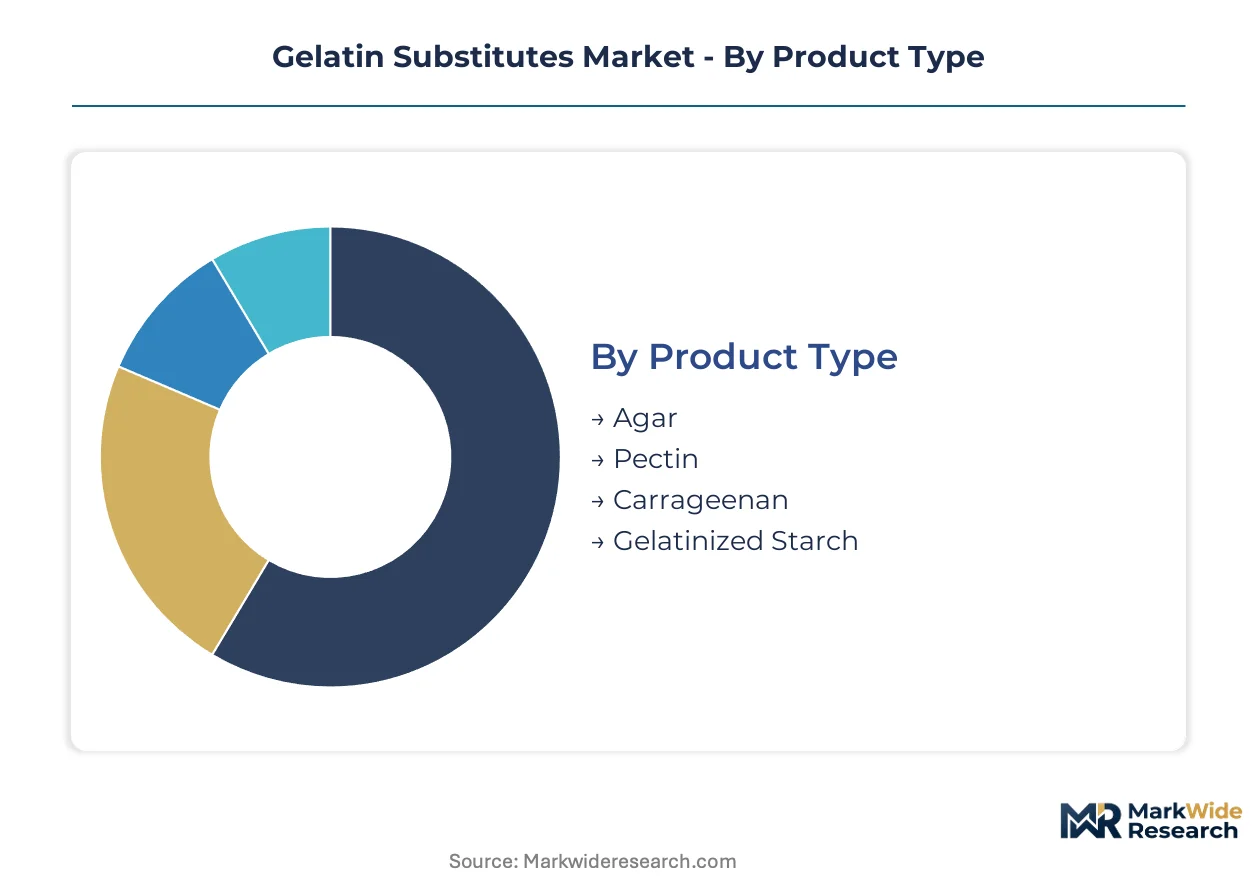
This analysis dissects the Gelatin Substitutes Market across key dimensions, revealing distinct demand patterns and competitive dynamics. Understanding these segments is critical for manufacturers to align product development with specific consumer preferences and regulatory requirements. Each category highlights unique functional attributes and market penetration strategies.
Product Type:
Regulatory bodies increasingly scrutinize ingredient origins, impacting the market share of various product types.
- Pectin:A complex polysaccharide extracted from citrus peels and apples, known for its gelling properties in acidic environments. Demand concentrates in European confectionery and dairy products, driven by clean-label consumer trends.
- Carrageenan:A linear sulfated polysaccharide extracted from red edible seaweeds, providing thickening and stabilizing functions. Its use in dairy-free alternatives and confectionery is substantial, particularly in the United Kingdom, due to its versatile textural properties.
- Agar:A gelatinous substance derived from red algae, primarily used for its firm gelling capabilities. It is gaining traction in meat alternatives.
- Gelatinized Starch:Modified starches that swell in cold water, offering thickening and stabilizing characteristics. This type is critical for specific textural requirements in nutraceuticals.
Established volume favors Pectin; emerging adoption favors Agar.
Source Type:
Ingredient sourcing directly influences application suitability and consumer acceptance across diverse product categories.
- Plant-based:Derived from terrestrial plants like fruits, seeds, and roots, offering clean-label appeal and allergen-free alternatives. This source type sees concentrated demand in vegan confectionery and dairy-free products across Germany.
- Seaweed:Sourced from various marine algae, yielding hydrocolloids such as agar and carrageenan with distinct gelling and thickening properties. Demand is robust in the European Union for its functional versatility in food formulations.
- Microbial:Produced through fermentation processes involving microorganisms, enabling customized functional properties and consistent supply. This source type is emerging for high-purity nutraceuticals.
- Animal-derived:Traditional gelatin sources from collagen, still present in some formulations, though facing reformulation pressure. This source type is declining in ethical consumer markets.
Plant-based sources represent the fastest-growing trajectory, driven by ethical consumerism.
Application:
Application segments exhibit varying volume requirements and functional specifications, shaping ingredient demand.
- Confectionery:Encompasses gummies, jellies, and other sweet treats where gelling agents provide texture and stability. This segment shows high demand in the United Kingdom, spurred by the push for vegan-friendly sweets.
- Dairy Products:Includes yogurts, desserts, and dairy-free alternatives requiring thickening and stabilizing agents for desired consistency. Demand for plant-based options is significant in Germany, aligning with dietary shifts.
- Meat Alternatives:Products designed to mimic meat textures, relying on hydrocolloids for structure and mouthfeel. This application area requires specific textural properties.
- Nutraceuticals:Functional foods and supplements where gelatin substitutes encapsulate active ingredients or provide specific delivery matrices. High-value applications are gaining traction.
Confectionery applications are highly cost-sensitive; meat alternatives prioritize specific textural performance.
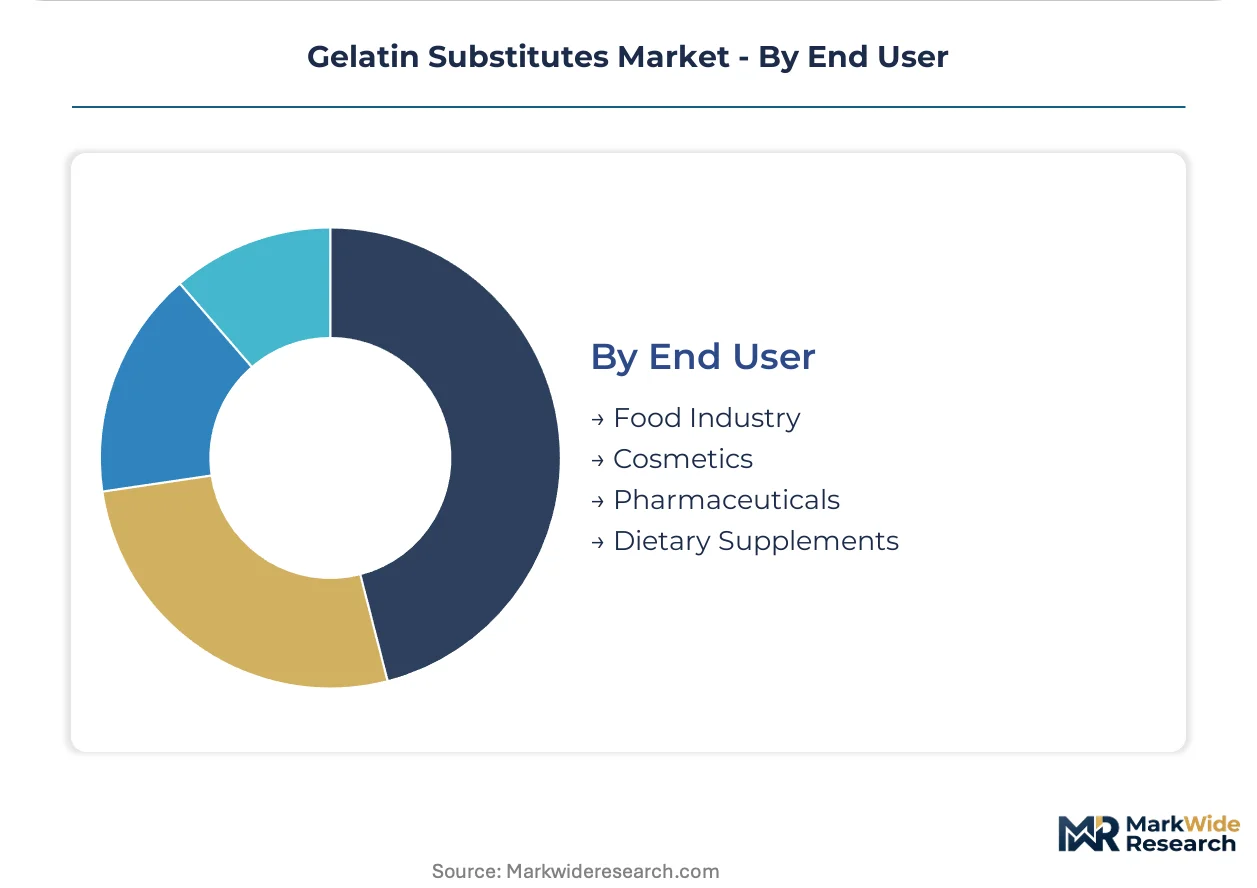
End User:
Different end-user industries possess distinct procurement patterns and regulatory compliance needs for gelatin substitutes.
- Food Industry:The largest consumer, using gelatin substitutes across a wide array of products for gelling, thickening, and stabilizing. This industry faces intense pressure from EU food labeling laws for transparent ingredient declarations.
- Pharmaceuticals:Utilizes hydrocolloids for capsule formation, binding agents, and drug delivery systems, requiring high purity and specific functional characteristics. Demand in this sector is governed by stringent FDA and EMA regulations.
- Cosmetics:Incorporates gelatin substitutes as emulsifiers, thickeners, and film-forming agents in personal care products. Vegan trends influence ingredient selection in this sector.
- Dietary Supplements:Employs plant-based alternatives for capsule shells and binding agents, catering to health-conscious consumers. This segment aligns with clean-label preferences.
The Food Industry is driven by volume; Pharmaceuticals are driven by high-purity functional requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing-power asymmetry in the gelatin substitutes market places European manufacturers in a different position than those in Asia. Raw material sourcing costs vary significantly across continents, influencing final product pricing and market access for diverse product categories.
Germany
Demand for plant-based dairy alternatives and vegan confectionery drives market expansion in Germany. EFSA regulations ensure ingredient safety and transparent sourcing for food manufacturers. The Rhine-Main region sees significant research and development investment in novel hydrocolloid formulations for industrial food production.
United Kingdom
Consumer preference for vegan confectionery and dairy-free products boosts gelatin substitute consumption across the United Kingdom. The Food Standards Agency monitors ingredient labeling and ensures compliance for plant-based products. London's vibrant food tech incubators foster innovation in textural system development for new product launches.
China
Stricter GB standards for food additives necessitate reformulation efforts among both domestic and international manufacturers in China. The NMPA regulates novel food ingredients, impacting market entry and product innovation. Shanghai's extensive food processing hubs require compliant and traceable gelatin substitute supplies for their diverse product portfolios.
United States
Clean-label trends in nutraceuticals and meat alternatives fuel significant ingredient demand across the United States. The US FDA approves new hydrocolloid applications, ensuring safety and functional performance. California's expansive plant-based food sector actively seeks functional alternatives for product development.
France
Rising demand for clean-label ingredients in gourmet food and premium confectionery applications supports market growth in France. ANSM ensures the safety of food additives used in French food products. Brittany's marine biotechnology clusters focus on sustainable sourcing and innovation in seaweed-derived hydrocolloids.
Gelatin Substitutes Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the gelatin substitutes market. The competitive structure bifurcates between large-scale commodity suppliers and niche specialty producers. Strategic archetypes include integrated ingredient giants, agile bio-tech innovators, and regional formulation specialists. Capacity expansion, strategic partnerships, and targeted R&D define competitive moves across the landscape.
Large-scale ingredient suppliers dominate the volume-driven segments, leveraging extensive manufacturing capabilities and global distribution networks. Cargill, Incorporated and Ingredion Incorporated exemplify this scale-driven approach, providing a broad portfolio of starch-based and carrageenan products to diverse food industries. Conversely, specialized firms like Java Biocolloid occupy a position in high-purity, niche markets, focusing on specific seaweed-derived ingredients such as agar. These players cater to high-value applications requiring precise functional attributes, consistent quality, and often, customized solutions for complex formulations.
| Leading Market Players |
|---|
| CP Kelco |
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Java Biocolloid |
| Koninklijke DSM N.V. |
| Ingredion Incorporated |
| GELITA AG |
| NOW Foods |
| DuPont de Nemours, Inc. |
| Others |
Cost & Logistics Intelligence
European Food Safety Authority (EFSA) regulations gate supply qualification and influence price differentiation for gelatin substitutes across the continent. These stringent standards compel manufacturers to invest in traceable sourcing and quality control, impacting ingredient costs.
Pricing Analysis
Configured-to-order pricing for specialized multi-hydrocolloid systems contrasts with standard commodity spot pricing for bulk ingredients like starch. Price differentiation hinges on quality grade, particularly for nutraceuticals, and the level of customization required for complex formulations. Pricing softness runs through high-volume confectionery segments due to input cost volatility. Pharmaceutical and nutraceutical buyers exhibit lower price sensitivity, prioritizing purity and functional performance.
Supply Chain Analysis
China and Southeast Asia anchor seaweed cultivation and processing for agar and carrageenan, while the African Sahel is the primary source for acacia gum. The market draws from specific red algae species and citrus peels as raw material dependencies. Commodity price volatility, influenced by environmental conditions affecting seaweed harvests, presents a structural supply chain risk. Distribution runs through a blend of direct sales from large ingredient suppliers and specialized distributors for niche, high-purity products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gelatin substitutes market presents a significant service-attach opportunity, with formulation and R&D support expanding faster than ingredient sales. Custom textural solution development offers a recurring-revenue layer for suppliers.
For Market Incumbents: Shield core market share by investing in advanced fermentation technology to ensure consistent, high-purity hydrocolloid supply. Diversify raw material sourcing beyond regions vulnerable to climate shifts, mitigating input cost volatility. Strategic partnerships with major CPGs for co-development of multi-hydrocolloid systems can counter emerging biotech threats and secure long-term contracts. Focus R&D on replicating gelatin's unique melt-in-the-mouth sensory profile.
For New Entrants and Emerging Players: Rapid FDA and EFSA certification fast-tracks for novel microbial hydrocolloids can enable new entrants to penetrate high-value segments. Target underpenetrated applications like scaffolding for cell-based meats or intricate 3D-printed food structures. A go-to-market angle focusing on highly customized, functionally superior ingredients for nutraceuticals or premium plant-based dairy offers white-space opportunity.
For Investors and Strategic Acquirers: The European Union's updated food labeling laws reshape the acquisition landscape, favoring companies with transparent, plant-based ingredient portfolios. Long-term viability remains strong over the next 5-10 years, driven by sustained clean-label and vegan trends. Target agile biotech innovators possessing proprietary fermentation IP for novel hydrocolloids. A signal to watch is an increase in M&A activity involving firms specializing in microbial protein and polysaccharide production.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Technology Investment | Secures consistent supply of functional hydrocolloids, reducing reliance on volatile agricultural inputs. |
| Multi-Hydrocolloid System R&D | Creates bespoke textural solutions for complex food matrices, enabling novel product development. |
| Geographic Sourcing Diversification | Mitigates supply chain risks from single-region dependencies and environmental fluctuations. |
| Strategic Co-development Partnerships | Embeds suppliers into customer R&D, fostering long-term relationships and custom solutions. |
| Novel Application Scouting | Unlocks new revenue streams in high-tech food and nutraceuticals, beyond traditional confectionery. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from authoritative sources. Primary research involved discussions with R&D directors, procurement managers, regulatory affairs specialists, and food scientists across key geographies. Secondary data encompassed EFSA reports, FDA filings, China GB standards, and industry association publications, triangulating findings from both bottom-up and top-down approaches.
The analysis established a comprehensive forecasting framework across the analysis window, integrating quantitative modeling with qualitative market insights. Segmentation dimensions modeled included product type, source type, application, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected demand shifts. Key industry-specific forecast inputs included consumer dietary preference surveys and regulatory approval timelines for novel hydrocolloids.
The analysis sits within stated boundaries; outcomes outside unforeseen geopolitical events or rapid technological disruptions would require recalibration. Forecasts reflect assumptions regarding sustained clean-label trends and stable regulatory environments. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Gum Arabic Market
Ingredients
Global Egg White Peptide Market
Ingredients
Citrus Pectin Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
Plant Based Ingredients Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Oyster Peptide Market
Ingredients
Smoked Yeast Market
Ingredients
Mirepoix Market
Ingredients
Canada Sodium Reduction Ingredients Market
Ingredients
Fucoidan Extract Market
Ingredients
France Protein Market
Ingredients
Pea Hull Fiber Market