
 Soy Milk Powder Market | 2026-2036
Soy Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Milk Powder Market Analytics
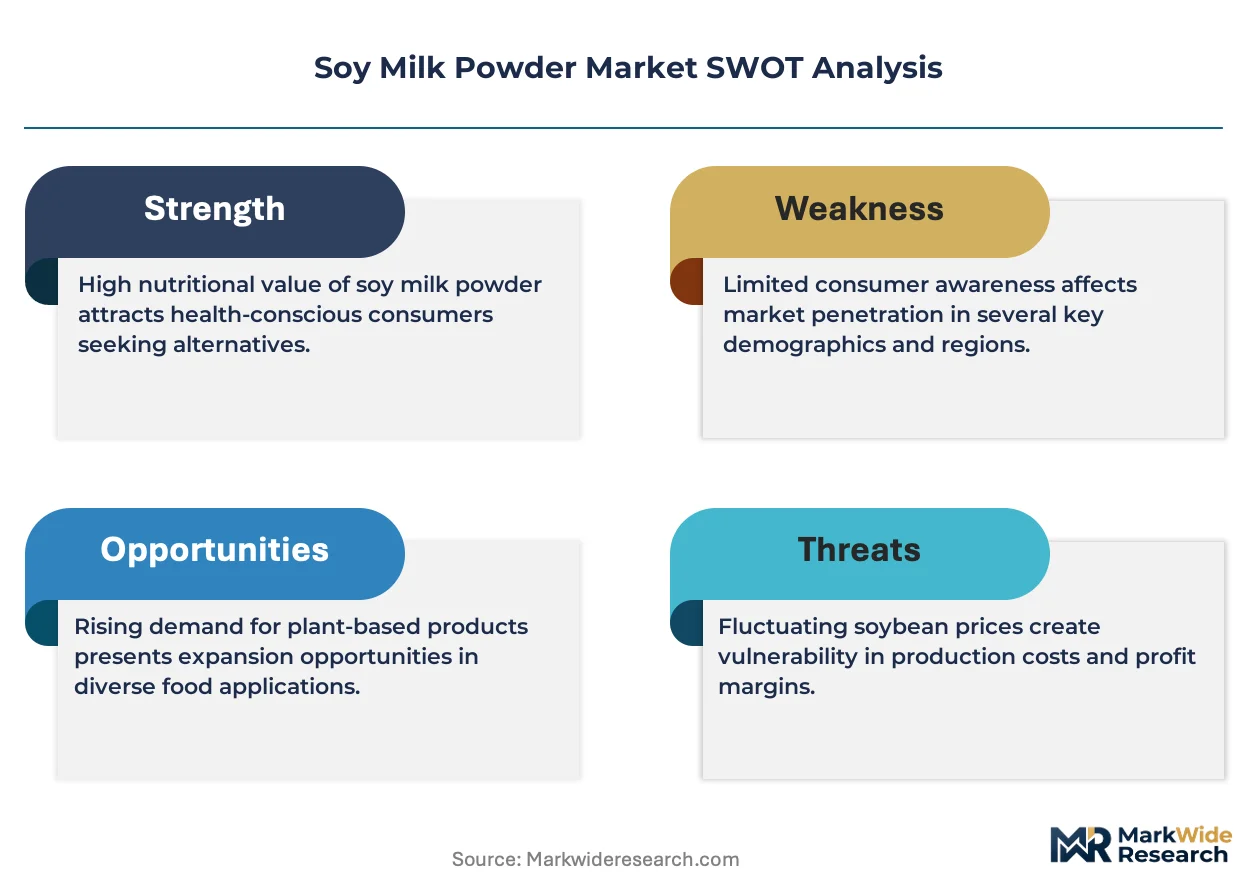
ISO 22000 certification is rotating as the decisive gate for commercial-scale supply contracts, effectively filtering out informal processors across Asia-Pacific sourcing networks. SunOpta Inc. leverages its integrated organic supply chain from North American growers to finished powder. NOW Foods sustains a specialized position in non-GMO and allergen-controlled product lines for health-conscious consumers. Vitasoy International Holdings Ltd. anchors its competitive stance through decades of brand equity in Greater China beverage channels.
Soy milk powder consists of dehydrated aqueous soy extract, typically containing 40-50% protein by weight after spray-drying or roller-drying, serving as a shelf-stable dairy alternative for beverage reconstitution and food manufacturing. The organic product type commands premium positioning as supply scarcity of certified non-GMO soybeans constrains volume expansion. Instant formulations lead functional demand from foodservice operators seeking cold-water solubility without clumping. Distribution through health stores captures the highest per-unit margins despite representing lower throughput than supermarket or online channels.
China's SAMR enforces GB standards for plant-based infant formula powders, while the USDA Organic seal and EU Organic Regulation shape export eligibility for North American and European suppliers respectively. FDA oversight of soy protein health claims in the United States directly influences product labeling strategies and consumer communication. Stakeholders must monitor evolving protein content thresholds in national food codes and calibrate formulation investments before regulatory divergence fragments cross-border product specifications.
Market Dynamics
ISO 22000 certification is filtering informal processors from commercial supply chains across Asia-Pacific sourcing networks, concentrating procurement among qualified spray-drying facilities near Ho Chi Minh City and Jakarta.
Growth Catalysts
- EU Novel Food regulations:Tightened entry requirements for non-dairy alternative powders are accelerating investment in compliant processing infrastructure by Southeast Asian exporters seeking European market access.
- Spray-drying technology advancement:Infant formula manufacturers in Vietnam are expanding procurement of spray-dried soy protein isolates with enhanced cold-water solubility for premium reconstitution performance.
- Ho Chi Minh City dairy corridor:Demand concentration in Vietnam's processing hub is generating cluster economies that reduce logistics costs for containerized powder exports to ASEAN markets.
Market Restraints
- Certified organic soybean scarcity:Supply constraints for non-GMO certified beans limit volume expansion of premium organic product lines despite price premiums.
- GB standards compliance:China's SAMR enforcement of plant-based infant formula powder regulations creates formulation divergence costs for exporters serving multiple national food codes.
- Dairy protein substitution:Whey and casein powders retain cost advantages in performance nutrition applications, compressing soy protein isolate penetration in sports nutrition segments.
Strategic Opportunities
- USDA Organic and EU Organic Regulation alignment:Dual-certified production lines enable North American suppliers to capture premium positioning in both export markets without separate processing runs.
- Health store channel expansion:Direct-to-practitioner distribution captures highest per-unit margins through allergen-controlled and non-GMO specialized product lines.
- Instant formulation innovation:Cold-water solubility without clumping addresses unmet foodservice operator needs for beverage reconstitution efficiency.
Industry Challenges
- ISO 22000 certification timeline:Formal processors face 12-18 month compliance periods that delay contract eligibility against established certified competitors.
- Protein content threshold calibration:Diverging national food codes require formulation investments before regulatory fragmentation locks in incompatible product specifications across export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Milk Powder Market |
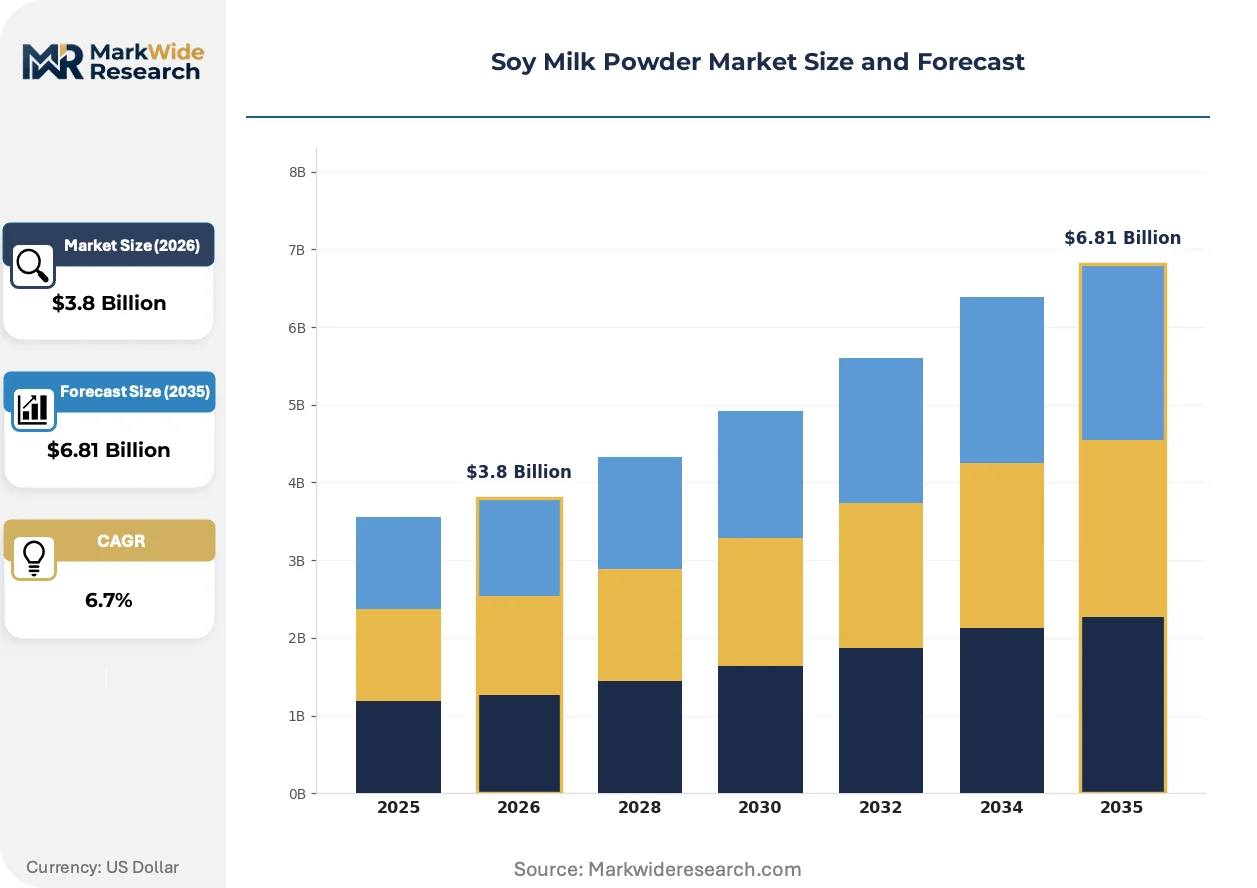
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant, Organic, Non-Organic, Flavored End Use: Beverages, Food Products, Bakery, Ice Cream Distribution Channel: Online, Supermarkets, Health Stores, Specialty Shops Packing Type: Bags, Tetra Packs, Cans, Bulk |
| Companies Covered | Enfamil, Wyeth, NOW Foods, SunOpta Inc., Weiwei Group, Unisoy, PANOS, Vitasoy International Holdings Ltd., Similac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Milk Powder Market Evolving Landscape
Processing technology and certification requirements are restructuring competitive advantage around integrated supply chain control and regulatory compliance velocity rather than commodity scale alone.
Spray-drying equipment with integrated protein denaturation control is bifurcating the processing landscape between infant-grade isolates and standard food-ingredient powders. Vietnamese and Indonesian contract manufacturers are adopting these systems to meet EU Novel Food entry requirements. The technology is compressing margins for legacy roller-drying facilities while enabling premium positioning for compliant suppliers.
China's SAMR enforcement of updated GB standards for plant-based infant formula powders is forcing reformulation investments by exporters targeting maternal nutrition segments. The industrial consequence is segmented production lines dedicated to Chinese regulatory compliance versus other export markets. Infant formula specialists are responding with regional SKU strategies that isolate China-bound inventory from standard export formulations.
Foodservice procurement is consolidating around instant solubility specifications that eliminate clumping in cold-water reconstitution. Health store and online channels are capturing preference shifts toward allergen-controlled and non-GMO certifications that command margin premiums. This behavioral rotation is most visible in North American and European markets where clean-label positioning drives switching decisions among institutional buyers.
Soy Milk Powder Market Segmentation
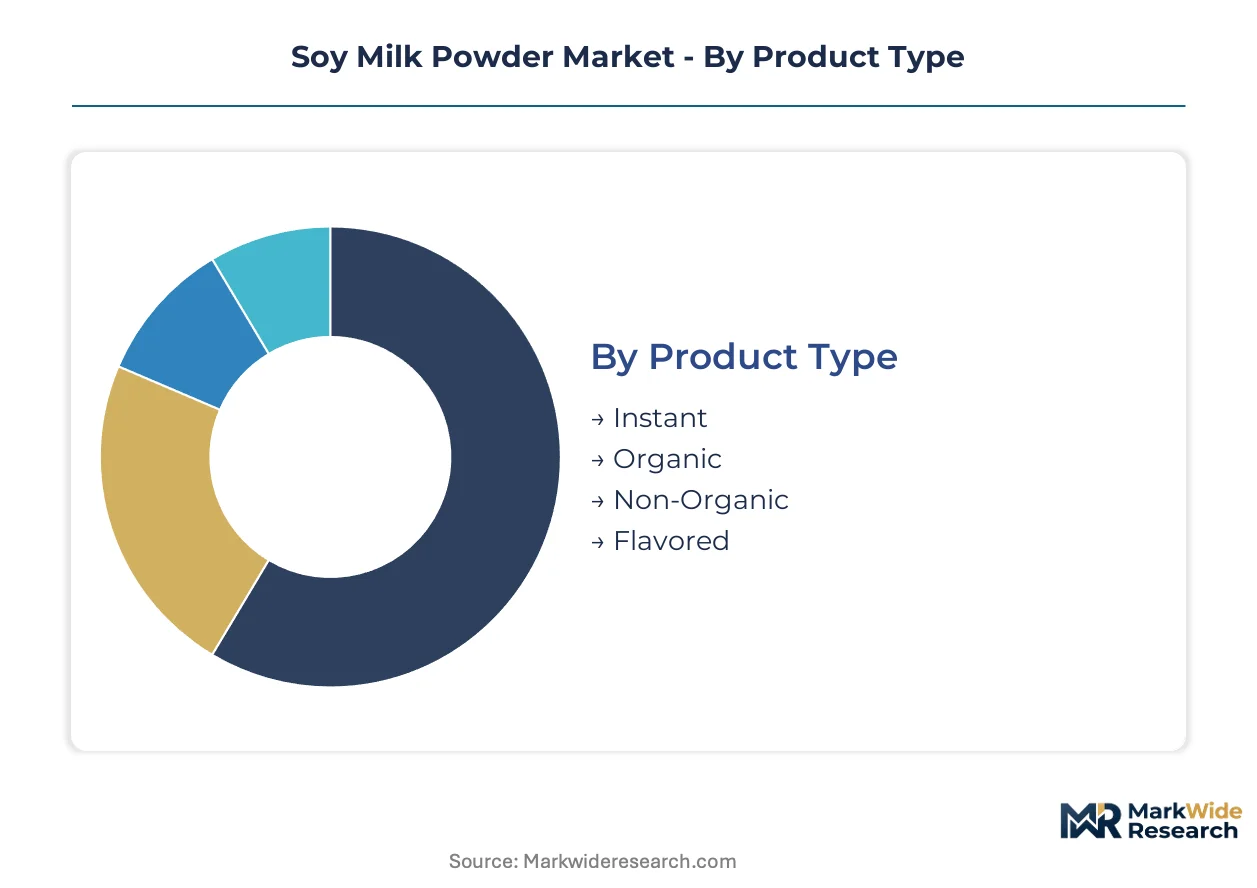
Soy milk powder segmentation reflects divergent margin architectures across certification tiers, application requirements, and channel economics. Manufacturers calibrate production lines against these boundaries to capture premium positioning without fragmenting operational efficiency.
Product Type:
Margin pools concentrate in certified organic and instant formulations where supply scarcity and functional performance justify price premiums over commodity grades.
- Instant:Cold-water solubility without clumping requires controlled protein denaturation during spray-drying. Foodservice operators in Vietnam's Ho Chi Minh City corridor specify this grade for beverage reconstitution efficiency, driving procurement concentration among ISO 22000-certified processors.
- Organic:Certified non-GMO soybean scarcity constrains volume expansion despite substantial price premiums. USDA Organic and EU Organic Regulation dual-certification enables North American suppliers to access both export markets without separate processing runs.
- Non-Organic:Standard commodity grade serves cost-sensitive food manufacturing applications with minimal certification overhead.
- Flavored:Vanilla, chocolate, and malt variants target direct-to-consumer beverage markets with differentiated taste profiles.
Instant formulations hold installed capacity. Organic is rotating up the share rankings.
End Use:
Application economics diverge sharply between infant-grade isolates demanding regulatory compliance and industrial food ingredients prioritizing cost efficiency.
- Beverages:Reconstituted soy milk for direct consumption commands formulation investment in solubility and taste masking. China's SAMR enforces GB standards for plant-based infant formula powders, creating segmented production lines for maternal nutrition versus standard export formulations.
- Food Products:Protein fortification in meat alternatives and nutritional bars utilizes standard-grade isolates with lower purity thresholds.
- Bakery:Functional properties including emulsification and moisture retention drive specification requirements in commercial baking operations.
- Ice Cream:Fat mimetic properties in frozen dessert applications require specific protein hydrolysis levels for texture control.
Beverage applications absorb regulatory compliance costs. Food Products is climbing the fastest as meat alternative formulation expands.
Distribution Channel:
Channel selection directly determines margin capture, with health stores and specialty shops yielding per-unit premiums despite lower throughput velocity.
- Health Stores:Allergen-controlled and non-GMO specialized lines achieve highest per-unit margins through direct-to-practitioner distribution models. Clean-label positioning drives switching decisions among institutional buyers in North American and European markets.
- Online:Direct-to-consumer platforms enable subscription models and personalized nutrition positioning with reduced intermediary markup.
- Supermarkets:Mass retail channels prioritize price competitiveness and shelf-stable packaging formats for household penetration.
- Specialty Shops:Ethnic grocery and organic-focused retailers serve diaspora communities and health-conscious urban consumers.
Health Stores sustain margin leadership. Online is gaining share fastest through subscription model adoption.
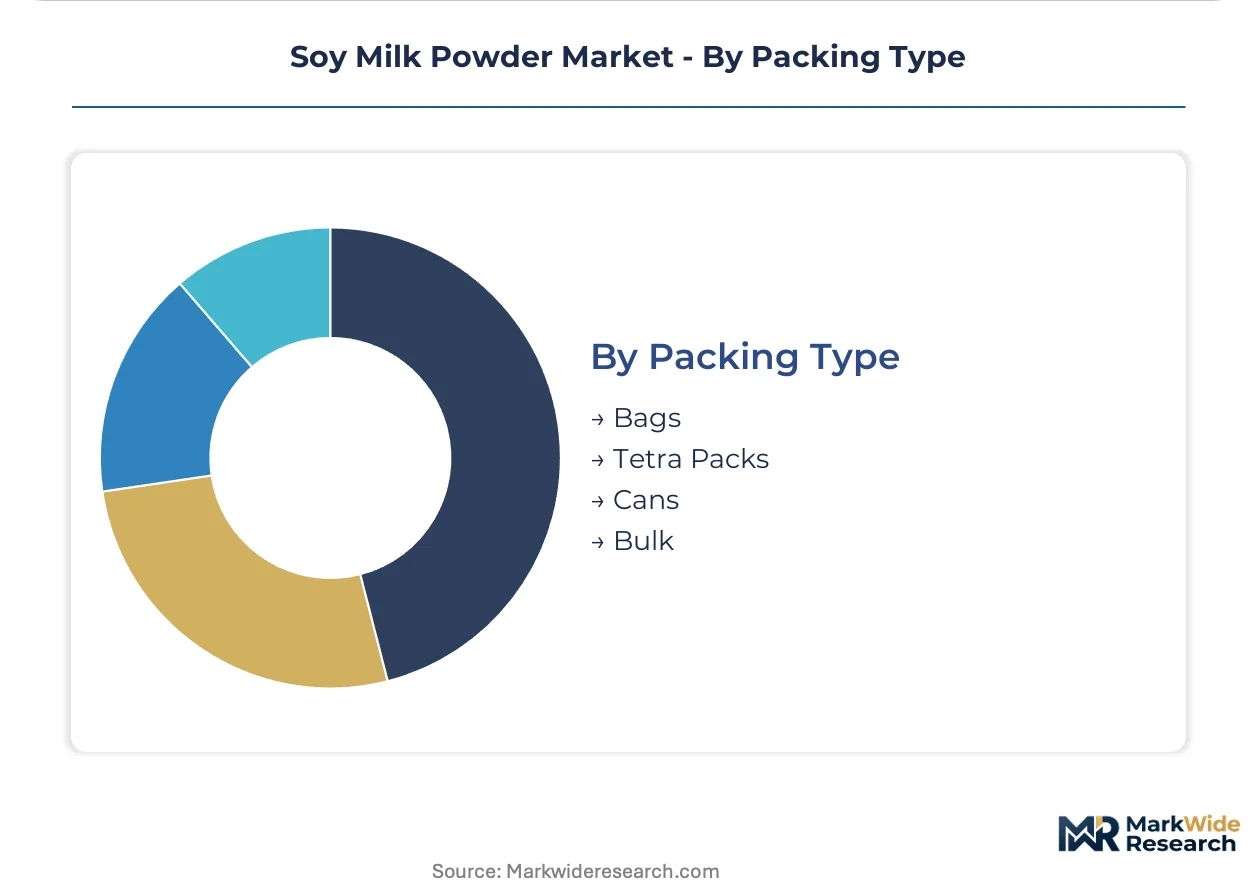
Packing Type:
Packaging economics align with volume scale and shelf-life requirements across consumer, foodservice, and industrial procurement segments.
- Bulk:Industrial-scale tote bags and fiber drums serve food manufacturers with dedicated handling infrastructure and rapid inventory turnover.
- Bags:Consumer-sized pouches target household reconstitution with resealable features and portion control.
- Tetra Packs:Aseptic brick packaging extends shelf stability for ambient distribution in tropical climates.
- Cans:Metal containers provide maximum protection against moisture and oxygen for premium positioning and gift markets.
Bulk commands foodservice volume. Bags is expanding most quickly through retail channel diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Novel Food regulations are accelerating infrastructure investment among Southeast Asian exporters seeking European market access. China's SAMR enforcement of GB standards for plant-based infant formula powders is fragmenting production lines for maternal nutrition segments. Vietnam's Ho Chi Minh City dairy corridor is generating cluster economies that reduce logistics costs for containerized powder exports.
China
Maternal nutrition demand from urban middle-class consumers drives formulation investments in protein fortification. SAMR enforces GB standards for plant-based infant formula powders that require segmented production lines isolating China-bound inventory. Yangtze River Delta processors near Shanghai are expanding spray-drying capacity to serve domestic infant formula manufacturers.
Vietnam
Foodservice operators in the Ho Chi Minh City corridor specify instant solubility grades for beverage reconstitution efficiency. The country's national food safety authority aligns inspection protocols with EU Novel Food entry requirements for export eligibility. Spray-drying facilities near Ho Chi Minh City are capturing procurement concentration from ASEAN-bound containerized powder shipments.
United States
Health-conscious consumers in coastal metropolitan markets prioritize allergen-controlled and non-GMO certifications. FDA oversight of soy protein health claims directly influences product labeling strategies and consumer communication. Pacific Northwest organic soybean growers supply certified processors serving dual USDA Organic and EU Organic Regulation export channels.
Germany
Clean-label positioning drives switching decisions among institutional buyers in food manufacturing and foodservice procurement. EU Organic Regulation and EFSA oversight shape import eligibility and health claim substantiation requirements for non-dairy alternative powders. Bavarian organic food processors are integrating spray-dried soy protein isolates into meat alternative formulations for European retail chains.
Indonesia
Expanding middle-class consumption of reconstituted beverages supports demand for standard-grade soy milk powder in retail channels. The country's national food and drug regulator enforces halal certification requirements that filter processing facility eligibility for domestic distribution. Jababeka industrial estate near Jakarta is attracting spray-drying investment from contract manufacturers serving ASEAN export markets.
Soy Milk Powder Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and distribution channel access. The vendor base stratifies between integrated organic supply chain operators, regional contract manufacturers, and branded consumer goods companies. Three archetypes dominate: North American integrated organic processors, Southeast Asian contract manufacturers, and Greater China beverage brand owners. M&A activity concentrates on spray-drying capacity acquisition, while strategic partnerships secure certified organic soybean supply.
Among North American integrated operators, SunOpta Inc. exemplifies the supply chain control archetype through its captive organic grower networks. NOW Foods occupies a specialist position in allergen-controlled and non-GMO product lines for health store distribution. Vitasoy International Holdings Ltd. anchors the branded beverage channel archetype through decades of equity in Greater China markets.
| Leading Market Players |
|---|
| Enfamil |
| Wyeth |
| NOW Foods |
| SunOpta Inc. |
| Weiwei Group |
| Unisoy |
| PANOS |
| Vitasoy International Holdings Ltd. |
| Similac |
| Others |
Value Network & Pricing Analysis
Spray-dried soy protein isolates displacing roller-dried commodity grades in infant formula applications simultaneously concentrates procurement power among ISO 22000-certified processors near Ho Chi Minh City and compresses margins for legacy facilities lacking cold-water solubility capabilities.
Pricing Analysis
Certification level creates the primary spread between premium organic dual-certified grades and standard commodity powders. Three-tier pricing structure across premium, standard, and economy levels anchors on USDA Organic and EU Organic Regulation alignment, with instant solubility formulations commanding additional premiums from foodservice operators. Cost compression in standard non-organic tiers is intensifying because Vietnamese contract manufacturers are expanding spray-drying capacity for ASEAN export markets. Industrial food manufacturers exhibit highest price sensitivity, while health store channels absorb substantial premiums for allergen-controlled and non-GMO specialized lines.
Supply Chain Analysis
Strategic stockpiling of certified organic soybeans dominates inventory strategy among North American integrated processors confronting supply scarcity, while Asian contract manufacturers favor just-in-time procurement of standard-grade beans from regional traders. Supply concentrates in the United States, Vietnam, and Indonesia, with raw material flows drawing from North American organic grower networks, Brazilian commodity soybean exporters, and regional ASEAN oilseed processors. Single-source vulnerability in certified organic bean supply creates structural risk for premium product lines. Distribution runs through containerized bulk shipments to industrial food manufacturers, with health store and online channels capturing higher-margin direct-to-consumer flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across China's SAMR, EU Novel Food requirements, and FDA oversight creates specialized formulation niches that reward compliance velocity over commodity scale.
For Market Incumbents: Compound certification advantages by extending ISO 22000-compliant spray-drying capacity into secondary ASEAN production nodes before regulatory divergence locks in incompatible product specifications. Deepen backward integration into certified organic soybean supply through captive grower contracts or strategic alliances with North American organic farming cooperatives. Prioritize dual USDA Organic and EU Organic Regulation alignment to capture premium positioning without separate processing runs. For New Entrants and Emerging Players: Cold-water solubility specification gaps in foodservice procurement present immediate white-space opportunity, as established processors under-serve mid-scale Vietnamese beverage operators seeking instant formulations without minimum order thresholds. Target Indonesia's expanding retail channel for standard-grade reconstituted beverages, where halal certification requirements filter incumbent eligibility. Pursue direct-to-practitioner distribution models in North American health store channels, where allergen-controlled positioning commands margin premiums absent from mass retail. For Investors and Strategic Acquirers: Capital is best deployed toward integrated organic supply chain operators with captive grower networks and existing dual-certification infrastructure, as these assets compound defensive moats against commodity price volatility and regulatory compliance cost inflation. Monitor SAMR enforcement actions on GB standards for plant-based infant formula powders as the critical inflection signal; accelerated reformulation mandates would strand non-compliant production capacity and concentrate valuation among pre-certified processors.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Production Line Investment | Enables simultaneous USDA Organic and EU Organic Regulation access without redundant processing runs. |
| Spray-Drying Capacity Expansion | Captures procurement concentration from infant formula manufacturers seeking cold-water solubility specifications. |
| Certified Organic Supply Agreement | Secures non-GMO bean flows constrained by scarcity against competing premium product lines. |
| Direct-to-Practitioner Distribution Buildout | Penetrates health store channels yielding highest per-unit margins through allergen-controlled positioning. |
| Regional SKU Segmentation | Isolates China-bound inventory from standard export formulations to manage SAMR compliance costs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association reports, combining structured interviews with spray-drying facility operators, infant formula procurement managers, organic certification auditors, and health store category buyers with validation against SAMR enforcement notices, USDA Organic certification databases, and EU Novel Food approval registries. Bottom-up capacity assessments across Vietnamese and Indonesian processing corridors triangulate against top-down demand estimates from foodservice and maternal nutrition segments.
Segmentation dimensions modeled include certification tier, solubility grade, end-use application, distribution channel, and regional regulatory cluster across the analysis window. CAGRs derive from production capacity expansion trajectories, import elasticity estimates, and substitution dynamics between soy and dairy protein isolates. Forecast inputs incorporate spray-drying technology adoption curves and evolving protein content thresholds in national food codes.
Underlying assumptions cover sustained enforcement of GB standards by SAMR and continued alignment of Vietnamese inspection protocols with EU Novel Food requirements, with deviation risk concentrated in regulatory divergence fragmenting cross-border product specifications. Revision becomes warranted when organic soybean supply scarcity crosses thresholds forcing rationing among dual-certified processors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Dry Cream Substitute Market
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
Non-Dairy Creamer Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Lactose-Free Milk Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Cultured Dairy Blends Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
Europe Dairy Alternatives Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
Dry Yogurt Market