
 Bay Leaf Oil Market | 2026-2036
Bay Leaf Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Bay Leaf Oil Market Outlook
Synthetic eugenol is recalibrating raw material economics for natural bay leaf oil processors. Givaudan International SA leverages captive sourcing from Mediterranean growers to sustain fragrance-grade supply security. Symrise AG anchors its position through biotechnology investments that reduce batch-to-batch variability. BASF SE competes on industrial-scale distillation capacity serving pharmaceutical contract manufacturers.
Bay leaf oil is a volatile essential oil distilled from Laurus nobilis leaves, containing eugenol, cineole, and linalool as principal actives, with a refractive index typically ranging from 1.465 to 1.470 at 20°C; it functions primarily as a natural antimicrobial agent, flavor modifier, and perfumery raw material across regulated consumer industries. The essential oil segment dominates value capture due to pharmaceutical and aromatherapy certification requirements, while the fragrance oil category navigates tighter IFRA concentration limits in leave-on cosmetic applications. Food flavoring applications lead volume consumption through processed meat and sauce formulations, though cosmetics represents the fastest-expanding margin pool as clean-label preservatives displace synthetic parabens.
FDA oversight of food-contact substances and EPA registration requirements for antimicrobial claims constrain product positioning in the United States, while REACH compliance and ECHA substance evaluations shape market access across European Union member states. ISO 4720 and AFNOR NF T 75-230 standards govern essential oil authenticity testing, forcing producers to invest in chromatographic fingerprinting capabilities. Stakeholders must monitor evolving pharmacopeial monographs and regional natural labeling thresholds to align certification investments with demand migration toward verifiable botanical provenance.
Market Dynamics
Synthetic eugenol oversupply from petrochemical routes is compressing natural bay leaf oil margins and forcing Kerala distillers to reposition toward certified-organic grades. This structural price tension between fermentation-derived and botanical actives is reshaping investment priorities across extraction infrastructure.
Growth Catalysts
- Clean-label preservative mandates:FSSAI's tightened restrictions on synthetic parabens in cosmetic formulations are accelerating personal care brand migration toward natural antimicrobial alternatives.
- ISO 4720 certification premiums:Chromatographic authenticity protocols are enabling European fragrance houses to command price premiums for verifiable Laurus nobilis provenance.
- Steam distillation efficiency gains:Continuous-flow extraction systems are reducing energy intensity per liter by 15-20% in Tamil Nadu processing clusters.
Market Restraints
- Raw material cost volatility:Drought cycles in Mediterranean growing regions are destabilizing leaf supply contracts for mid-scale processors.
- REACH registration burdens:ECHA substance evaluation timelines are extending market access lead times for Indian exporters targeting EU cosmetic applications.
- Fermentation-based eugenol substitution:Givaudan's biotechnology-derived alternatives are capturing price-sensitive fragrance compound formulations.
Strategic Opportunities
- Underpenetrated North American therapeutic markets:FDA GRAS self-affirmation pathways remain underutilized for aromatherapy-grade positioning in wellness retail channels.
- Pharmaceutical contract manufacturing convergence:Co-processing partnerships with antibiotic API producers are opening validated GMP supply relationships.
- EU Green Deal bioeconomy incentives:Horizon Europe funding streams are subsidizing carbon-negative distillation technology adoption.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography-mass spectrometry interpretation expertise is concentrated among retiring technicians in Kerala's traditional processing cooperatives.
- Batch-to-batch standardization complexity:Seasonal terpene profile variation is complicating IFRA compliance documentation for fragrance oil exports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bay Leaf Oil Market |
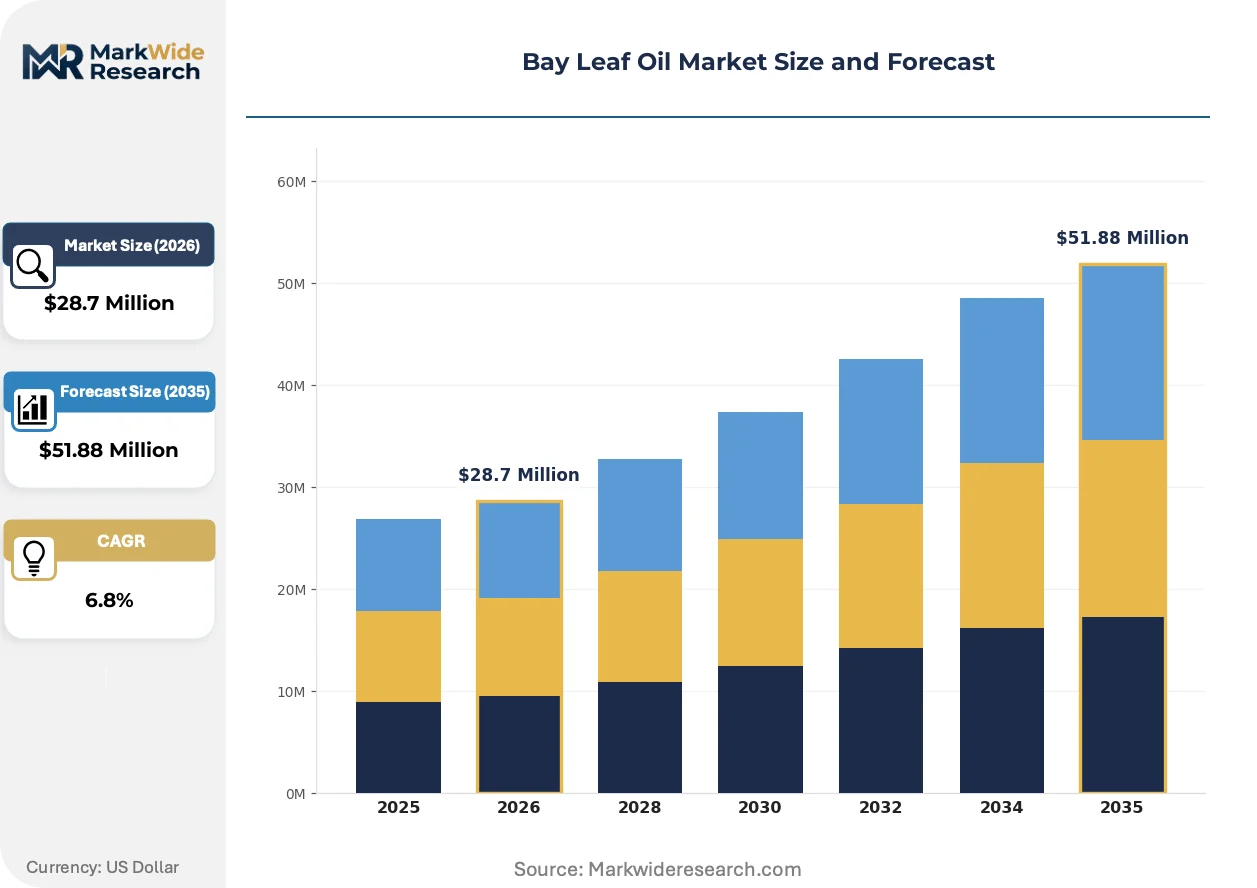
| Market Size in 2026 | $28.7 Million |
| Market Size in 2035 | $51.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Extract, Herbal Oil, Fragrance Oil Application: Food Flavoring, Aromatherapy, Cosmetics, Pharmaceuticals End User: Food Industry, Personal Care, Healthcare, Household Sales Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | BASF SE, DSM, Croda International, Givaudan International SA, Symrise AG, International Flavours and Fragrances Inc., Biolandes SAS, Aryan International, Essential Oils Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bay Leaf Oil Market Strategic Shifts
Supercritical CO2 extraction is displacing conventional steam distillation as the dominant processing paradigm, unlocking higher cineole recovery rates and cleaner sensory profiles. This technological transition is redistributing competitive advantage toward capital-intensive operators.
Microwave-assisted extraction is electrifying yield economics for small-batch artisanal producers. Specialty spice exporters in Madagascar are adopting 2.45 GHz systems to reduce cycle times from six hours to forty minutes. The technology is compressing minimum viable scale thresholds and enabling farm-gate value capture previously reserved for centralized processors.
REACH Annex XIV authorization requirements for skin-sensitizing substances are tightening documentation burdens for cinnamaldehyde-containing botanical extracts. Cosmetic formulators are reformulating toward eugenol-dominant bay leaf oil variants to preempt regulatory exclusion. German fragrance compounders are accelerating substitution programs ahead of 2027 sunset dates.
Direct-procurement platforms are disintermediating traditional spice trading hierarchies. European essential oil buyers are establishing blockchain-traceable contracting relationships with individual Tamil Nadu farming cooperatives. This channel shift is most visible in certified-organic segments where provenance verification commands 25-40% price premiums over conventional grades.
Bay Leaf Oil Market Segmentation
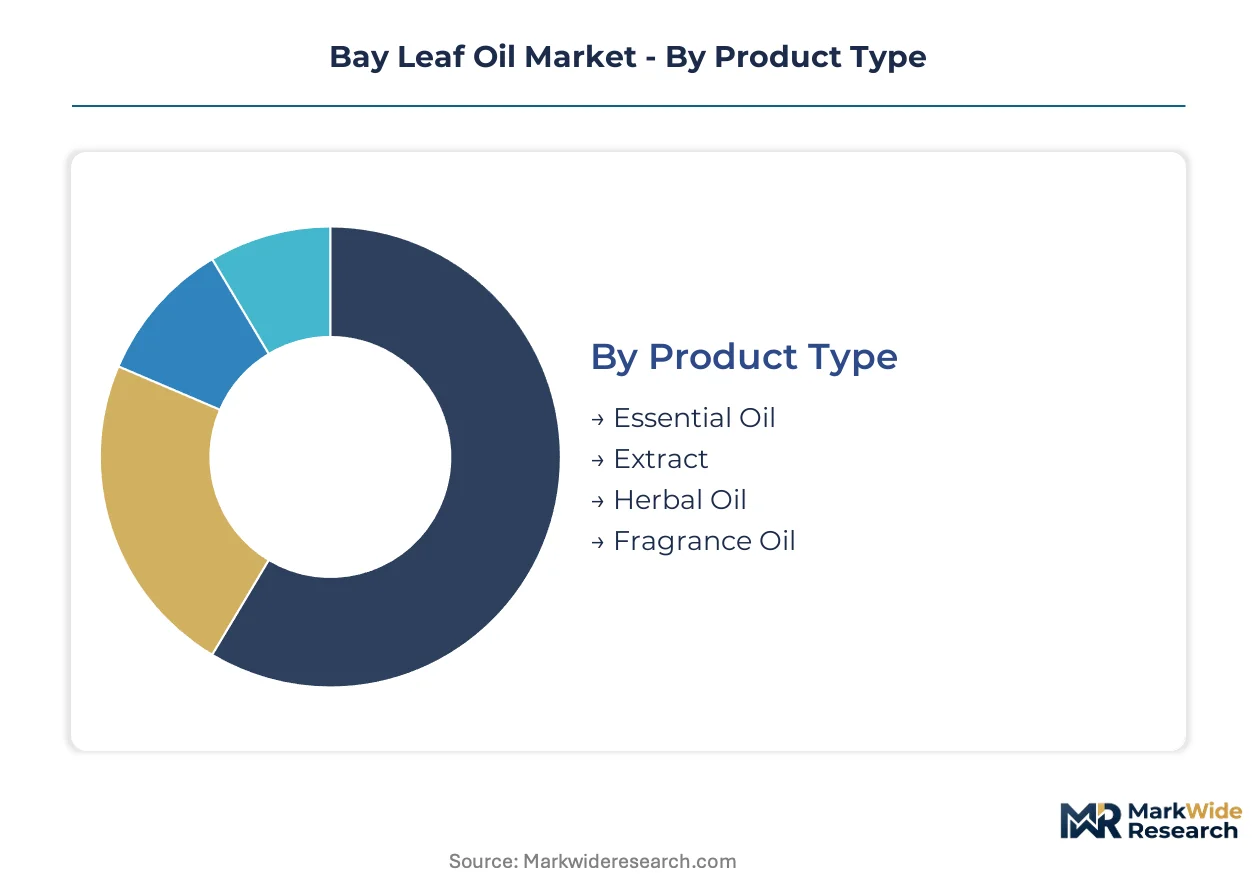
Bay leaf oil procurement decisions pivot on certification grade, end-use regulatory thresholds, and extraction method provenance. Distinct margin architectures separate pharmaceutical-grade essential oils from commodity fragrance compounds, while channel choice determines traceability depth for clean-label positioning.
Product Type:
Buyers segment primarily by purity specification and chromatographic certification requirements, with pharmaceutical and fragrance house procurement teams applying divergent quality gateways.
- Essential Oil:Steam-distilled or CO2-extracted Laurus nobilis oil meeting ISO 4720 authenticity standards with specified eugenol and cineole ranges. Pharmaceutical and aromatherapy certification in India's Kerala and Tamil Nadu processing clusters commands 25-40% premiums over conventional grades.
- Fragrance Oil:Compounded formulations blending natural bay leaf extract with synthetic modifiers to achieve IFRA-compliant concentration limits in leave-on cosmetics. Givaudan International SA and Symrise AG procurement teams prioritize batch-to-batch consistency for fine fragrance applications.
- Extract:Solvent-based or aqueous preparations retaining broader polyphenolic profiles for food and nutraceutical use.
- Herbal Oil:Traditional infusion methods producing lower potency oils for regional Ayurvedic and folk medicine markets.
Volume sits with Essential Oil; growth tilts toward Fragrance Oil.
Application:
Regulatory pathway complexity and margin capture potential separate food-grade flavoring from therapeutic positioning strategies.
- Food Flavoring:Processed meat, sauce, and ready-meal formulations consuming the largest volume share. FSSAI's tightened synthetic preservative restrictions in India are accelerating natural antimicrobial adoption in processed food manufacturing.
- Cosmetics:Clean-label preservative systems displacing parabens in skincare and haircare formulations. Personal care brands in Europe's REACH-regulated markets are reformulating toward eugenol-dominant variants to preempt cinnamaldehyde authorization sunset dates.
- Aromatherapy:Wellness retail and therapeutic-grade positioning requiring pharmacopeial monograph compliance.
- Pharmaceuticals:Antimicrobial and anti-inflammatory API precursors subject to FDA GRAS or EMA herbal medicine registration pathways.
Food Flavoring dominates tonnage; Cosmetics represents the steepest expansion trajectory.
End User:
Scale economics and formulation expertise requirements fragment the buyer landscape across industrial compounders and artisanal producers.
- Food Industry:Industrial meat processors and sauce manufacturers purchasing in drum quantities with specification-driven contracting.
- Personal Care:Cosmetic formulators and contract manufacturers requiring IFRA-compliant documentation and batch-specific chromatographic certificates.
- Healthcare:Pharmaceutical API producers and natural medicine manufacturers pursuing validated GMP supply relationships.
- Household:Diffuser and home fragrance brands sourcing compounded oils through wholesale distributors.
Food Industry anchors procurement volume; Personal Care is climbing the fastest.
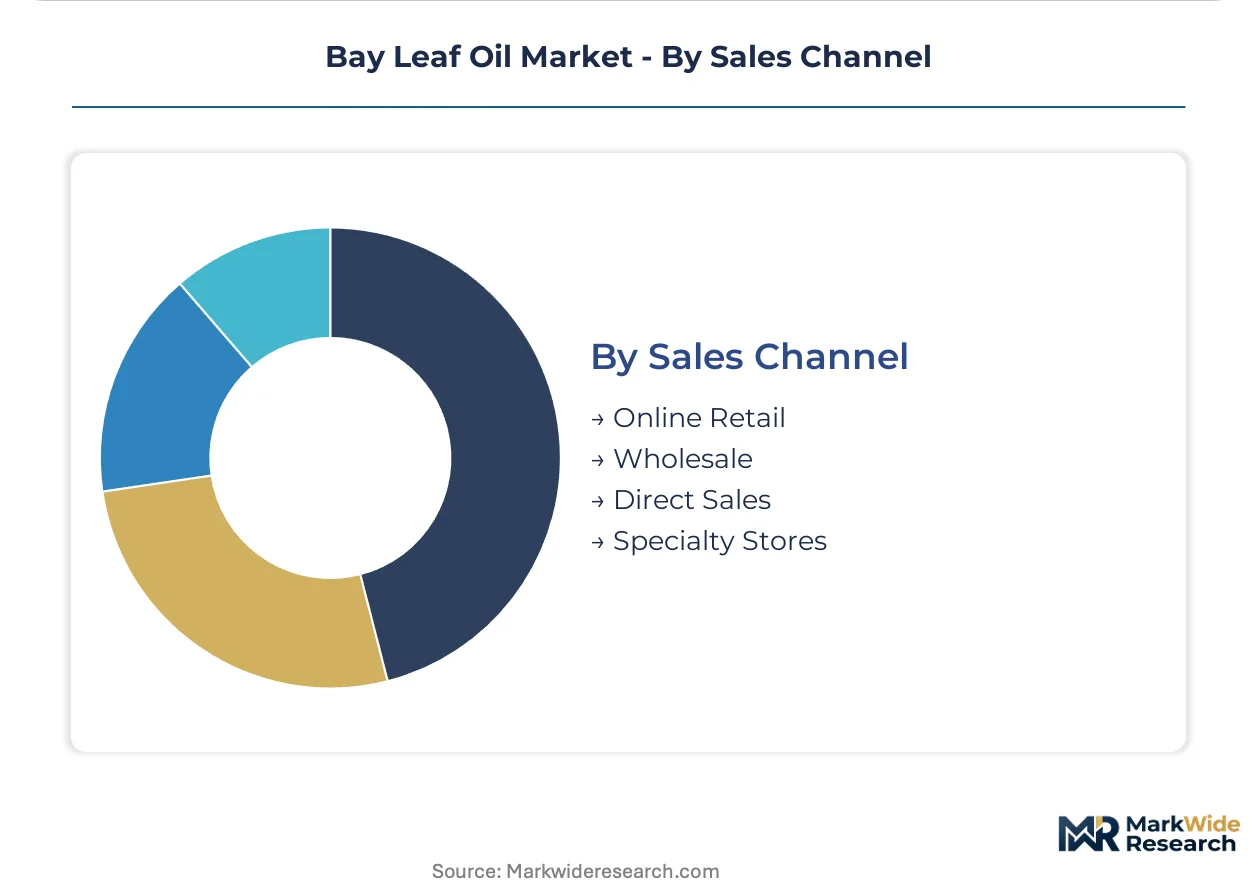
Sales Channel:
Traceability requirements and order scale determine channel selection, with provenance-verified organic grades bypassing traditional trading hierarchies.
- Wholesale:Bulk transactions through spice trading houses and essential oil merchants serving mid-scale processors and regional compounders.
- Direct Sales:Blockchain-traceable contracting between European fragrance houses and individual Tamil Nadu farming cooperatives, capturing certified-organic premiums.
- Online Retail:E-commerce platforms serving artisanal soap makers, small-batch cosmetic producers, and wellness entrepreneurs with smaller minimum order quantities.
- Specialty Stores:Physical aromatherapy and natural health retailers catering to consumer-direct therapeutic-grade purchases.
Wholesale retains volume leadership; Direct Sales is gaining share fastest through provenance verification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates bay leaf oil processing demand through Kerala and Tamil Nadu distillation clusters, while regulatory divergence across import markets fragments export compliance requirements for origin-based producers.
India
Kerala's traditional cooperatives and Tamil Nadu's continuous-flow extraction facilities anchor global essential oil supply. FSSAI's tightened synthetic preservative restrictions accelerate domestic cosmetic brand migration toward natural antimicrobial alternatives. Chromatographic fingerprinting capabilities concentrate in Kochi and Coimbatore processing hubs as ISO 4720 certification premiums expand.
United States
Wellness retail channels and aromatherapy-grade positioning drive therapeutic demand through FDA GRAS self-affirmation pathways. EPA registration requirements for antimicrobial claims constrain product positioning in household applications. Direct-procurement platforms disintermediate traditional trading hierarchies as California and New York-based fragrance houses establish blockchain-traceable contracting relationships.
Germany
REACH Annex XIV authorization timelines for skin-sensitizing substances accelerate cosmetic formulator reformulation toward eugenol-dominant variants. EU Green Deal bioeconomy incentives subsidize carbon-negative distillation technology adoption. Fragrance compounders in Hamburg and Frankfurt anchor substitution programs ahead of 2027 cinnamaldehyde sunset dates.
France
Fine fragrance houses prioritize batch-to-batch consistency for IFRA-compliant concentration limits in leave-on cosmetic applications. ANSM oversight of cosmetic safety dossiers tightens documentation burdens for botanical extract imports. Grasse-based perfumery laboratories validate chromatographic authenticity protocols enabling provenance-verified price premiums.
Madagascar
Specialty spice exporters adopt microwave-assisted extraction systems to compress cycle times and enable farm-gate value capture. The country's national agricultural regulator monitors export quality standards for essential oil shipments. Artisanal producers in Antananarivo processing zones leverage 2.45 GHz technology to reduce minimum viable scale thresholds.
Bay Leaf Oil Market Competitive Environment
Capacity expansion dominates the current landscape as extraction technology transitions reshape competitive positioning. The vendor base separates into capital-intensive CO2 extraction operators, traditional steam distillation cooperatives, and biotechnology-derived alternative producers. Three strategic archetypes define the field: provenance-verified organic specialists, industrial-scale pharmaceutical-grade suppliers, and fermentation-based eugenol competitors. Geographic expansion through direct-procurement platforms and portfolio diversification into compounded fragrance oils represent the dominant competitive moves.
Within the industrial-scale tier, BASF SE and DSM exemplify capacity-driven positioning through pharmaceutical contract manufacturing relationships. Givaudan International SA anchors the fragrance-grade supply security archetype through Mediterranean grower networks. Symrise AG occupies the biotechnology investment vector targeting batch-to-batch variability reduction. These three companies represent distinct strategic postures rather than interchangeable competitors.
| Leading Market Players |
|---|
| BASF SE |
| DSM |
| Croda International |
| Givaudan International SA |
| Symrise AG |
| International Flavours and Fragrances Inc. |
| Biolandes SAS |
| Aryan International |
| Essential Oils Company |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between ISO 4720-verified essential oils and commodity fragrance compounds manifests in parallel supply chain configurations, with Kerala's chromatography-equipped cooperatives commanding 25-40% premiums over Tamil Nadu's conventional processors while synthetic eugenol from petrochemical routes compresses mid-tier margins.
Pricing Analysis
Volume concentrates in food-grade flavoring oils traded on spot markets, while margin capture tilts toward pharmaceutical and aromatherapy certifications requiring batch-specific chromatographic documentation. Three-tier pricing structure across certified-organic, conventional essential, and compounded fragrance grades reflects divergent quality gateways and buyer price sensitivity. Pricing pressure stems from fermentation-derived eugenol substitution by biotechnology leaders, eroding natural oil competitiveness in price-sensitive fragrance compound formulations. Industrial meat processors exhibit highest price sensitivity through specification-driven drum-quantity contracting, while European fragrance houses demonstrate lowest sensitivity for provenance-verified organic grades.
Supply Chain Analysis
ISO 4720 certification gating concentrates qualified supply in India's Kerala and Tamil Nadu processing clusters, with Madagascar's emerging microwave-assisted extraction operations adding artisanal capacity. Raw material flows draw from Mediterranean Laurus nobilis growers, Indian domestic leaf collections, and Southeast Asian spice trading networks. Single-source vulnerability runs through Kerala's aging gas chromatography-mass spectrometry technician pool as analytical expertise concentrates among retiring specialists. Distribution runs through spice trading houses for bulk wholesale, direct-procurement platforms for certified-organic premiums, and e-commerce channels for artisanal small-batch buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
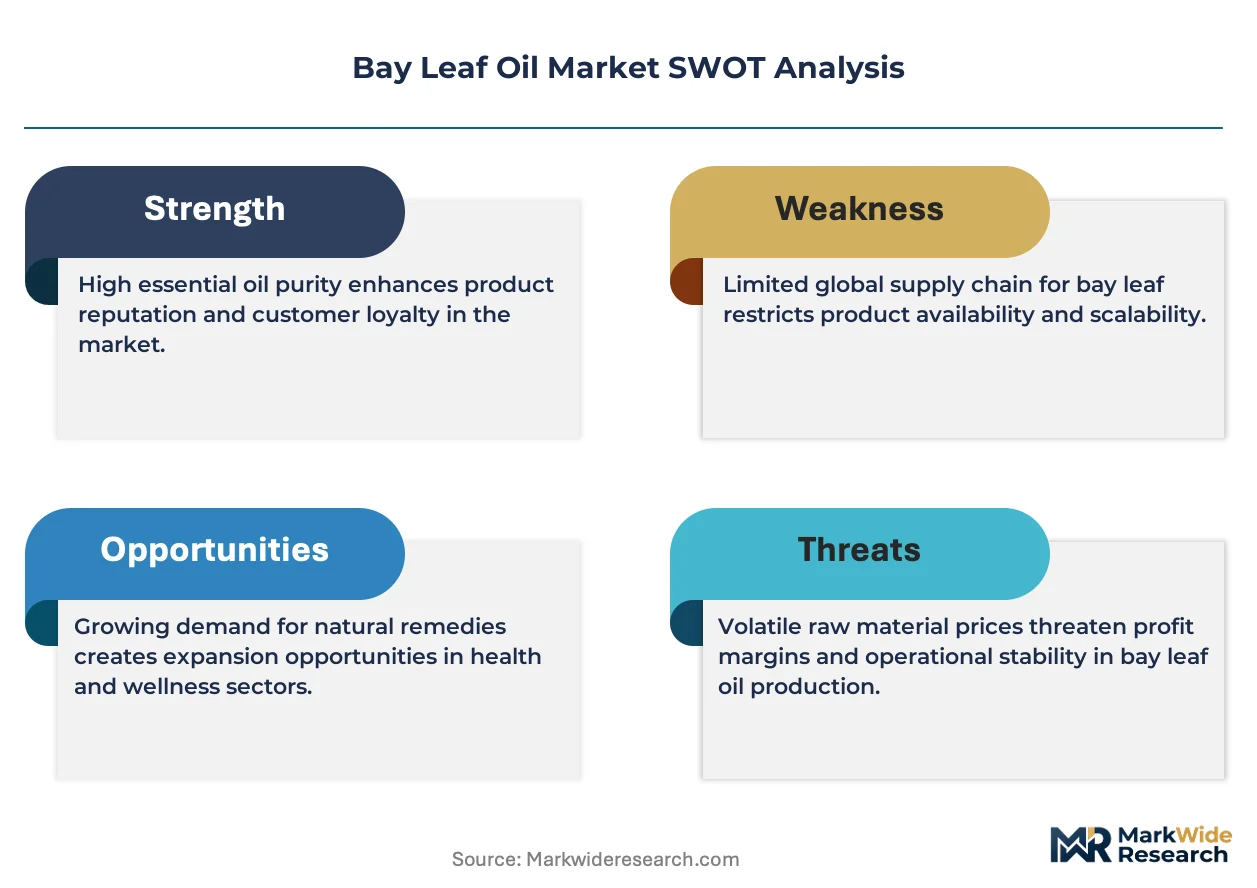
Analytical chemist scarcity in Kerala's traditional cooperatives props pricing for chromatography-certified grades, constraining supply elasticity and sustaining premium capture for authentication-capable processors.
For Market Incumbents: Hedge synthetic eugenol substitution risk by deepening captive sourcing relationships with Mediterranean growers and accelerating continuous-flow extraction efficiency investments in Tamil Nadu. Prioritize ISO 4720 certification infrastructure to defend margin position against biotechnology-derived alternatives from fragrance compound leaders. Channel control through blockchain-traceable direct contracting with European buyers offers pricing power insulation from commodity spot volatility. For New Entrants and Emerging Players: Begin with underpenetrated North American therapeutic wellness channels where FDA GRAS self-affirmation pathways remain underutilized for aromatherapy-grade positioning. Madagascar's microwave-assisted extraction technology enables farm-gate value capture with compressed minimum viable scale thresholds, offering a white-space entry point outside India's concentrated processing clusters. A specialty spice exporter positioning with 2.45 GHz extraction systems and blockchain provenance documentation captures clean-label premium migration. For Investors and Strategic Acquirers: Re-rating potential sits with chromatography-certified organic specialists given EU Green Deal bioeconomy incentives subsidizing carbon-negative distillation technology adoption. Long-term viability across the analysis window favors processors with validated GMP supply relationships to pharmaceutical contract manufacturers over commodity fragrance compounders exposed to synthetic substitution. The signal to watch is REACH Annex XIV authorization timeline acceleration for cinnamaldehyde-containing botanicals, which would accelerate eugenol-dominant variant demand and reshape acquisition target valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mediterranean Grower Networks | Givaudan's captive sourcing model secures fragrance-grade leaf supply against drought-driven raw material volatility. |
| Continuous-Flow Extraction Technology Adoption | Tamil Nadu processors reduce energy intensity per liter while scaling ISO 4720-certified output for pharmaceutical buyers. |
| Blockchain-Traceable Direct Procurement Platforms | European fragrance houses bypass traditional spice trading hierarchies to capture 25-40% certified-organic price premiums. |
| Carbon-Negative Distillation Infrastructure | EU Green Deal subsidies enable German compounders to meet ECHA sustainability documentation requirements ahead of competitors. |
| Pharmaceutical GMP Supply Relationship Validation | BASF SE anchors industrial-scale positioning through antibiotic API producer co-processing partnerships with audit-ready documentation. |
Study Parameters
Trade customs databases, FSSAI regulatory filings, and ISO certification registries formed the secondary backbone, supplemented by primary interviews with Kerala distillation cooperative managers, Tamil Nadu continuous-flow facility engineers, European fragrance house procurement directors, and pharmaceutical contract manufacturing quality officers. Bottom-up and top-down triangulation validated volume estimates across extraction method, certification grade, and end-use application segments.
Bottom-up modeling anchored projections in individual processor capacity, leaf supply contracts, and batch yield data, while top-down cross-checks applied end-use industry consumption coefficients across food flavoring, cosmetics, aromatherapy, and pharmaceutical applications. Segmentation dimensions included product type purity specification, application regulatory pathway, end-user scale economics, and sales channel traceability depth. CAGRs were derived from fitted growth curves incorporating FSSAI preservative restriction timelines, REACH authorization sunset dates, and clean-label migration elasticities.
Underlying measurement precision varies by segment; ISO 4720-certified essential oils carry tighter precision than compounded fragrance oils due to chromatographic documentation availability. Forecasts incorporate assumptions around synthetic eugenol substitution rates, drought cycle frequency in Mediterranean growing regions, and analytical chemist pipeline replenishment in Kerala. A model refresh is warranted upon material change in REACH Annex XIV authorization timelines or EU Green Deal bioeconomy subsidy disbursement rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Casein Market
Ingredients
Mexico Sodium Reduction Ingredients Market
Ingredients
Soy Protein Concentrate Market
Ingredients
Hen Egg White Protein Market
Ingredients
Sunflower Meal Market
Ingredients
Milk Mineral Concentrate Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
Baobab Powder Market
Ingredients
North America Gluten Free Flour Market
Ingredients
Cold Pressed Oil Market
Ingredients
Energy Ingredients Market
Ingredients
Pet Food Ingredients Market
Ingredients
Sugared Egg Yolk Market
Ingredients
Europe Protein Market
Ingredients
Potato & Yam Derivatives Market