
 China Beer Adjuncts Market | 2026-2036
China Beer Adjuncts Market Size, Share, and Industry Trends Forecast 2026-2036
China Beer Adjuncts Market Insights
Market Context
Direct procurement channels between adjunct suppliers and brewery groups is rewriting traditional distribution economics in China's brewing sector. Tsingtao Brewery sustains backward integration into rice and barley sourcing across Shandong and Heilongjiang growing regions. China Resources Beer leverages its state-backed logistics network to control inbound grain flows to thirty-plus production sites. Anheuser-Busch InBev competes through contracted sorghum programs with cooperatives in Inner Mongolia and Liaoning.
Technical Definition and Segment Structure
Beer adjuncts comprise unmalted cereal grains—principally rice, corn, and sorghum—added to the mash bill at substitution rates of 20-40% to dilute protein content, lighten body, and reduce raw material costs while maintaining enzymatic conversion during lautering. Their primary commercial purpose is to standardize wort fermentability and extend production volume for mass-market lagers without sacrificing alcohol yield per hectoliter. Rice dominates product type volume due to its neutral flavor profile and established milling infrastructure in Yangtze River Delta states, though sorghum gains traction among craft breweries seeking regional terroir differentiation. Microbreweries represent the fastest-expanding end user category as smaller batch sizes tolerate higher per-kilogram adjunct costs for specialty flavor outcomes.
Regulatory Framework and Outlook
SAMR enforces GB standards for brewing grain mycotoxin limits and labeling disclosures, while the MIIT oversees energy-efficiency benchmarks in adjunct processing facilities that shape capital investment timelines. China's dual carbon goals from MEE are pressuring large-scale breweries to document supply chain emissions from rice paddies and cornfields through to malting adjuncts. Stakeholders must monitor whether stricter carbon accounting rules will favor locally sourced sorghum over imported barley substitutes.
Market Dynamics
Direct procurement channels between adjunct suppliers and brewery groups are rewriting traditional distribution economics in China's brewing sector. Tsingtao Brewery sustains backward integration into rice and barley sourcing across Shandong and Heilongjiang growing regions.
Growth Catalysts
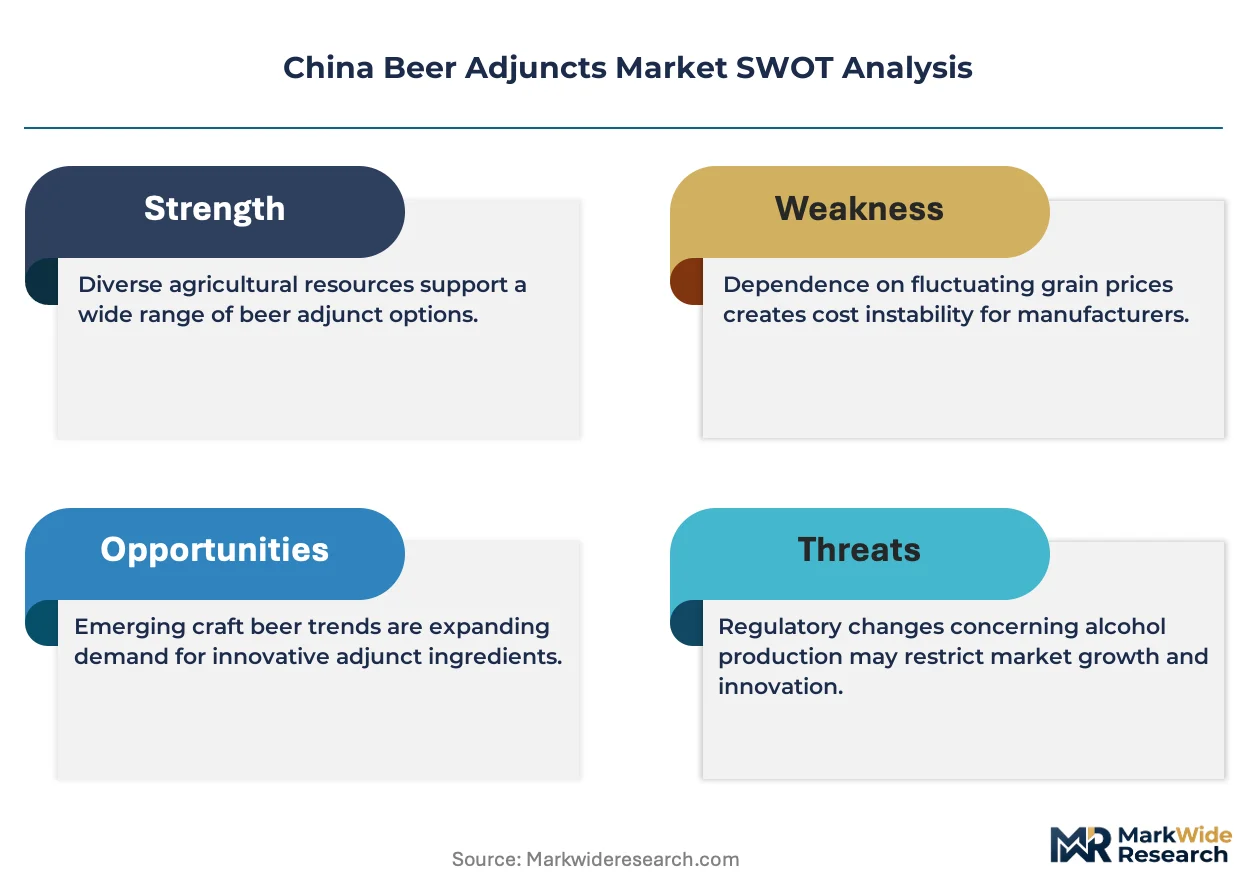
- Dual carbon goals from MEE:Pressure on large-scale breweries to document supply chain emissions from rice paddies and cornfields through to malting adjuncts is accelerating investment in traceability infrastructure.
- Craft brewery expansion:Microbreweries represent the fastest-expanding end user category as smaller batch sizes tolerate higher per-kilogram adjunct costs for specialty flavor outcomes.
- Shandong Province demand concentration:Tsingtao Brewery and multiple mid-sized maltsters anchor regional procurement, creating dense supplier networks that reduce logistics friction for rice and sorghum deliveries.
Market Restraints
- Input cost volatility in corn:Weather-driven yield fluctuations in Northeast China growing regions create margin compression for brewers locked into annual sorghum and corn contracts.
- SAMR contaminant testing expansion:Updated GB standards for brewing grain mycotoxin limits now require stricter testing protocols that extend certification timelines for new suppliers.
- Technical limitation in enzymatic conversion:Substitution rates above 40% for unmalted cereal grains risk incomplete starch conversion during lautering, capping cost-reduction potential for mass-market lager production.
Strategic Opportunities
- Inner Mongolia sorghum programs:Contracted cultivation with agricultural cooperatives offers brewers terroir differentiation and supply security outside volatile rice import channels.
- MIIT energy-efficiency benchmarks:Processing facility upgrades to meet industrial efficiency standards unlock subsidized financing for adjunct millers modernizing drying and storage infrastructure.
- Direct-to-brewery digital platforms:Emerging B2B grain marketplaces are disintermediating traditional distributor layers, enabling smaller breweries to source specialty adjuncts without volume minimums.
Industry Challenges
- Mycotoxin testing laboratory capacity:SAMR's expanded GB standards have created bottlenecks in certified testing facilities, delaying new supplier qualification timelines by months.
- Legacy malting system compatibility:Retrofitting existing brewhouses for variable adjunct ratios requires capital investment in mash tun agitation and lautering equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Beer Adjuncts Market |
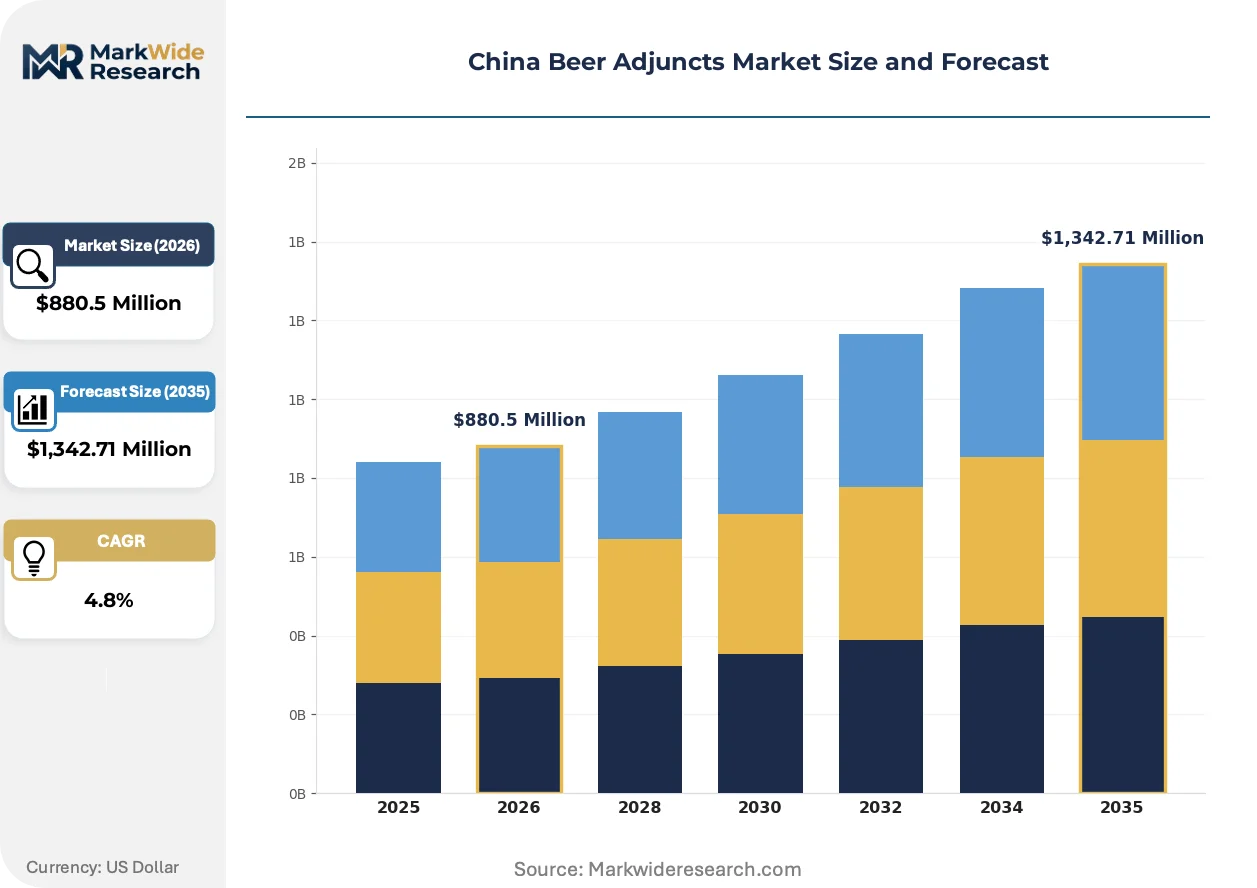
| Market Size in 2026 | $880.5 Million |
| Market Size in 2035 | $1,342.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rice, Corn, Sorghum, Oats, Wheat, Barley Application: Lager, Ale, Stout, Porter, Pilsner, Wheat Beer End User: Microbreweries, Craft Breweries, Large-scale Breweries, Contract Brewers, Brewpubs Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores, Wholesale Markets |
| Companies Covered | China Resources Beer (Holdings) Company Limited, Tsingtao Brewery Co., Ltd, Anheuser-Busch InBev, Beijing Yanjing Brewery, Carlsberg A/S, Guangzhou Zhujiang Brewery Co., Ltd, Budweiser APAC, Hangzhou Cheerday Brewery Co., China Resources Enterprise, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Beer Adjuncts Market Trends and Innovations
China's beer adjuncts sector is experiencing accelerated transformation through regulatory tightening, craft brewery experimentation, and supply chain digitization. These forces are compressing traditional procurement cycles while opening new technical pathways for differentiation.
Near-infrared spectroscopy is digitizing quality assurance workflows across adjunct receiving and storage operations. Mid-sized maltsters in Shandong and Jiangsu provinces are deploying handheld NIR units to verify protein and moisture content in rice and sorghum deliveries within minutes rather than hours. This technology is digitizing supplier scorecards and enabling real-time rejection of out-of-specification grain batches before unloading.
SAMR enforcement of updated GB standards for brewing grain mycotoxin limits is reshaping supplier qualification protocols. The regulation mandates documented testing for aflatoxin and deoxynivalenol across all unmalted cereal inputs, forcing breweries to maintain certified laboratory relationships or invest in in-house chromatography capacity. Large-scale lager producers with centralized procurement functions are absorbing compliance costs more readily than fragmented craft brewery segments.
Brewery technical staffs are rotating toward direct sourcing relationships with agricultural cooperatives, bypassing traditional grain trading houses. This pattern is most visible in Liaoning and Heilongjiang provinces, where craft breweries contract specific sorghum varieties for single-batch releases. Cooperative contracts specify harvest timing and drying protocols that trading intermediaries previously obscured, giving brewers control over flavor precursor development in their adjunct inputs.
China Beer Adjuncts Market Segmentation
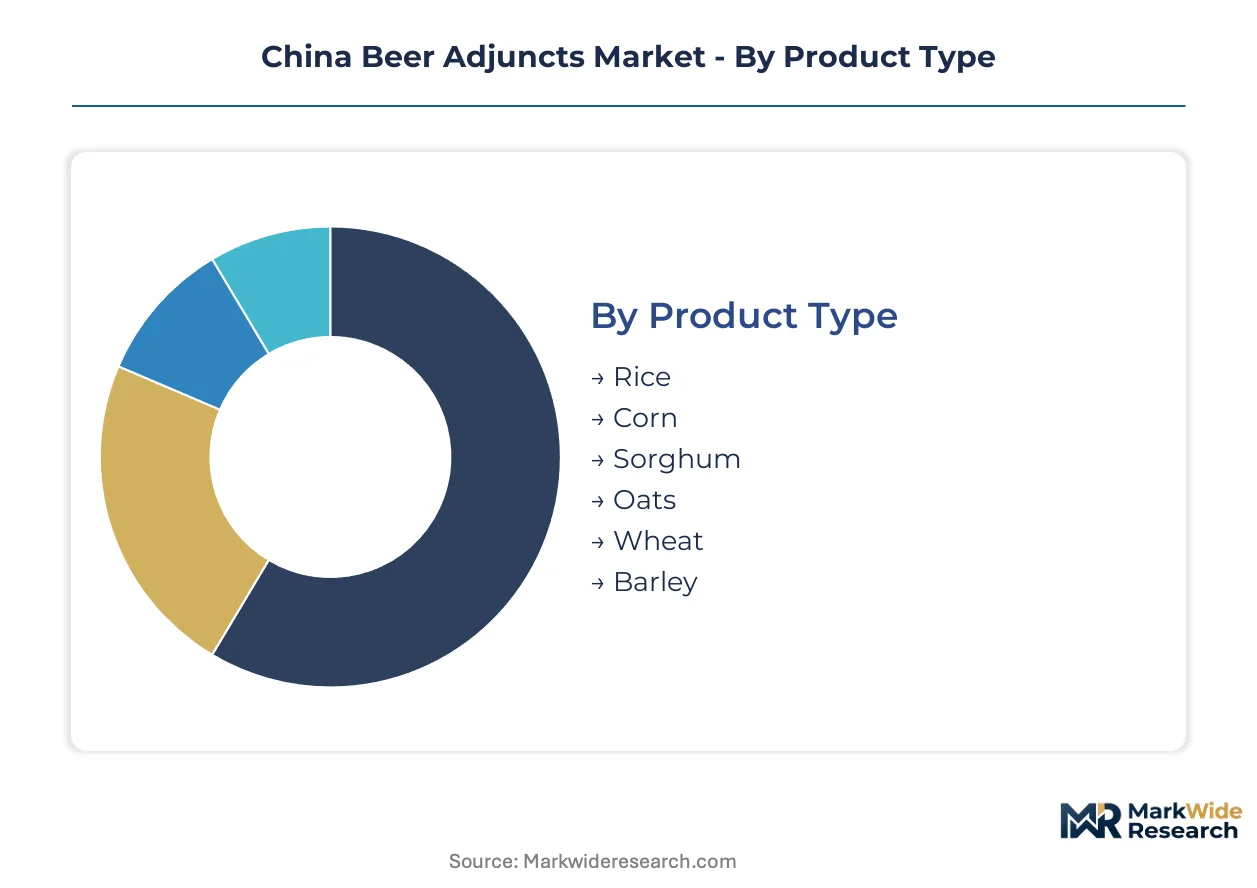
China's beer adjuncts market fragments across grain types, brewing applications, and procurement channels that each impose distinct technical specifications and margin structures. Understanding these segment boundaries clarifies where supplier power concentrates and where new entrants can bypass entrenched intermediaries.
Product Type:
The use-case spectrum spans mass-market lagers demanding neutral flavor carriers through craft experiments seeking regional terroir expression.
- Rice:Milled to 85-90% extraction rates with protein content below 7%, this adjunct delivers the cleanest enzymatic conversion profile for high-adjunct lager recipes. Procurement concentrates in Jiangsu and Anhui provinces where Tsingtao Brewery and China Resources Beer maintain captive milling relationships. Cost stability from domestic harvests makes rice the default choice for volume producers managing thin margins.
- Sorghum:Red and white varietals from Inner Mongolia and Liaoning offer phenolic complexity and drought-resistant supply security that rice imports cannot match. Craft breweries in Beijing and Shanghai contract specific harvest lots for single-batch releases, absorbing 15-20% per-kilogram premiums for documented provenance.
- Corn:Yellow dent varieties from Northeast China provide the lowest-cost starch source for economy lager production.
- Oats:Rolled or flaked formats add mouthfeel body to oatmeal stouts and specialty ales.
- Wheat:Unmalted soft wheat varieties support Belgian-style witbier formulations.
- Barley:Unmalted feed-grade barley functions as cost diluent where malting quality specifications are relaxed.
Established volume favors rice; emerging adoption favors sorghum.
Application:
Substitution rates and enzymatic tolerance vary sharply across beer styles, creating tiered technical barriers for adjunct suppliers.
- Lager:Mass-market pale lagers tolerate 30-40% adjunct ratios, the highest technically permissible before lautering efficiency collapses. This segment consumes over half of national rice and corn adjunct volume through Tsingtao Brewery and China Resources Beer procurement.
- Ale:Top-fermented styles typically restrict adjuncts to 10-15% to preserve malt-forward flavor balance, though fruit-forward sub-styles experiment with sorghum and oat additions.
- Stout:Dark roasted malts mask adjunct character, permitting oat and unmalted barley use for body extension.
- Porter:Similar technical parameters to stout with lower roast intensity.
- Pilsner:German-style purity conventions limit adjunct acceptance, though Czech-variant producers in China increasingly relax this constraint.
- Wheat Beer:Unmalted wheat adjuncts support traditional formulations alongside malted wheat base.
Volume concentration sits with lager; steepest expansion trajectory belongs to ale as craft capacity multiplies.
End User:
Procurement scale and specification tolerance divide end users into volume-driven majors and flexibility-seeking independents.
- Large-scale Breweries:Tsingtao Brewery, China Resources Beer, and Anheuser-Busch InBev operate dedicated adjunct milling facilities or backward-integrated sourcing programs. Their annual procurement volumes justify direct supplier relationships that bypass distributor markups entirely.
- Craft Breweries:Smaller batch sizes and flavor experimentation priorities enable 2-3x per-kilogram spending on specialty sorghum and oat varieties. Liaoning and Heilongjiang cooperative contracts supply this segment's provenance documentation requirements.
- Microbreweries:Sub-1,000 hectoliter annual output tolerates highest unit costs for differentiated inputs.
- Contract Brewers:White-label production for retail and hospitality brands demands flexible adjunct sourcing without capital investment.
- Brewpubs:On-premise consumption models prioritize story-driven ingredient provenance over cost minimization.
Procurement leverage favors large-scale breweries; sourcing agility favors microbreweries.
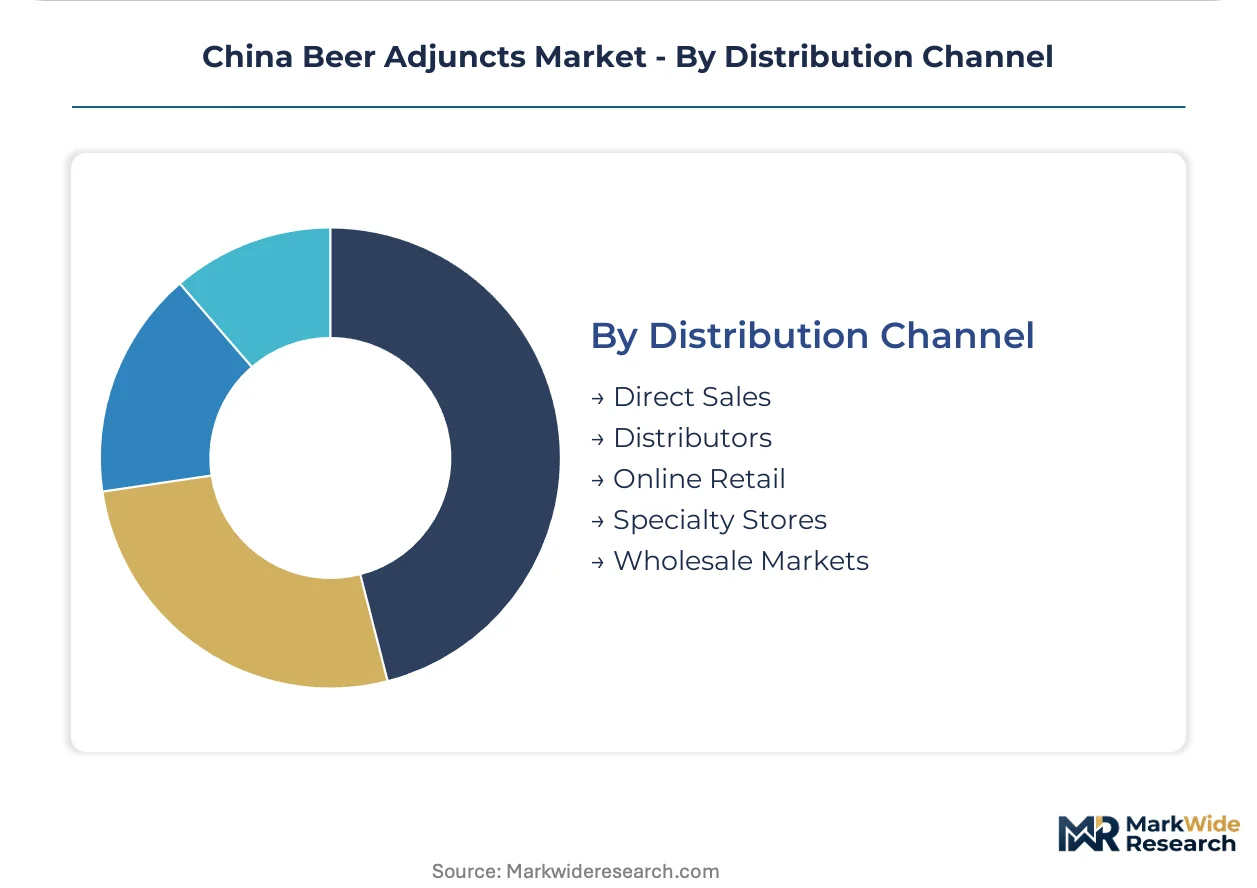
Distribution Channel:
Channel selection determines certification burden, payment terms, and minimum order thresholds that filter supplier accessibility.
- Direct Sales:Brewery groups with annual adjunct demand exceeding 50,000 metric tons negotiate direct contracts with rice millers and grain cooperatives. This channel eliminates 8-12% distributor margins but requires in-house logistics and SAMR compliance documentation.
- Distributors:Regional grain trading houses aggregate smaller brewery orders and manage mycotoxin testing certification. Shandong Province hosts the densest distributor network, serving mid-sized maltsters without direct procurement infrastructure.
- Online Retail:Emerging B2B platforms enable 500-kilogram minimum orders for craft breweries seeking specialty adjuncts.
- Specialty Stores:Localized ingredient suppliers serve homebrew and nano-brewery segments.
- Wholesale Markets:Traditional agricultural commodity exchanges supply economy-grade corn and barley with minimal quality assurance.
Cost efficiency favors direct sales; accessibility favors distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial procurement policies under China's dual carbon goals from MEE are redirecting adjunct sourcing toward localized supply chains. Sub-regional brewing clusters now compete on traceability infrastructure and cooperative contracting models.
Shandong Province
Tsingtao Brewery anchors rice and barley procurement across the Shandong Peninsula, with backward integration into captive milling facilities in Qingdao and Weifang. SAMR's updated GB standards for mycotoxin testing have consolidated supplier qualification around three certified laboratory partnerships in Jinan. The province's dense maltster network reduces logistics friction for sorghum deliveries from neighboring Hebei.
Heilongjiang Province
Northeast China corn production supplies economy lager adjunct demand through contracted harvest programs with agricultural cooperatives in Harbin prefecture. MIIT energy-efficiency benchmarks for grain processing facilities have accelerated drying infrastructure upgrades in Suihua and Qiqihar. Cold-chain storage investments in Daqing support year-round adjunct availability despite seasonal harvest windows.
Inner Mongolia
Drought-resistant sorghum cultivation in Hohhot and Ordos prefectures offers craft breweries terroir differentiation outside volatile rice import channels. The region's cooperative contracting model specifies harvest timing and drying protocols that trading intermediaries previously obscured. Carbon accounting documentation from paddies to malting adjuncts is advancing fastest here due to MEE pilot programs.
Liaoning Province
Shenyang and Dalian brewing clusters source specialty sorghum varieties for single-batch craft releases through direct cooperative relationships. Near-infrared spectroscopy deployment in Dalian port facilities accelerates quality verification for inbound grain shipments. The province's logistics connectivity to Beijing-Tianjin-Hebei consumption centers reduces last-mile distribution costs for premium adjunct grades.
Jiangsu Province
Yangtze River Delta rice milling infrastructure concentrates in Suzhou and Wuxi, serving China Resources Beer procurement across thirty-plus production sites. Handheld NIR units are digitizing supplier scorecards for protein and moisture verification within minutes of delivery. Provincial environmental regulations under MEE dual carbon goals are pressuring facilities to document supply chain emissions from paddy to brewhouse.
China Beer Adjuncts Market Competitive Landscape
On the supply side, the industry is consolidating around brewery groups with captive sourcing infrastructure and fragmented among specialty suppliers serving craft experimentation. Three strategic archetypes dominate: state-backed volume producers with logistics networks, multinational brewers with contracted cooperative programs, and regional craft specialists with provenance-focused procurement. Competitive moves center on backward integration into grain sourcing and digitization of supplier qualification workflows.
Among state-backed volume producers, China Resources Beer (Holdings) Company Limited and Tsingtao Brewery Co., Ltd exemplify the integrated sourcing archetype, each maintaining direct procurement channels that bypass traditional distributor markups. Anheuser-Busch InBev occupies a position representing multinational brewers leveraging contracted sorghum cultivation for supply security. These three anchors illustrate how scale-driven procurement leverage competes against agility-focused craft sourcing models.
| Leading Market Players |
|---|
| China Resources Beer (Holdings) Company Limited |
| Tsingtao Brewery Co., Ltd |
| Anheuser-Busch InBev |
| Beijing Yanjing Brewery |
| Carlsberg A/S |
| Guangzhou Zhujiang Brewery Co., Ltd |
| Budweiser APAC |
| Hangzhou Cheerday Brewery Co. |
| China Resources Enterprise |
| Others |
Pricing and Supply Chain Analysis
Commodity volatility in Northeast China corn harvests determines both pricing tier spreads and supply chain shape across China's beer adjuncts sector. Weather-driven yield fluctuations compress margins for brewers locked into annual contracts while forcing procurement diversification into Inner Mongolia sorghum and Yangtze River Delta rice channels.
Pricing Analysis
Certification level under SAMR's updated GB standards creates the primary spread between premium and economy adjunct tiers. Pricing stratifies across documented mycotoxin testing compliance, with large-scale breweries absorbing centralized laboratory costs while craft operators face 15-20% per-kilogram premiums for provenance-verified sorghum lots. Cost compression in economy corn adjuncts is intensifying because of harvest volatility in Heilongjiang growing regions. Large-scale lager producers exhibit lowest price sensitivity due to backward-integrated sourcing, whereas microbreweries tolerate highest unit costs for flavor differentiation.
Supply Chain Analysis
Upstream rice cultivation concentrates in Jiangsu and Anhui provinces, with sorghum sourcing anchored in Inner Mongolia and Liaoning cooperative programs. The supply chain draws from three distinct feedstock regions: Yangtze River Delta milling infrastructure, Northeast China corn belts, and drought-resistant sorghum zones. Single-source vulnerability exists for rice-dependent brewers exposed to import channel disruption. Distribution runs through direct procurement contracts for volume majors and regional grain trading houses for mid-sized maltsters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's beer adjuncts market is entering a cyclical recovery phase as MEE dual carbon goals force supply chain reinvestment and SAMR regulatory tightening consolidates supplier qualification around certified testing infrastructure.
For Market Incumbents: Harden backward integration into captive milling facilities to defend against distributor margin erosion and emerging B2B platform disintermediation. Expand direct cooperative contracting in Inner Mongolia and Liaoning to secure sorghum supply outside volatile rice import channels. Prioritize NIR spectroscopy deployment across receiving operations to accelerate quality verification and reduce out-of-specification rejection costs.
For New Entrants and Emerging Players: Pursue specialty sorghum and oat segments where provenance documentation commands 15-20% price premiums and volume minimums exclude incumbent distributors. Target Liaoning and Heilongjiang craft brewery clusters with direct cooperative relationships that bypass traditional grain trading houses. Lead with digital platform integration offering 500-kilogram minimum orders without legacy certification bottlenecks.
For Investors and Strategic Acquirers: SAMR's expanded GB standards for mycotoxin testing reshape the acquisition landscape toward certified laboratory assets and compliant milling infrastructure. Position for five-to-ten year viability through mid-cap maltsters with established SAMR partnerships and dense regional supplier networks. Watch for inflection in carbon accounting documentation requirements that would favor localized sorghum sourcing over rice import dependence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Contracting | Direct sorghum programs with Inner Mongolia agricultural cooperatives bypass volatile rice import channels. |
| NIR Spectroscopy Deployment | Handheld units at Shandong and Jiangsu facilities digitize supplier scorecards and accelerate quality verification. |
| Certified Laboratory Partnership Expansion | SAMR-compliant testing capacity in Jinan consolidates supplier qualification timelines for new market entrants. |
| Direct-to-Brewery Digital Platform Launch | B2B grain marketplaces disintermediate traditional distributors and enable craft brewery sourcing without volume minimums. |
| Carbon Accounting Documentation Investment | MEE pilot programs in Inner Mongolia advance supply chain emissions tracking from paddies through malting adjuncts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brewery procurement directors, maltster operations managers, grain cooperative representatives, and SAMR compliance officers. Secondary validation drew from MIIT energy-efficiency filings, SAMR GB standard updates, agricultural customs data, and provincial carbon accounting disclosures. Bottom-up volume modeling across rice, sorghum, corn, and specialty adjunct categories was triangulated against top-down brewery capacity assessments.
Calibration against historical procurement patterns and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include grain type, brewing application, end-user scale tier, and distribution channel structure. CAGRs were derived from trend extrapolation of direct procurement growth, craft brewery expansion rates, and carbon accounting adoption curves. Industry-specific inputs incorporated SAMR certification timeline delays and MEE pilot program geographic rollout patterns.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, currency fluctuation in rice import channels, or accelerated SAMR enforcement would shift the trajectory. Forecasts reflect documented assumptions regarding cooperative contracting adoption and laboratory capacity expansion. Cross-checking against provincial agricultural output statistics and brewery group procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Whey Protein Ingredients Market
Ingredients
Cheese Ingredients Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Canola Meal Market
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
Broccoli Powder Market
Ingredients
Global Malt Ingredients Market
Ingredients
Europe Amino Acid Market
Ingredients
Rendered Products Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
Chickpea Protein Ingredients Market
Ingredients
Egg Membrane Powder Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
India Olive Oil Market
Ingredients
Textured Soy Flour Market