
 India Bakery Ingredients Market | 2026-2036
India Bakery Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
India Bakery Ingredients Market Foresight
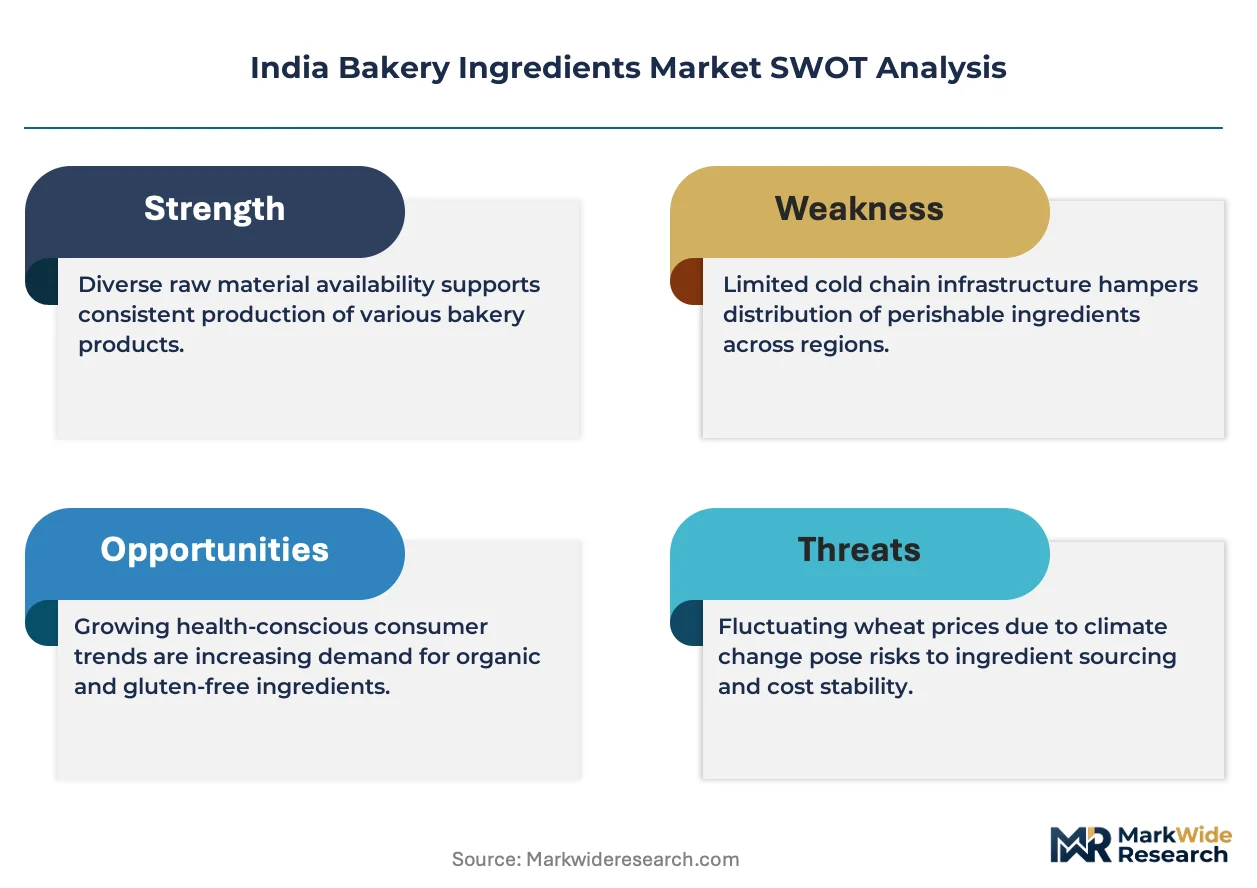
FSSAI licensing under the Food Safety and Standards Act is redrawing competitive access across the India bakery ingredients landscape. Cargill, Incorporated leverages its integrated supply chain from grain sourcing to specialty fat production to sustain volume leadership in western India. Associated British Foods PLC anchors its position through AB Mauri's yeast and bakery ingredient distribution network, which dominates the organized bakery channel. Advanced Enzyme Technologies Ltd differentiates via indigenous enzyme solutions tailored to Indian wheat varietals, competing on cost against imported alternatives.
Bakery ingredients encompass functional inputs including flours, leavening agents, fats, emulsifiers, and enzymes formulated to specific protein content, ash levels, and falling number parameters for controlled fermentation and crumb structure. Their primary commercial purpose is to standardize output quality across high-throughput production environments where batch consistency determines shelf placement and brand equity. Flour and fats together occupy the deepest margin pools given their irreplaceable volume share in formulations and the pricing power conferred by localized milling infrastructure. Yeast is registering the fastest structural expansion as frozen dough adoption spreads from quick-service restaurants into in-store supermarket bakeries, while specialty stores channel remains the most fragmented distribution tier with consolidation pressure building.
FSSAI fortification rules and BIS quality specifications for wheat products shape ingredient procurement by mandating micronutrient premix inclusion and standardized protein grading. The Food Safety and Standards Authority also governs additive limits for emulsifiers and preservatives, directly influencing R&D allocation among domestic compounders. Stakeholders must monitor how state-level enforcement variance between Maharashtra, Karnataka, and Tamil Nadu creates asymmetric compliance costs that will determine regional supplier viability.
Market Dynamics
FSSAI fortification mandates are compressing formulation cycles across India's bakery ingredients sector, forcing premix suppliers to revalidate micronutrient stability under accelerated shelf-life conditions while maintaining dough rheology standards.
Growth Catalysts
- FSSAI Wheat Flour Fortification Rules:Mandatory iron, folic acid, and vitamin B12 inclusion in packaged atta is expanding premix volumes for industrial millers supplying Maharashtra and Karnataka bakery clusters.
- Quick-Service Restaurant Frozen Dough Adoption:QSR chains operating in Bengaluru and Mumbai are converting central kitchens to blast-frozen par-baked formats, pulling demand for high-gluten flour and specialized yeast strains.
- Artisanal Bakery Scaling:Premium sourdough and viennoiserie specialists in Bandra and Indiranagar are consolidating procurement to secure consistent protein content and ash specifications from dedicated millers.
Market Restraints
- Palm Oil Price Volatility:Bakery fat compounders face margin compression from Malaysian crude palm oil futures, which transmit directly to shortening and margarine cost structures.
- Import Dependency for Specialty Enzymes:Fungal alpha-amylase and xylanase supplies concentrate among three European producers, exposing Indian compounders to freight and currency risk.
- BIS Certification Timelines:Bureau of Indian Standards testing protocols for new emulsifier blends extend 14-18 months, freezing formulation pipelines for clean-label launches.
Strategic Opportunities
- Tamil Nadu Organized Retail Expansion:Reliance Fresh and Spencer's in-store bakery formats in Chennai and Coimbatore are underpenetrated versus western India, creating first-mover space for yeast and premix distributors.
- PLI Scheme for Food Processing:Production-linked incentives for cold chain infrastructure reduce frozen dough logistics costs, enabling QSR backward integration into captive ingredient blending.
- Clean-Label Emulsifier Convergence:Enzymatic interesterification combined with lecithin fractionation is opening reformulation pathways for trans-fat-free shortenings in premium cookie segments.
Industry Challenges
- Skilled Bakery Technologist Scarcity:Industrial bakers with falling number and farinograph interpretation capabilities are concentrated in Mumbai and Pune, constraining plant expansion in secondary cities.
- Legacy ERP Integration:Mid-tier ingredient distributors in tier-2 markets operate on fragmented inventory systems that cannot reconcile FSSAI batch traceability requirements with real-time stock rotation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Bakery Ingredients Market |
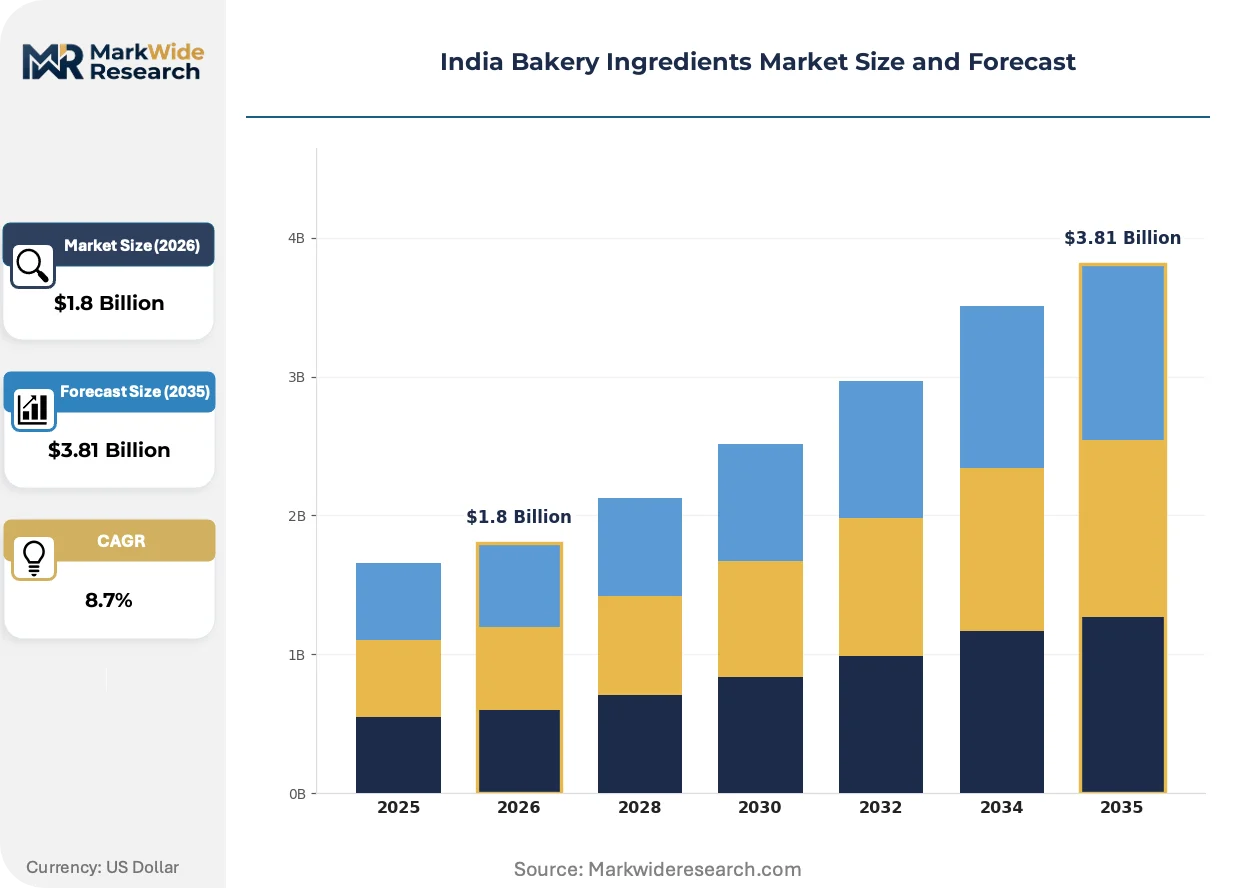
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flour, Sugar, Yeast, Fats End User: Bakeries, Restaurants, Cafes, Retailers Application: Bread, Pastries, Cakes, Cookies Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | DSM-Firmenich AG, Advanced Enzyme Technologies Ltd, Cargill, Incorporated, Tate & Lyle PLC, Dawn Food Products Inc., Associated British Foods PLC, Archer Daniels Midland Co., Ingredion Inc., Puratos NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Bakery Ingredients Market Shifts & Advancements
Ingredient functionality is decoupling from commodity sourcing as enzyme engineering and precision fermentation enable performance claims previously locked to specific wheat origins or fat compositions.
Enzyme-directed dough conditioning is bifurcating the industrial bakery segment between high-throughput plants adopting amylase-glucose oxidase synergies for extended shelf life and artisan operators rejecting any additive declarations. AB Mauri and domestic compounders are field-testing fungal lipase variants that reduce shortening requirements by 12-15% in laminated doughs without texture degradation. The structural consequence is compressing traditional fat supplier margins while expanding enzyme house technical service contracts.
FSSAI's 2023 notification on micronutrient premix stability testing is forcing reformulation of iron encapsulation systems to prevent rancidity in whole wheat flour during monsoon storage. Industrial millers in Nashik and Ahmedabad are revalidating supplier qualifications under accelerated 45°C humidity chamber protocols. The organized retail bakery channel is absorbing most compliance costs through private-label specification tightening, while unorganized biscuit manufacturers face exclusion from institutional procurement.
Direct miller-to-bakery procurement contracts are displacing layered distributor networks in Maharashtra and Karnataka, compressing working capital cycles from 60-day credit to 15-day advance payment with volume rebates. Large bakery chains including Britannia and Parle's institutional divisions are consolidating wheat flour sourcing to three approved millers with captive laboratory facilities. The shift is most visible in Pune's industrial bakery corridor, where ingredient distributors report 30% volume attrition in flour categories over eighteen months.
India Bakery Ingredients Market Segmentation
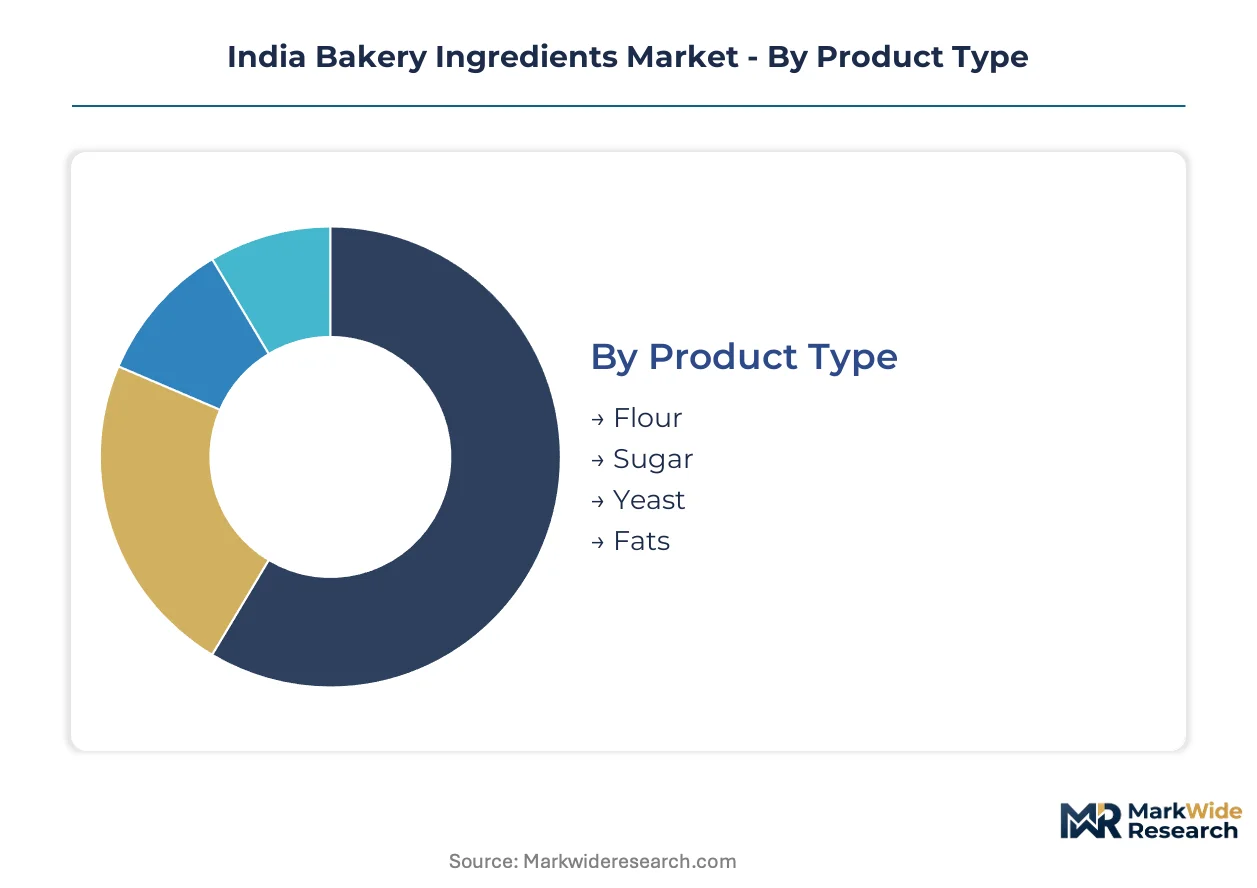
Segmentation in India's bakery ingredients market reveals how FSSAI fortification mandates and frozen dough adoption concentrate procurement power among distinct buyer archetypes. Each dimension exposes different margin pressures and technical service requirements that suppliers must navigate.
Product Type:
FSSAI's wheat flour fortification rules differentiate ingredient categories by micronutrient testing burden and shelf-life validation protocols.
- Flour:High-gluten and whole wheat varieties dominate industrial procurement in Maharashtra and Karnataka, where FSSAI mandates iron and folic acid premix inclusion. Nashik and Ahmedabad millers are requalifying suppliers under accelerated humidity chamber protocols to prevent rancidity during monsoon storage.
- Fats:Shortenings and margarines face margin compression from Malaysian crude palm oil futures volatility. Bakery fat compounders in western India are reformulating with enzymatic interesterification to meet trans-fat-free specifications for premium cookie segments.
- Yeast:Specialized strains for frozen dough applications are climbing fastest as Bengaluru and Mumbai QSR central kitchens convert to blast-frozen par-baked formats.
- Sugar:Refined and specialty sugars serve traditional mithai-influenced bakery applications with stable demand from unorganized biscuit manufacturers.
Established volume favors flour; emerging adoption favors yeast.
End User:
Customer type determines credit cycles and technical service intensity, with organized chains extracting 15-day advance terms versus 60-day distributor credit.
- Bakeries:Artisanal sourdough and viennoiserie specialists in Bandra and Indiranagar consolidate procurement for consistent protein content and ash specifications. These buyers demand falling number and farinograph interpretation support that constrains supplier expansion beyond Mumbai and Pune.
- Restaurants:Hotel and institutional kitchens in Chennai and Coimbatore represent underpenetrated territory versus western India, creating first-mover space for yeast and premix distributors targeting Reliance Fresh and Spencer's supply chains.
- Cafes:Premium coffee chains drive demand for clean-label emulsifiers and specialty fats in laminated dough applications.
- Retailers:In-store supermarket bakery formats absorb most FSSAI compliance costs through private-label specification tightening.
Organized chains command procurement leverage; artisanal operators prize technical partnership.
Application:
Product format dictates enzyme functionality requirements and clean-label positioning trade-offs.
- Bread:Industrial loaf production in Pune's bakery corridor drives amylase-glucose oxidase synergies for extended shelf life. Britannia and Parle's institutional divisions have consolidated flour sourcing to three approved millers with captive laboratory facilities.
- Pastries:Croissant and Danish applications require fungal lipase variants that reduce shortening requirements by 12-15% without texture degradation.
- Cakes:Aerated emulsion stability demands precise emulsifier blends facing 14-18 month BIS certification timelines.
- Cookies:Premium segments lead reformulation toward trans-fat-free shortenings through lecithin fractionation.
Volume concentration sits with bread; margin expansion favors pastries.
Distribution Channel:
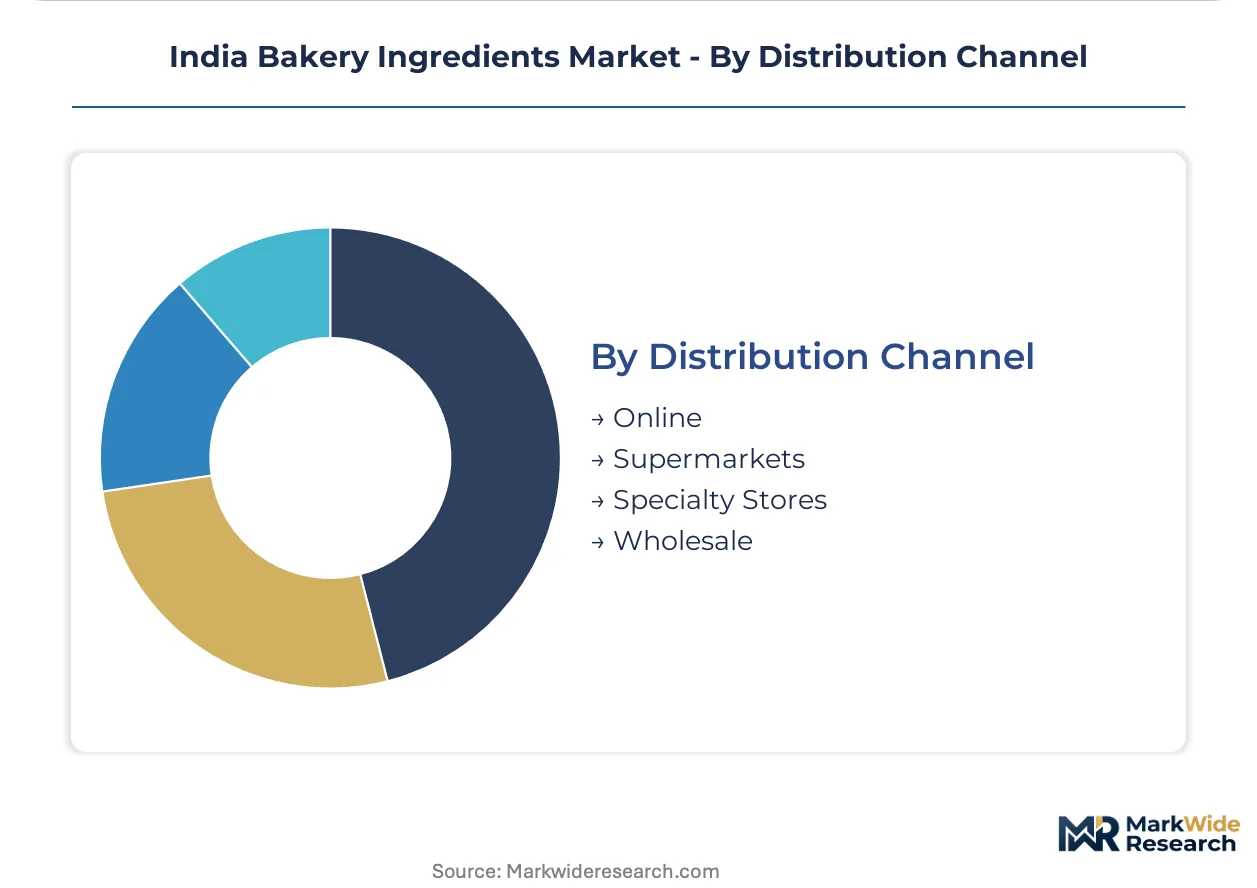
Channel structure determines batch traceability requirements and working capital compression exposure.
- Supermarkets:Organized retail bakery formats in Maharashtra and Karnataka are absorbing FSSAI compliance costs through specification tightening. Direct miller-to-bakery contracts here displace layered distributor networks, compressing credit cycles from 60 days to 15 days with volume rebates.
- Wholesale:Tier-2 market distributors operate on fragmented ERP systems that cannot reconcile FSSAI batch traceability with real-time stock rotation.
- Online:Digital procurement platforms serve artisanal bakers scaling ingredient sourcing with protein content guarantees.
- Specialty Stores:The most fragmented tier faces consolidation pressure as technical service capabilities concentrate among integrated suppliers.
Supermarkets drive contract consolidation; specialty stores lag systems integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI fortification mandates and PLI scheme incentives for food processing infrastructure are redrawing procurement geography across India's bakery ingredients landscape. State-level enforcement variance creates asymmetric compliance costs that concentrate supplier investment in western and southern corridors.
Maharashtra
Mumbai and Pune anchor industrial bakery procurement, with Britannia and Parle consolidating flour sourcing to three approved millers. FSSAI mandates on iron and folic acid premix inclusion drive supplier requalification under accelerated humidity protocols. Nashik millers are revalidating micronutrient stability for monsoon storage conditions.
Karnataka
Bengaluru's QSR central kitchens are converting to blast-frozen par-baked formats, pulling demand for high-gluten flour and specialized yeast strains. The PLI scheme for cold chain infrastructure reduces frozen dough logistics costs. Indiranagar artisanal bakeries consolidate procurement for consistent protein content specifications.
Gujarat
Ahmedabad millers serve as secondary supply nodes for western India bakery clusters facing FSSAI compliance timelines. BIS certification protocols for new emulsifier blends extend formulation pipelines. The state's industrial corridor attracts backward integration from compounders seeking captive blending capacity.
Tamil Nadu
Chennai and Coimbatore represent underpenetrated territory for organized retail bakery formats versus western India. Reliance Fresh and Spencer's in-store bakeries create first-mover space for yeast and premix distributors. State-level enforcement variance with Maharashtra generates compliance cost differentials for national suppliers.
Delhi-NCR
The National Capital Region channels institutional procurement for hotel and airline catering segments requiring standardized ingredient specifications. FSSAI batch traceability requirements strain legacy ERP systems among mid-tier distributors. Haryana's food processing parks attract ingredient compounders seeking tax incentives under state industrial policy.
India Bakery Ingredients Market Competitive Landscape
Player mix skews toward integrated multinational agribusinesses with grain origination capabilities and domestic enzyme specialists competing on cost against imported alternatives. Concentration is moderate at the top tier, with three to four firms controlling volume leadership in wheat derivatives and fermentation inputs. Two strategic archetypes dominate: global traders with captive milling infrastructure and indigenous biotech compounders with varietal-specific formulations. Competitive moves center on direct miller-to-bakery contract displacement of distributor networks and technical service bundling to secure frozen dough accounts.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Co. represent global traders with upstream grain control. Associated British Foods PLC anchors the organized bakery channel through yeast and ingredient distribution reach. Among domestic specialists, Advanced Enzyme Technologies Ltd exemplifies the indigenous enzyme house archetype competing on tailored solutions for Indian wheat varietals. These three firms occupy positions that reflect the market's structural tension between global supply security and local formulation adaptation.
| Leading Market Players |
|---|
| DSM-Firmenich AG |
| Advanced Enzyme Technologies Ltd |
| Cargill, Incorporated |
| Tate & Lyle PLC |
| Dawn Food Products Inc. |
| Associated British Foods PLC |
| Archer Daniels Midland Co. |
| Ingredion Inc. |
| Puratos NV |
| Others |
Supply & Pricing Matrix
Mill-level scale economies in Nashik and Ahmedabad concentrate milling capacity among fewer than two dozen integrated operators, compressing price floors for wheat flour while elevating procurement leverage for organized bakery chains. This concentration transmits directly into shortening and margarine cost structures, where compounders absorb Malaysian crude palm oil volatility through formula adjustments rather than price pass-through.
Pricing Analysis
Certification level creates the primary spread across ingredient tiers, with FSSAI-validated premixes commanding premiums over unfortified alternatives. Three-tier pricing structure across premium, standard, and economy levels segments buyers by technical service intensity and batch traceability guarantees. Cost compression in economy-tier fats is intensifying because palm oil futures transmit directly to bakery shortening formulations. Unorganized biscuit manufacturers exhibit highest price sensitivity, while QSR chains with frozen dough programs prioritize supply security over unit cost.
Supply Chain Analysis
Inventory cycles stretching 45-60 days for imported fungal alpha-amylase expose compounders to freight and currency risk. Supply concentrates in India for wheat milling, Malaysia for crude palm oil derivatives, and Europe for specialty enzyme inputs. Raw material dependencies center on monsoon-dependent wheat harvests, palm oil futures contracts, and single-source fungal culture collections. Single-source vulnerability for xylanase and lipase concentrates threatens formulation continuity. Distribution runs through direct miller-to-bakery contracts in Maharashtra and Karnataka, displacing layered distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial bakers with falling number and farinograph interpretation capabilities remain concentrated in Mumbai and Pune, constraining plant expansion in secondary cities and creating asymmetric technical service requirements that reshape competitive access.
For Market Incumbents: Fortify technical service bundling around frozen dough applications to secure QSR central kitchen contracts against enzyme house competitors. Deepen backward integration into captive wheat milling capacity in Nashik to defend margin position against direct miller-to-bakery contract displacement. Prioritize FSSAI premix validation investments to maintain organized retail bakery channel access as compliance costs escalate. For New Entrants and Emerging Players: Differentiate on indigenous enzyme solutions tailored to Indian wheat varietals, competing against imported alternatives on cost and localization speed. Target Tamil Nadu's underpenetrated organized retail bakery corridor in Chennai and Coimbatore, where Reliance Fresh and Spencer's formats lack dedicated yeast and premix distributors. Pursue technical partnership positioning with artisanal sourdough specialists in Bandra and Indiranagar who prize falling number interpretation support over commodity pricing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic enzyme compounders with varietal-specific formulation libraries over global traders dependent on generic culture collections. Long-term viability hinges on R&D intensity in fungal lipase and glucose oxidase variants as clean-label emulsifier replacements. Acquisition targets should display captive laboratory facilities and FSSAI premix validation capabilities. Watch frozen dough adoption rates in Bengaluru QSR chains as inflection indicator for yeast strain demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheat Milling | Cargill and ADM leverage grain origination control to secure flour supply for western India bakery clusters. |
| Enzyme Technical Service Expansion | Advanced Enzyme Technologies bundles falling number interpretation to anchor artisanal bakery relationships beyond Mumbai. |
| FSSAI Premix Validation Investment | Industrial millers in Nashik requalify suppliers under accelerated humidity protocols to maintain institutional procurement access. |
| Frozen Dough Cold Chain Partnership | PLI scheme incentives enable QSR backward integration into captive ingredient blending with reduced logistics costs. |
| Clean-Label Emulsifier Reformulation | Enzymatic interesterification combined with lecithin fractionation opens trans-fat-free pathways for premium cookie segments. |
Research Methodology
The analysis maps flour milling, fat compounding, enzyme manufacturing, and yeast fermentation sub-sectors, each validated through procurement directors at organized bakery chains, technical service managers at enzyme houses, and FSSAI compliance officers. Primary interviews with plant managers at Nashik and Ahmedabad millers, distribution channel partners in tier-2 markets, and R&D directors at domestic compounders combined with secondary validation. Secondary sources include FSSAI notification records, BIS certification timelines, customs data on enzyme imports, and SEC filings from listed agribusinesses. Bottom-up volume builds from individual facility capacities and top-down demand estimates from bakery production statistics underwent cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end user category, application format, and distribution channel dimensions throughout the forecast period. CAGRs derived from segment-level growth rate assumptions calibrated to capacity expansion announcements and regulatory implementation timelines. Industry-specific forecast inputs incorporated PLI scheme cold chain infrastructure buildout schedules and FSSAI fortification mandate compliance trajectories.
Material uncertainties — palm oil futures volatility, state-level FSSAI enforcement variance, and skilled technologist availability — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation speed and QSR format adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bleached Flour Market
Ingredients
Global Dry Yeast Market
Ingredients
Vital Wheat Gluten Market
Ingredients
Potato & Yam Derivatives Market
Ingredients
Smoked Yeast Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Hydrogenated Starch Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Meat Extract Market
Ingredients
Organic Edible Oil Market
Ingredients
Bulk Food Ingredients Market
Ingredients
GCC Egg Powder Market
Ingredients
North America Milk Protein Market
Ingredients
Europe Edible Oil Market
Ingredients
Self-Rising Flour Market
Ingredients
Middle East and Africa Pea Starch Market