
 Fresh Yeast Market | 2026-2036
Fresh Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Yeast Market Analysis
Consolidation among industrial bakeries and large food manufacturers is realigning procurement volumes toward fewer, larger contracts with dedicated supply agreements. Lesaffre International leverages its European milling and fermentation infrastructure to sustain long-term partnerships with multinational bakery chains. Lallemand, Inc. competes through specialized strains for brewing and distilling applications, while Angel Yeast Co. Ltd. anchors Asia-Pacific supply networks with cost-optimized compressed yeast production.
Fresh yeast comprises living Saccharomyces cerevisiae cells in moist cake or compressed form, typically containing 70% water and requiring refrigeration below 8°C to preserve viability for leavening bread, beer, and bioethanol fermentation. Compressed yeast dominates commercial bakery channels due to its rapid activation and established cold-chain logistics, whereas instant yeast captures household and small-bakery growth through extended shelf stability and dispensing convenience. Liquid yeast maintains niche penetration in craft brewing and pharmaceutical fermentation, where strain-specific inoculation protocols command technical premiums.
The FDA Food Safety Modernization Act and EU Hygiene Regulation impose pathogen-monitoring and cold-chain documentation obligations that elevate compliance costs for cross-border yeast shipments. BIS certification requirements in India and GB standards in China add national testing layers that filter smaller exporters from premium supply tiers. Stakeholders must monitor evolving strain-registration pathways and temperature-excursion liabilities as live-culture logistics complexity intensifies across regulatory jurisdictions.
Market Dynamics
Live-culture cold-chain logistics are reshaping competitive positioning in fresh yeast distribution, as refrigerated transport networks and real-time viability monitoring separate viable suppliers from commodity players unable to sustain temperature integrity across extended supply radii.
Growth Catalysts
- EU Hygiene Regulation:Mandatory pathogen-monitoring protocols for live cultures are professionalizing bakery procurement, driving volume consolidation toward certified cold-chain operators in Germany, France, and Italy.
- Clean-label fermentation:Consumer rejection of chemical leavening agents in artisanal bread is pulling compressed yeast into premium bakery channels previously dependent on instant alternatives.
- Bioethanol strain optimization:Industrial fermentation facilities are expanding fresh yeast inoculation for fuel-grade ethanol production, creating parallel demand streams beyond food applications.
Market Restraints
- Refrigeration energy costs:Compressed yeast's 70% moisture content and sub-8°C storage requirement expose distributors to electricity price volatility and carbon-tax exposure under EU Green Deal frameworks.
- Supply concentration in Western Europe:Milling and fermentation infrastructure clusters in France and Germany, creating geographic vulnerability to regional cold-chain disruptions or energy rationing events.
- Instant yeast substitution:Extended-shelf-life dried alternatives are capturing household and small-bakery segments where refrigeration infrastructure is limited or unreliable.
Strategic Opportunities
- India FSSAI modernization:India's food safety regulator is streamlining live-culture import pathways, opening premium supply tiers for cold-chain-compliant European exporters previously filtered by BIS certification complexity.
- Craft brewing liquid yeast:Strain-specific inoculation protocols in microbreweries are creating technical-premium niches for propagators capable of custom Saccharomyces cerevisiae cultivation.
- Pharmaceutical fermentation:Biologics manufacturers are adopting fresh yeast for precision inoculation in therapeutic protein production, diverting technical-grade supply from commodity channels.
Industry Challenges
- Cold-chain technician scarcity:Refrigerated logistics operations require specialized personnel capable of managing temperature-excursion protocols and live-culture viability documentation, with training pipelines lagging demand in emerging markets.
- Multi-jurisdiction compliance layering:Simultaneous adherence to FDA Food Safety Modernization Act documentation, EU Hygiene Regulation pathogen thresholds, and national certification schemes in India and China strains quality-assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Yeast Market |
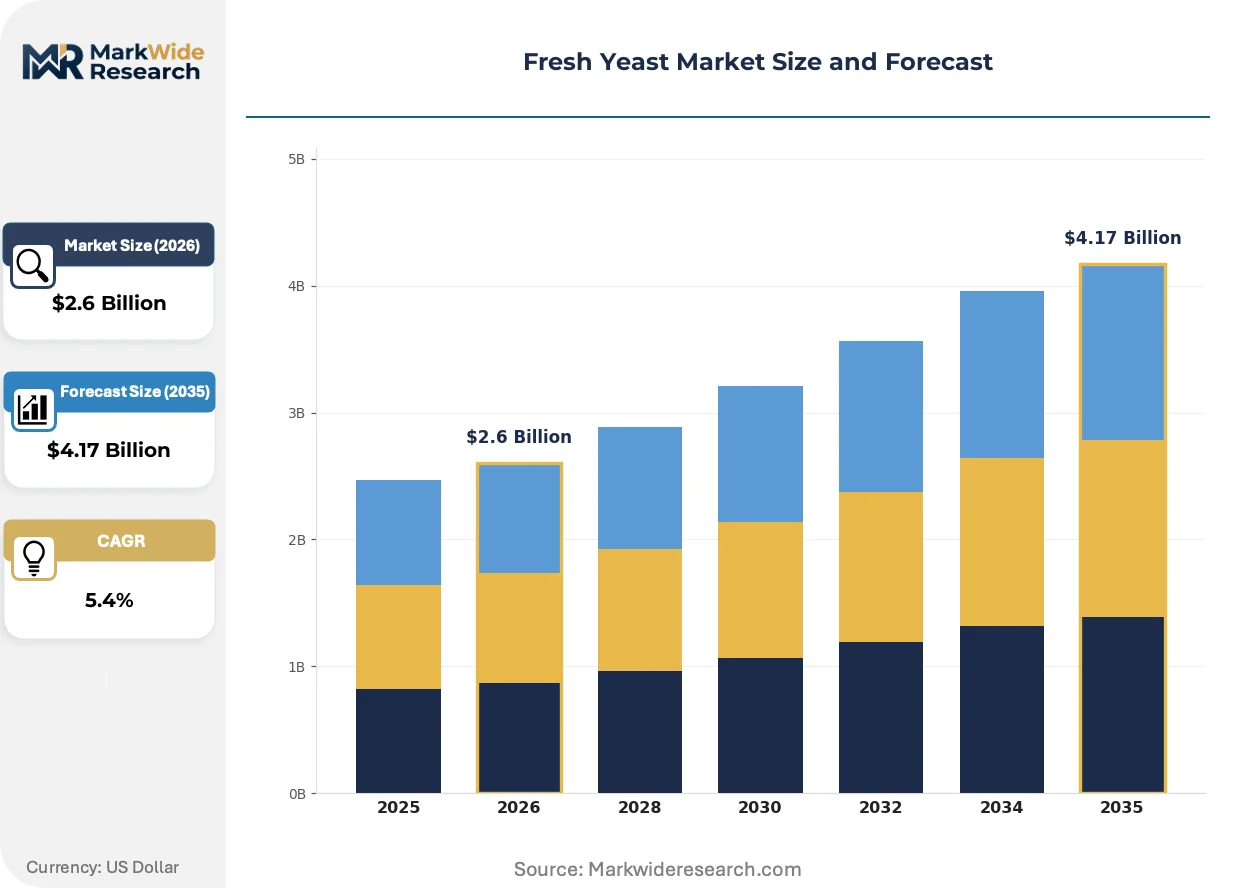
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.17 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressed Yeast, Active Dry Yeast, Instant Yeast, Liquid Yeast Application: Bakery, Brewing, Distilling, Pharmaceuticals End User: Household, Commercial Bakeries, Industrial Bakeries, Food Manufacturers Packaging Type: Bags, Sachets, Jars, Bulk Containers |
| Companies Covered | AB Mauri Foods, Inc., Lesaffre International, Associated British Foods Plc, Lallemand, Inc., Angel Yeast Co. Ltd., Oriental Yeast Co. Ltd., Kerry Group Plc, Koninklijke DSM N.V., Leiber GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Yeast Market Emerging Trajectories
Digital temperature-monitoring infrastructure and strain-banking capabilities are compressing the technical gap between industrial propagators and specialized suppliers, redistributing competitive advantage toward logistics sophistication rather than fermentation scale alone.
Blockchain-enabled cold-chain verification is decentralizing trust mechanisms in live-culture shipments. Artisanal bakeries and craft breweries are adopting distributed-ledger documentation to verify strain provenance and temperature integrity without relying on centralized laboratory certification. This compression of verification costs is enabling smaller propagators to compete for contracts previously reserved to vertically integrated multinationals.
REACH chemical-safety documentation requirements for fermentation byproducts are tightening strain-registration pathways in Europe. Industrial bakeries and bioethanol producers must now submit extended toxicity dossiers for novel Saccharomyces cerevisiae variants, extending product-development timelines and elevating regulatory-affairs overhead. German and French propagators with established registration portfolios are capturing premium-tier supply agreements as competitors face compliance backlogs.
Direct-to-bakery distribution models are displacing traditional wholesale intermediaries in urban markets. Metropolitan artisanal clusters in Milan, Barcelona, and Copenhagen are sourcing compressed yeast through dedicated refrigerated courier networks, bypassing regional distributors and compressing order-to-delivery cycles. This channel restructuring is most visible in European capitals where bakery density supports viable last-mile cold-chain economics.
Fresh Yeast Market Segmentation
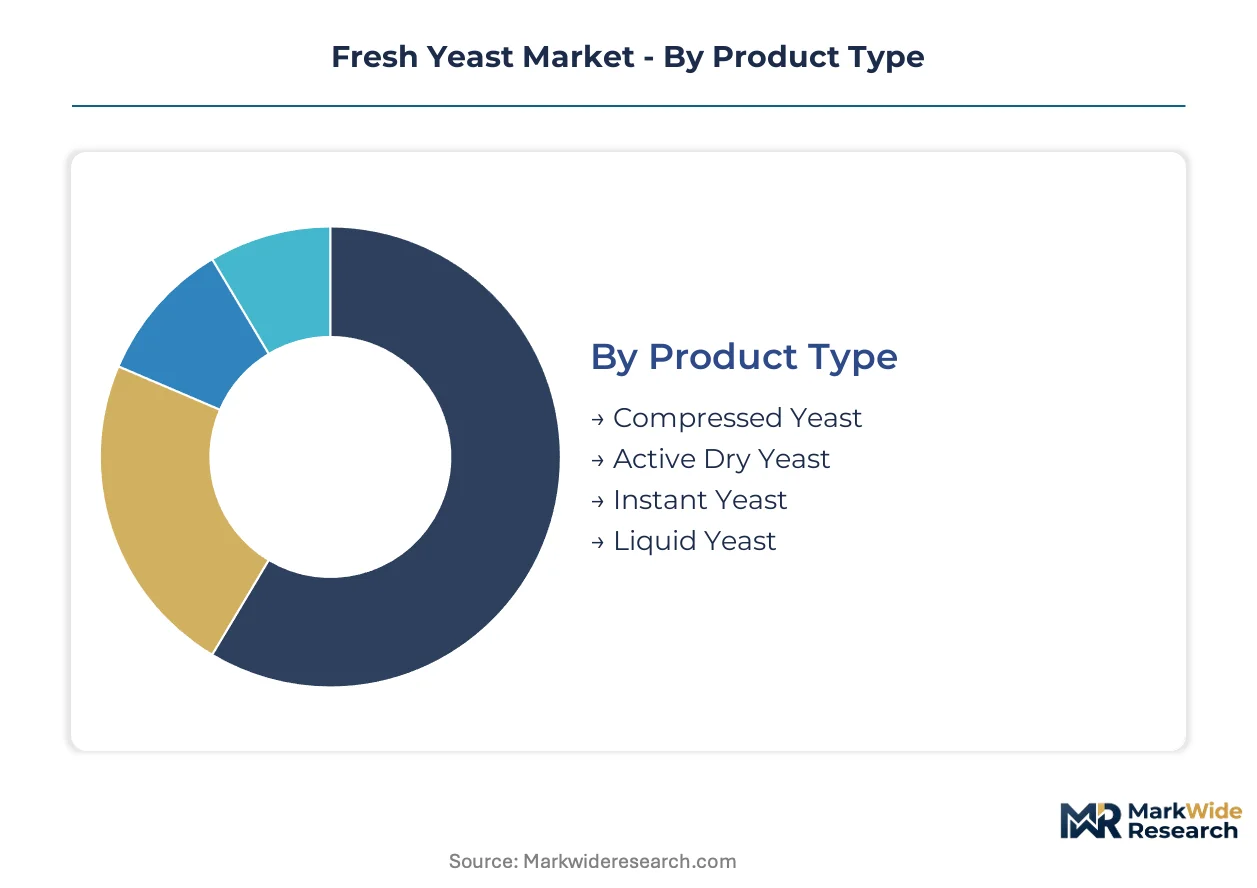
Fresh yeast segmentation reflects divergent technical requirements across moisture content, shelf stability, and cold-chain intensity. Each category maps distinct procurement patterns, from industrial bulk contracts to household retail formats.
Product Type:
Standardization dominates at the commodity end while strain-specific customization commands technical premiums in specialized applications.
- Compressed Yeast:Living Saccharomyces cerevisiae cells suspended in approximately 70% moisture cake form, requiring continuous refrigeration below 8°C to maintain leavening viability. Commercial bakeries in Germany, France, and Italy anchor procurement volumes, driven by EU Hygiene Regulation pathogen-monitoring mandates that professionalize cold-chain documentation.
- Liquid Yeast:Propagated cell suspensions with strain-specific purity for controlled inoculation protocols. Craft brewing operations in Copenhagen and Milan microbreweries generate technical-premium demand, constrained by refrigerated courier network density for last-mile viability assurance.
- Active Dry Yeast:Dehydrated granules with extended ambient storage tolerance, sacrificing activation speed for distribution flexibility.
- Instant Yeast:Rapid-dissolving dried formulation eliminating rehydration steps, capturing household and small-bakery segments with limited refrigeration infrastructure.
Most installed capacity flows through Compressed Yeast. Expansion is steepest in Liquid Yeast.
Application:
Volume concentration sits with mature fermentation channels while emerging therapeutic applications redirect technical-grade supply.
- Bakery:Leavening agent for bread, pastry, and fermented dough production across artisanal and industrial scales. Clean-label consumer preferences in Western European markets are pulling compressed yeast into premium channels previously dependent on chemical alternatives.
- Pharmaceuticals:Precision inoculation medium for therapeutic protein and biologics manufacturing. Biologics producers in Switzerland and Germany are diverting high-purity fresh yeast from commodity food channels, constrained by REACH chemical-safety documentation for novel strain variants.
- Brewing:Primary fermentation inoculant for beer production, spanning industrial lager facilities to craft ale operations.
- Distilling:Ethanol conversion catalyst for spirits and fuel-grade bioethanol production.
Procurement scale peaks in Bakery. Steepest expansion trajectory occurs in Pharmaceuticals.
End User:
Customer sophistication determines contract structure, from spot retail purchases to multi-year dedicated supply agreements with viability guarantees.
- Industrial Bakeries:High-volume automated production facilities with integrated cold-chain receiving infrastructure. Consolidation among European multinational bakery chains is concentrating procurement into fewer, larger contracts with dedicated supply agreements and real-time temperature monitoring.
- Household:Individual consumers purchasing small-format retail packaging for domestic baking. Instant yeast sachets dominate this segment where refrigeration reliability varies and activation convenience outweighs leavening performance optimization.
- Commercial Bakeries:Independent and small-chain operations with moderate throughput and mixed procurement channels.
- Food Manufacturers:Processed food producers incorporating yeast as ingredient or processing aid.
Contract value concentrates with Industrial Bakeries. Volume growth is fastest in Commercial Bakeries adopting direct-to-bakery distribution.
Packaging Type:
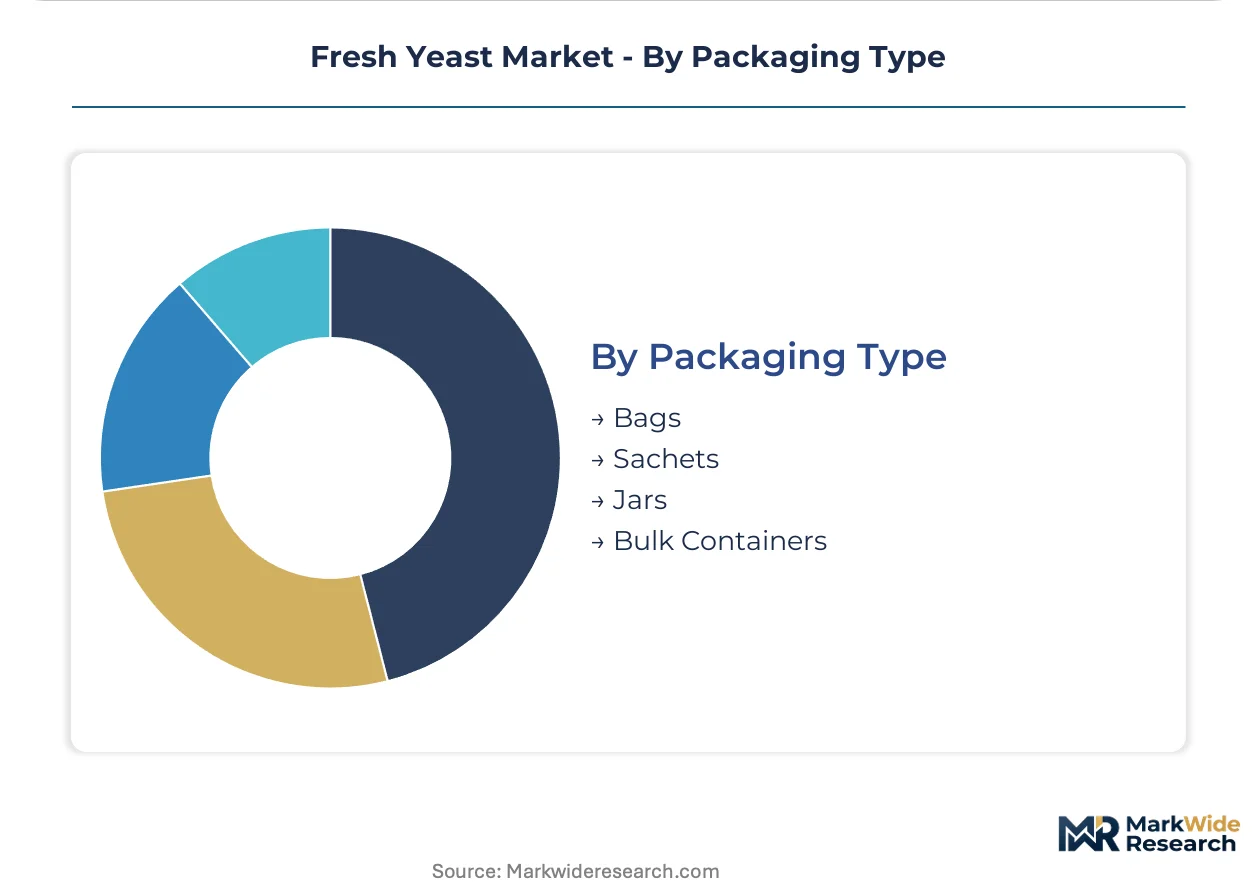
Format selection balances shelf-life extension against activation speed and handling efficiency in target use environments.
- Bulk Containers:Industrial-grade totes and drums for high-volume commercial and manufacturing procurement. Bioethanol fermentation facilities and industrial bakeries in France and Germany receive compressed yeast through reusable refrigerated bulk systems with integrated temperature logging.
- Sachets:Single-use sealed pouches for household and small-bakery portions. Instant yeast sachets capture retail growth in Indian urban markets where FSSAI modernization is streamlining import pathways for shelf-stable dried formats.
- Bags:Multi-serve flexible packaging for commercial bakery replenishment cycles.
- Jars:Reclosable rigid containers for household consumers with intermittent baking frequency.
Logistics throughput runs heaviest through Bulk Containers. Format innovation is most active in Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled fermentation technicians and cold-chain logistics specialists concentrate in Western European milling corridors, anchoring technical capabilities that sustain compressed yeast viability across extended distribution networks.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia drive compressed yeast procurement volumes, with the EU Hygiene Regulation mandating pathogen-monitoring protocols that professionalize procurement documentation. The country's national food safety authority enforces sub-8°C cold-chain standards that filter smaller distributors from premium supply tiers. Berlin-Brandenburg hosts dedicated refrigerated courier networks serving metropolitan artisanal clusters.
France
Traditional baking cultures in Île-de-France and Auvergne-Rhône-Alpes sustain artisanal demand for living yeast cultures, with clean-label consumer preferences pulling compressed formats into premium channels. REACH chemical-safety documentation requirements for fermentation byproducts extend strain-registration timelines for novel Saccharomyces cerevisiae variants. Lyon and Paris anchor direct-to-bakery distribution models displacing traditional wholesale intermediaries.
Italy
Milan and Barcelona metropolitan clusters source compressed yeast through dedicated refrigerated courier networks, bypassing regional distributors to compress order-to-delivery cycles. The EU Green Deal framework exposes distributors to carbon-tax exposure on refrigeration energy costs. Emilia-Romagna's industrial baking infrastructure maintains high-volume automated production with integrated cold-chain receiving systems.
United States
Craft brewing operations in Denver and Portland generate technical-premium demand for liquid yeast with strain-specific purity requirements. The FDA Food Safety Modernization Act imposes pathogen-monitoring and cold-chain documentation obligations that elevate compliance costs for live-culture shipments. Pacific Northwest microbreweries adopt blockchain-enabled verification to decentralize trust mechanisms in strain provenance documentation.
India
FSSAI modernization is streamlining live-culture import pathways, opening premium supply tiers for cold-chain-compliant European exporters previously filtered by BIS certification complexity. Mumbai and Delhi-NCR urban markets show retail growth in instant yeast sachets where refrigeration reliability varies. Maharashtra's food manufacturers incorporate yeast as processing aid in processed food production lines.
Fresh Yeast Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base separates into three functional strata: multinational propagators with integrated milling infrastructure, regional specialists commanding technical-premium niches, and cost-optimized volume producers serving emerging markets. Two dominant competitive moves define current positioning: strategic partnerships with refrigerated logistics operators to extend cold-chain radii, and portfolio diversification into strain-banking services for craft brewing and pharmaceutical applications.
Among European-based propagators, Lesaffre International and Lallemand, Inc. occupy positions within the integrated infrastructure tier, representing archetypes of fermentation-scale operations with established registration portfolios. Angel Yeast Co. Ltd. anchors the Asia-Pacific cost-optimization vector, exemplifying volume-focused production serving regional supply networks. These three entities collectively represent the geographic and functional span of competitive positioning in live-culture logistics.
| Leading Market Players |
|---|
| AB Mauri Foods, Inc. |
| Lesaffre International |
| Associated British Foods Plc |
| Lallemand, Inc. |
| Angel Yeast Co. Ltd. |
| Oriental Yeast Co. Ltd. |
| Kerry Group Plc |
| Koninklijke DSM N.V. |
| Leiber GmbH |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal carbon-tax framework gates qualified supply for cold-chain-compliant distributors and restricts premium-tier pricing access to propagators with documented refrigeration energy efficiency and strain-registration portfolios. Compressed yeast's sub-8°C storage mandate ties pricing power directly to electricity cost absorption capability and carbon-border adjustment exposure.
Pricing Analysis
Bundled cold-chain logistics services versus unbundled commodity yeast supply splits the pricing architecture across the market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EU Hygiene Regulation pathogen-monitoring protocols and volume scale of industrial bakery contracts. Pricing pressure stems from electricity price volatility in France and Germany eroding distributor margins. Household consumers in India exhibit highest price sensitivity, while Swiss biologics manufacturers demonstrate lowest sensitivity due to strain-purity requirements.
Supply Chain Analysis
Warehouse-distribution layer concentration in regional cold-chain hubs around Lyon, Berlin-Brandenburg, and Milan anchors hub-and-spoke patterns for last-mile viability assurance. Manufacturing concentrates in France, Germany, and China, with fermentation infrastructure drawing from molasses feedstock, refrigerated transport fleets, and strain-banking facilities. Single-source vulnerability to regional energy rationing events in Western Europe presents structural supply risk. Distribution runs through dedicated refrigerated courier networks displacing traditional wholesale intermediaries in metropolitan artisanal clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU cold-chain compliance costs and India's FSSAI modernization streamlining import pathways for European exporters previously filtered by BIS certification complexity.
For Market Incumbents: Hedge against instant yeast substitution by securing backward integration into strain-banking services for craft brewing and pharmaceutical fermentation applications. Expand capacity addition in India to capture FSSAI modernization benefits before certification backlogs resolve. Defend against Angel Yeast Co. Ltd. cost-optimization pressure through REACH registration portfolio depth. For New Entrants and Emerging Players: Capture white-space in liquid yeast technical-premium niches serving Copenhagen and Milan microbreweries with strain-specific inoculation protocols. Target India's commercial bakery segment adopting direct-to-bakery distribution models in Mumbai and Delhi-NCR. Deploy blockchain-enabled cold-chain verification as go-to-market differentiation against vertically integrated multinationals. For Investors and Strategic Acquirers: Roll-up economics work for regional cold-chain logistics specialists because fragmented refrigerated courier networks in European capitals lack scale efficiency and strain-banking capabilities. Five-to-ten year viability hinges on consolidation of direct-to-bakery distribution infrastructure. Target propagators with established EU Hygiene Regulation certification portfolios. Watch FSSAI import pathway streamlining velocity as inflection indicator for India market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Strain-Banking Service Expansion | Captures technical-premium demand from Swiss biologics manufacturers requiring REACH-documented Saccharomyces cerevisiae variants. |
| Direct-to-Bakery Distribution Buildout | Compresses order-to-delivery cycles for Milan and Barcelona metropolitan artisanal clusters bypassing wholesale intermediaries. |
| India Cold-Chain Infrastructure Partnership | Positions European exporters to exploit FSSAI modernization before BIS certification complexity filters reassert. |
| Blockchain Cold-Chain Verification Deployment | Decentralizes trust mechanisms for Pacific Northwest craft breweries adopting distributed-ledger strain provenance documentation. |
| Pharmaceutical Fermentation Grade Certification | Diverts technical-grade supply from commodity food channels into therapeutic protein production under EMA purity standards. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with industrial bakery procurement directors, refrigerated logistics operations managers, craft brewing fermentation specialists, pharmaceutical biologics manufacturing leads, and EU regulatory affairs consultants with secondary validation. Sources included customs and trade flow databases for molasses and yeast product movements, SEC filings of diversified food ingredient conglomerates, EFSA and FDA pathogen-monitoring protocol documentation, and cold-chain energy consumption disclosures under EU Green Deal frameworks. Bottom-up volume aggregation across product type, application, and end-user segments was cross-checked against top-down market sizing from fermentation capacity installations.
Comparable-period anchoring tied projection models to historical reference periods spanning pre-pandemic baseline, supply disruption intervals, and regulatory implementation phases across the analysis window. Segmentation dimensions modeled included moisture content tier, cold-chain intensity requirement, strain-specificity level, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating bakery industry consolidation rates, bioethanol fermentation facility expansion, and household instant yeast substitution patterns.
Energy price volatility, regulatory pathway delays, and strain-registration backlog accumulation are the dominant revision risks for forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Oat Grass Powder Market
Ingredients
United Kingdom Gelatin Market
Ingredients
Soluble Fibers Market
Ingredients
Corn Peptide Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Africa Sodium Reduction Ingredients Market
Ingredients
Hemp Seed Peptide Market
Ingredients
China Protein Market
Ingredients
Amaranth Seed Oil Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
Phytosterols Market
Ingredients
Synephrine Market
Ingredients
Food Colors Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Bleached Flour Market