
 Potato Starch Market | 2026-2036
Potato Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Potato Starch Market Intelligence
The market for potato starch is decoupling, with specialty modified starches for pharmaceutical and personal care applications separating from the commodity-grade native starches used in bulk food processing and paper manufacturing. Avebe specializes in high-purity starches for value-added food applications. In contrast, Cargill leverages its extensive global supply chain to compete on volume and cost in the commodity segment. Emsland Group differentiates through a focus on non-food applications like adhesives and bioplastics.
Potato starch is a carbohydrate extracted from potato tubers, characterized by large oval granules that provide high viscosity and a clear, tasteless gel when cooked. Its primary industrial function is as a thickener, binder, and texturizer. Modified starch variants, designed for specific pH or temperature stability, command higher margins in pharmaceutical and food processing applications. Native starch remains the volume leader, primarily serving the paper coating and basic food additive sectors.
Food safety and labeling regulations from bodies like the US FDA and the European Food Safety Authority (EFSA) govern its use as an additive. In China, GB standards dictate purity and processing requirements for both food and industrial grades. Stakeholders must now decide whether to invest in capacity for high-purity modified starches or optimize logistics for cost-competitive native starch distribution.
Market Dynamics
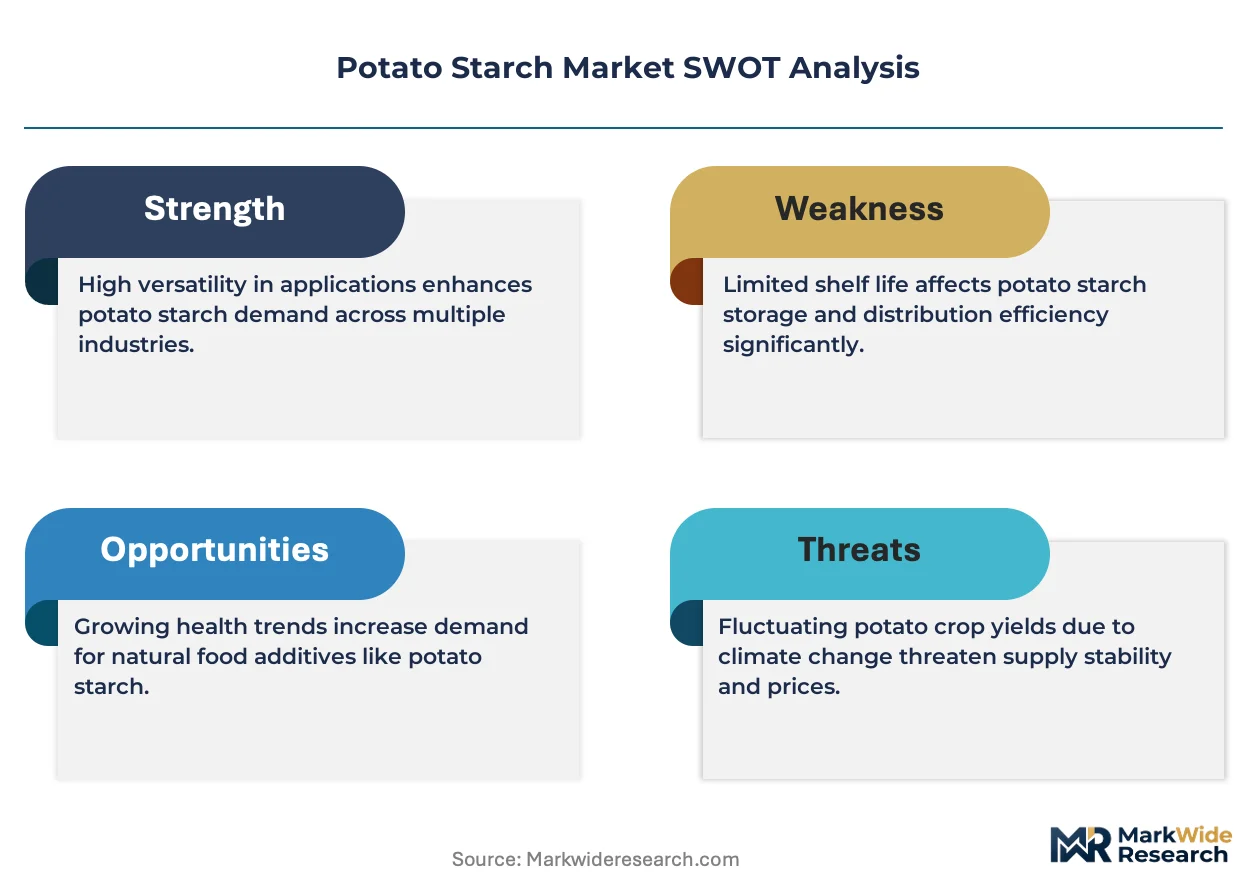
The fundamental market dynamic is the bifurcation between high-value modified starches and volume-driven native starches. This split is driven by divergent end-market requirements, with food and pharma demanding functional specialization while paper and basic foods prioritize cost efficiency.
Growth Catalysts
- Clean-Label Movement:Demand from food processors for simple, recognizable ingredients is boosting potato starch's use as a texturizer and binder, especially in gluten-free and non-GMO product formulations across North America and Europe.
- Bio-based Policies:The European Union's Green Deal creates a strong pull for potato starch in non-food applications, such as biodegradable packaging films and as a bio-based binder in paper coatings, displacing petroleum-derived alternatives.
- Asian Processed Food Sector:China's expanding confectionery, noodle, and processed meat industries are consuming vast quantities of native and modified starch for texture management, thickening, and yield improvement, anchoring volume demand.
Market Restraints
- Input Crop Volatility:The potato starch supply chain is directly exposed to agricultural risks, including potato crop failures from blight disease, adverse weather patterns, and fluctuations in raw potato prices, creating cost instability.
- Energy-Intensive Processing:Production is heavily dependent on energy for washing, refining, and drying the starch, making manufacturers vulnerable to volatile electricity and natural gas prices, which directly impacts gross margins.
- Substitution from Other Starches:In many bulk applications like adhesives and basic food thickening, potato starch faces direct price competition from corn, tapioca, and wheat starches, which often have more stable and geographically diverse supply chains.
Strategic Opportunities
- Pharmaceutical Excipients:Developing ultra-pure, highly-modified starches for use as binders and disintegrants in pharmaceutical tablets and capsules opens a high-margin, regulation-shielded market segment distinct from food applications.
- Plant-Based Food Formulation:The rapid growth of the meat and dairy alternatives market presents a significant opportunity for potato starch as a key texturizing, binding, and gelling agent to improve the sensory properties of finished products.
- Geographic Expansion in Southeast Asia:Rising processed food consumption and nascent domestic manufacturing in countries like Vietnam and Indonesia represent an underpenetrated market for both native and modified starch suppliers.
Industry Challenges
- Wastewater Management:Starch extraction generates large volumes of high-COD (Chemical Oxygen Demand) wastewater, requiring significant capital investment in treatment facilities to meet environmental regulations like the EU's Industrial Emissions Directive.
- Complex Certification Requirements:Producers must navigate a web of certifications, including food safety standards from EFSA and the FDA, non-GMO verification, and organic certifications, which adds cost and administrative overhead.
- Seasonal Supply Logistics:Aligning the seasonal potato harvest in Northern Hemisphere production zones with steady, year-round global demand requires sophisticated inventory management and logistical planning to avoid supply disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potato Starch Market |
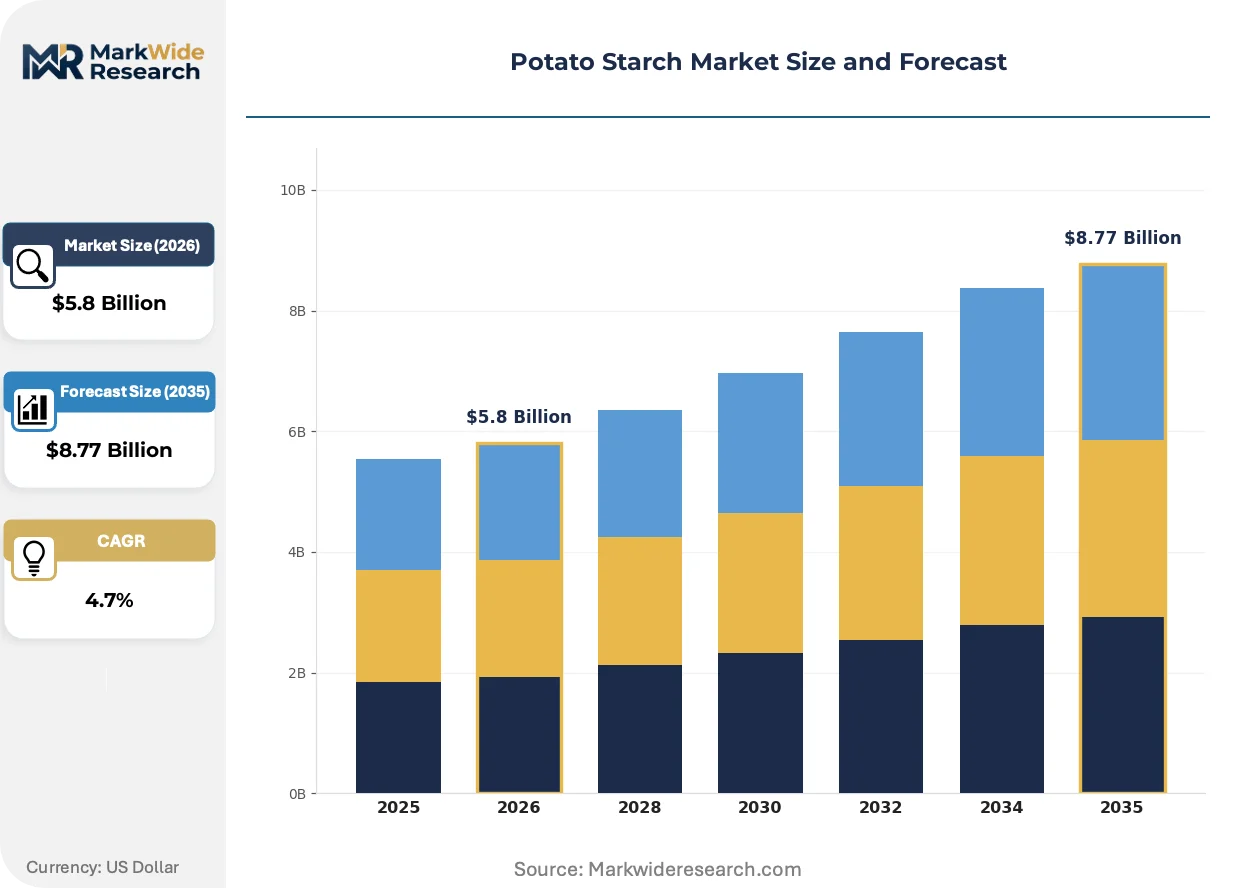
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Pre-gelatinized Starch, Cross-linked Starch Application: Food Processing, Paper Coating, Textile Finishing, Adhesives, Pharmaceuticals End User Industry: Confectionery Manufacturers, Textile Producers, Packaging Companies, Personal Care Makers, Pharmaceutical Companies Form: Powder, Granules, Gel, Film, Paste |
| Companies Covered | Emsland Group, AKV Langholt, Cargill, KMC, Alojas, AGRANA Group, Ingredion, Finnamyl, Avebe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potato Starch Market Strategic Shifts & Innovations
Technological advancements are focused on unlocking novel functionalities through physical and enzymatic modification. This is transforming potato starch from a simple thickener into a high-performance ingredient tailored for specific processing conditions and final product attributes.
Advanced physical modification techniques, such as drum-drying or spray-cooking, create cold-water-swellable (CWS) starches. Instant food manufacturers are rapidly adopting CWS starches to provide immediate viscosity in products like soups, sauces, and fillings. This innovation is electrifying product development by removing the need for a heating step, which simplifies manufacturing processes and reduces energy consumption for food brands.
Chinese GB standards for food additives are becoming a major regulatory checkpoint for the industry. These national standards mandate stringent limits on impurities and require detailed traceability, directly impacting all starch sold into China's massive food processing sector. Exporters must now invest heavily in quality control systems and documentation to ensure compliance, raising the barrier to entry for lower-quality suppliers.
A preference for ingredients with clear provenance and sustainability credentials is reshaping buying behavior. Procurement decisions in the food industry, particularly for premium and health-focused brands, are shifting from a pure cost basis to a value basis that includes non-GMO and organic certifications. This shift is most visible in the European Union and North American markets, where clean-label claims are a powerful consumer driver.
Potato Starch Market Segmentation

The potato starch market exhibits distinct segmentation, reflecting the varied functional requirements across its industrial and food applications. Understanding these segments enables stakeholders to identify specific growth pockets and optimize product development strategies for specialized end-use needs.
Product Type:
The market differentiates potato starch products based on their processing and functional properties.
- Native Starch:This is the unmodified form of potato starch, extracted directly from potato tubers and dried. It serves as a fundamental thickening agent and binder in bulk food applications and is widely used in paper coating for its cost-effectiveness in China's manufacturing sector.
- Modified Starch:Chemically or physically altered potato starch enhances specific properties like stability under heat, acid, or shear. Demand for these variants is concentrating in the pharmaceutical industry and specialized food processing for improved texture and shelf life, particularly in Europe.
- Pre-gelatinized Starch:This form is pre-cooked and dried, allowing it to swell and thicken instantly in cold water. Instant food manufacturers in North America utilize pre-gelatinized starch for convenience products like gravies and dessert mixes.
- Cross-linked Starch:Cross-linking enhances the starch's resistance to high temperatures, low pH, and shear forces. This robust variant finds application in retort-processed foods and acidic sauces, preventing breakdown during severe processing.
Native Starch leads on scale; Modified Starch leads on momentum.
Application:
Potato starch finds diverse application across industrial and food sectors, leveraging its unique functional attributes.
- Food Processing:Potato starch functions as a thickener, binder, texturizer, and stabilizer in a wide array of food products. This application segment is driven by the expanding processed food sector in China and the clean-label movement in Europe.
- Pharmaceuticals:Ultra-pure modified potato starches serve as excipients, disintegrants, and binders in tablet formulations and capsule manufacturing. This high-value segment benefits from stringent quality requirements and regulatory compliance from bodies like the US FDA and European EMA.
- Paper Coating:Potato starch provides strength, stiffness, and printability to paper and paperboard products. This bulk application is significant in Asia's packaging industry, where cost-efficiency and performance are critical.
- Textile Finishing:Potato starch is employed in textile sizing to strengthen yarns and improve weaving efficiency. Manufacturers in Asian textile hubs use starch to enhance fabric texture and finish.
- Adhesives:Industrial adhesives utilize potato starch as a natural binder in products like corrugated board and multi-wall paper bags. Its binding properties offer a bio-based alternative in various packaging solutions.
Food Processing commands the largest share; Pharmaceuticals represent the fastest-growing trajectory.
End User Industry:
End-user industries dictate specific demand profiles for potato starch, ranging from bulk industrial use to specialized consumer products.
- Confectionery Manufacturers:These companies use potato starch for gelling, thickening, and texturizing candies, gums, and other sweet products. China's extensive confectionery market consumes substantial volumes of potato starch.
- Pharmaceutical Companies:These firms require highly purified and specialized potato starches for drug formulation and delivery systems. Regulatory standards from the US FDA and European EFSA govern ingredient quality for these applications.
- Textile Producers:Manufacturers in the textile sector apply potato starch for sizing and finishing processes to improve fabric quality and processing efficiency. This segment is particularly relevant in India's and Vietnam's textile industries.
- Packaging Companies:Firms producing corrugated cardboard, paper bags, and other paper-based packaging use potato starch as a natural adhesive. The demand for sustainable packaging solutions in Europe drives this segment.
- Personal Care Makers:Potato starch acts as a natural absorbent, thickener, and texturizer in cosmetic and personal hygiene products like powders and creams. Consumer preference for natural ingredients in North America boosts this segment.
Confectionery Manufacturers drive substantial volume demand; Personal Care Makers are expanding most quickly.
Form:
The physical form of potato starch influences its ease of handling, dispersion properties, and suitability for various manufacturing processes.
- Powder:Powdered potato starch is the most common form, offering versatility in dry blending and aqueous dispersion. This form is widely used across food processing and industrial applications due to its ease of storage and precise dosing.
- Granules:Granular potato starch provides controlled dissolution and specific textural properties in certain food formulations. It is often preferred in applications requiring gradual thickening or specific mouthfeel.
- Gel:Potato starch can be processed into a gel form, which is utilized in ready-to-use food preparations and specific cosmetic formulations. Gel forms offer pre-hydrated convenience for manufacturers.
- Film:Starch-based films are emerging in biodegradable packaging and edible film applications. The European Union's Green Deal policies encourage the development of these bio-based materials.
- Paste:Potato starch paste is a pre-hydrated, viscous solution used directly in industrial applications like adhesives or textile sizing. This form offers immediate functionality without requiring on-site cooking.
Powdered starch accounts for the dominant share; Film forms are gaining significant traction in new applications.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Talent concentrations in agricultural science and food technology drive innovation and market expansion across key global regions. These specialized workforces develop advanced starch modification techniques and optimize processing efficiencies, directly influencing the potato starch supply chain. Regional demand profiles vary significantly based on industrial maturity and regulatory frameworks.
China
China's extensive confectionery and processed food manufacturing sectors consume vast quantities of potato starch. The country's GB standards dictate stringent purity and processing requirements for all starch products. Food processing clusters in the Yangtze River Delta continue to anchor significant volume demand for both native and modified starch variants.
United States
Clean-label movements and the demand for gluten-free formulations boost potato starch's use in North American food processing. The US FDA governs the use of potato starch as an additive, ensuring safety and quality across food and pharmaceutical applications. Instant food manufacturers in the Midwest region actively adopt pre-gelatinized starches for convenience products.
Germany
Germany's emphasis on bio-based materials and sustainable solutions generates strong demand for potato starch in non-food applications. The European Food Safety Authority (EFSA) regulates food additive use, promoting high standards for clean-label ingredients. Research and development hubs in North Rhine-Westphalia focus on novel starch applications in bioplastics and pharmaceuticals.
India
India's expanding textile and processed food industries represent a growing market for potato starch. The Food Safety and Standards Authority of India (FSSAI) oversees food safety regulations, influencing ingredient sourcing and quality. Textile manufacturing hubs in Maharashtra utilize potato starch for sizing and finishing processes, improving fabric quality.
Potato Starch Market Key Industry Players
Top-tier vendors anchor the high-purity, modified starch segment, while a broader base of suppliers competes on volume and cost in the commodity native starch market. Three primary strategic archetypes emerge: specialized functional ingredient providers, large-scale commodity producers, and non-food application innovators. Geographic expansion into emerging Asian markets and portfolio diversification into high-margin segments represent dominant competitive moves.
Specialists in high-purity starches, such as Avebe, focus on value-added food applications requiring precise functional attributes. Cargill leverages its extensive global supply chain to compete aggressively on volume and cost effectiveness in commodity starch markets. The Emsland Group differentiates its offerings through a strong focus on non-food applications, including adhesives and bioplastics.
| Leading Market Players |
|---|
| Emsland Group |
| AKV Langholt |
| Cargill |
| KMC |
| Alojas |
| AGRANA Group |
| Ingredion |
| Finnamyl |
| Avebe |
| Others |
Cost & Logistics Intelligence
Raw potato prices and energy costs directly influence upstream potato starch production. These input costs impact final pricing across commodity and specialty segments, from bulk paper manufacturers to pharmaceutical companies.
Pricing Analysis
Bundled product-service offerings distinguish specialty potato starch pricing from the unbundled, transactional nature of native starch. Pricing stratifies across premium, standard, and economy tiers based on modification level, certification (e.g., non-GMO), and volume scale. Pricing softness reflects intense competition from corn and tapioca starches in bulk applications. Pharmaceutical companies exhibit the lowest price sensitivity, prioritizing functional performance and regulatory compliance.
Supply Chain Analysis
Logistics and freight costs significantly influence potato starch supply, particularly for bulk native starch shipped from European production zones to Asian markets. Supply concentrates in agricultural regions of Europe, notably the Netherlands and Germany, and increasingly in China. The supply chain relies on raw potato availability and stable energy inputs. Commodity price volatility for potatoes presents a structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The potato starch market presents a clear margin-expansion story, driven by the shift towards high-purity modified starches for pharmaceutical and personal care applications. This premium-tier shift allows for greater value capture across the supply chain.
For Market Incumbents:
Deploy advanced enzymatic modification techniques to differentiate specialty starches, insulating against commodity price volatility from corn and tapioca. Incumbents should invest in non-GMO and organic certifications to capture premium segment demand in Europe and North America. Expand high-purity production capacity in strategic Asian markets like China. This counters the threat of substitution.
For New Entrants and Emerging Players:
A significant price-point gap exists between premium modified starches and economy native starches, creating entry opportunities. New entrants should target the underpenetrated pharmaceutical excipients market in Southeast Asia, leveraging regional manufacturing growth. Focus on plant-based food formulations in North America and Europe, emphasizing clean-label and functional benefits. A go-to-market strategy centered on sustainable sourcing and localized technical support will gain traction.
For Investors and Strategic Acquirers:
Consolidation pressure builds where advanced modification capabilities are scarce and market access is fragmented. The potato starch market remains viable over a 5-10 year window, particularly in high-value segments. Acquisition targets include mid-sized specialty starch producers with proprietary modification technologies or strong regional distribution networks in Southeast Asia. The signal to watch is a rise in M&A activity within the broader bio-based materials sector, indicating strategic repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand High-Purity Modified Starch Capacity | Meets pharmaceutical and personal care demand, driving higher margins and specialized market penetration. |
| Invest in Sustainable Sourcing Programs | Addresses clean-label consumer preferences and EU Green Deal requirements, enhancing brand reputation and market access. |
| Develop Cold-Water-Swellable (CWS) Variants | Supports instant food manufacturers in North America, simplifying processes and reducing energy consumption for food brands. |
| Geographic Expansion into Southeast Asia | Captures rising processed food consumption and textile industry growth in Vietnam and Indonesia. |
| Optimize Wastewater Treatment Technologies | Ensures compliance with environmental regulations like the EU's Industrial Emissions Directive, reducing operational risks. |
Research Approach
Coverage spans China, United States, Germany, and India, with primary inputs from each region. Interviews included food technologists, procurement managers, regulatory affairs specialists, and R&D directors. Secondary validation utilized US FDA filings, EFSA reports, China GB standards, and FSSAI guidelines. This approach ensured robust bottom-up and top-down data triangulation.
Granularity extended to product type, application, end-user industry, and form, with regional regulatory clusters modeled at a granular level. The analytical framework projected market trajectories across the analysis window. Compound Annual Growth Rates (CAGRs) were derived using regression analysis and anticipated market share shifts. Raw potato crop yields and energy price forecasts served as critical inputs.
Caveats apply where extreme weather events or new regulatory mandates could materially shift the outlook. Forecasts reflect documented assumptions, but competitive starch innovations also present revision triggers. Stakeholders should weigh these assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Horny Goat Weed Extract Market
Ingredients
Savory Ingredients Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
Low Fat Cooking Oil Market
Ingredients
Sugar Beet Pectin Market
Ingredients
Dry Mixes Market
Ingredients
Pork Skin Gelatin Market
Ingredients
Asia-Pacific Brewing Enzymes Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
China Soy Protein Market
Ingredients
Global Cocoa Ingredients Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
Egg Free Premix Market
Ingredients
Lupine Peptides Market
Ingredients
Hemp Seed Peptide Market