
 Xylooligosaccharide Market | 2026-2036
Xylooligosaccharide Market Size, Share, and Industry Trends Forecast 2026-2036
Xylooligosaccharide Market Analytics
Dietary supplement companies is bifurcating from food manufacturers as the dominant buyer archetype for high-purity xylooligosaccharide. Shandong Kangwei Bioengineering leverages captive enzymatic refining capacity to serve pharmaceutical-grade contracts. Beneo GmbH anchors European demand through its prebiotic ingredient platform and FOS-XOS blending expertise. Shandong Longlive Biotechnology dominates bulk conventional XOS output through integrated corn cob sourcing in Shandong province.
Xylooligosaccharide consists of two to seven xylose units linked by β-1,4-glycosidic bonds, typically manufactured via controlled enzymatic hydrolysis of xylan-rich lignocellulosic biomass such as corn cobs, sugarcane bagasse, or bamboo shoots, with commercial grades ranging from 35% to 95% purity. XOS functions as a selective prebiotic that stimulates bifidobacteria and lactobacilli proliferation without the dosage limitations of inulin or fructooligosaccharides. Food and beverage applications retain volume leadership but face margin compression from commoditized conventional XOS, while nutraceutical-grade organic XOS commands premium positioning through dual certification requirements. Pharmaceutical applications represent the fastest-expanding segment as clinicians validate XOS for metabolic syndrome adjuvant therapy and colorectal health protocols.
China's NMPA governs prebiotic food ingredient registrations through GB standards for oligosaccharide purity and microbial limits, while the EU EFSA evaluates health claim substantiation under the Nutrition and Health Claims Regulation. Japan's Ministry of Health, Labour and Welfare maintains FOSHU approval pathways that XOS suppliers must navigate for functional food positioning. Stakeholders must monitor regulatory divergence between China's process-based standards and Europe's outcome-based health claim requirements when allocating R&D and registration budgets across regional portfolios.
Market Dynamics
Enzymatic refining capacity concentration in Shandong province is bifurcating the Xylooligosaccharide market into pharmaceutical-grade premium supply and commoditized conventional grades, with purity thresholds becoming the primary competitive moat.
Growth Catalysts
- EFSA Health Claim Pathways:The EU's expanding prebiotic labeling standards are validating XOS for metabolic syndrome protocols, opening reimbursement-adjacent positioning in European nutraceutical channels.
- Japan FOSHU Approval:Japan's Ministry of Health, Labour and Welfare maintains functional food approval pathways that XOS suppliers navigate for premium functional positioning in aging-population formulations.
- Corn Cob Cluster Economics:Integrated feedstock processing in Shandong province supplies the majority of global XOS output, creating cost-advantaged enzymatic hydrolysis at scale.
Market Restraints
- Xylan Feedstock Volatility:Corn cob and bamboo shoot prices fluctuate with agricultural commodity cycles, compressing margins for non-integrated processors lacking captive biomass supply.
- Regulatory Divergence Friction:China's GB standards for oligosaccharide purity impose process-based compliance costs that conflict with Europe's outcome-based health claim substantiation requirements.
- Inulin Substitution Pressure:Established prebiotic ingredients with lower production costs and broader formulation familiarity threaten XOS adoption in price-sensitive food applications.
Strategic Opportunities
- Pharmaceutical Adjuvant Positioning:Clinicians are validating XOS for colorectal health protocols and metabolic syndrome therapy, creating prescription-adjacent demand outside traditional food and supplement channels.
- Dual Certification Premium Tier:Organic XOS with pharmaceutical-grade purity and food-grade certification commands positioning unavailable to conventional grades, capturing margin pools in functional medicine.
- Enzyme Engineering Convergence:Advances in thermostable xylanase development and membrane filtration integration are reducing enzymatic hydrolysis cycle times and purification costs.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:The intersection of enzymology, downstream processing, and regulatory affairs expertise required for pharmaceutical-grade XOS production exceeds current workforce supply in major producing regions.
- Cross-Border Registration Timelines:Navigating China's NMPA prebiotic food ingredient registrations alongside EU EFSA health claim substantiation creates multi-year compliance horizons that strain R&D allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xylooligosaccharide Market |
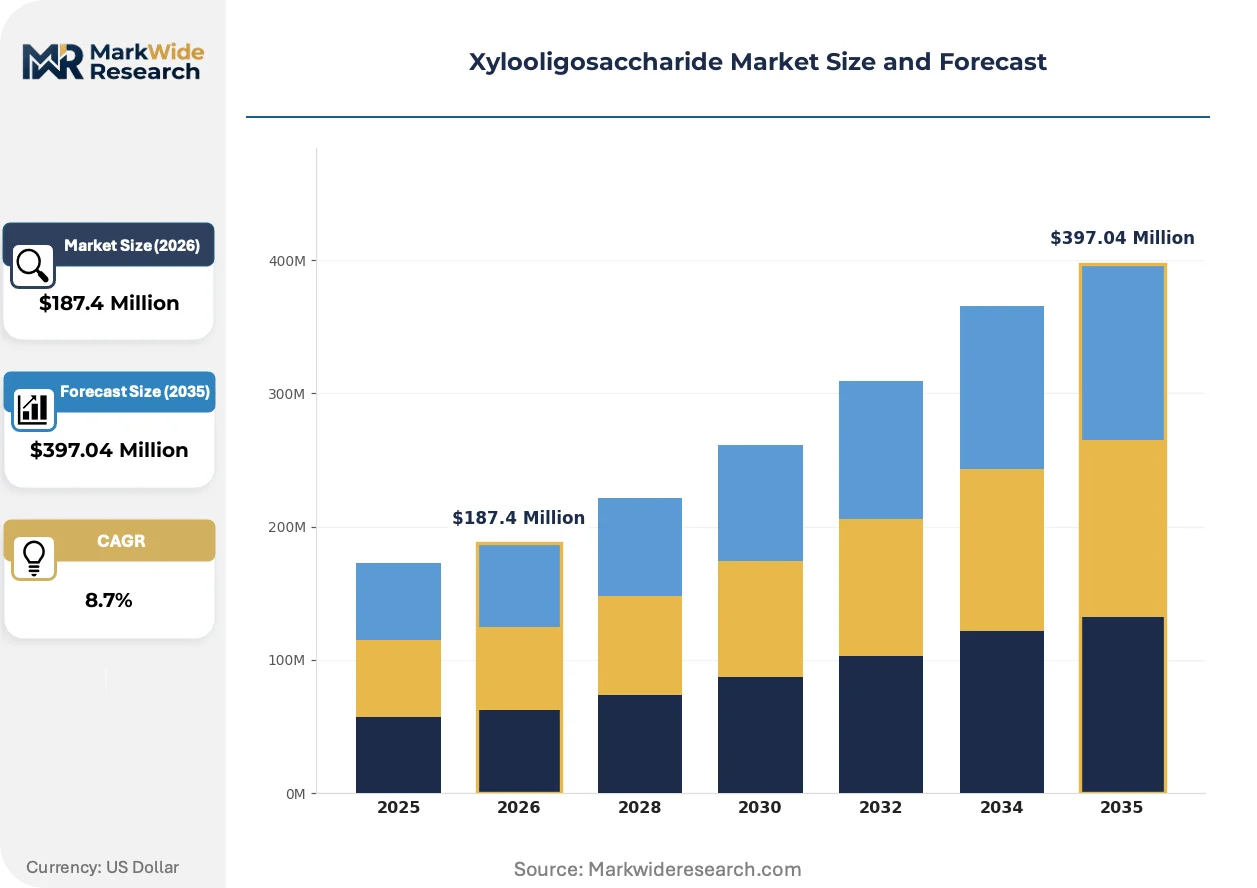
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: XOS, Non-GMO XOS, Organic XOS, Conventional XOS Application: Food & Beverage, Nutraceuticals, Feed, Pharmaceuticals End User: Food Manufacturers, Dietary Supplement Companies, Pharmaceutical Firms, Animal Feed Producers Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Shandong Kangwei Bioengineering, Beneo GmbH, Shandong Longlive Biotechnology, Shandong Bailong Chuangyuan, Longlive Bio-Technology, Henan Heagreen Bio-technology, Quantum Hi-Tech Biological, Hubei Widely Chemical Technology, Yibin Yatai Biological Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xylooligosaccharide Market Evolving Landscape
Continuous enzymatic processing and membrane separation technologies are compressing unit economics for high-purity XOS, while regulatory frameworks in major consuming regions are hardening purity thresholds and expanding approved health positioning.
Immobilized enzyme reactor systems for xylan hydrolysis are miniaturizing the capital footprint required for pharmaceutical-grade XOS production. Mid-scale nutraceutical manufacturers in North America and Europe are adopting these systems to bypass Shandong supply concentration. The technology is enabling distributed production models that reduce cross-border regulatory exposure and shorten supply chains for time-sensitive biologic applications.
China's NMPA is tightening GB standard enforcement for oligosaccharide microbial limits and purity thresholds, accelerating consolidation among non-integrated processors. Domestic producers with captive enzymatic refining capacity are absorbing market share from smaller competitors dependent on toll manufacturing. Pharmaceutical-grade contract manufacturers are responding by deepening backward integration into enzyme production and xylan feedstock sourcing.
Direct procurement relationships between dietary supplement formulators and enzymatic refiners are displacing traditional ingredient distributor intermediaries in high-purity XOS channels. Large supplement brands with gut microbiome platforms are establishing multi-year offtake agreements with Shandong producers possessing dual certification capabilities. This pattern concentrates most visibly in North American markets where supplement companies seek supply security for clinical validation programs.
Xylooligosaccharide Market Segmentation
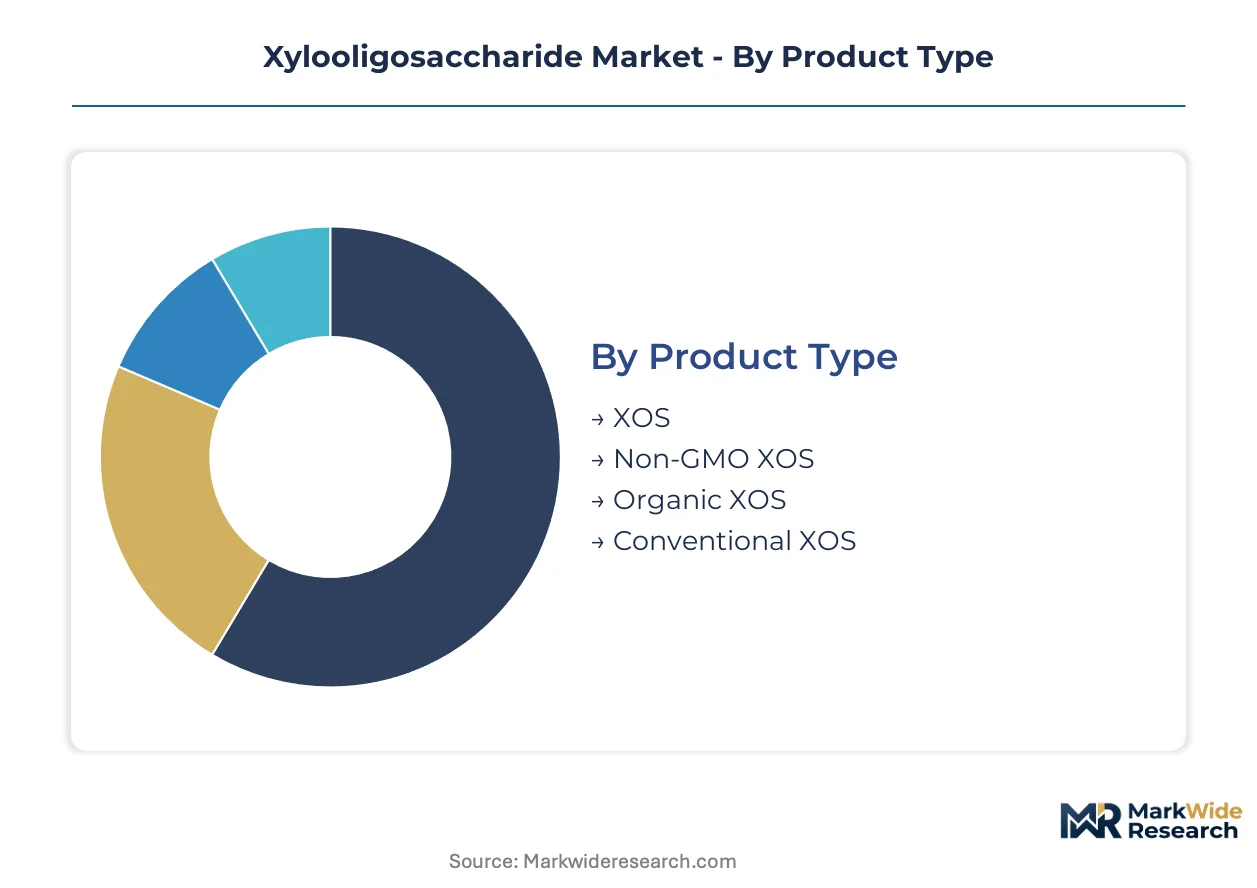
Xylooligosaccharide procurement patterns diverge sharply across purity grades and end-use certifications, with pharmaceutical and nutraceutical buyers enforcing standards that food manufacturers rarely require. Segmentation reveals how enzymatic refining economics and regulatory thresholds partition demand into distinct margin tiers.
Product Type:
EFSA health claim substantiation and China's GB standards impose divergent purity benchmarks that segment XOS into certification-driven tiers with incompatible cost structures.
- XOS:Standard-grade xylooligosaccharide containing 35-70% xylooligosaccharide content by dry weight, manufactured via enzymatic hydrolysis of corn cob xylan without organic certification. Demand concentrates in mass-market food applications where cost sensitivity overrides purity premiums, though EFSA's expanding prebiotic labeling standards are elevating minimum viable specifications.
- Non-GMO XOS:Identity-preserved production using non-genetically modified corn cob feedstock and documented chain-of-custody verification. North American dietary supplement companies in California and New York are driving procurement as state-level labeling requirements harden and consumer litigation risk escalates.
- Organic XOS:Dual-certified material meeting USDA Organic and pharmaceutical-grade purity thresholds simultaneously. Japanese FOSHU applicants and European functional medicine formulators absorb limited supply at substantial premiums.
- Conventional XOS:Commodity-grade output from integrated Shandong processors using standard agricultural corn cob feedstock without certification overlays. Bulk food and beverage manufacturers in China's domestic market represent the primary offtake channel.
Conventional XOS handles the majority of throughput; Non-GMO XOS is expanding most quickly on share as North American liability frameworks tighten.
Application:
Margin structure across applications correlates directly with clinical validation intensity and reimbursement proximity.
- Food & Beverage:Volume-dominant channel incorporating XOS into dairy alternatives, baked goods, and functional beverages at 35-55% purity grades. China's domestic processors and Southeast Asian beverage manufacturers absorb Shandong's conventional output, though inulin substitution pressure constrains pricing power in commodity formulations.
- Nutraceuticals:Capsule, powder, and sachet formulations targeting gut microbiome modulation with 70-95% purity requirements. Direct procurement relationships between North American supplement brands and dual-certified Shandong refiners are displacing traditional distributor intermediaries.
- Feed:Poultry and swine gut health applications utilizing lower-purity XOS as antibiotic replacement agents. Brazilian and Vietnamese integrated livestock operations represent concentrated demand as export-oriented producers face EU import residue standards.
- Pharmaceuticals:Adjunct therapy positioning for metabolic syndrome and colorectal health protocols requiring 95%+ purity with full documentation. Clinicians in Germany and Japan are validating prescription-adjacent protocols outside traditional food and supplement channels.
Food & Beverage handles the majority of throughput; Pharmaceuticals is climbing the fastest as clinical validation programs advance.
End User:
Procurement sophistication separates integrated formulators with captive regulatory affairs capacity from price-sensitive commodity buyers.
- Food Manufacturers:Multinational dairy, bakery, and beverage processors sourcing conventional XOS through annual tender processes. Margins compress as Shandong's integrated producers compete on scale rather than certification depth.
- Dietary Supplement Companies:Gut microbiome platform builders establishing multi-year offtake agreements with enzymatic refiners possessing dual certification capabilities. North American brands with clinical validation programs are concentrating procurement among three Shandong suppliers.
- Pharmaceutical Firms:Prescription-adjacent developers requiring batch-level documentation and pharmacokinetic validation. European metabolic syndrome therapy protocols and Japanese colorectal health applications are driving qualification timelines.
- Animal Feed Producers:Integrated livestock operations and premix compounders utilizing 35-50% purity XOS for antibiotic reduction claims. Brazilian export-oriented poultry processors face EU residue standards that elevate documentation requirements.
Food Manufacturers handle the majority of throughput; Dietary Supplement Companies are gaining share fastest as direct procurement displaces distributor channels.
Distribution Channel:
Channel selection reflects order size, certification complexity, and geographic proximity to enzymatic refining capacity.
- Online Retail:Direct-to-consumer probiotic and prebiotic supplement sales through branded e-commerce platforms. North American and European microbiome-focused startups leverage this channel for subscription-based recurring revenue.
- Supermarkets:Mass-market functional food and beverage placement requiring conventional XOS at commodity price points. China's domestic retail consolidation favors suppliers with Shandong logistics integration.
- Health Stores:Specialty retail positioning for organic and Non-GMO certified XOS supplements. Japanese drugstores and German Reformhaus chains maintain premium positioning through pharmacist consultation.
- Direct Sales:Bulk procurement contracts between dietary supplement formulators and enzymatic refiners bypassing traditional ingredient distributors. Large North American brands with clinical validation programs are consolidating supply relationships.
Supermarkets handle the majority of throughput; Direct Sales is climbing the fastest as supplement companies secure supply for validation programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzymatic refining capacity clusters in Shandong province supply the majority of global output, creating geographic asymmetry between production concentration and demand dispersion across major consuming markets.
China
Dietary supplement formulators and pharmaceutical developers drive procurement of high-purity grades for gut microbiome and metabolic syndrome applications. NMPA's GB standards for oligosaccharide purity and microbial limits govern prebiotic food ingredient registrations. Shandong province's integrated corn cob processing clusters dominate enzymatic hydrolysis output, with captive refiners absorbing market share from toll-dependent competitors.
United States
North American supplement brands with clinical validation programs establish multi-year offtake agreements for dual-certified supply. State-level labeling requirements in California and New York harden procurement standards for identity-preserved production. Direct procurement relationships between microbiome platform builders and Shandong refiners displace traditional distributor intermediaries.
Germany
Clinicians validate XOS for metabolic syndrome adjuvant therapy and colorectal health protocols, driving prescription-adjacent demand outside food channels. EFSA health claim substantiation under the Nutrition and Health Claims Regulation evaluates prebiotic positioning. Functional medicine formulators in German Reformhaus chains absorb limited organic XOS supply at substantial premiums.
Japan
Aging-population formulations targeting gut health sustain FOSHU approval pathway navigation for premium functional positioning. METI oversees industrial biotechnology standards while MHLW maintains functional food regulatory frameworks. Japanese drugstores maintain premium prebiotic positioning through pharmacist consultation models.
Brazil
Integrated livestock operations utilize lower-purity XOS for poultry and swine gut health as antibiotic replacement agents. ANVISA governs feed additive registrations while export-oriented producers face EU import residue standards. Brazilian premix compounders represent concentrated demand for documented supply chains.
Xylooligosaccharide Market Competitive Landscape
Concentration sits with integrated enzymatic refiners possessing captive xylan feedstock sourcing and dual certification capabilities. The market structure bifurcates between pharmaceutical-grade premium supply and commoditized conventional grades, with purity thresholds serving as the primary competitive moat. Three archetypes dominate: Shandong-based integrated processors with backward control over corn cob supply, European prebiotic ingredient platforms with FOS-XOS blending expertise, and emerging North American distributed producers adopting immobilized enzyme reactor systems. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as mid-scale manufacturers bypass Shandong supply concentration through technology licensing.
Among Shandong-based integrated processors, Shandong Kangwei Bioengineering, Shandong Longlive Biotechnology, and Shandong Bailong Chuangyuan occupy positions exemplifying the enzymatic refining archetype with captive feedstock control. Beneo GmbH represents the European prebiotic platform model, anchoring regional demand through ingredient blending capabilities. These named entities serve as structural anchors for understanding competitive positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Shandong Kangwei Bioengineering |
| Beneo GmbH |
| Shandong Longlive Biotechnology |
| Shandong Bailong Chuangyuan |
| Longlive Bio-Technology |
| Henan Heagreen Bio-technology |
| Quantum Hi-Tech Biological |
| Hubei Widely Chemical Technology |
| Yibin Yatai Biological Technology |
| Others |
Value Network & Pricing Analysis
Shandong province's integrated corn cob processing clusters generate pronounced scale economies that compress unit costs for enzymatic hydrolysis while simultaneously elevating purity thresholds as competitive barriers. This capacity concentration creates asymmetric pricing power where captive refiners command premium positioning for pharmaceutical-grade output while commoditized conventional grades face margin compression from toll-dependent competitors.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade XOS at 95%+ purity from nutraceutical grades at 70-95% and conventional food-grade material at 35-70%. Price differentiation hinges on dual certification depth—USDA Organic plus pharmaceutical-grade documentation—and captive enzymatic refining capacity versus toll manufacturing dependence. Pricing pressure intensifies in conventional grades as integrated Shandong processors compete on scale, while pharmaceutical-grade premiums expand as clinical validation programs advance metabolic syndrome protocols. Food manufacturers exhibit highest price sensitivity due to inulin substitution alternatives, whereas pharmaceutical developers demonstrate lowest sensitivity given batch-level documentation requirements.
Supply Chain Analysis
China produces the majority of global XOS output through Shandong province's corn cob processing clusters, with secondary refining presence in Henan and Hubei provinces. Raw material dependencies center on xylan-rich agricultural residues—corn cobs, sugarcane bagasse, bamboo shoots—plus thermostable xylanase enzymes and membrane filtration systems. Single-source vulnerability concentrates in Shandong's enzymatic refining capacity, where NMPA regulatory tightening is accelerating consolidation among non-integrated processors. Distribution runs through direct procurement relationships between North American supplement brands and dual-certified refiners, displacing traditional ingredient distributor intermediaries in high-purity channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through dual certification requirements creates substantial switching costs for pharmaceutical-grade buyers. The intersection of enzymatic refining expertise and multi-jurisdictional compliance documentation erects barriers that favor incumbents with established NMPA and EFSA navigation capabilities.
For Market Incumbents: Consolidate market position by deepening backward integration into thermostable xylanase production and captive xylan feedstock sourcing, neutralizing margin pressure from agricultural commodity volatility. Expand enzymatic refining capacity in Shandong to absorb toll-dependent competitor share as NMPA GB standard enforcement tightens. Prioritize dual certification investment for organic and pharmaceutical-grade positioning to capture functional medicine premium pools.
For New Entrants and Emerging Players: EFSA health claim fast-track navigation offers entry positioning for metabolic syndrome adjuvant therapy applications where clinical validation intensity exceeds incumbent supply flexibility. Target North American dietary supplement companies seeking supply security for gut microbiome platforms, leveraging immobilized enzyme reactor systems to bypass Shandong supply concentration. Deploy distributed production models with shortened supply chains for time-sensitive biologic applications.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated enzymatic refiners with captive feedstock control and dual certification capabilities over toll-dependent processors facing regulatory consolidation pressure. Long-term viability across the projection horizon rests on backward integration depth and multi-jurisdictional registration portfolios. Monitor EFSA health claim substantiation timelines as inflection indicators for prescription-adjacent demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Xylanase Production | Captive enzyme supply reduces cycle times and insulates margin from agricultural input volatility. |
| Dual Certification Investment | USDA Organic plus pharmaceutical-grade documentation unlocks functional medicine premium positioning. |
| EFSA Health Claim Navigation | Substantiation under Nutrition and Health Claims Regulation enables reimbursement-adjacent European positioning. |
| Immobilized Enzyme Reactor Deployment | Miniaturized capital footprint enables distributed production bypassing Shandong supply concentration. |
| Direct Procurement Relationship Building | Multi-year offtake agreements with North American supplement brands displace distributor intermediaries. |
Research Methodology
Initial hypotheses were tested against primary input from enzymatic refining plant managers, dietary supplement procurement leads, regulatory affairs directors at prebiotic ingredient platforms, and pharmaceutical formulation scientists, then refined through secondary validation. Primary stakeholder engagement combined structured interviews with downstream offtake agreement negotiators and technical discussions with bioprocess engineering specialists. Secondary sources encompassed NMPA GB standard filings, EFSA health claim substantiation records, USDA Organic certification databases, and customs trade data for xylan-rich agricultural residue flows. Bottom-up capacity assessments across Shandong refining clusters were triangulated against top-down demand modeling from nutraceutical and pharmaceutical end-use segments.
Variance-decomposition framing isolates volume drivers from price-mix effects across purity grade tiers, application segments, and geographic demand clusters. The analytical framework models segmentation dimensions including product certification level, end-use application intensity, and regional regulatory pathway complexity. CAGRs were derived from regression-based trajectory fitting calibrated to enzymatic refining capacity expansion schedules and clinical validation program advancement timelines. Industry-specific forecast inputs incorporate NMPA enforcement intensity scenarios and EFSA health claim approval velocity assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained NMPA regulatory tightening and stable agricultural commodity input costs; material deviation in either driver would warrant model refresh. Forecasts reflect assumptions regarding enzymatic hydrolysis yield improvements and membrane filtration cost curves. Specific revision risks include xylan feedstock price spikes from competing biomass demand and accelerated inulin substitution in price-sensitive food applications. Recalibration cycles align with material shifts in regulatory enforcement intensity and clinical validation milestone achievements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Boysenberry Extract Market
Ingredients
Avocado Powder Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Clean Label Flour Market
Ingredients
Oyster Peptide Market
Ingredients
Diastatic Malt Market
Ingredients
Konjac Flour Market
Ingredients
Rose Extract Market
Ingredients
Middle East and Africa Lipids Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
Lupin Flour Market
Ingredients
Sunflower Meal Market
Ingredients
Olive Leaf Extract Market
Ingredients
Tomato Concentrate Market
Ingredients
Hydrolyzed Vegetable Protein Market
Ingredients
Philippines Edible Oils & Fats Market