
 Global Cocoa Nibs Market | 2026-2036
Global Cocoa Nibs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cocoa Nibs Market Foresight
Demand from nutraceutical formulators is hardening as cocoa nibs gain traction in functional food portfolios. Barry Callebaut AG leverages its bean sourcing infrastructure to secure premium-grade nibs for European chocolate makers. Cargill, Incorporated anchors its position through integrated processing facilities in Côte d'Ivoire and Ghana. Olam Food Ingredients competes on traceability platforms that map farm-level origin for retail-ready cocoa nibs.
Cocoa nibs consist of cracked, fermented, and dried cocoa beans with the outer husk removed, typically containing 50-55% cocoa butter and 12-18% protein by weight; manufacturers roast or leave raw depending on end-use flavor and alkaloid profiles. The roasted segment dominates foodservice channels where Maillard-reacted notes suit bakery and confectionery applications, while organic nibs command premium shelf positioning in North American natural retail. Nutraceuticals represents the fastest-growing application as polyphenol content drives supplement formulation, though bulk bags remain the standard packaging format for industrial buyers managing throughput at scale.
FDA food safety standards govern import and processing protocols for cocoa nibs entering United States distribution, while EFSA purity criteria and EU Deforestation Regulation due diligence rules reshape supplier qualification across European markets. Ghana's Cocoa Board and Ivory Coast's Coffee and Cocoa Council enforce farmgate pricing and export licensing that directly constrains raw material availability. Stakeholders must monitor how emerging origin verification technologies and evolving deforestation liability frameworks reshape procurement geography and contract structures.
Market Dynamics
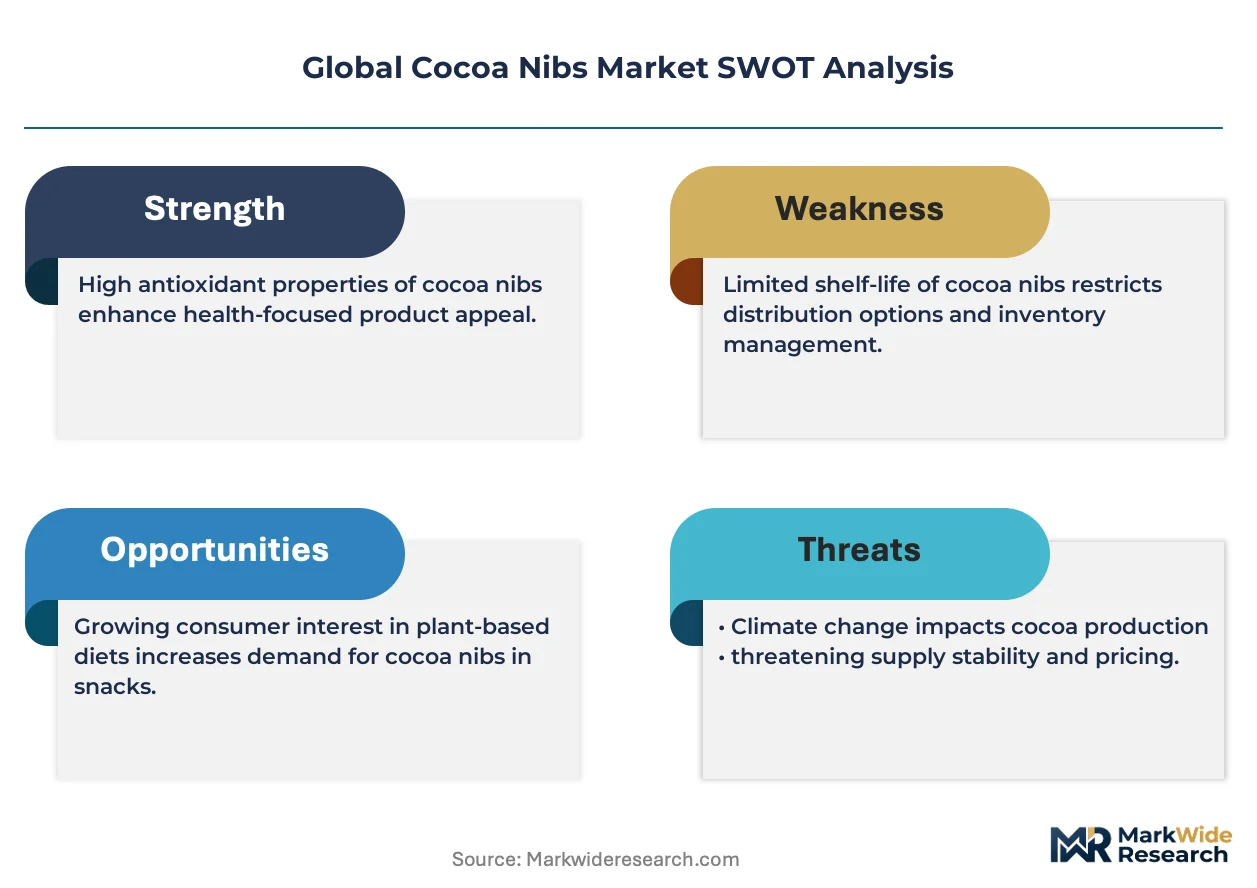
The EU Deforestation Regulation is forcing cocoa nibs suppliers to rebuild traceability infrastructure across West African supply chains, compressing procurement timelines and elevating compliance costs for bean-to-bar manufacturers sourcing from Ghana and Ivory Coast cooperatives.
Growth Catalysts
- Clean-label snack formulation:Functional food brands in Germany and the United States are incorporating cocoa nibs as polyphenol-rich ingredients in energy bars and granolas.
- EU Deforestation Regulation:Mandatory due diligence rules are accelerating investment in farm-level origin verification technologies across European import channels.
- Bean-to-bar direct sourcing:Artisanal chocolate makers are establishing direct procurement relationships with Ivory Coast and Ghana cooperatives, bypassing commodity exchanges.
Market Restraints
- Cocoa bean price volatility:Farmgate pricing set by Ghana's Cocoa Board and Ivory Coast's Coffee and Cocoa Council creates input cost instability for processors.
- Supply concentration risk:Over 60% of global cocoa bean output originates from two West African nations, exposing buyers to regional climate and political disruptions.
- Technical limitation:Husk removal and roasting consistency remain labor-intensive stages where small-batch quality variance exceeds industrial tolerance thresholds.
Strategic Opportunities
- Underpenetrated nutraceuticals:Supplement formulators in the United States are developing standardized polyphenol extracts from cocoa nibs for cardiovascular health positioning.
- Organic certification tailwind:USDA Organic and EU Organic standards are creating premium shelf positioning in North American natural retail channels.
- Blockchain traceability convergence:Distributed ledger technology paired with satellite monitoring is enabling real-time deforestation verification for ESG-compliant buyers.
Industry Challenges
- Origin verification skill gap:Procurement teams lack expertise in geospatial auditing and farmer database management required by EU Deforestation Regulation compliance.
- Certification timeline compression:Organic and Fairtrade certification cycles of 18-24 months lag behind brand launch schedules for clean-label product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cocoa Nibs Market |
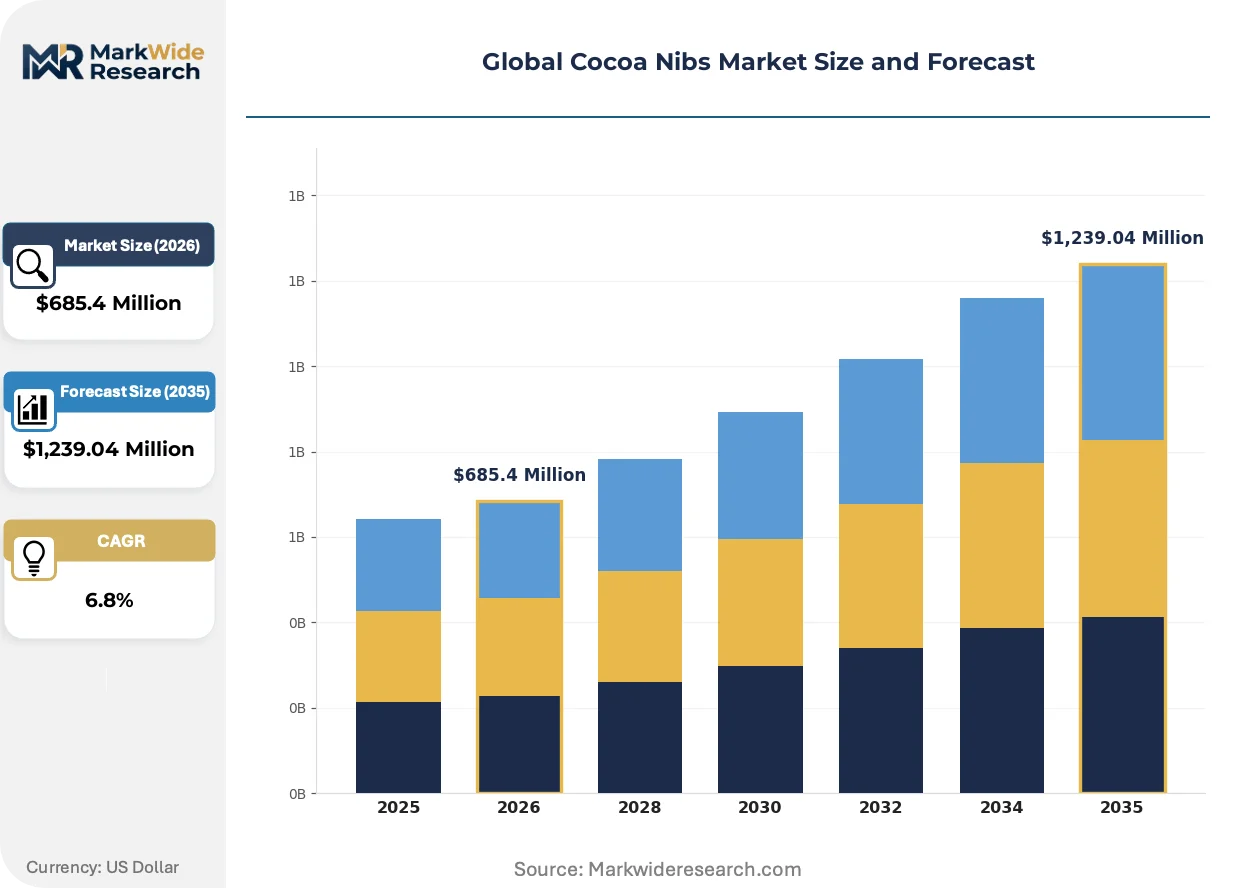
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw, Roasted, Organic, Confectionery Grade, Natural Application: Baking, Beverages, Snacks, Cosmetics, Nutraceuticals End User: Food Manufacturers, Beverage Producers, Personal Care, Dietary Supplements, Culinary Arts Packaging Type: Bulk Bags, Pouches, Glass Jars, Paper Bags, Vacuum Sealed Packs |
| Companies Covered | Barry Callebaut AG, Cargill, Incorporated, Olam Food Ingredients, Cemoi Group, ECOM Agroindustrial Corp. Limited, United Cocoa Processor, Inc., Fine Cocoa Products Corporation, Navitas Organics, BMV Cocoa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cocoa Nibs Market Shifts & Advancements
Processing technology and regulatory compliance systems are converging to reshape how cocoa nibs move from farm to finished goods, with automation and traceability investments dominating capital allocation decisions.
Optical sorting systems equipped with near-infrared spectroscopy are automating husk removal and bean grading at cocoa processing facilities. Mid-scale bean-to-bar manufacturers in Germany and Belgium are adopting these systems to reduce manual labor dependency. The technology is automating quality consistency checks that previously required skilled sensory evaluation, compressing batch-to-batch variance.
EFSA purity criteria for heavy metals and EU Deforestation Regulation due diligence obligations are tightening supplier qualification protocols across European markets. Importers must now document farm-level geolocation data and deforestation-free status for every cocoa bean shipment. Smallholder-dependent supply chains in Ghana and Ivory Coast face the steepest compliance burden as they retrofit traceability infrastructure.
Direct-to-manufacturer contracting is displacing commodity exchange purchases among premium chocolate makers. Bean-to-bar producers in Brooklyn, Brussels, and Berlin are negotiating multi-year offtake agreements with single-origin cooperatives. This pattern is most visible in Germany, where artisanal manufacturers source directly from Ghana's ABOCFA and Ivory Coast's ECookim cooperatives, bypassing Amsterdam and London futures markets.
Global Cocoa Nibs Market Segmentation
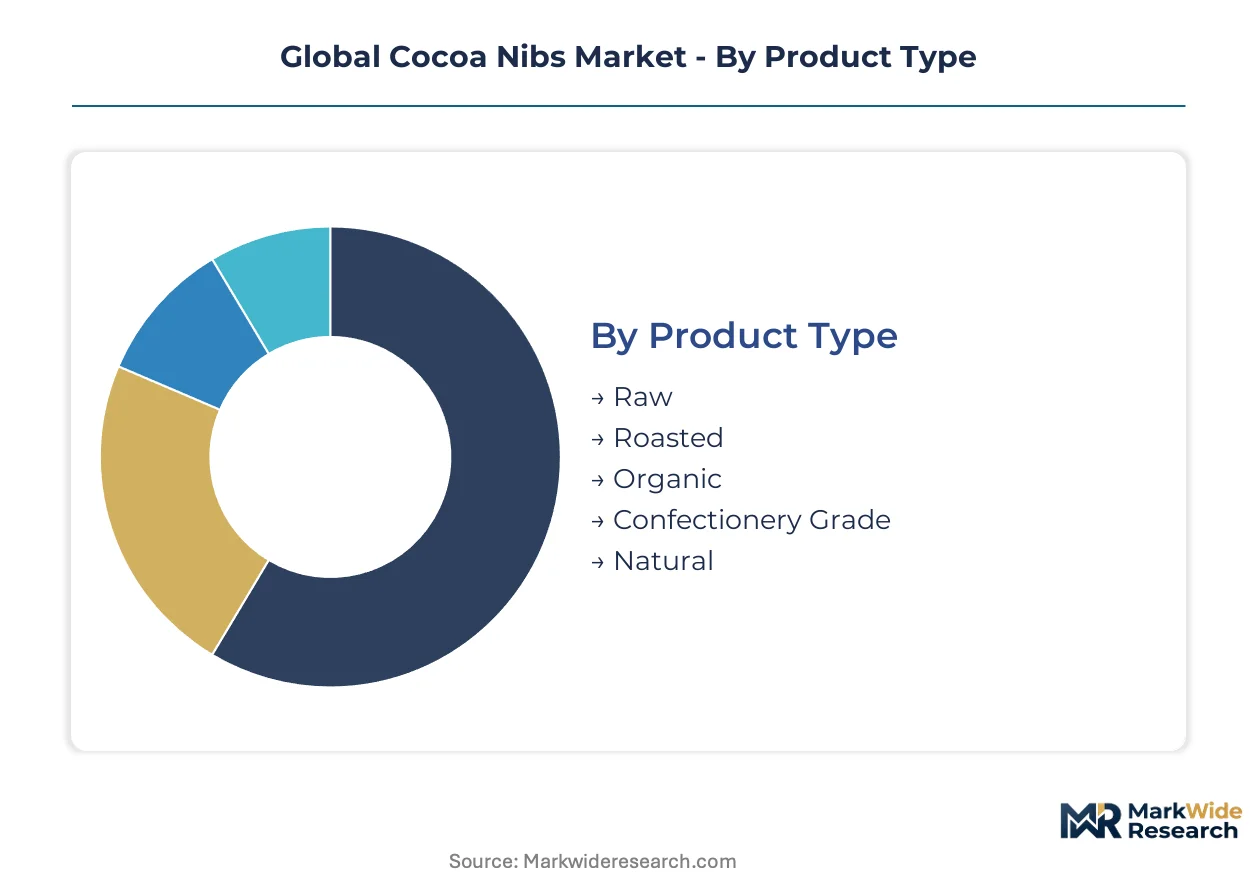
Cocoa nibs command divergent price premiums and processing investments depending on certification status and thermal treatment. Segmentation reveals where capital deployment concentrates and which buyer specifications reshape supplier qualification requirements.
Product Type:
Capital intensity varies sharply across processing stages, with thermal treatment and organic certification demanding the heaviest infrastructure outlays.
- Roasted:Thermal processing between 120-150°C develops Maillard-reacted flavor compounds preferred by German artisanal chocolate makers and Belgian confectionery houses. Roasting equipment requires substantial energy inputs and precise temperature control systems that smaller processors struggle to finance.
- Organic:Certification mandates three-year transition periods, segregated supply chains, and annual third-party audits that elevate working capital requirements by 40-60% over conventional processing. North American natural retail channels in the United States absorb the majority of organic-certified volume.
- Raw:Unroasted nibs retain higher polyphenol concentrations for nutraceutical extraction, commanding premium positioning in supplement formulations.
- Confectionery Grade:Uniform particle size distribution and sub-2% husk residue specifications serve industrial chocolate manufacturers in Switzerland and Italy.
- Natural:Conventionally processed nibs without organic certification compete on price in bulk foodservice channels across France and the Netherlands.
Most installed capacity flows through Roasted. Expansion is steepest in Organic.
Application:
Volume concentration and margin structure diverge significantly across end-use categories, with functional food positioning extracting the highest value per kilogram.
- Nutraceuticals:Standardized polyphenol extracts for cardiovascular health supplements require HPLC-verified flavanol content above 8%, driving specification tightening among United States formulators. FDA dietary supplement cGMP compliance adds regulatory overhead that filters out smaller suppliers.
- Snacks:Clean-label energy bars and granolas in Germany incorporate nibs as texture and antioxidant contributors, with bean-to-bar manufacturers in Berlin sourcing directly from Ghana cooperatives to meet EUDR traceability mandates.
- Baking:Artisan bakeries in Paris and Vienna utilize roasted nibs for bitter chocolate notes in sourdough and viennoiserie applications.
- Beverages:Craft breweries in Belgium and the United States infuse nibs into stouts and porters during secondary fermentation.
- Cosmetics:Cocoa butter extraction from nibs supports natural skincare formulations in France and South Korea.
Snacks absorb the greatest volume tonnage. Nutraceuticals deliver the steepest margin expansion.
End User:
Procurement sophistication and contract structures vary dramatically by buyer scale and technical requirements.
- Food Manufacturers:Industrial chocolate producers in Switzerland and Belgium negotiate multi-year offtake agreements with Ivory Coast cooperatives, embedding EUDR geolocation verification into contract terms. These buyers command the largest single-contract volumes.
- Dietary Supplements:United States nutraceutical brands require Certificates of Analysis documenting heavy metal compliance with FDA food safety standards and polyphenol potency verification.
- Beverage Producers:Specialty coffee roasters and craft breweries in Portland and Copenhagen source smaller lots with origin-specific flavor profiles.
- Personal Care:Cosmetic formulators in France prioritize cocoa butter yield and fatty acid profiles over flavor characteristics.
- Culinary Arts:Michelin-starred restaurants in London and New York procure limited quantities through specialty distributors for plated dessert applications.
Food Manufacturers dominate contract value. Dietary Supplements are gaining share fastest.
Packaging Type:
Packaging selection reflects throughput scale, shelf-life requirements, and retail channel positioning.
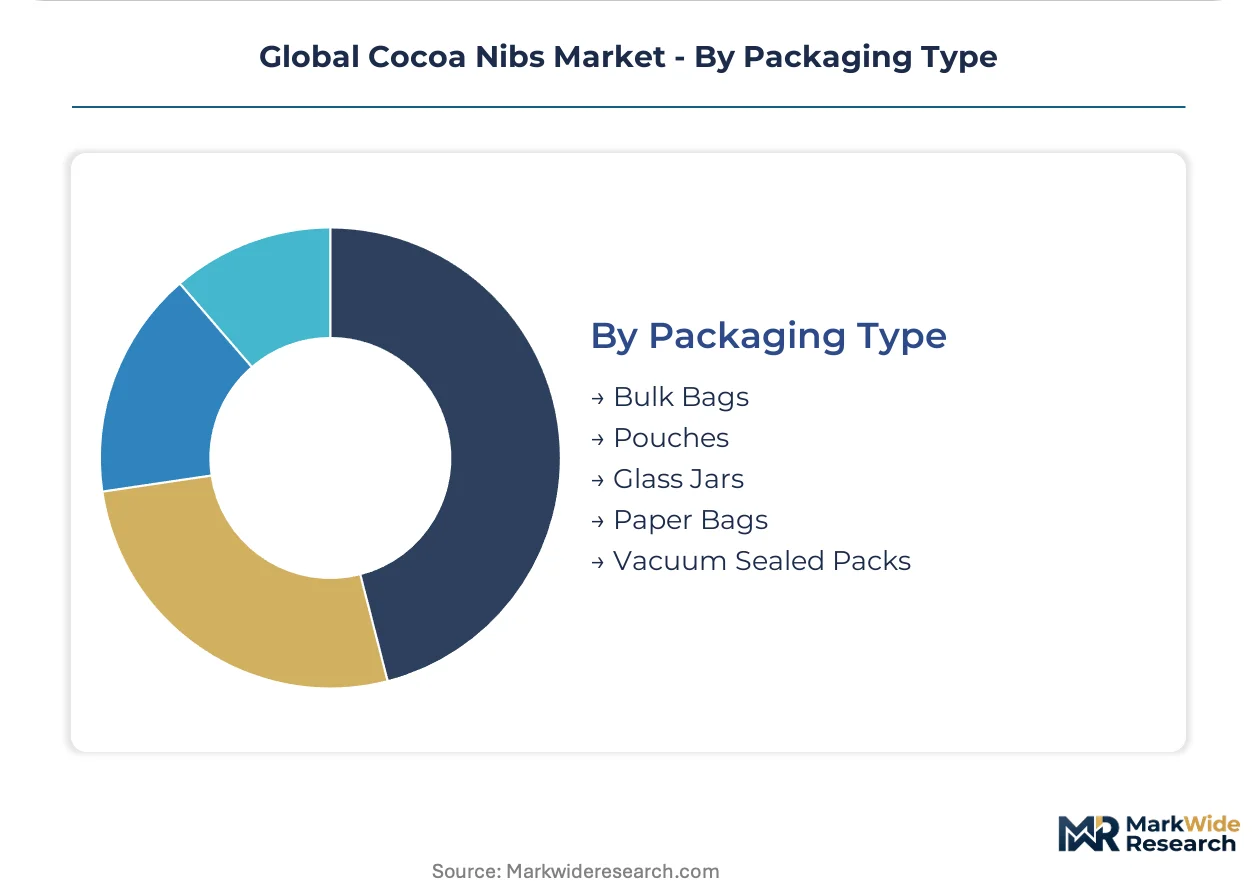
- Bulk Bags:25-50kg multi-wall paper sacks with moisture barriers serve industrial processors in Germany and the Netherlands managing container-scale throughput. These formats minimize per-unit packaging cost but require rapid inventory turnover.
- Vacuum Sealed Packs:Nitrogen-flushed barrier films extend shelf life to 24 months for premium retail channels in the United States and Japan, justifying 3-4x packaging cost premiums.
- Pouches:Stand-up bags with resealable closures target natural retail and specialty grocery in North America.
- Glass Jars:Transparent packaging showcases visual quality for direct-to-consumer brands in Brooklyn and London.
- Paper Bags:Kraft packaging with PLA windows serves zero-waste retailers in Scandinavia and California.
Bulk Bags move the greatest tonnage. Vacuum Sealed Packs are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
West African farmgate cooperatives anchor raw material flows, while European processing clusters and North American nutraceutical formulators reshape value capture across the cocoa nibs supply chain.
Germany
Bean-to-bar manufacturers in Berlin and Hamburg source directly from Ghana's ABOCFA and Ivory Coast's ECookim cooperatives to meet EU Deforestation Regulation traceability mandates. The EUDR due diligence rules compress procurement timelines for artisanal chocolate makers. Bavaria's specialty food processors are retrofitting optical sorting systems to automate husk removal and reduce manual labor dependency.
United States
FDA food safety standards govern import protocols for cocoa nibs entering distribution channels, while nutraceutical formulators in Brooklyn and Portland develop standardized polyphenol extracts. Clean-label snack brands incorporate nibs into energy bars and granolas for natural retail channels. The Pacific Northwest cluster of craft breweries infuses nibs into stouts during secondary fermentation.
Belgium
Confectionery houses in Brussels and Antwerp command premium-grade roasted nibs with Maillard-reacted flavor profiles for praline and couverture applications. EFSA purity criteria for heavy metals reshape supplier qualification protocols. Flemish processing facilities are adopting near-infrared spectroscopy systems to automate bean grading and compress batch-to-batch variance.
Ghana
The Ghana Cocoa Board enforces farmgate pricing and export licensing that directly constrains raw material availability for international buyers. Origin verification technologies are retrofitting traceability infrastructure across smallholder-dependent supply chains. Ashanti Region cooperatives are negotiating multi-year offtake agreements with European bean-to-bar manufacturers.
Switzerland
Industrial chocolate producers negotiate multi-year contracts embedding geolocation verification into terms with West African cooperatives. Swissmedic food safety oversight aligns with EUDR compliance requirements for import channels. Zurich and Geneva processing clusters concentrate confectionery-grade capacity for uniform particle size distribution specifications.
Global Cocoa Nibs Market Competitive Landscape
Capacity expansion dominates the current landscape as processors retrofit traceability infrastructure to meet EU Deforestation Regulation compliance deadlines. The vendor base stratifies across integrated agricultural conglomerates, mid-scale organic specialists, and regional bean-to-bar suppliers. Three archetypes anchor competitive positioning: West African origin-integrated processors, European certification-heavy refiners, and North American nutraceutical-focused formulators. M&A activity and strategic partnerships concentrate on securing farm-level geolocation data capabilities.
Among integrated agricultural conglomerates, Barry Callebaut AG and Cargill, Incorporated exemplify scale-driven archetypes with bean sourcing infrastructure spanning Ghana and Ivory Coast. Olam Food Ingredients occupies a position within the traceability-specialist tier, mapping farm-level origin for retail-ready cocoa nibs. These three entities represent contrasting approaches to EUDR compliance—backward integration into cooperative relationships, captive processing facilities in Abidjan and Tema, and distributed ledger technology deployment for real-time deforestation verification.
| Leading Market Players |
|---|
| Barry Callebaut AG |
| Cargill, Incorporated |
| Olam Food Ingredients |
| Cemoi Group |
| ECOM Agroindustrial Corp. Limited |
| United Cocoa Processor, Inc. |
| Fine Cocoa Products Corporation |
| Navitas Organics |
| BMV Cocoa |
| Others |
Supply & Pricing Matrix
Backward integration into West African cooperative relationships anchors supply position and pricing power for European bean-to-bar manufacturers, compressing procurement timelines while elevating origin-verification premiums. The EU Deforestation Regulation tightens this nexus by mandating geolocation documentation that only integrated buyers can efficiently fulfill.
Pricing Analysis
Farmgate pricing set by Ghana's Cocoa Board and Ivory Coast's Coffee and Cocoa Council drives input-cost pass-through volatility that processors struggle to hedge. Three-tier pricing structure across organic-certified, conventional specialty, and commodity-grade nibs reflects certification burden and traceability investment. Cost compression in conventional tiers is intensifying because spot-market liquidity is thinning under EUDR compliance pressure. Industrial chocolate manufacturers in Switzerland and Belgium exhibit lowest price sensitivity, while bulk foodservice buyers in France and the Netherlands resist premium absorption.
Supply Chain Analysis
Single-source vulnerability sits with Ivory Coast and Ghana, which together feed the majority of raw bean flows into global processing channels. The supply chain draws from fermented cocoa beans, jute bagging materials, and ocean freight capacity from West African ports. Commodity price volatility in farmgate cocoa constitutes the dominant structural risk, compounded by climate exposure across the West African cocoa belt. Distribution runs through Amsterdam and Hamburg port clusters for European processing, with containerized shipments direct to United States East Coast ports for North American nutraceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cocoa nibs market reads as a late-cycle quality story where artisanal chocolate makers and nutraceutical formulators are hardening specifications around polyphenol potency and deforestation-free provenance.
For Market Incumbents: Acquire traceability technology platforms to secure EUDR-compliant geolocation data capabilities before compliance deadlines compress. Consolidate processing capacity in Belgium and Germany to capture optical sorting automation efficiencies that smaller competitors cannot finance. The threat of origin-verification skill gaps among procurement teams elevates platform value. For New Entrants and Emerging Players: Direct-to-manufacturer e-commerce channels targeting Brooklyn and Berlin bean-to-bar makers offer the most penetrable entry vector. White-space exists in USDA Organic-certified raw nibs for United States supplement formulators seeking HPLC-verified flavanol content. A subscription-based sampling program with origin storytelling bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale organic specialists because certification timelines and segregated supply chains create barriers that favor scaled compliance investment. The five-to-ten year viability window hinges on EUDR enforcement breadth and nutraceutical extraction demand. Watch blockchain traceability adoption rates among Ivory Coast cooperatives as the inflection indicator for platform value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Relationships | Secures farm-level geolocation data required by EU Deforestation Regulation compliance protocols. |
| Optical Sorting Technology Deployment | Automates husk removal and bean grading to reduce manual labor dependency in German processing facilities. |
| Organic Certification Investment | Captures premium shelf positioning in United States natural retail channels with three-year transition timelines. |
| Blockchain Traceability Platform | Enables real-time deforestation verification for ESG-compliant buyers sourcing from Ghana cooperatives. |
| Nutraceutical Extraction Partnership | Develops standardized polyphenol extracts for cardiovascular health supplement formulations in Brooklyn. |
Research Methodology
Bottom-up nutraceutical and confectionery end-use modeling reconciled against top-down cocoa bean supply tracking forms the analytical core of this study. Primary interviews with bean-to-bar manufacturers, cooperative export managers, optical sorting equipment suppliers, and FDA regulatory consultants combined with secondary validation from Ghana Cocoa Board export statistics, Ivory Coast Coffee and Cocoa Council licensing data, EFSA purity criteria documentation, and United States customs import records. Triangulation across these sources ensures segmentation integrity.
Input-output matrix framing connects West African farmgate production volumes through processing capacity utilization rates to end-use consumption patterns across the projection horizon. Segmentation dimensions modeled include product type, application category, end-user scale, and packaging format, with organic certification status and EUDR compliance tier as cross-cutting variables. CAGRs were derived from weighted average growth rates across these segments, incorporating cocoa butter price elasticity and polyphenol extraction yield improvements as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for satellite-based deforestation monitoring would alter the outlook if implementation timelines accelerate or compliance thresholds tighten. Forecasts reflect assumptions around EUDR enforcement consistency and farm-level traceability infrastructure investment. Cocoa bean disease outbreaks or cooperative political instability represent specific risk factors that could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
High Protein Cat Food Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Reishi Mushroom Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Global Pine Pollen Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Sofrito Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Asia Pacific Pet Milk Replacers Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Acacia Honey Market
Specialty Foods
Global Nata De Coco Market
Specialty Foods
Halal Market