
 Omega Ingredients Market | 2026-2036
Omega Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Omega Ingredients Market Analytics
Pharmaceutical-grade EPA and DHA concentration tiers is unwinding upward price realization across the value chain. BASF SE leverages backward integration into marine lipid sourcing to sustain margin capture. Koninklijke DSM N.V. anchors its position through synthetic biology pathways for algal-derived omega-3s. Cargill Incorporated competes on oilseed crushing scale, extending its reach into flaxseed oil fractions for food fortification.
Omega ingredients comprise purified long-chain polyunsaturated fatty acids—principally eicosapentaenoic acid and docosahexaenoic acid—extracted via molecular distillation or supercritical CO2 processing, standardized to specific oxidation and heavy-metal thresholds for human and animal consumption. Fish oil dominates volume flows due to established catch-to-capsule infrastructure, while algal oil represents the fastest-growing origin category as biotechnology yields improve and vegan label claims harden in nutraceutical positioning. Softgel formulations command premium shelf space in pharmacy channels, whereas powder forms penetrate infant nutrition and animal feed blending operations.
FDA New Dietary Ingredient notifications and EMA monograph revisions on omega-3 purity standards shape formulation requirements and import clearance protocols for concentrate suppliers. REACH compliance and EU Green Deal sustainability disclosure mandates add traceability costs that favor vertically integrated harvesters over traders. Stakeholders must monitor marine stewardship certification thresholds and cell-culture oil cost curves to calibrate sourcing bets between wild-catch and fermentation-derived supply.
Market Dynamics
EPA/DHA concentration thresholds under EMA and FDA monograph updates are compressing formulation flexibility while elevating API purity requirements across pharmaceutical and nutraceutical channels.
Growth Catalysts
- Chronic disease protocols:Cardiovascular and neurodegenerative treatment guidelines in Germany and the US now incorporate pharmaceutical-grade omega-3 APIs as adjunct therapies, expanding prescription volumes.
- REACH and EU Green Deal mandates:Sustainability disclosure requirements favor vertically integrated harvesters with certified marine stewardship, locking in supply contracts with traceable origin documentation.
- Algal fermentation yields:Biotechnology advances in synthetic biology pathways are reducing production costs for vegan-certified DHA, opening infant nutrition and clean-label positioning.
Market Restraints
- Wild-catch input volatility:Peruvian anchovy quotas and North Atlantic mackerel biomass fluctuations create raw material cost instability for fish oil refiners.
- Heavy-metal compliance burden:EFSA and FDA oxidation and contaminant thresholds require molecular distillation or supercritical CO2 processing investments that raise capex barriers for mid-scale entrants.
- Cell-culture oil cost floor:Fermentation-derived EPA remains 40-60% above marine lipid equivalents, limiting substitution in price-sensitive animal feed applications.
Strategic Opportunities
- India pharmaceutical outsourcing:CDSCO approval pathways for imported APIs create contract manufacturing openings for concentrate suppliers meeting ICH Q7 standards.
- Softgel-to-powder pivot:Infant formula and clinical nutrition brands in Japan and South Korea are requesting microencapsulated powder forms for stability and dosing precision.
- Synthetic biology convergence:CRISPR-edited algal strains combined with continuous fermentation are collapsing DHA production timelines from weeks to days.
Industry Challenges
- Analytical chemist scarcity:EPA/DHA quantification via GC-MS and oxidation stability testing require specialized technicians in short supply across contract labs.
- Multi-jurisdiction dossier complexity:FDA NDI notifications, EMA CEP applications, and TGA ARTG listings demand parallel regulatory teams with divergent documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omega Ingredients Market |
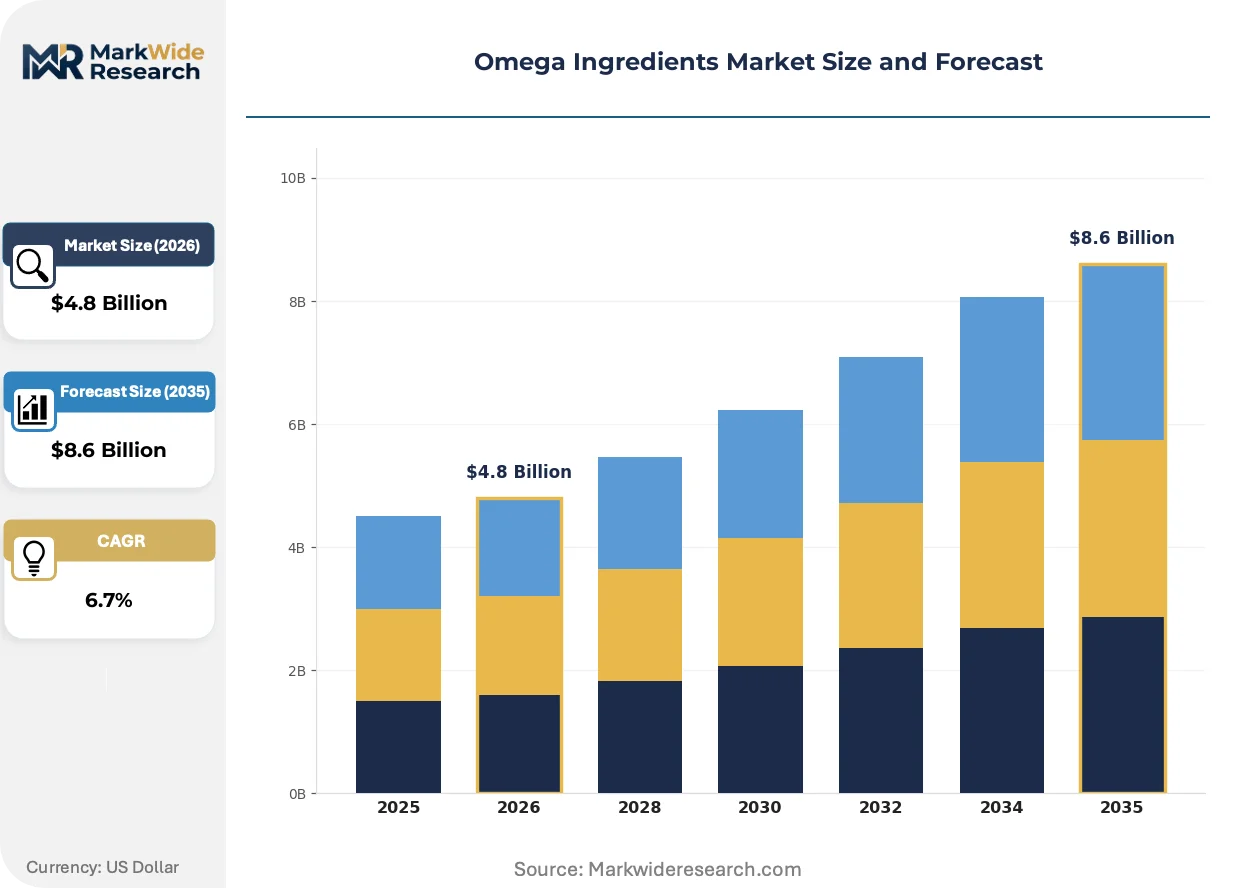
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Flaxseed Oil, Krill Oil, Algal Oil Application: Nutraceuticals, Food & Beverages, Pharmaceuticals, Animal Feed Form: Liquid, Capsule, Powder, Softgel End User: Health-conscious Consumers, Athletes, Patients, Pet Owners |
| Companies Covered | BASF SE, Koninklijke DSM N.V., Cargill Incorporated, Aker BioMarine, Archer Daniels Midland Company, Croda International Plc, Corbion N.V., KD Pharma Group, Omega Protein Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omega Ingredients Market Evolving Landscape
Synthetic biology and precision fermentation are collapsing the cost curve for algal-derived omega-3s, while regulatory tightening on marine sourcing accelerates biotechnology investment.
Supercritical CO2 extraction is supplanting molecular distillation as the preferred concentration method for high-EPA concentrates. Pharmaceutical softgel manufacturers in Germany and Switzerland are adopting CO2 systems to meet tightened oxidation thresholds under revised EMA monographs. This shift is compressing capacity utilization at legacy solvent-based refineries and favoring capital-rich players with captive CO2 infrastructure.
EMA monograph revisions on omega-3 purity standards are forcing reformulation across the European prescription omega-3 segment. Manufacturers must now demonstrate sub-ppm heavy metal residuals and accelerated oxidation stability, triggering revalidation of entire analytical methods. The German pharmacy channel, where KD Pharma and BASF operate concentrated refining facilities, is experiencing the tightest compliance timelines.
Buyer concentration among infant formula multinationals is consolidating procurement around dual-source qualification requirements. Nestlé and Danone are now mandating separate marine and algal supply chains for DHA to mitigate origin risk, displacing single-source fish oil contracts. This pattern is most visible in European and North American sourcing offices, where sustainability scorecards now outweigh unit cost in vendor selection.
Omega Ingredients Market Segmentation
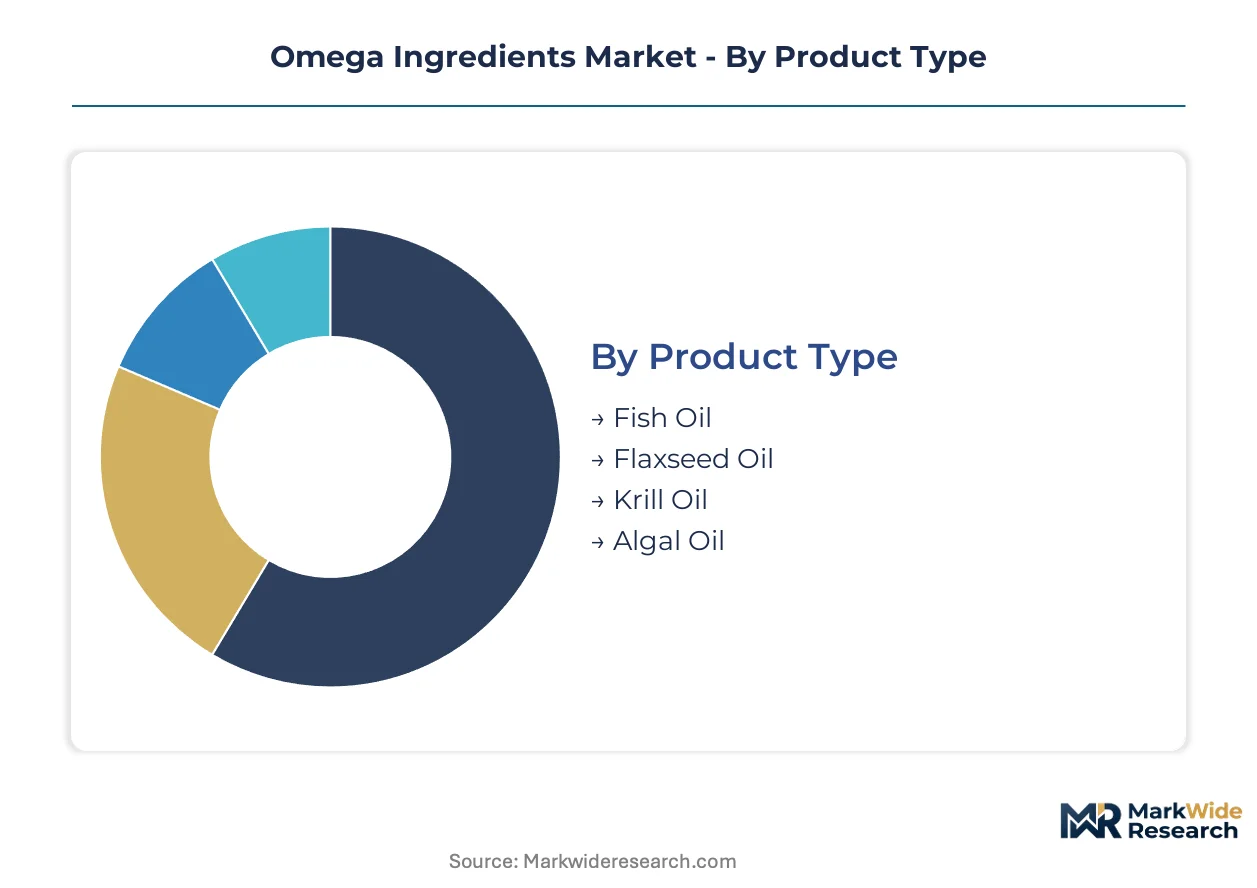
Omega ingredients fragment across four distinct dimensions that determine formulation requirements, regulatory pathways, and margin capture. Product origin dictates heavy-metal compliance burden and vegan certification eligibility. Application channel shapes purity thresholds and packaging specifications.
Product Type:
Algal oil faces the most intense substitution pressure as fermentation yields improve and marine lipid prices fluctuate.
- Fish Oil:Purified long-chain EPA and DHA extracted via molecular distillation from anchovy, mackerel, and sardine biomass. Demand concentrates in German pharmaceutical softgel manufacturing where KD Pharma and BASF operate concentrated refining facilities under tightened EMA oxidation thresholds.
- Algal Oil:Fermentation-derived DHA and EPA from Schizochytrium or Crypthecodinium strains using synthetic biology pathways. Infant nutrition brands in Japan and South Korea are mandating dual-source qualification with algal supply chains to mitigate marine origin risk.
- Flaxseed Oil:Alpha-linolenic acid from oilseed crushing operations; Cargill leverages scale for food fortification applications.
- Krill Oil:Phospholipid-bound omega-3s from Antarctic Euphausia superba harvest; distinct absorption kinetics command premium positioning in nutraceutical channels.
Fish oil retains volume leadership; algal oil holds the steepest expansion curve.
Application:
Cost tier stratification separates pharmaceutical-grade APIs from commodity feed additives.
- Pharmaceuticals:Prescription-grade EPA/DHA concentrates standardized to ICH Q7 purity with sub-ppm heavy metal residuals. Cardiovascular and neurodegenerative treatment guidelines in Germany and the US now incorporate these APIs as adjunct therapies.
- Nutraceuticals:Dietary supplement formulations spanning softgels, liquids, and gummies with variable concentration tiers. FDA New Dietary Ingredient notifications and EMA monograph revisions shape import clearance protocols.
- Food & Beverages:Microencapsulated powders and oil blends for functional food fortification; stability requirements drive powder form adoption.
- Animal Feed:Price-sensitive aquaculture and livestock applications where fish oil dominates; algal oil cost premium limits penetration.
Pharmaceuticals command margin leadership; nutraceuticals deliver the broadest volume base.
Form:
Customer type determines packaging preference between convenience-driven softgels and precision-dosing powders.
- Softgel:Gelatin or plant-based capsule shells containing liquid oil concentrates; pharmacy channel premium positioning.
- Powder:Microencapsulated or free-flowing formats for infant formula and clinical nutrition stability requirements.
- Capsule:Two-piece hard shells for higher-dose nutraceutical applications.
- Liquid:Oil formats for food blending and high-volume feed operations.
Softgel dominates pharmacy revenue; powder is expanding most quickly in Asian infant nutrition.
End User:
Supply concentration aligns with channel access rather than geographic clustering.
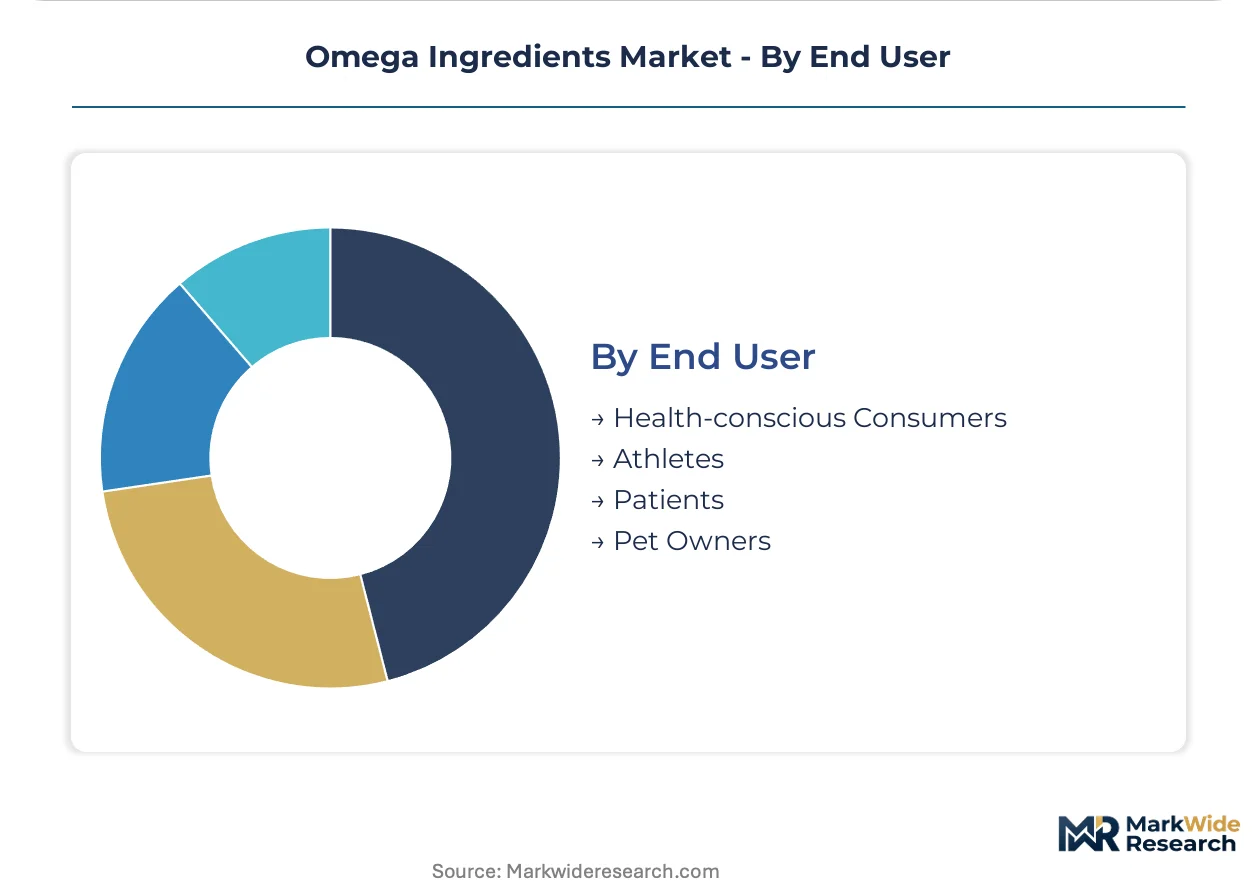
- Health-conscious Consumers:Clean-label seekers driving vegan-certified algal oil demand and marine stewardship verification.
- Patients:Prescription omega-3 recipients under cardiology and neurology protocols; compliance depends on reimbursement status.
- Athletes:Sports nutrition segment prioritizing anti-inflammatory positioning and rapid absorption claims.
- Pet Owners:Premium companion animal nutrition driving DHA inclusion in veterinary formulations.
Health-conscious consumers anchor volume; patients represent the highest value-per-unit capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine lipid refining capacity clusters along North Sea and Baltic coastlines where EMA oversight is tightest. Algal fermentation investments are spreading to Asia-Pacific manufacturing zones seeking CDSCO and MFDS pathway access.
Germany
Cardiovascular prescription protocols drive pharmaceutical-grade EPA/DHA demand through pharmacy channels. EMA monograph revisions on oxidation thresholds force revalidation of analytical methods at concentrated refining facilities. The Schleswig-Holstein corridor hosts molecular distillation and supercritical CO2 processing infrastructure serving continental prescription markets.
United States
FDA New Dietary Ingredient notifications shape import clearance for concentrate suppliers targeting nutraceutical channels. Chronic disease management guidelines now incorporate omega-3 APIs as adjunct therapies in cardiology protocols. The New Jersey and Pennsylvania corridor anchors softgel manufacturing and pharmaceutical packaging operations.
China
Domestic infant formula brands are mandating dual-source DHA qualification to mitigate marine origin risk. NMPA registration pathways for imported APIs create compliance complexity for foreign concentrate suppliers. The Yangtze River Delta concentrates algal fermentation R&D and contract manufacturing capacity.
India
CDSCO approval pathways for pharmaceutical-grade APIs open contract manufacturing opportunities for ICH Q7-compliant suppliers. Nutraceutical demand from urban health-conscious consumers expands distribution through pharmacy and e-commerce channels. The Mumbai-Pune corridor hosts oilseed processing and softgel formulation operations.
Japan
Infant nutrition brands request microencapsulated powder forms for stability and dosing precision in clinical applications. PMDA consultation procedures for novel delivery formats extend development timelines for foreign entrants. The Kansai region maintains specialized refining capacity for high-purity DHA concentrates.
Omega Ingredients Market Competitive Landscape
Concentration sits with diversified chemical conglomerates possessing captive marine lipid sourcing and pharmaceutical-grade refining infrastructure. Mid-scale specialists compete on algal fermentation yields and vegan certification positioning. Strategic archetypes span backward-integrated harvester-refiners, synthetic biology platform operators, and oilseed crushing scale players. Capacity expansion in supercritical CO2 systems and fermentation tank farms represent the dominant competitive moves.
Among diversified chemical conglomerates, BASF SE and Koninklijke DSM N.V. exemplify the backward-integrated archetype with control over marine lipid supply chains. Cargill Incorporated occupies a position as the oilseed crushing scale specialist extending into flaxseed oil fractions. These three entities anchor the competitive structure through distinct sourcing strategies—marine capture, algal fermentation, and oilseed processing—each representing a viable pathway to omega-3 concentrate supply.
| Leading Market Players |
|---|
| BASF SE |
| Koninklijke DSM N.V. |
| Cargill Incorporated |
| Aker BioMarine |
| Archer Daniels Midland Company |
| Croda International Plc |
| Corbion N.V. |
| KD Pharma Group |
| Omega Protein Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Peruvian anchovy harvesters and German refiners lock in supply access and price visibility across the pharmaceutical-grade omega-3 value chain. These arrangements insulate BASF and KD Pharma from spot-market volatility while binding them to minimum volume commitments that shape inventory planning.
Pricing Analysis
EMA monograph revisions dictate the pricing tier structure across the European prescription omega-3 segment. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade APIs with sub-ppm heavy metal certification from nutraceutical concentrates and feed-grade fractions. Price differentiation rests on oxidation stability thresholds and origin documentation rather than brand premium. Cost compression in the standard nutraceutical tier is intensifying because algal fermentation yields are collapsing production timelines. Animal feed buyers exhibit the highest price sensitivity, while prescription channel patients under reimbursement coverage show the least.
Supply Chain Analysis
Strategic stockpile preferences dominate marine lipid procurement given Peruvian anchovy quota volatility and North Atlantic mackerel biomass fluctuations. Supply concentrates in Peru for wild-catch inputs, Germany for pharmaceutical refining, and China for algal fermentation R&D. Raw material dependencies draw from Antarctic krill biomass, Schizochytrium fermentation feedstocks, and flaxseed oilseed crushing. Single-source vulnerability runs through Peruvian anchovy quotas, which supply over half of global EPA/DHA concentrates. Distribution runs through pharmacy channels for prescription products and e-commerce platforms for direct-to-consumer nutraceuticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algal-derived synthetic biology pathways threaten incumbent marine lipid positions as fermentation costs approach parity with wild-catch refining. Incumbents must defend through certification depth and origin traceability rather than volume scale alone.
For Market Incumbents: Fortify backward integration into marine stewardship-certified harvesting operations to secure origin documentation required under EU Green Deal mandates. Deepen analytical chemistry capabilities for EPA/DHA quantification via GC-MS to offset technician scarcity in contract labs. These moves counter synthetic biology entrants racing to collapse DHA production economics.
For New Entrants and Emerging Players: Microencapsulated powder formulation services represent a service-layer gap where incumbents under-serve Japanese and South Korean infant nutrition brands demanding stability and dosing precision. Penetrate the clinical nutrition segment through PMDA consultation pathway expertise. Position on dual-source qualification capabilities that Nestlé and Danone now mandate for DHA procurement.
For Investors and Strategic Acquirers: Synthetic biology platform operators with CRISPR-edited algal strains and continuous fermentation infrastructure present the highest acquisition target archetype for long-term positioning. Monitor algal oil cost curves as the inflection indicator; substitution accelerates when fermentation-derived EPA reaches parity with marine lipid equivalents in price-sensitive applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Meets tightened EMA oxidation thresholds for high-EPA pharmaceutical concentrates. |
| Algal Fermentation Scale-Up | Collapses DHA production timelines from weeks to days via CRISPR-edited strains. |
| Marine Stewardship Certification Program | Locks in EU Green Deal compliance and traceability documentation for pharmacy channels. |
| Backward Integration into Anchovy Harvesting | Secures Peruvian quota access and insulates against wild-catch input volatility. |
| Microencapsulation Technology Licensing | Opens infant formula and clinical nutrition powder form markets in Japan and South Korea. |
Research Methodology
A standing panel of pharmaceutical procurement managers, algal fermentation R&D directors, and regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EMA monograph filings, FDA New Dietary Ingredient notifications, FAO fishery statistics, and EU Green Deal sustainability disclosure records. Bottom-up volume modeling across product origin, application channel, and form factor segments was triangulated against top-down market sizing from customs trade data and industry association reports.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation across product origin, application purity tier, delivery form, and geographic regulatory cluster. CAGRs were derived from fitted growth curves anchored to disclosed capacity expansions and patent filing trajectories. Forecast inputs incorporated algal fermentation yield improvement curves and marine lipid quota allocation patterns.
Forecasts assume regulatory continuity in EMA and FDA monograph regimes; material policy shifts would require re-modeling of compliance cost burdens and import clearance protocols. Revision becomes warranted when algal oil production costs cross below marine lipid equivalents in price-sensitive feed applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Campesterol Market
Ingredients
Europe Dairy Protein Market
Ingredients
Industrial and Bar-B-Que Charcoal Market
Ingredients
North America Vegetable Oils Market
Ingredients
United Kingdom Protein Market
Ingredients
Starch Market
Ingredients
Amaranth Seed Oil Market
Ingredients
Fig Ingredient Market
Ingredients
Dry Malt Products Market
Ingredients
Cold-Pressed Coconut Oil Market
Ingredients
Potato Protein Market
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market
Ingredients
Peanut Flour Market
Ingredients
South America Fats and Oil Market
Ingredients
Egg Membrane Powder Market
Ingredients
Terminalia Extract Market