
 Dried Distillers' Grains with Soluble Market | 2026-2036
Dried Distillers' Grains with Soluble Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Distillers' Grains with Soluble Market Foresight
Bulk-to-bagged packaging flexibility is hardening as a decisive purchasing criterion for mid-size feed operations. Green Plains Inc. leverages its integrated ethanol- feed platform to control unit economics across production and distribution. Cargill Incorporated anchors procurement relationships with large-scale livestock integrators through dedicated supply contracts. POET LLC differentiates via consistent protein specification guarantees that reduce formulation uncertainty for nutritionists.
Dried Distillers' Grains with Soluble refers to the nutrient-rich co-product remaining after starch fermentation for ethanol production, typically containing 27-30% crude protein, 10-12% fat, and residual fiber from the original grain. This material serves primarily as a cost-competitive protein and energy source in formulated animal diets, displacing soybean meal and corn in ruminant, swine, and poultry rations. Modified DDGS commands attention among nutritionists seeking higher metabolizable energy values through reduced fiber content, while pelleted DDGS reduces handling losses and dust exposure during bulk transport. The DDGS-ME variant occupies a narrower but growing niche in aquaculture formulations where precise nutrient density matters.
The US EPA Renewable Fuel Standard and FDA Center for Veterinary Medicine feed safety protocols jointly determine production volumes and product specifications for domestic suppliers. China's NMPA and agricultural import quarantine standards shape market access for international DDGS shipments, with mycotoxin thresholds frequently cited in trade negotiations. Stakeholders must monitor biofuel policy adjustments and precision livestock feeding technology adoption, as both forces will recalibrate the value proposition of distillers' co-products relative to alternative protein sources.
Market Dynamics
The US EPA's Renewable Fuel Standard mandates ethanol blending volumes that sustain distillers' grain co-product output, while livestock producers in North America expand DDGS inclusion rates as corn prices fluctuate. This regulatory-production nexus creates structural interdependence between biofuel policy and feed ingredient supply.
Growth Catalysts
- Ethanol mandate compliance:The US EPA Renewable Fuel Standard sustains baseline DDGS production volumes by requiring minimum renewable fuel blending. This creates captive supply for feed processors.
- Protein displacement economics:Ruminant nutritionists in the US Midwest actively reformulate diets to substitute DDGS for soybean meal when relative pricing favors the co-product.
- Integrated cluster efficiency:Ethanol-feed processing hubs in Iowa and Nebraska minimize logistics costs through co-located production, strengthening unit economics against dispersed competitors.
Market Restraints
- Corn price volatility:Input cost swings for the primary feedstock compress ethanol processor margins and destabilize DDGS pricing predictability for buyers.
- Chinese import barriers:China's NMPA mycotoxin thresholds and agricultural quarantine standards frequently block US DDGS shipments, constraining export market access.
- Metabolizable energy ceiling:Residual fiber content limits DDGS inclusion rates in monogastric diets compared to corn, creating formulation ceilings for swine and poultry nutritionists.
Strategic Opportunities
- Modified DDGS expansion:Reduced-fiber processing variants command premium positioning in aquaculture formulations where precise nutrient density matters.
- Pelletization infrastructure:Dust-reduced handling formats open channel access to automated bulk-receiving operations previously deterred by material handling losses.
- Precision livestock feeding:Real-time ration optimization technology enables dynamic DDGS inclusion rate adjustment based on daily commodity price signals.
Industry Challenges
- Formulation expertise scarcity:Nutritionists capable of balancing variable DDGS protein and fat specifications against amino acid profiles remain concentrated at large integrators.
- Quality certification timelines:FDA Center for Veterinary Medicine feed safety protocol compliance creates batch-release delays that conflict with just-in-time delivery requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Distillers' Grains with Soluble Market |
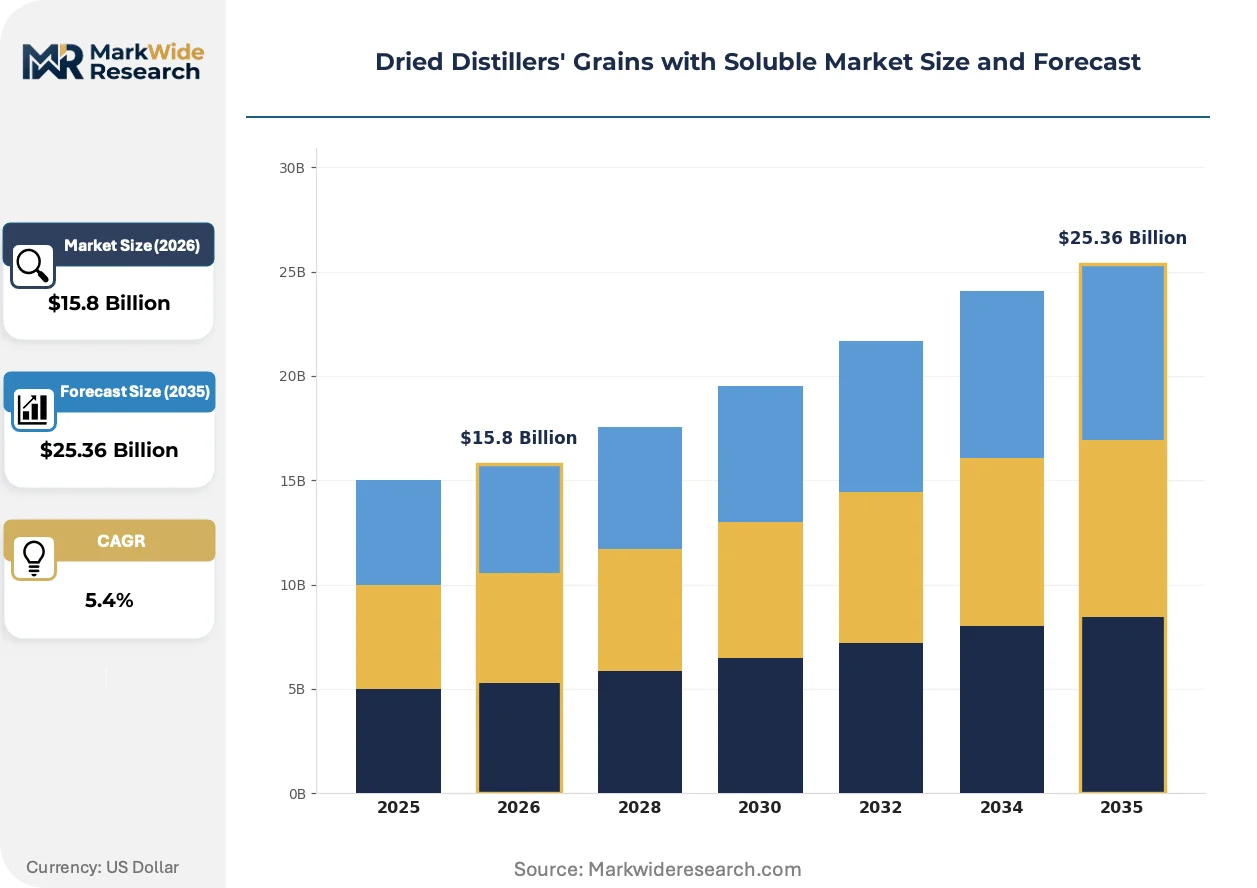
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $25.36 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DDGS, Modified DDGS, Pelleted DDGS, DDGS-ME End Use Industry: Animal Feed, Aquaculture, Pet Food, Biofuels Form: Powder, Granules, Pellets, Liquid Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Green Plains Inc., Cargill Incorporated, Archer Daniels Midland Company, Flint Hills Resources, CropEnergies AG, POET LLC, CHS Inc., Land O'Lakes Inc., Valero Energy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Distillers' Grains with Soluble Market Shifts & Advancements
Processing technology advances and regulatory recalibration are compressing product development cycles while reshaping buyer-supplier relationships. These forces favor operators with integrated production platforms and flexible packaging capabilities.
Near-infrared spectroscopy systems for real-time protein and moisture testing are modularizing quality assurance workflows at receiving terminals. Large-scale livestock integrators in Nebraska and Kansas deploy these units to reject off-specification loads before unloading. This capability is modularizing procurement risk management by enabling spot-market purchasing without laboratory turnaround delays.
The EU Green Deal's sustainability certification requirements for imported feed ingredients are tightening traceability obligations for DDGS exporters. European livestock cooperatives now demand batch-level ethanol plant origin documentation. Swine operations in Denmark and the Netherlands have restructured supplier qualification processes to accommodate these verification protocols.
Consolidated buying desks at protein companies are compressing supplier rosters and demanding multi-year volume commitments with price collars. This concentration shifts negotiation leverage toward buyers with storage capacity and formulation flexibility. The pattern is most visible across integrated poultry operations in the southeastern United States, where three-procurement-officer teams now manage national ingredient sourcing.
Dried Distillers' Grains with Soluble Market Segmentation
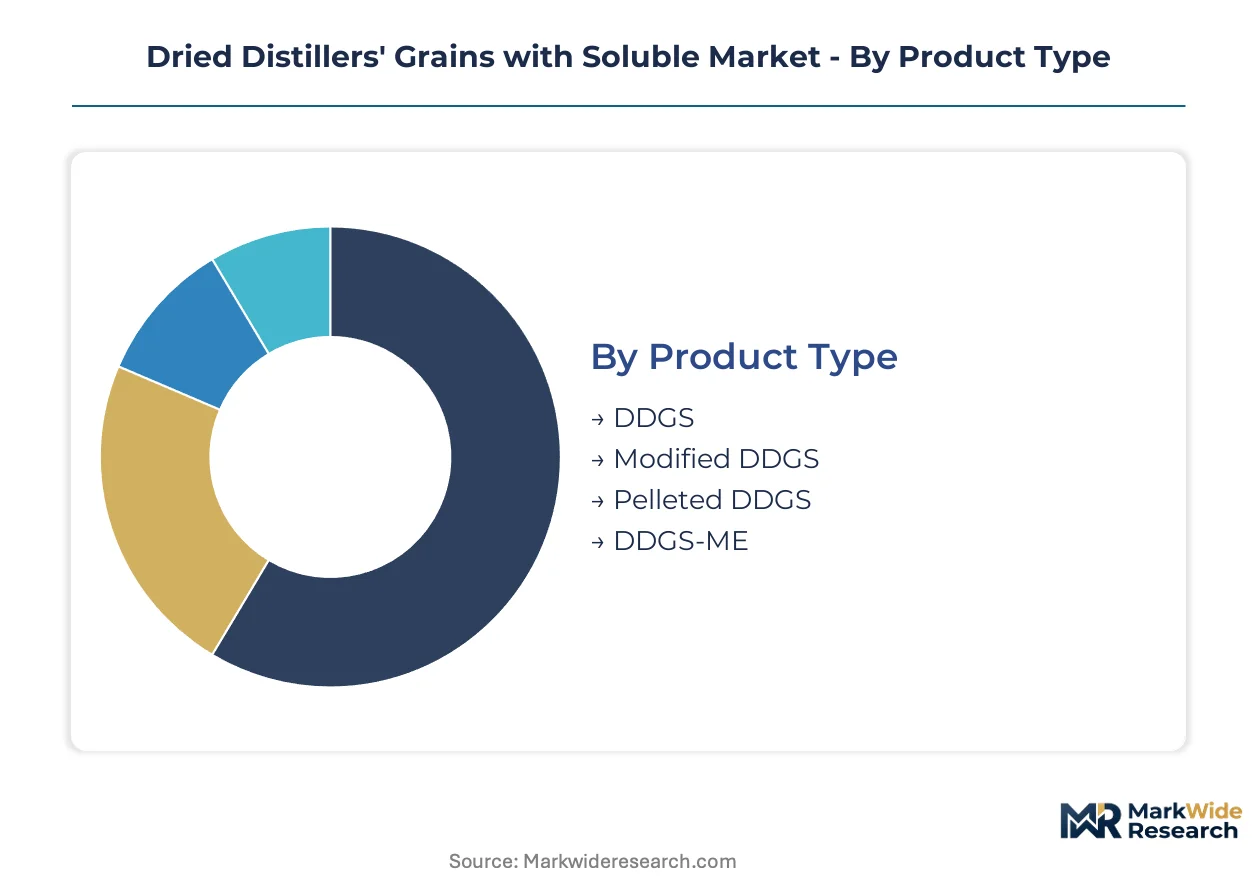
Segmentation in the Dried Distillers' Grains with Soluble Market reveals how processing investments and buyer requirements split value capture across the supply chain. Distinct capital requirements, handling specifications, and channel economics shape competitive positioning within each dimension.
Product Type:
Capital intensity varies sharply across processing variants, with thermal modification and pelletization equipment representing the largest upfront outlays.
- DDGS:The standard dried co-product contains 27-30% crude protein and 10-12% fat, serving as the baseline protein-energy source for ruminant formulations. Demand concentrates among Midwest cattle feedlots in Iowa and Nebraska where proximity to ethanol plants minimizes delivered cost.
- Modified DDGS:Reduced-fiber processing via partial oil extraction elevates metabolizable energy values, commanding premium positioning in aquaculture diets where precise nutrient density determines feed conversion ratios. Danish salmon operations specify this variant for grower-phase rations.
- Pelleted DDGS:Compacted format reduces dust exposure and handling losses during automated bulk receiving.
- DDGS-ME:High-metabolizable energy variant occupies narrow aquaculture niche requiring strict amino acid balancing.
Standard DDGS absorbs the bulk of installed capacity; Modified DDGS is expanding most quickly.
End Use Industry:
Formulation sophistication and volume scale determine customer acquisition economics across downstream applications.
- Animal Feed:Ruminant, swine, and poultry nutritionists deploy DDGS as cost-competitive protein displacing soybean meal and corn. US Midwest integrators in Kansas and Nebraska actively reformulate inclusion rates based on daily commodity spreads.
- Aquaculture:Salmon and shrimp operations in Denmark and the Netherlands demand modified variants with guaranteed metabolizable energy specifications and batch-level origin documentation under EU Green Deal traceability protocols.
- Pet Food:Premium kibble manufacturers utilize DDGS for protein fortification with palatability masking requirements.
- Biofuels:Anaerobic digestion and thermal conversion applications exploit residual energy content in off-specification or expired material streams.
Animal Feed commands dominant volume share; Aquaculture shows the steepest expansion trajectory.
Form:
Physical state selection hinges on handling infrastructure compatibility and nutrient preservation requirements during storage and transport.
- Powder:Fine-ground material maximizes surface area for rapid nutrient release in controlled-environment feeding systems but requires dust suppression measures.
- Granules:Intermediate particle size balances flowability with dissolution kinetics, preferred by mid-size feed mills lacking pneumatic handling systems.
- Pellets:Densified format reduces transportation volume by 15-20% and eliminates segregation during bulk shipment, critical for automated receiving operations at large integrators.
- Liquid:Soluble extract form enables precision inclusion in total mixed rations and liquid feed supplements.
Pellets dominate bulk logistics channels; Granules gain share among regional feed manufacturers upgrading handling systems.
Distribution Channel:
Channel selection reflects buyer scale, storage capacity, and price risk management capabilities.
- Direct Sales:Ethanol producers contract directly with large livestock integrators for offtake volumes exceeding 10,000 tons annually, with pricing tied to corn futures spreads.
- Retail:Bagged product sales serve hobby farmers and small-scale operations through farm supply cooperatives.
- Online:Digital procurement platforms emerge for spot purchases by nutritionists seeking price transparency and rapid delivery scheduling.
- Distributors:Regional aggregators consolidate volumes from multiple ethanol plants to offer blended specifications and just-in-time delivery to mid-size feed operations.
Direct Sales capture the majority of volume throughput; Online channels are climbing the fastest among emerging procurement methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Renewable Fuel Standard tax incentives anchor production concentration in Iowa and Nebraska ethanol-feed processing corridors. These zones minimize logistics costs through co-located distillation and drying infrastructure.
United States
Midwest cattle feedlots in Kansas and Nebraska expand DDGS inclusion rates as corn price volatility pressures protein displacement economics. The US EPA Renewable Fuel Standard mandates ethanol blending volumes that sustain baseline co-product output. Integrated clusters in Iowa concentrate 60% of national distillation capacity with captive feed processing.
China
Domestic ethanol expansion and livestock sector consolidation drive modified DDGS demand for precision aquaculture formulations. China's NMPA mycotoxin thresholds and agricultural quarantine standards block most US shipments, forcing reliance on domestic supply. Shandong Province ethanol processors serve regional pig farming operations with reduced-fiber variants.
Germany
Danish and Dutch livestock cooperatives demand batch-level origin documentation under EU Green Deal traceability protocols. CropEnergies AG operates integrated facilities supplying modified DDGS to salmon operations in Scandinavia. The EFSA feed safety framework governs import specifications and residual contaminant limits.
Brazil
Sugarcane ethanol dominance limits corn-based DDGS scale, though expanding corn ethanol investments in Mato Grosso signal supply growth. ANVISA feed safety regulations align with international mycotoxin standards. São Paulo state processors experiment with bagged distribution formats for regional dairy cooperatives.
Canada
Prairie province feedlots source DDGS from US Midwest exporters as domestic ethanol capacity remains limited. Health Canada and PMRA joint oversight governs feed safety and veterinary drug residue protocols. Alberta cattle operations integrate DDGS into backgrounding rations during winter feeding periods.
Dried Distillers' Grains with Soluble Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the DDGS value chain. The market structure consolidates around integrated ethanol-feed processors with captive supply advantages and independent distributors serving fragmented regional feed operations. Three archetypes dominate: multi-plant ethanol operators with downstream feed platforms, agricultural trading houses with procurement scale, and cooperative-owned processors with farmer-member supply security. Capacity expansion and strategic partnerships constitute the primary competitive moves, with operators seeking geographic coverage and formulation expertise.
Among US-based integrated processors, Green Plains Inc., POET LLC, and Valero Energy Corporation exemplify the ethanol-to-feed platform archetype. These operators control unit economics through co-located distillation and drying infrastructure. Cargill Incorporated and Archer Daniels Midland Company represent agricultural conglomerates leveraging procurement relationships with large-scale livestock integrators. CHS Inc. and Land O'Lakes Inc. occupy the cooperative structure tier with farmer-member governance and regional supply security.
| Leading Market Players |
|---|
| Green Plains Inc. |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Flint Hills Resources |
| CropEnergies AG |
| POET LLC |
| CHS Inc. |
| Land O'Lakes Inc. |
| Valero Energy Corporation |
| Others |
Supply & Pricing Matrix
Pelletization infrastructure deployment across Iowa and Nebraska ethanol corridors simultaneously compresses handling costs and concentrates supply leverage among integrated processors. This capital-intensive shift rewards operators with captive drying capacity while marginalizing dispersed competitors dependent on third-party logistics.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with spot inventory commanding discounts against annual offtake agreements. Contract-based long-term offtake structures prevail, with price differentiation hinging on protein specification guarantees and bulk-to-bagged flexibility. Pricing pressure stems from corn futures volatility that destabilizes processor margin calculations. Mid-size feed operations exhibit highest price sensitivity due to limited storage capacity, while large integrators with formulation flexibility absorb variability.
Supply Chain Analysis
Regional distribution centers in Iowa, Nebraska, and Kansas anchor hub-and-spoke patterns that minimize last-mile costs to cattle feedlots. Supply concentrates in the United States, with secondary nodes in China and Germany serving captive domestic ethanol output. Corn feedstock, natural gas for drying, and transport logistics constitute critical input dependencies. Tariff exposure through Chinese NMPA quarantine restrictions creates structural export risk. Distribution runs through direct sales channels for volumes exceeding ten thousand tons annually.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near-infrared spectroscopy deployment at receiving terminals signals a technology-transition phase, displacing laboratory-based quality verification with real-time protein and moisture testing.
For Market Incumbents: Hedge against formulation expertise scarcity by embedding nutritionist teams within large integrator accounts. Secure backward integration into corn origination to buffer margin compression from feedstock volatility. Prioritize FDA Center for Veterinary Medicine certification investments to accelerate batch-release timelines against just-in-time delivery demands.
For New Entrants and Emerging Players: Capture white-space in modified DDGS supply for Danish and Dutch aquaculture operations demanding EU Green Deal traceability documentation. Target underpenetrated pelletized distribution to automated bulk-receiving operations in southeastern US poultry integrators. Lead with digital procurement platforms offering price transparency and rapid delivery scheduling.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated ethanol-feed platform acquisitions by agricultural conglomerates seeking captive supply advantages. Long-term viability favors operators with co-located distillation and drying infrastructure across the projection horizon. Monitor biofuel policy adjustments under the US EPA Renewable Fuel Standard as the critical inflection signal for production volume sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Pelletization Infrastructure Deployment | Reduces handling losses and dust exposure for automated bulk-receiving operations at large integrators. |
| Modified DDGS Capacity Expansion | Captures premium positioning in aquaculture formulations requiring precise metabolizable energy specifications. |
| Near-Infrared Spectroscopy Integration | Enables real-time quality verification at receiving terminals without laboratory turnaround delays. |
| Direct Sales Contract Structuring | Locks in volume commitments with price collars from large livestock integrators with storage capacity. |
| EU Green Deal Traceability Certification | Unlocks market access for Danish and Dutch livestock cooperatives demanding batch-level origin documentation. |
Research Methodology
Document review covered EPA regulatory filings, FDA feed safety protocols, and ethanol production databases, complemented by interviews with plant managers at Midwest ethanol processors, procurement leads at Kansas cattle feedlots, nutritionists at large poultry integrators, and distribution channel partners. Secondary validation drew from USDA crop reports, EIA biofuel statistics, and customs trade records. Bottom-up volume estimates triangulated against top-down demand projections from livestock inventory data.
Cross-referencing historical price spreads against panel input from procurement officers anchored the analytical framework across the modeling period. Segmentation dimensions included product type, end-use industry, physical form, and distribution channel complexity. CAGRs derived from regression analysis of ethanol mandate compliance trajectories and livestock sector consolidation patterns. Industry-specific forecast inputs incorporated corn futures volatility indices and precision livestock feeding technology adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biofuel policy recalibration and Chinese import barrier adjustments. Outputs reflect documented assumptions regarding Renewable Fuel Standard continuity and mycotoxin threshold stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
Specialty Flours Market
Ingredients
Volatile Fatty Acids Market
Ingredients
Anhydrous Caffeine Market
Ingredients
Bromelain Ingredient Market
Ingredients
Wheat Malt Market
Ingredients
Organic Edible Oil Market
Ingredients
Organic Starch Market
Ingredients
Caramel Ingredient Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
L-Arabinose Market
Ingredients
GCC Egg Powder Market
Ingredients
Pepsin Market
Ingredients
Hibiscus Extract Market
Ingredients
Rice Starch Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market