
 Cooking Oils and Fats Market | 2026-2036
Cooking Oils and Fats Market Size, Share, and Industry Trends Forecast 2026-2036
Cooking Oils and Fats Market Analysis
Market Context
REACH is broadening the cost-of-entry calculus for European processors by mandating exhaustive substance safety documentation across the supply chain. Wilmar International Limited leverages its integrated plantation-to-refinery footprint to absorb these compliance burdens without margin erosion. Cargill Incorporated anchors its position through deep backward integration into North American oilseed crushing. Bunge Limited competes by dominating South American origination and export logistics.
Technical Definition and Segment Structure
Cooking oils and fats encompass triglyceride-based lipid products derived from vegetable, animal, or synthetic sources, characterized by smoke points ranging from 160°C for unrefined flaxseed oil to 270°C for refined avocado oil, serving primarily as heat-transfer media, flavor carriers, and texture modifiers in food preparation. Palm oil occupies the dominant volume position due to its cost-efficiency and versatility across frying, baking, and confectionery applications, while extra virgin olive oil commands the premium tier through Protected Designation of Origin certifications and polyphenol-linked health positioning. The food service end user segment represents the fastest-expanding demand pool as quick-service restaurants and cloud kitchens standardize high-stability frying mediums across multi-unit operations.
Regulatory Frame and Outlook
EMA, EFSA, and FDA collectively govern permissible contaminant thresholds, labeling protocols, and novel food approvals across the three largest consumption blocs, with each regulator tightening enforcement on 3-MCPD ester limits and trans-fat reduction mandates. The EU Green Deal and CSRD disclosure requirements are forcing processors to document scope-three emissions from agricultural sourcing through retail distribution. Stakeholders must monitor divergence between European precautionary standards and American risk-based frameworks when allocating reformulation budgets and regional product portfolios.
Market Dynamics
High-oleic oil adoption is compressing frying stability standards across food service chains, forcing processors to reconfigure refining investments toward oxidative resistance metrics rather than commodity volume throughput.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-emission processing equipment are accelerating capital turnover toward closed-loop extraction systems, creating upgrade cycles across Mediterranean olive oil cooperatives.
- Cloud kitchen proliferation:Centralized frying operations in urban delivery hubs are standardizing high-stability oil procurement at contract volumes previously unseen in fragmented food service.
- Southeast Asian palm clusters:Integrated plantation-to-port infrastructure in Malaysia and Indonesia is compressing logistics costs for refined, bleached, deodorized output.
Market Restraints
- Input cost volatility:Soybean and sunflower seed prices swing with Black Sea corridor disruptions, squeezing crush margins for European independents without origination assets.
- Supply concentration risk:Indonesian and Malaysian palm oil production controls roughly 85 percent of global vegetable oil trade volume, exposing buyers to export levy shocks.
- REACH documentation burden:ECHA substance safety dossiers require 18-24 month lead times for novel processing aids, freezing formulation innovation pipelines.
Strategic Opportunities
- CSRD disclosure mandates:EU Green Deal scope-three reporting requirements are creating premium tiers for processors with verified deforestation-free supply chains.
- Avocado oil expansion:Cold-pressed variants are penetrating premium retail in Germany and the Netherlands as polyphenol positioning displaces conventional extra virgin olive oil.
- Direct-to-food service platforms:Digital procurement channels are disintermediating traditional distributor layers for mid-scale restaurant groups in São Paulo and Mexico City.
Industry Challenges
- Refining chemist scarcity:Expertise in 3-MCPD ester mitigation and trans-fat reduction is concentrating at major integrated processors, leaving regional independents exposed to regulatory non-compliance.
- Capex intensity for deodorization:Vacuum stripping systems capable of sub-0.5 percent trans-fat output require 40-60 million dollar investments that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooking Oils and Fats Market |
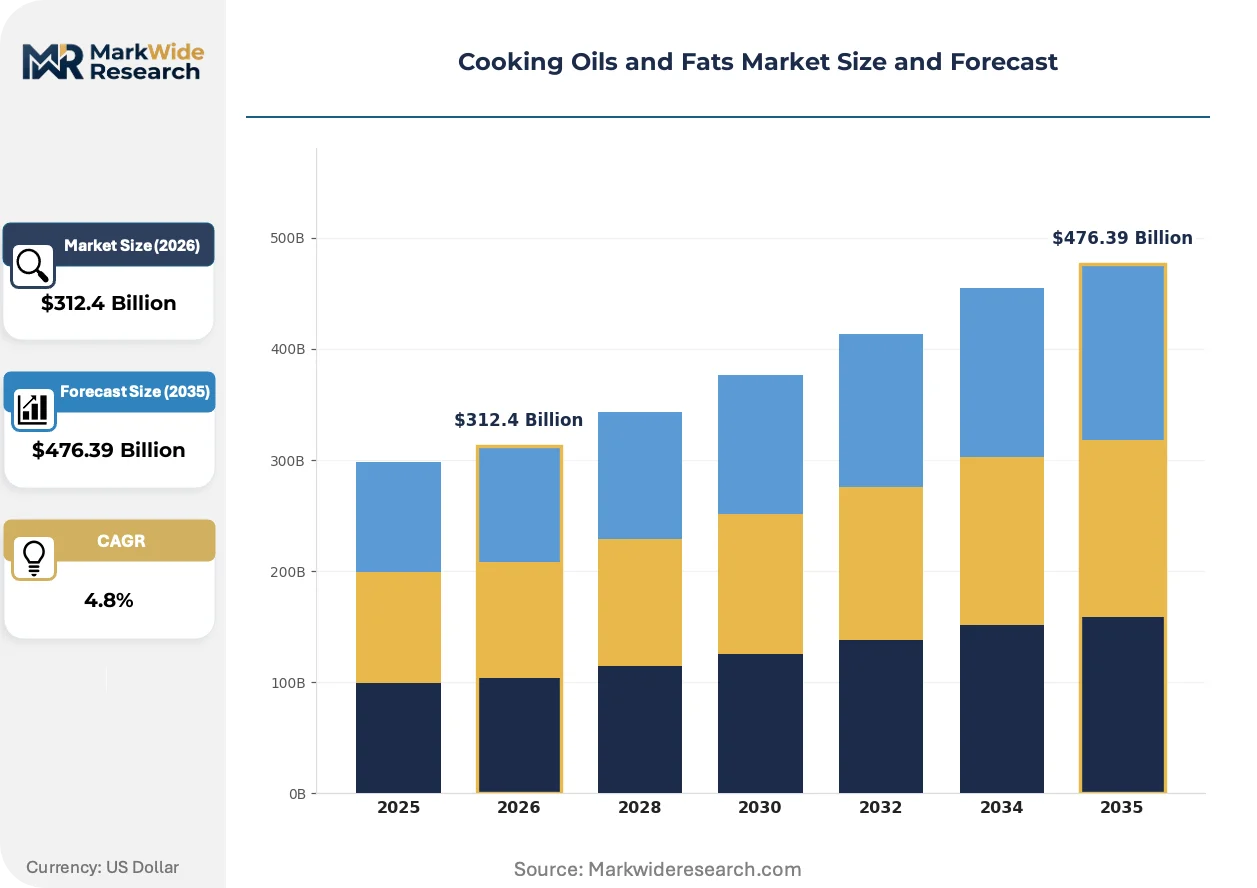
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $476.39 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oil, Olive Oil, Coconut Oil, Palm Oil Form: Liquid, Solid, Semi-Solid, Spray End User: Household, Food Service, Industrial, Bakery Grade: Refined, Crude, Extra Virgin, Organic |
| Companies Covered | Archer Daniels Midland Company, Wilmar International Limited, Cargill Incorporated, Bunge Limited, Associated British Foods PLC, Ajinomoto Co., Inc., Mewah International Inc., United Plantations Berhad, Olam International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooking Oils and Fats Market Emerging Trajectories
Enzymatic interesterification and precision fermentation are rewriting lipid functionalization pathways, separating processors with biotech capabilities from legacy chemical refiners.
Enzymatic interesterification is rewriting the economics of structured fat production by enabling room-temperature rearrangement of triglyceride profiles without hydrogenation. Quick-service chains in the United States are adopting enzymatically modified high-oleic shortenings to eliminate trans-fats while maintaining fry life. This technology is compressing the premium commanded by fully hydrogenated legacy alternatives.
REACH substance authorization timelines are extending reformulation windows for European processors seeking novel emulsifier approvals. EFSA evaluations for 3-MCPD ester limits are forcing simultaneous reformulation across infant formula and confectionery applications. Margarine manufacturers are responding by accelerating backward integration into controlled chemical refining.
Consolidated procurement by multi-unit food service operators is displacing spot-market purchasing for frying oils across North American and Western European markets. Contract structures now specify oxidative stability indices and carbon intensity scores alongside price. This behavioral shift is most visible in the United Kingdom, where burger chains and chicken concepts have centralized oil specification authority at the corporate level.
Cooking Oils and Fats Market Segmentation
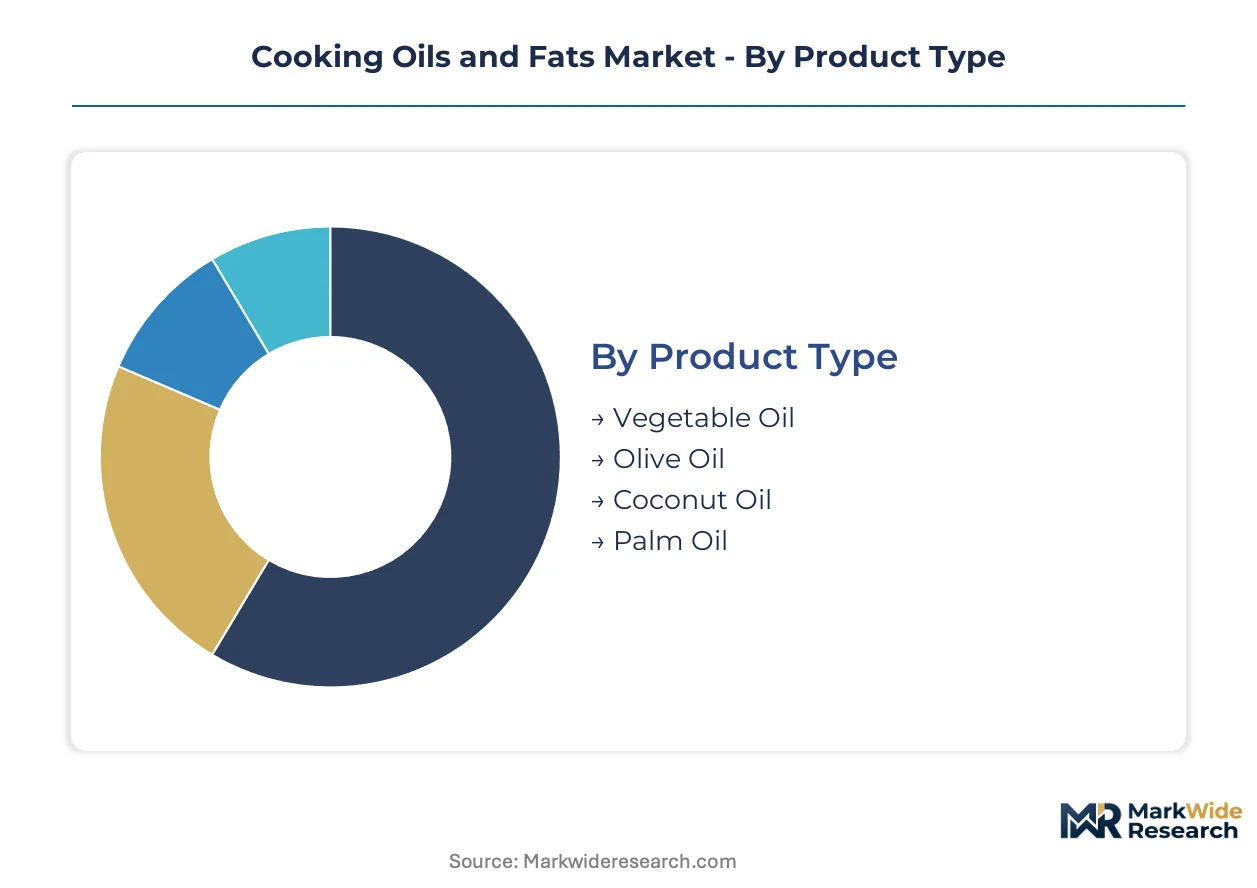
Segmentation in cooking oils and fats separates commodity volume plays from premium extraction margins. Refining intensity, certification tiers, and end-use thermal stability requirements create distinct competitive battlegrounds across each dimension.
Product Type:
Volume concentrates in seed oils while premium accrues to origin-certified grades with polyphenol retention.
- Vegetable Oil:Soybean, canola, and sunflower blends dominate industrial frying and packaged food manufacturing through cost-optimized fatty acid profiles. Food service chains in the United States are standardizing high-oleic soybean variants to extend fry life without hydrogenation.
- Olive Oil:Extra virgin grades with Protected Designation of Origin status command retail premiums through phenolic compound positioning. Italian and Spanish cooperatives are consolidating around early-harvest extraction to differentiate against seed oil commoditization.
- Coconut Oil:Cold-pressed virgin variants serve functional food and cosmetic applications with medium-chain triglyceride labeling.
- Palm Oil:Refined, bleached, deodorized output from Malaysian and Indonesian integrated processors supplies global confectionery and instant noodle markets at the lowest per-calorie lipid cost.
Today's leader: Palm Oil. Tomorrow's challenger: Olive Oil.
Form:
Physical state determines packaging economics, shelf stability engineering, and application-specific dispensing infrastructure.
- Liquid:Pourable oils in PET and glass bottles dominate retail household penetration and bulk food service dispensing. Cloud kitchen operators in São Paulo are specifying bag-in-box liquid formats to reduce handling labor in centralized frying operations.
- Solid:Fully hydrogenated and interesterified fats provide structure in laminated dough and confectionery coatings. North American bakeries are shifting toward enzymatically modified solid shortenings to eliminate trans-fat labeling while maintaining creaming functionality.
- Semi-Solid:Tub margarines and spreads balance spreadability with oxidative stability through controlled crystallization.
- Spray:Aerosolized oils with propellant systems target low-fat cooking positioning and precise portion control in household segments.
Household convenience favors Liquid. Industrial reformulation is accelerating Solid.
End User:
Procurement scale and specification authority concentrate differently across fragmented households versus consolidated food service operators.
- Household:Supermarket and e-commerce retail channels drive small-format packaging innovation and health-claim labeling. German discounters are private-labeling high-oleic sunflower oil to capture Mediterranean diet positioning at mid-tier price points.
- Food Service:Multi-unit quick-service restaurants and cloud kitchens specify oxidative stability indices and carbon intensity scores in annual contracts. Burger chains in the United Kingdom have centralized oil procurement authority to enforce frying medium consistency across franchise networks.
- Industrial:Snack food and ready-meal manufacturers demand tanker-load volumes with customized fatty acid profiles and extended fry life guarantees.
- Bakery:Laminated dough and cake applications require plastic fat functionality with specific solid fat content curves across temperature ranges.
Contract discipline is tightest in Food Service. Volume scale peaks in Industrial.
Grade:
Processing intensity separates commodity throughput from premium extraction with traceability documentation.
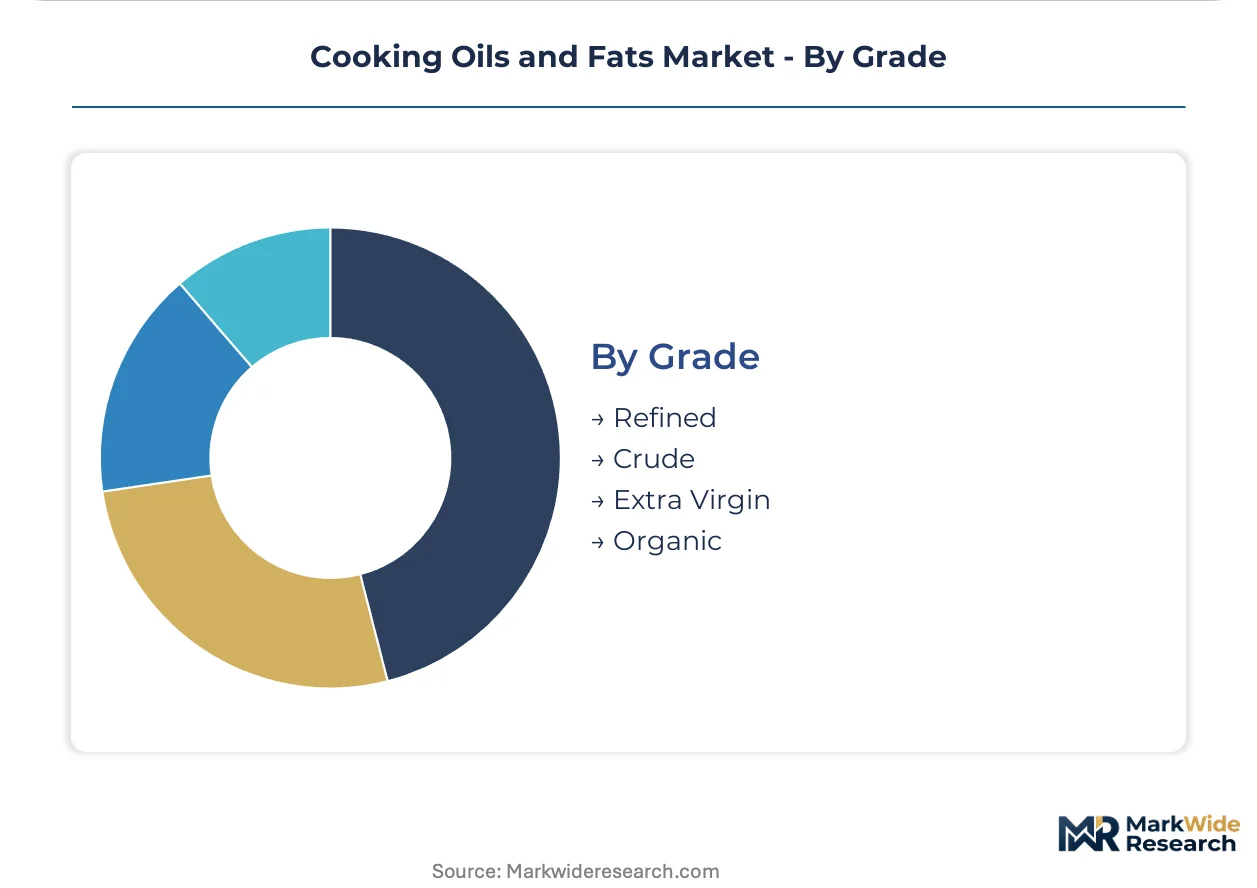
- Refined:Neutral flavor and high smoke point output serves universal frying and baking applications through chemical or physical refining. REACH documentation requirements are extending lead times for European processors seeking novel refining aid approvals.
- Crude:Unrefined oils with retained phospholipids and color pigments feed specialty feed and industrial oleochemical streams.
- Extra Virgin:Cold-pressed olive oil with free acidity below 0.8% and perceptible fruitiness commands origin-certified retail premiums. Greek and Portuguese producers are expanding early-harvest volumes to challenge Italian and Spanish dominance in polyphenol-rich positioning.
- Organic:Certified supply chains with prohibited synthetic input documentation capture allergen-conscious and sustainability-motivated segments.
Certification complexity is highest in Extra Virgin. Volume efficiency peaks in Refined.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cooking oils and fats industry traces its modern scaling to nineteenth-century European rendering and oilseed pressing, with industrial hydrogenation later perfected in Germany and Britain before palm oil cultivation shifted commercial gravity toward Southeast Asian plantation economies.
Indonesia
Indonesian palm oil estates supply roughly sixty percent of global vegetable oil trade volume through integrated plantation-to-port corridors in Sumatra and Kalimantan. The national export levy regime adjusts monthly, exposing international buyers to sudden cost shocks. Refining clusters around Belawan and Dumai ship refined, bleached, deodorized output to Indian and Chinese food manufacturers.
Malaysia
Malaysian processors leverage ISO-certified sustainability schemes to capture EU deforestation-free procurement mandates. The Malaysian Sustainable Palm Oil certification now covers ninety percent of national production. Port Klang and Pasir Gudang house the world's densest concentration of specialty fat hydrogenation and interesterification capacity.
United States
Midwest soybean crushing corridors in Iowa and Illinois anchor North American oil supply through Bunge and Cargill origination networks. FDA trans-fat labeling rules finalized in 2015 forced nationwide reformulation toward high-oleic soybean varieties. Texas and Georgia food service distributors now specify oxidative stability indices in annual frying oil contracts.
Brazil
Brazilian soybean processors in Mato Grosso and Paraná dominate South American export flows through Santos port crushing terminals. ANVISA tightening of 3-MCPD ester limits in infant formula applications is forcing simultaneous confectionery and margarine reformulation. Campinas and São Paulo host Latin America's largest edible oil refining and packaging infrastructure.
Netherlands
Rotterdam's port refiners serve as Europe's primary blending and redistribution hub for West African and Southeast Asian crude arrivals. ECHA REACH documentation requirements extend lead times for novel processing aid approvals to eighteen months. The Europoort cluster specializes in zero-trans-fat shortening production for German and French bakery chains.
Cooking Oils and Fats Market Vendor Landscape
The competitive structure tilts toward plantation-integrated conglomerates with captive crushing and refining assets. Three tiers separate global traders with origination control, regional refiners dependent on spot feedstock, and specialty oil bottlers competing on certification premiums. Dominant moves include backward integration into oilseed crushing and strategic port terminal investments that lock in export logistics.
Among Asia-Pacific plantation-integrated conglomerates, Wilmar International Limited and United Plantations Berhad exemplify the archetype of captive supply chains from seedling to refined product. Archer Daniels Midland Company anchors North American origination through Midwest crushing networks. These three represent distinct geographic anchor points rather than overlapping competitive terrain.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Wilmar International Limited |
| Cargill Incorporated |
| Bunge Limited |
| Associated British Foods PLC |
| Ajinomoto Co., Inc. |
| Mewah International Inc. |
| United Plantations Berhad |
| Olam International Limited |
| Others |
Supply Flow & Price Mechanics
Malaysian crude palm oil futures pricing cascades through integrated plantation-to-refinery corridors into three distinct procurement tiers: spot-indexed bulk contracts for industrial fryers, annual offtake agreements with oxidative stability specifications for quick-service chains, and premium-certified retail SKUs commanding polyphenol-linked positioning in European supermarkets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates extra virgin olive oil with Protected Designation of Origin status from refined commodity blends and unbranded bulk shipments. Price differentiation rests on certification grade and volume scale, with carbon intensity documentation emerging as a new surcharge mechanism under EU Green Deal procurement rules. Cost compression in mid-tier refined oils is intensifying because Indonesian export levy volatility transfers directly into CIF Rotterdam quotations. Industrial snack manufacturers exhibit highest price sensitivity due to tanker-load volume exposure, while premium retail bottlers in Germany and the Netherlands absorb modest increases to protect shelf positioning.
Supply Chain Analysis
EU F-Gas Regulation domestic-content mandates for lower-emission processing equipment are reshaping sourcing toward European-originated closed-loop extraction systems. Geographic supply concentrates in Indonesia, Malaysia, and Brazil, with Indonesian and Malaysian palm estates controlling roughly eighty-five percent of global vegetable oil trade volume. Raw material flows draw from soybean crushing corridors in Iowa and Illinois, sunflower seed origination in the Black Sea basin, and palm fruit bunches from Sumatra and Kalimantan estates. Single-source vulnerability from Indonesian export levy shocks exposes buyers to sudden cost adjustments. Distribution runs through Rotterdam blending terminals for European redistribution and Santos port terminals for South American export flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cooking oils and fats market operates as a regulatory compounder where EU REACH documentation requirements and CSRD scope-three disclosure mandates are elevating compliance costs into sustainable competitive moats for integrated processors.
For Market Incumbents: Acquire controlled chemical refining assets with 3-MCPD ester mitigation capabilities to preempt ANVISA tightening in Brazilian infant formula applications. Consolidate backward integration into oilseed crushing in Mato Grosso and Paraná to offset Black Sea sunflower seed volatility. Lock in multi-year oxidative stability contracts with cloud kitchen operators in São Paulo and Mexico City before digital procurement platforms fully disintermediate distributor layers. For New Entrants and Emerging Players: Begin with enzymatic interesterification service provision to North American bakeries seeking trans-fat elimination without hydrogenation infrastructure investment. Target white-space in cold-pressed avocado oil penetration across German and Dutch premium retail channels where polyphenol positioning displaces conventional extra virgin olive oil. Pursue direct-to-food-service platform partnerships with mid-scale restaurant groups bypassing traditional distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with plantation-integrated conglomerates with captive sustainability certification and scope-three disclosure infrastructure already operational. Long-term viability over the five-to-ten year window favors processors with verified deforestation-free supply chains and Malaysian Sustainable Palm Oil coverage. Watch for Indonesian export levy regime adjustments as the inflection signal indicating margin compression or expansion across Southeast Asian origination assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill and Bunge anchor North American supply through Iowa and Illinois corridor control. |
| Sustainability Certification Investment | Malaysian processors capture EU deforestation-free procurement with MSPO coverage. |
| Enzymatic Interesterification Capacity | Quick-service chains adopt modified high-oleic shortenings to eliminate trans-fat labeling. |
| Cloud Kitchen Supply Agreement | Centralized frying operations in urban delivery hubs standardize high-stability procurement. |
| Direct-to-Food-Service Platform Launch | Digital channels disintermediate traditional distributors for São Paulo restaurant groups. |
Methodological Framework
Multiple input streams — primary interviews with refinery operations directors, food service procurement managers, and sustainability compliance officers; secondary validation through customs trade data, ECHA REACH dossier filings, and SEC processor disclosures; and bottom-up volume triangulation against top-down macroeconomic indicators — were reconciled to construct segment-level demand estimates.
Historical volume trajectories were cross-referenced against panel input from crushing corridor operators and port terminal logistics providers to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product type, grade tier, end-use application, and regional regulatory cluster dimensions. CAGRs were derived from iterative convergence between supply-side capacity expansion schedules and demand-side procurement contract specifications, with specific weighting applied to EU F-Gas Regulation equipment replacement cycles and cloud kitchen proliferation rates.
Caveats apply where Indonesian export levy regime adjustments, Black Sea corridor disruptions, or EFSA 3-MCPD ester limit revisions could materially shift the outlook for crush margins and reformulation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Egg White Peptide Market
Ingredients
Agave Inulin Market
Ingredients
Zea Mays Starch Market
Ingredients
Date Syrup Market
Ingredients
Europe Feed Yeast Market
Ingredients
Rose Extract Market
Ingredients
Coconut Flour Market
Ingredients
South America Lipid Market
Ingredients
Resistant Starch Market
Ingredients
Farnesene Market
Ingredients
Arachidonic Acid Market
Ingredients
Microencapsulated Oil Market
Ingredients
South America Clean Ingredients Market
Ingredients
Torula Yeast Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Grape Skin Extract Market