
 Soft Biscuit Market | 2026-2036
Soft Biscuit Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Biscuit Market Insights
Premium clean-label tier upgrades is reorganizing competitive dynamics across the soft biscuit category. Mondelez International leverages its global R&D infrastructure to reformulate core brands with reduced additive profiles. Britannia Industries anchors its position through deep distribution in South Asian traditional trade channels. Parle Products competes on manufacturing scale, operating one of the world's largest biscuit production networks from Mumbai.
Soft biscuits denote leavened baked goods with moisture content exceeding five percent, typically incorporating wheat flour, sugars, fats, and functional emulsifiers to achieve a tender, compressible crumb structure designed for ambient shelf-stable snacking. Chocolate chip and fruit filled variants command the widest household penetration, though margin pools concentrate in vanilla cream where inclusions and layered fillings justify price premiums. Resealable pouches within packaging type are displacing rigid formats as convenience-driven repeat-purchase behavior reshapes supermarket and online retail shelf sets.
FDA nutrition labeling rules and the EU Green Deal's packaging waste framework together elevate compliance costs for cross-border soft biscuit suppliers while creating preferential market access for reformulators ahead of enforcement curves. BIS fortification standards in India and FSSAI labeling mandates further fragment the regulatory landscape that multinational manufacturers must navigate. Stakeholders should monitor how divergent shelf-life claims and front-of-pack scoring systems reshape consumer trust and retail listing decisions across priority markets.
Market Dynamics
EU Green Deal packaging waste directives are compressing format choices across the soft biscuit value chain, forcing manufacturers to abandon multilayer laminates before enforcement deadlines while reformulating for moisture retention in mono-material structures.
Growth Catalysts
- Clean-label reformulation:Health-conscious households in Germany trade up to additive-reduced soft biscuits with shorter ingredient declarations. Bakers leverage enzyme technology to maintain shelf stability without synthetic preservatives.
- EU Green Deal packaging mandates:Recyclable material requirements accelerate mono-polymer pouch adoption. Suppliers capturing design-for-recycling certifications secure preferential retail listings ahead of 2030 targets.
- Traditional trade channel density:Deep distribution networks in South Asian kirana stores sustain volume throughput for mass-market soft biscuits. Last-mile refrigeration gaps favor ambient-stable formats with extended durability.
Market Restraints
- Wheat flour input volatility:Black Sea supply disruptions transmit price shocks into soft biscuit cost structures. Margin compression limits promotional flexibility for mid-tier brands.
- Multilayer packaging technical lock-in:Existing barrier film investments create stranded asset risk. Retrofitting lines for recyclable mono-materials demands capital outlays that smaller producers cannot absorb.
- Fresh bakery substitution:In-store bakery counters and artisan micro-bakeries capture occasion-based snacking. Soft biscuits face share erosion where refrigerated distribution penetrates.
Strategic Opportunities
- Fortification mandates in India:FSSAI micronutrient requirements create formulation differentiation space. Early movers in iron and folic acid enrichment capture institutional procurement contracts.
- Resealable pouch channel innovation:Convenience-driven repeat-purchase behavior reshapes supermarket and online retail shelf sets. Zip-lock formats command price premiums in grab-and-go occasions.
- Plant-based fat convergence:Blended palm and shea alternatives meet clean-label and sustainability credentials simultaneously. European retailers list these variants in dedicated ethical snacking bays.
Industry Challenges
- Emulsifier reformulation expertise gap:Reduced additive targets demand enzyme and lecithin system mastery. Talent scarcity in bakery science functions slows clean-label pipeline velocity.
- Dual certification timeline friction:Simultaneous BIS fortification and EU organic approvals extend time-to-market. Documentation burdens favor multinationals with dedicated regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Biscuit Market |
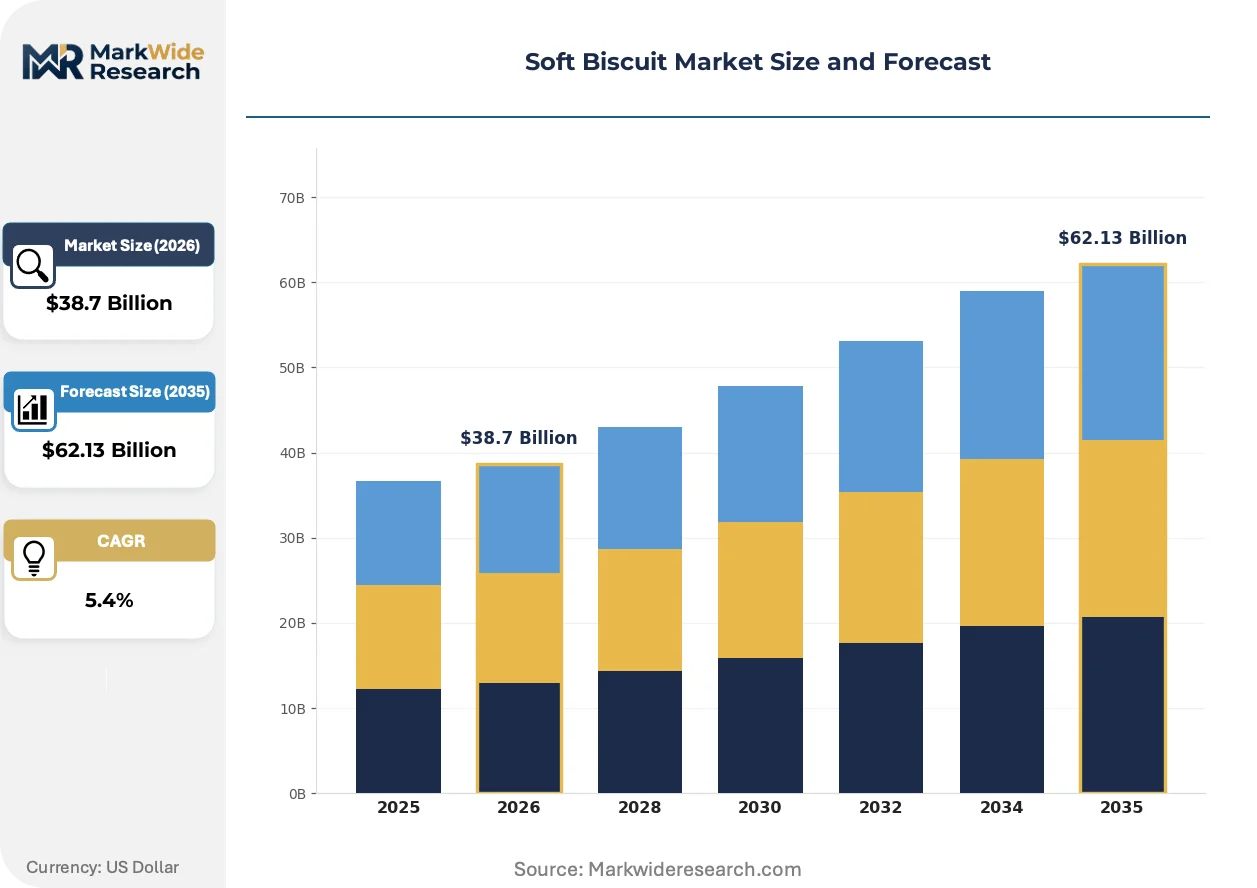
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Chip, Vanilla Cream, Fruit Filled, Oatmeal Raisin Packaging Type: Resealable Pouches, Cardboard Boxes, Plastic Containers, Bulk Packs Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops Customer Type: Households, Cafes, Restaurants, Bakeries |
| Companies Covered | Mondelez International, Inc., Nestle SA, Britannia Industries Limited, ITC Limited, Kellogg Company, Campbell Soup Company, Lotus Bakeries NV, Parle Products Pvt. Ltd., General Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Biscuit Market Trends and Innovations
Active packaging technologies and front-of-pack scoring systems are restructuring how soft biscuits compete for shelf space and consumer trust across developed and emerging markets simultaneously.
Modified atmosphere packaging with oxygen-scavenging films is decomposing the traditional trade-off between shelf-life extension and clean-label positioning. German retailers now specify these technologies for private-label soft biscuit programs. The structural consequence compresses synthetic preservative use while maintaining distribution reach into traditional trade channels lacking cold chain infrastructure.
EU Green Deal packaging waste directives enforce design-for-recycling standards that eliminate multilayer barrier structures. Industrial consequence falls heaviest on cream-filled variants requiring moisture and fat migration resistance. Manufacturers respond with mono-PE pouches featuring plasma-deposited silicon oxide coatings, though these lines require capital conversion.
Front-of-pack Nutri-Score labeling in France and Germany rotates purchase decisions toward reformulated recipes with reduced sugar and saturated fat. Discounters and convenience chains reallocate shelf facings to B and C graded SKUs. This behavior shift concentrates most visibly in vanilla cream segments where margin pools justify reformulation investment.
Soft Biscuit Market Segmentation
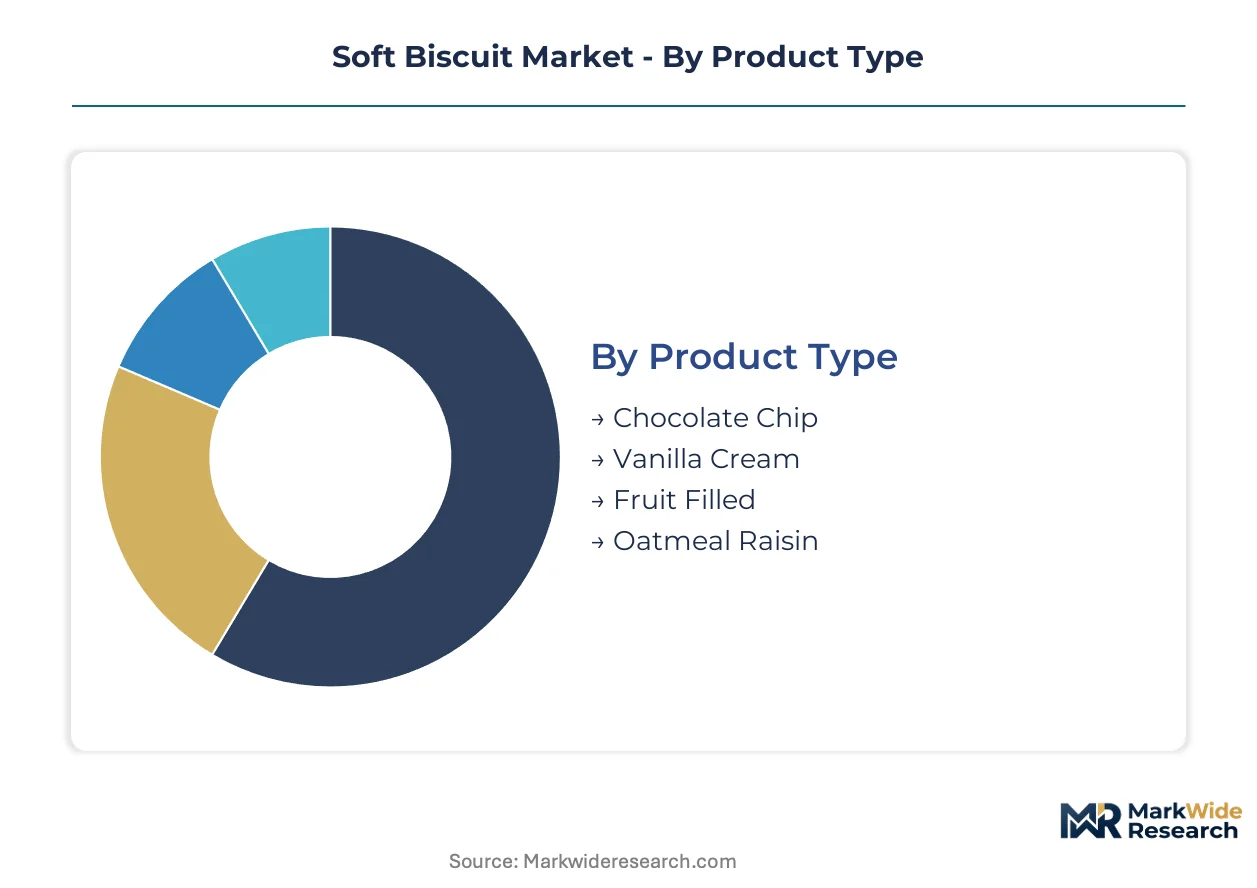
Soft biscuit manufacturers configure production lines and inventory buffers around distinct demand profiles that vary by consumption occasion, packaging convenience, and channel economics. Segmentation clarity determines where reformulation investments and packaging line conversions generate measurable returns versus stranded capacity.
Product Type:
Fresh bakery counters and artisan micro-bakeries exert substitution pressure most acutely on commoditized variants, while layered and inclusion-heavy formats defend shelf space through manufacturing complexity barriers.
- Chocolate Chip:Semisweet morsels distributed through wheat-flour dough create the category's most recognizable visual signature. German households drive clean-label demand for additive-reduced chocolate chip variants with shorter ingredient declarations.
- Vanilla Cream:Dual-texture sandwiches with fat-based fillings between tender biscuits command price premiums through inclusion complexity. Margin pools concentrate here as layered structures justify shelf-space investments against fresh bakery alternatives.
- Fruit Filled:Jam or preserve centers require moisture migration control through specialized emulsifier systems. These variants compete directly with refrigerated pastry cases in European convenience channels.
- Oatmeal Raisin:Rolled oat inclusions and dried fruit deliver texture differentiation in health-positioned snacking. Demand concentrates in North American households seeking perceived nutritional upgrades from conventional cookies.
Chocolate Chip retains volume leadership; Vanilla Cream holds the steepest expansion curve.
Packaging Type:
Cost tier stratification separates convenience-driven premium formats from economy-scale bulk configurations, with mid-tier rigid boxes facing compression from both directions.
- Resealable Pouches:Mono-polymer or multilayer flexible films with zip-lock closures extend ambient shelf stability while enabling portion-controlled consumption. Online retail channels and German supermarkets specify these formats for private-label programs.
- Cardboard Boxes:Paperboard cartons with film windows balance shelf presence against material cost, though EU Green Deal mandates accelerate displacement toward recyclable alternatives.
- Plastic Containers:Rigid PET or PP tubs protect cream-filled variants from compression damage during distribution. These formats face stranded asset risk as retailers enforce design-for-recycling certifications.
- Bulk Packs:Large-format bags or boxes target institutional procurement in cafes and bakeries with cost-per-unit minimization. Last-mile refrigeration gaps in South Asian kirana stores sustain demand for ambient-stable bulk configurations.
Resealable Pouches are gaining share fastest; Bulk Packs anchor volume in traditional trade channels.
Distribution Channel:
Customer type concentration varies sharply by channel, with household pantry loading dominating supermarkets while immediate consumption drives convenience store velocity.
- Supermarkets:Full-category shelf sets with promotional stacking and private-label adjacencies. Nutri-Score labeling in France and Germany rotates facings toward reformulated recipes with reduced sugar grades.
- Online Retail:Direct-to-door fulfillment with subscription bundling and review-driven discovery. Zip-lock pouch formats command price premiums in grab-and-go occasion targeting.
- Convenience Stores:Single-serve and small-format placements for impulse snacking. Shelf-space constraints favor high-velocity SKUs with recognized brand equity.
- Specialty Shops:Curated artisan and import selections with premium positioning. Clean-label and ethical sourcing credentials determine listing decisions in this channel.
Supermarkets retain volume leadership; Online Retail climbs the fastest as fulfillment infrastructure matures.
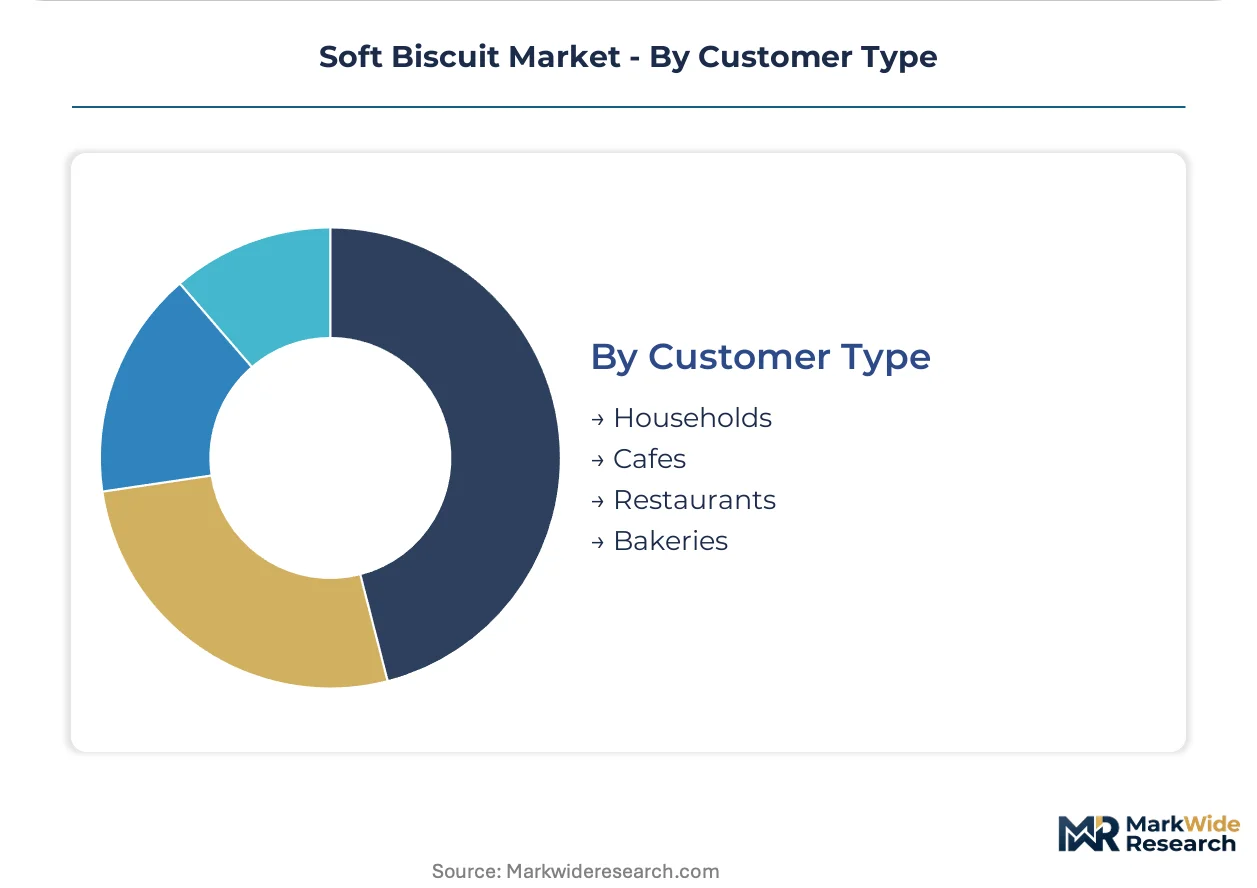
Customer Type:
Application maturity separates established household pantry consumption from emerging foodservice formats where soft biscuits compete against in-house bakery production.
- Households:Pantry stocking for at-home snacking and lunchbox inclusion. Health-conscious trading up in Western Europe concentrates demand in additive-reduced formulations with shorter ingredient lists.
- Cafes:Portion-controlled accompaniments to coffee service with visual presentation requirements. These operators balance cost control against perceived quality differentiation from commodity alternatives.
- Restaurants:Dessert menu components and amenity tray inclusions with brand signaling value. Procurement decisions emphasize consistent supply reliability and extended ambient durability.
- Bakeries:Ingredient inputs for composite desserts or resale of packaged formats. This segment faces the strongest fresh bakery substitution pressure where refrigerated distribution penetrates.
Households retain volume leadership; Cafes show the steepest expansion trajectory as out-of-home snacking recovers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soft biscuit manufacturing clusters concentrate in Western Europe and South Asia, with regulatory divergence creating distinct competitive environments across priority markets.
Germany
Health-conscious households drive demand for additive-reduced formulations with shorter ingredient declarations. EU Green Deal packaging waste directives accelerate mono-polymer pouch adoption ahead of 2030 enforcement deadlines. Munich and Stuttgart industrial corridors host reformulation R&D facilities serving private-label programs.
India
Deep kirana store distribution networks sustain volume throughput for mass-market ambient-stable formats. FSSAI fortification mandates for iron and folic acid create formulation differentiation space for early movers. Mumbai anchors one of the world's largest biscuit production networks, with Maharashtra state concentrating manufacturing scale.
United States
FDA nutrition labeling rules elevate compliance costs while rotating consumer preference toward front-of-pack transparency. Chocolate chip and oatmeal raisin variants dominate household pantry stocking occasions. Chicago and Minneapolis metropolitan areas concentrate North American production capacity for cream-filled formats.
France
Nutri-Score front-of-pack labeling rotates retail shelf facings toward B and C graded SKUs with reduced sugar profiles. Vanilla cream segments justify reformulation investment through concentrated margin pools. Paris and Lyon retail corridors drive premium clean-label tier upgrades in specialty channels.
United Kingdom
Online retail subscription bundling reshapes repeat-purchase behavior for resealable pouch formats. Post-Brexit regulatory divergence from EU packaging standards creates dual certification burdens for cross-border suppliers. London and Birmingham distribution hubs coordinate fulfillment infrastructure for convenience-driven snacking occasions.
Soft Biscuit Market Competitive Landscape
Concentration sits with multinational FMCG conglomerates possessing dedicated regulatory affairs capacity and global R&D infrastructure. Tiered competitive dynamics separate reformulation leaders from manufacturing-scale specialists and regional distribution anchors. Three archetypes dominate: global brand houses with enzyme technology mastery, South Asian mass-market players with kirana channel density, and European private-label suppliers with design-for-recycling certifications. Dominant competitive moves include portfolio diversification into clean-label tiers and backward integration into sustainable fat sourcing.
Within the global brand house tier, Mondelez International and Nestle SA occupy positions defined by cross-border compliance navigation and reformulation pipeline velocity. Britannia Industries and Parle Products exemplify the South Asian manufacturing-scale archetype, with Mumbai-based production networks anchoring traditional trade channel penetration. Lotus Bakeries NV represents the European specialist model, sitting within premium clean-label positioning with shorter ingredient list credentials.
| Leading Market Players |
|---|
| Mondelez International, Inc. |
| Nestle SA |
| Britannia Industries Limited |
| ITC Limited |
| Kellogg Company |
| Campbell Soup Company |
| Lotus Bakeries NV |
| Parle Products Pvt. Ltd. |
| General Mills, Inc. |
| Others |
Pricing and Supply Chain Analysis
Mono-polymer pouch adoption replacing multilayer laminates is redrawing procurement geography toward German and Austrian film suppliers while compressing margin structures for cream-filled variants that demand specialized barrier properties. This substitution dynamic simultaneously elevates compliance costs for legacy format holders and creates pricing premiums for early recyclability certifiers.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across soft biscuit formats, with design-for-recycling certification separating premium mono-PE pouches from standard multilayer configurations. Three-tier pricing structure across premium, standard, and economy levels reflects additive-reduced clean-label credentials, volume scale, and channel positioning. Cost compression in mid-tier rigid boxes is intensifying because retailers are reallocating shelf facings toward flexible formats. Mass-market kirana channels in India exhibit highest price sensitivity, while German specialty shops absorb premiums for shorter ingredient declarations.
Supply Chain Analysis
Germany and India anchor soft biscuit manufacturing scale, with Munich-Stuttgart corridors hosting reformulation R&D and Mumbai concentrating one of the world's largest production networks. Wheat flour draws from Black Sea origins and domestic milling, while palm and shea fat alternatives feed from Southeast Asian and West African sources. Single-source vulnerability concentrates in specialized emulsifier systems where enzyme technology mastery remains scarce. Distribution runs through deep kirana networks in South Asia and centralized retail consolidation in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label enzyme technology represents a high-growth disruption reshaping competitive viability, with EU packaging mandates accelerating format obsolescence for non-compliant suppliers.
For Market Incumbents: Secure design-for-recycling certifications ahead of 2030 enforcement deadlines while retrofitting production lines for mono-material structures. Backward integration into sustainable fat sourcing mitigates commodity volatility exposure. Channel control through direct kirana relationships in India defends volume throughput against fresh bakery substitution. For New Entrants and Emerging Players: Lead with iron and folic acid fortification compliance in India where FSSAI mandates create procurement differentiation for institutional contracts. White-space concentrates in resealable pouch innovation for online retail subscription models. Go-to-market positioning should target grab-and-go convenience occasions with zip-lock format premiums. For Investors and Strategic Acquirers: Capital is best deployed toward European private-label suppliers with enzyme technology mastery and existing recyclability certifications. Long-term viability over a multi-year horizon hinges on reformulation pipeline velocity rather than manufacturing scale alone. The signal to watch is front-of-pack Nutri-Score reallocation velocity in French and German retail facings.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Enzyme technology deployment satisfies EU additive reduction targets while maintaining shelf stability. |
| Mono-Polymer Packaging Conversion | Design-for-recycling certification secures preferential retail listings under EU Green Deal directives. |
| Fortification Compliance in India | FSSAI micronutrient mandates create institutional procurement contracts for early movers. |
| Resealable Pouch Channel Expansion | Zip-lock formats capture price premiums in online retail and convenience-driven repeat purchase. |
| Sustainable Fat Sourcing Integration | Blended palm and shea alternatives meet clean-label and ethical sourcing credentials simultaneously. |
Research Methodology
A standing panel of brand managers, category buyers at retailers, channel sales heads, and supply planners provided ongoing calibration against Nielsen retail audit data, customs records, SEC filings, and BIS fortification compliance databases. Primary interviews with industry stakeholders combined with secondary validation through regulatory filings and trade data. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Consistency checks validated projections against external benchmarks across the analysis window. Segmentation dimensions modeled include product type, packaging format, distribution channel, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and inflection point identification. Forecast inputs incorporated enzyme technology adoption curves and packaging line conversion timelines.
The analysis sits within stated boundaries; outcomes outside continued EU Green Deal enforcement and Black Sea supply stability would require recalibration. Forecasts reflect assumptions regarding clean-label consumer preference persistence and traditional trade channel durability. Recalibration cycles align with material shifts in front-of-pack scoring adoption and fortification mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
Matcha Cookie Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
Bread and Baked Food Market
Bakery Products
North America Pizza Oven Market
Bakery Products
South America Bakery Products Market
Bakery Products
Premixed Bread Flour Market
Bakery Products
Europe Zwieback Market
Bakery Products
Global Rice Cakes Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
Low-Calorie Toast Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Bakery Mixes Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Bakery Cases Market