
 Desiccated Coconut Market | 2026-2036
Desiccated Coconut Market Size, Share, and Industry Trends Forecast 2026-2036
Desiccated Coconut Market Analysis
Buyer concentration among multinational bakery chains is restructuring procurement patterns across the desiccated coconut value chain. Theppadungporn Coconut leverages its integrated processing facilities in Thailand to secure long-term supply agreements with industrial buyers. Celebes Coconut Corporation anchors its position through specialized output for confectionery applications in the Philippines. Renuka Holdings PLC sustains competitive standing via Sri Lankan origin branding and EU organic certification.
Desiccated coconut consists of coconut kernel that has been shredded, dried, and graded to moisture levels typically below 3%, yielding a shelf-stable ingredient for food manufacturing. The drying process employs either hot air convection or solar tunnel methods, with particle size ranging from fine powder to coarse chips determining end-use suitability. Shredded and flaked variants dominate current volume flows, while powdered grades command margin premiums in nutritional supplement formulations. The food industry segment leads absolute consumption, though snack foods applications are expanding fastest as clean-label coating demand rises. Pouch packaging is displacing bulk containers in direct-to-bakery channels, reflecting inventory management priorities among mid-size processors.
The EU Deforestation Regulation and FDA food facility registration requirements are reshaping export compliance costs for origin-country processors. ISO 22000 and HACCP certifications have become baseline qualifiers for access to European and North American food manufacturing supply chains. Stakeholders must monitor evolving deforestation due diligence thresholds and origin traceability technology investments to preserve market access in regulated jurisdictions.
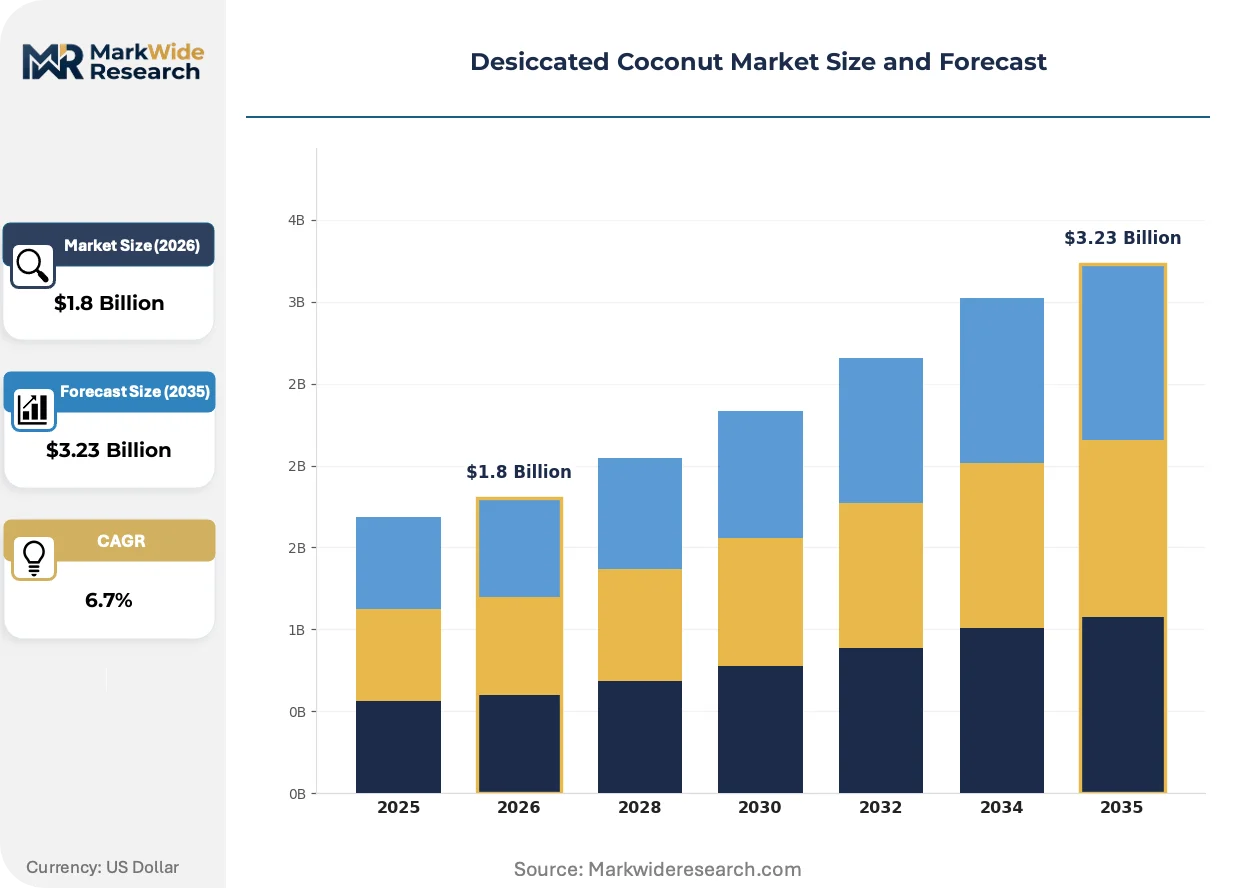
Market Dynamics
The EU Deforestation Regulation is compressing export timelines for Southeast Asian processors while concentrating procurement leverage among bakery chains with dedicated sustainability teams.
Growth Catalysts
- Clean-label coating demand:Snack manufacturers in North America are replacing synthetic glazes with desiccated coconut powders for texture and visual appeal.
- ISO 22000 certification expansion:Philippine processors are achieving baseline qualifications for European food manufacturing supply chains, unlocking contract volume.
- Sulawesi cluster capacity:Indonesian drying facilities are scaling hot air convection output to capture confectionery-grade demand from Japanese buyers.
Market Restraints
- Copra price volatility:Raw coconut kernel costs fluctuate with Philippine and Indonesian harvest cycles, squeezing processor margins.
- EU Deforestation Regulation friction:Traceability documentation requirements are extending shipment clearance times by 15-30 days for non-compliant exporters.
- Oat and almond flake substitution:Bakery formulators are testing alternative texturizers in premium pastry lines to reduce allergen labeling complexity.
Strategic Opportunities
- Nutritional supplement powders:Fine-grade desiccated coconut is capturing MCT oil adjacent positioning in functional food formulations.
- Pouch packaging channel expansion:Direct-to-bakery inventory management systems are displacing bulk container procurement among mid-size processors.
- Solar tunnel drying technology:Thai facilities are converging renewable energy systems with traditional processing to meet EU Green Deal carbon thresholds.
Industry Challenges
- Origin traceability system integration:Smallholder farm mapping requires GPS-based blockchain documentation that strains IT infrastructure at origin-country cooperatives.
- HACCP auditor capacity constraints:Certification backlog delays are extending facility approval timelines by 4-6 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desiccated Coconut Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shredded, Flaked, Powdered, Chips End User: Food Industry, Bakery, Confectionery, Snack Foods Packaging Type: Bags, Boxes, Pouches, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Theppadungporn Coconut, Thai Coconut Public Company Limited, KKP Industry, Metshu Exports, Klassic Coconut, Celebes Coconut Corporation, Universal Coco Indonesia, Heaven Coconut Global, Renuka Holdings PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desiccated Coconut Market Emerging Trajectories
Processing technology and packaging formats are converging to address traceability mandates and inventory velocity demands simultaneously. Three developments are restructuring competitive positioning across the value chain.
Blockchain-based farm-to-facility tracking is unifying documentation streams for EU Deforestation Regulation compliance. Indonesian cooperatives in Sulawesi are piloting satellite-verified smallholder mapping systems. This technology is compressing audit cycles from quarterly to real-time verification, enabling faster customs clearance at Rotterdam and Hamburg ports.
REACH chemical safety documentation requirements are extending to food-contact packaging materials for desiccated coconut imports. European importers are demanding full substance disclosure for pouch laminates and printing inks. Confectionery-grade suppliers with pre-submitted dossiers are capturing shelf space ahead of competitors facing regulatory delays.
Inventory ownership models are rotating toward consignment arrangements between processors and bakery chains. Southeast Asian exporters are absorbing carrying costs to secure multi-year supply agreements with multinational buyers. This pattern is most visible in Thailand, where Theppadungporn facilities are configuring dedicated production lines for single-customer specifications.
Desiccated Coconut Market Segmentation
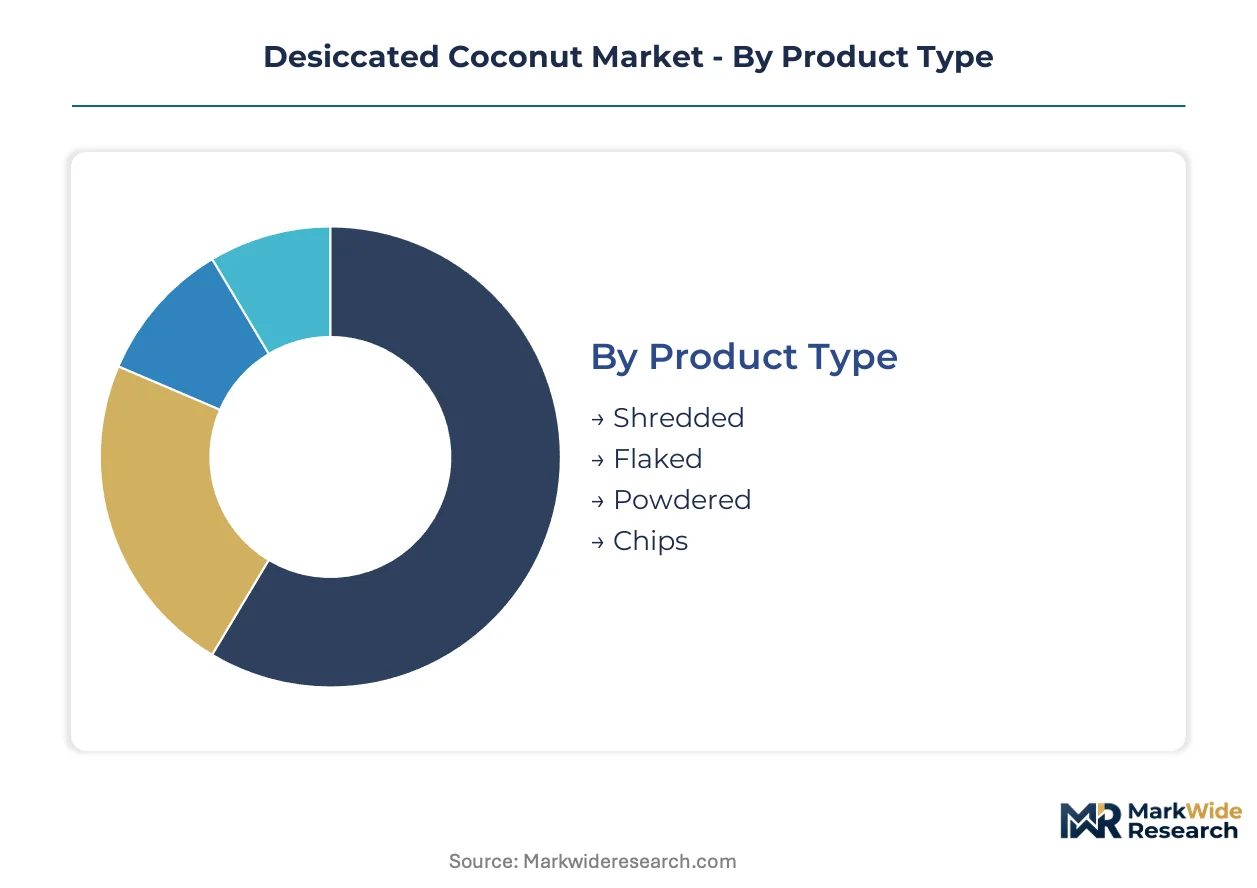
Desiccated coconut procurement patterns diverge sharply across product grades and end-use specifications, with moisture content, particle geometry, and certification status determining contract terms and margin capture. Bakery chains and confectionery manufacturers impose distinct technical requirements that reshape processing priorities at origin-country facilities.
Product Type:
Supply concentration among Southeast Asian drying clusters favors standardized output for high-volume grades while leaving specialty particle sizes underserved by integrated processors.
- Shredded:Medium-cut ribbon geometry with moisture below 3% serves industrial bakeries requiring uniform hydration in dough systems. Philippine and Indonesian facilities dedicate continuous hot-air lines to this specification for European and North American contract buyers. Shredded absorbs the bulk of installed capacity; Powdered is expanding most quickly.
- Flaked:Thin, broad laminar structure maximizes surface area for visual coverage in pastry decoration and premium confectionery coating. Japanese buyers concentrate procurement of this grade for seasonal wagashi applications, with Sulawesi processors configuring dedicated cutting and drying sequences. Flaked commands margin premiums in direct-to-bakery channels where appearance specifications are stringent.
- Powdered:Fine-milled particulate below 0.5mm enables suspension in beverage and nutritional supplement matrices.
- Chips:Coarse irregular fragments retain chew texture for granola and trail mix inclusions.
Shredded and flaked variants dominate current volume flows; powdered grades capture steepest expansion trajectory in functional food positioning.
End User:
Customer scale and specification rigor create tiered demand patterns, with multinational manufacturers imposing traceability requirements that exclude smallholder-dependent suppliers.
- Food Industry:Broad manufacturing segment spanning sauce thickeners, dairy alternatives, and ready-meal components. Clean-label momentum in North American and European processed foods is redirecting formulation toward coconut-derived texturizers with single-ingredient declarations. Food Industry concentrates procurement volume among the largest integrated processors with ISO 22000 and HACCP certification depth.
- Bakery:Artisan and industrial producers leverage desiccated coconut for moisture retention, fat displacement, and visual differentiation in laminated pastries and enriched breads. Southeast Asian bakery chains are scaling procurement of premium pastry lines with origin-specific branding requirements. Bakery demand is fragmenting across specification tiers from commodity shredded to organic-certified flaked grades.
- Confectionery:Chocolate enrobing and bar inclusion applications demand precise fat content and particle size distribution for coating adhesion.
- Snack Foods:Clean-label coating demand is accelerating replacement of synthetic glazes with coconut powder dusting systems.
Food Industry and Bakery absorb dominant procurement volumes; Snack Foods is gaining share fastest on clean-label coating conversion.
Packaging Type:
Inventory velocity requirements and contamination risk thresholds determine format selection, with direct-to-manufacturer channels displacing traditional wholesale packaging specifications.
- Bags:Multi-wall paper or woven polypropylene construction serves traditional wholesale distribution with 10-25kg net weights. Philippine exporters maintain bagging lines for legacy confectionery buyers with established repackaging infrastructure.
- Boxes:Corrugated containment with inner liner protection supports palletized ocean freight for industrial-scale buyers.
- Pouches:Laminated film structures with reseal features enable direct-to-bakery inventory management and reduced handling contamination. Thai processors are converting bulk-oriented facilities to pouch-dedicated lines for European mid-size bakery chains.
- Bulk Containers:Flexible intermediate bulk containers and lined sea containers minimize per-unit handling for integrated food manufacturers with captive repackaging.
Bulk containers retain volume leadership in plantation-processor integrated supply chains; pouches are climbing fastest on direct-channel conversion.
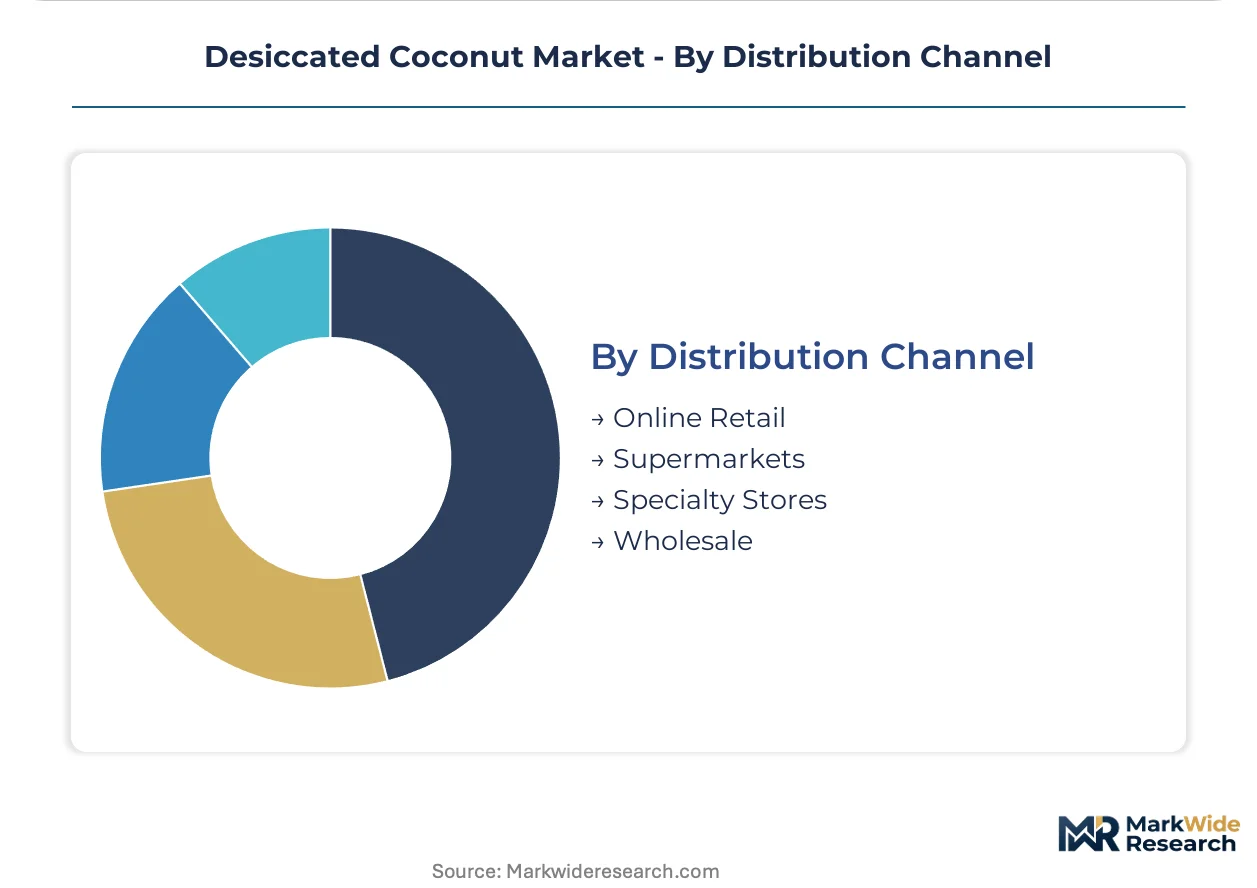
Distribution Channel:
Channel selection reflects buyer scale and certification burden tolerance, with traceability-intensive markets concentrating in vertically integrated supply arrangements.
- Online Retail:E-commerce platforms serve specialty ingredient buyers and small-scale food manufacturers with certified organic and fair-trade SKUs. Sri Lankan origin branding performs strongly in this channel via Renuka Holdings PLC affiliate storefronts.
- Supermarkets:Mass retail placement requires retail-ready packaging and sustained promotional investment, limiting participation to diversified food conglomerates with consumer marketing capabilities.
- Specialty Stores:Gourmet and ethnic food retailers stock premium grades with origin storytelling for home bakers and small commercial users.
- Wholesale:Traditional cash-and-carry and foodservice distributors remain significant in emerging market access where direct processor relationships are underdeveloped.
Wholesale channels retain volume concentration in price-sensitive procurement; online retail is expanding most quickly on specialty certification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bakery chain procurement concentrates in Southeast Asian processing clusters, while European deforestation compliance requirements reshape export logistics from origin-country drying facilities.
Indonesia
Japanese confectionery buyers drive demand for flaked grades with precise fat content specifications. The EU Deforestation Regulation mandates GPS-based farm mapping for Sulawesi-origin shipments. Makassar-area drying facilities scale hot-air convection capacity to capture contract volume from integrated food manufacturers.
Philippines
Confectionery coating applications require thin laminar structures for chocolate enrobing adhesion. FDA food facility registration requirements extend approval timelines for new market entrants. Davao processing clusters configure dedicated cutting sequences for seasonal wagashi export programs.
Thailand
Mid-size European bakery chains convert procurement to pouch-packaged inventory systems. EU Green Deal carbon thresholds accelerate solar tunnel drying adoption at integrated facilities. Samut Sakhon processors absorb carrying costs through consignment arrangements with multinational buyers.
Sri Lanka
Organic certification demand from North American specialty retailers sustains origin-premium positioning. FSSAI-equivalent export documentation requirements govern access to Indian subcontinent markets. Colombo-area cooperatives leverage EU organic branding for e-commerce channel penetration.
United States
Clean-label snack coating applications displace synthetic glazes with fine-milled coconut powders. FDA facility registration and HACCP baseline qualifications govern import acceptance at food manufacturing plants. California-based nutritional supplement formulators drive powdered grade procurement for MCT-adjacent functional positioning.
Desiccated Coconut Market Vendor Landscape
Thai producers anchor one tier; Philippine and Indonesian specialists hold flaked and confectionery-grade positions. The vendor base splits between integrated drying facilities with captive copra supply and merchant processors dependent on spot kernel markets. Three archetypes dominate: plantation-integrated multinationals, origin-country cooperatives with certification depth, and regional traders with flexible grade blending. Capacity expansion and backward integration into copra sourcing represent the dominant competitive vectors.
Among Thailand-based integrated processors, Theppadungporn Coconut and Thai Coconut Public Company Limited exemplify the plantation-linked archetype with dedicated production line configurations. Celebes Coconut Corporation represents the Philippine specialist position in confectionery-grade output. Renuka Holdings PLC occupies the Sri Lankan origin-branding tier with EU organic certification positioning.
| Leading Market Players |
|---|
| Theppadungporn Coconut |
| Thai Coconut Public Company Limited |
| KKP Industry |
| Metshu Exports |
| Klassic Coconut |
| Celebes Coconut Corporation |
| Universal Coco Indonesia |
| Heaven Coconut Global |
| Renuka Holdings PLC |
| Others |
Supply Flow & Price Mechanics
EU Deforestation Regulation traceability mandates are forcing Southeast Asian processors to absorb compliance costs that reshape contract pricing structures. Bakery chains with dedicated sustainability teams capture procurement leverage while smaller buyers face premium surcharges for documented origin grades.
Pricing Analysis
Volume flows concentrate in standardized shredded grades where commodity spot dynamics compress margins, while powdered and flaked variants sustain premium capture through specification rigor. Three-tier pricing structure across organic-certified, conventional food-grade, and economy industrial tiers reflects certification depth and particle geometry differentiation. Cost compression in economy grades is intensifying because Philippine and Indonesian copra spot markets feed raw material volatility. Smallholder-dependent cooperatives exhibit highest price sensitivity; multinational confectionery buyers with multi-year offtake agreements demonstrate lowest sensitivity due to volume guarantees.
Supply Chain Analysis
Domestic-content rules in EU member states and evolving FDA facility registration requirements in the United States are reshaping sourcing documentation burdens for origin-country exporters. Supply concentrates in Indonesia's Sulawesi cluster, Thailand's Samut Sakhon corridor, and the Philippines' Davao processing belt. Raw material flows draw from copra drying facilities, smallholder farm cooperatives, and plantation-integrated kernel supply. Single-source vulnerability runs through Sulawesi's concentration of flaked-grade capacity for Japanese confectionery buyers. Distribution runs through direct processor-to-manufacturer arrangements with consignment inventory models displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated processors with captive copra supply and certification depth. The EU Deforestation Regulation is forcing weaker merchant-dependent operators toward acquisition or exit.
For Market Incumbents: Cement backward integration into copra sourcing to secure margin control against Philippine and Indonesian harvest volatility. Expand Sulawesi and Samut Sakhon capacity with solar tunnel drying configurations that satisfy EU Green Deal carbon thresholds. ISO 22000 and HACCP certification depth represents the critical lever for European and North American contract retention. For New Entrants and Emerging Players: Enter via nutritional supplement powder formulations where MCT-adjacent functional positioning commands margin premiums and incumbent capacity is thinnest. Target North American specialty retail e-commerce channels with organic-certified Sri Lankan origin branding. Pursue blockchain-based farm-to-facility traceability as a differentiated go-to-market angle for EU Deforestation Regulation compliance. For Investors and Strategic Acquirers: The window for entry favors plantation-integrated processors with existing certification infrastructure and direct bakery chain relationships. Acquisition targets should demonstrate captive kernel supply or consignment arrangement traction with multinational buyers. Watch for HACCP auditor capacity constraints easing as a signal that new facility approvals may accelerate competitive entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copra Sourcing | Captive kernel supply insulates margin compression from Philippine and Indonesian harvest volatility. |
| Solar Tunnel Drying Technology Deployment | Thai facilities leverage renewable energy convergence to meet EU Green Deal carbon thresholds. |
| Blockchain Farm-to-Facility Traceability Implementation | Indonesian cooperatives compress audit cycles from quarterly to real-time for Rotterdam customs clearance. |
| Consignment Inventory Arrangement Expansion | Southeast Asian exporters absorb carrying costs to secure multi-year supply agreements with bakery chains. |
| Pouch Packaging Line Conversion | Direct-to-bakery inventory management systems displace bulk containers among mid-size European processors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this desiccated coconut market assessment. Primary interviews with coconut processing facility managers, procurement leads at multinational bakery chains, confectionery manufacturing R&D directors, and certification body auditors combined with secondary validation across EU Deforestation Regulation implementation documents, FDA food facility registration databases, and ISO 22000 certification registries. Bottom-up volume modeling from origin-country drying capacity and top-down demand triangulation from end-use sector consumption patterns ensured cross-verified outputs.
Granularity-level modeling operated at product type, end-use specification, packaging format, and regional processing cluster dimensions across the projection horizon. CAGRs derived from segmented volume trajectory analysis incorporating copra price cycle assumptions, certification adoption curves, and direct-channel conversion rates. Forecast inputs included Sulawesi capacity expansion timelines, HACCP auditor queue lengths, and EU traceability technology penetration at Indonesian cooperatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended EU Deforestation Regulation enforcement delays or accelerated oat and almond flake substitution in bakery formulations. Assumptions reflect documented facility capacity, certification backlog status, and buyer procurement pattern shifts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Olive Leaf Extract Market
Ingredients
Freeze-Dried Vegetable Powder Market
Ingredients
Potato Granules Market
Ingredients
Bran Market
Ingredients
Rice Bran Oil Market
Ingredients
Corn Gluten Meal Market
Ingredients
North America Protein Ingredients Market
Ingredients
Carrot Fiber Market
Ingredients
Phytogenic Market
Ingredients
Alginate Market
Ingredients
Thinned Starch Market
Ingredients
PHO Oils Market
Ingredients
Yeast Derivatives Market
Ingredients
Homecare Ingredients Market
Ingredients
Barley Flake Market
Ingredients
Mustard Oil Market