
 Africa Fats and Oil Market | 2026-2036
Africa Fats and Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Fats and Oil Market Outlook
Mechanical pressing and solvent extraction is reconfiguring how African processors recover oil from oilseeds and palm fruits, replacing traditional hand-pressing methods with continuous systems that raise yield rates. Wilmar International Ltd leverages integrated crushing and refining assets across multiple African countries to secure supply chain control. Cargill Incorporated anchors its position through farmer outreach programs that secure soybean and sunflower seed offtake. Olam International competes by dominating cashew and shea nut processing corridors linking West African origins to export markets.
Africa fats and oils encompass triglyceride-based lipids extracted from oilseed crops, tree fruits, and animal tissues, with free fatty acid content, iodine value, and smoke point serving as critical quality parameters governing suitability for food frying, cosmetic formulation, or biodiesel feedstock. The product type dimension shows vegetable oils commanding the largest volume share while palm oil generates the densest margin pools due to refining complexity and regional supply concentration. Within end users, the food industry remains the mature baseline consumption layer, whereas biofuels represents the fastest-growing demand segment as African governments mandate renewable fuel blending programs.
National food safety regulators across African Union member states enforce Codex Alimentarius-aligned standards for edible oil purity, while the African Organisation for Standardisation harmonizes regional quality benchmarks to facilitate intra-African trade. BIS-equivalent national standards bodies in South Africa and Nigeria conduct routine aflatoxin and adulteration surveillance that shapes processor compliance investments and import gatekeeping. Stakeholders must monitor how AfCFTA rules-of-origin negotiations and emerging EU deforestation regulation due diligence requirements will reshape sourcing geography and certification burdens for palm and shea supply chains.
Market Dynamics
AfCFTA tariff phase-outs and EU deforestation due diligence rules are restructuring sourcing corridors, forcing processors to revalidate supplier networks and relocate crushing assets closer to feedstock origins.
Growth Catalysts
- Biodiesel blending mandates:Nigerian and South African renewable fuel programs are absorbing waste oils and palm fatty acid distillate, creating dedicated offtake channels for refiners.
- Shea industrialization:West African governments are funding cooperative consolidation and quality grading infrastructure to capture premium cosmetic-grade exports.
- Mechanical pressing upgrades:Continuous screw press systems are replacing batch hand-pressing in Ghana and Côte d'Ivoire, lifting oil recovery rates from oilseeds.
Market Restraints
- Input cost volatility:Palm fruit bunch prices swing with Malaysian ringgit-denominated benchmark futures, compressing Nigerian refiner margins unpredictably.
- Supply concentration risk:Over half of African soybean crush capacity sits in South Africa, exposing East African buyers to rail-logistics bottlenecks and currency mismatch.
- Technical limitation:Aflatoxin contamination in groundnut oil persists due to inadequate drying infrastructure in Sahelian storage corridors.
Strategic Opportunities
- Underpenetrated geography:Ethiopia's edible oil deficit exceeds domestic production by a factor of four, opening import-substitution crushing investments for sunflower and rapeseed.
- Regulatory tailwind:AfCFTA rules-of-origin negotiations are simplifying cross-border oilseed movements between Senegal and Mali, enabling integrated West African supply basins.
- Technology convergence:Near-infrared spectroscopy and blockchain traceability are merging to verify shea nut provenance for EU cosmetic buyers demanding deforestation-free documentation.
Industry Challenges
- Skill gap in process automation:Kenyan and Tanzanian refiners struggle to recruit technicians capable of maintaining continuous deodorizer and fractionation systems.
- Capex intensity:Solvent extraction plants require USD-denominated equipment imports, exposing Nigerian processors to naira depreciation and extended payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Fats and Oil Market |
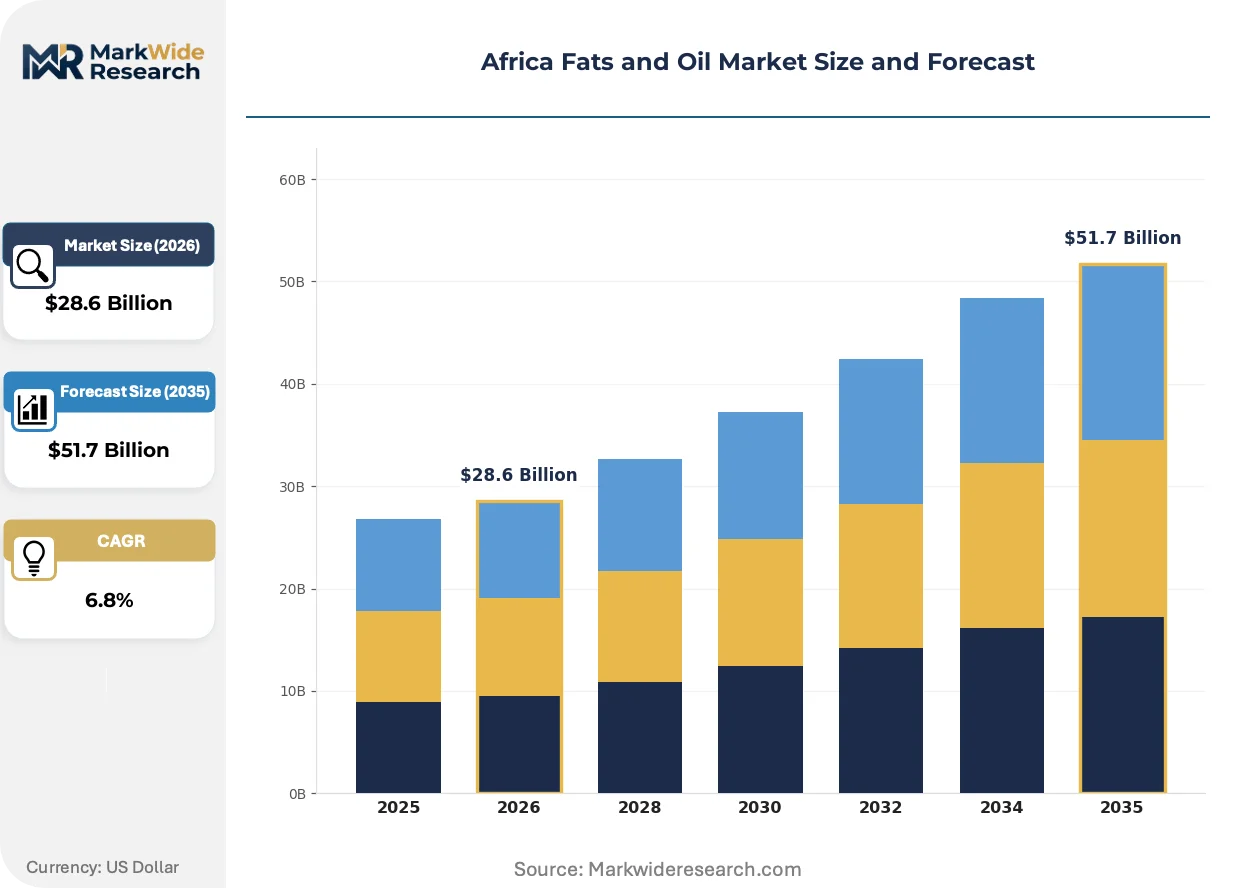
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oils, Animal Fats, Palm Oil, Olive Oil End User: Food Industry, Cosmetics, Pharmaceuticals, Biofuels Distribution Channel: Direct Sales, Retail, E-commerce, Wholesalers Application: Cooking, Baking, Margarine Production, Industrial Use |
| Companies Covered | Wilmar International Ltd, Cargill Incorporated, Archer Daniels Midland Company, Bunge Limited, Olam International, Fuji Vegetable Oil Inc., Africa Palm Products (pty) Ltd, CEOCO (Pty) Ltd, Supa Oils, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Fats and Oil Market Strategic Shifts
Digital infrastructure is penetrating African oil processing at the traceability and quality-control layers, replacing paper-based supplier records with sensor-verified chain-of-custody systems that satisfy export-market compliance.
Near-infrared spectroscopy is virtualizing traditional laboratory testing for free fatty acid content and moisture levels in palm oil deliveries. Large Nigerian refiners and Côte d'Ivoire cooperatives are adopting handheld NIR devices at receiving bays, compressing quality verification from days to minutes and enabling real-time price adjustments based on actual oil content rather than visual grading.
EU Deforestation Regulation due diligence obligations are forcing shea and palm supply chain restructuring across West Africa. Processors must now geolocate every supplying farm and document land-use change history, redirecting investment toward traceability software and third-party audit services rather than capacity expansion alone.
Buyers in Senegal and Ghana are consolidating procurement through processor-direct contracts, bypassing traditional aggregator networks that added opacity and adulteration risk. Food manufacturers now demand tanker-truck deliveries with sealed sampling ports, shifting volume toward integrated refiners capable of certifying refining date, storage temperature, and fatty acid profile per batch.
Africa Fats and Oil Market Segmentation
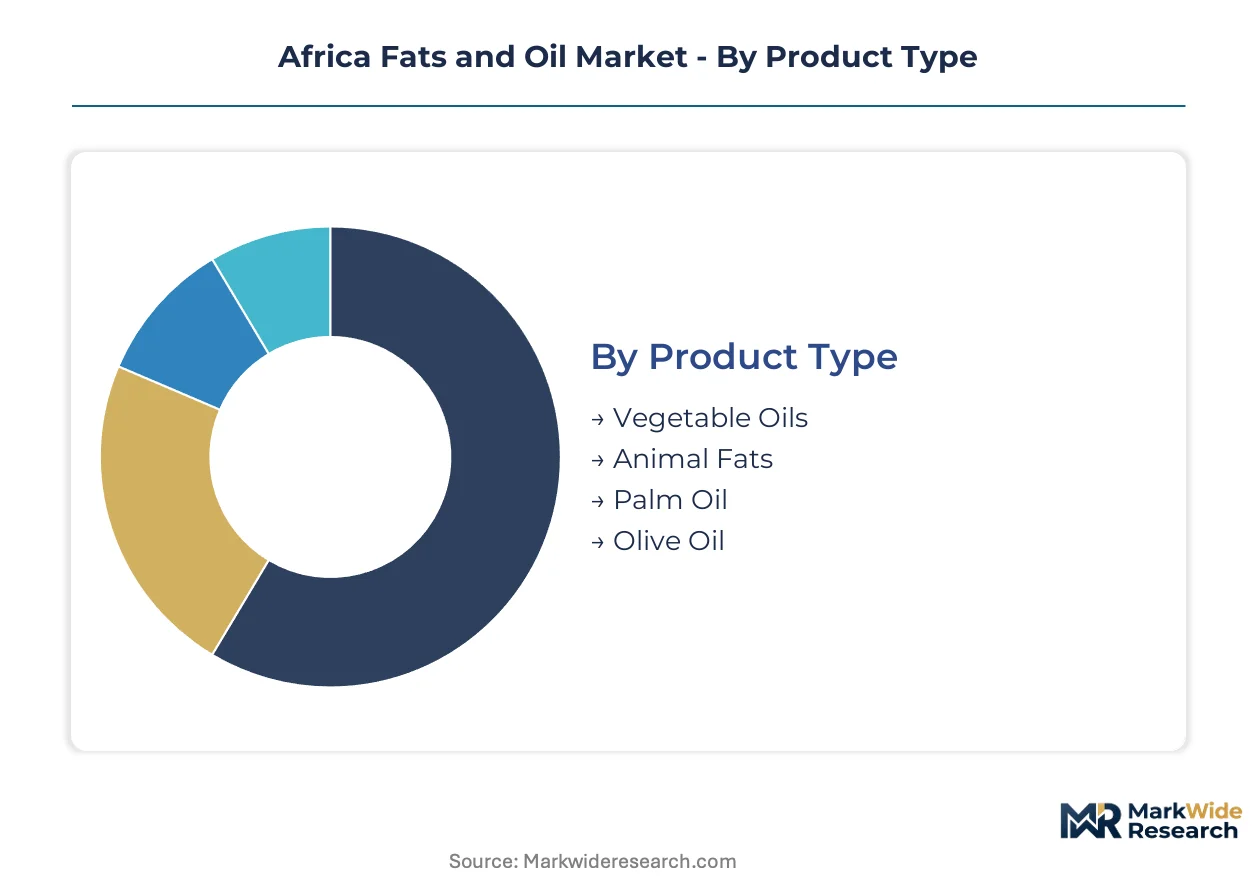
African fats and oils procurement patterns diverge sharply by product chemistry and end-use specification, with food-grade refining commanding fundamentally different logistics than cosmetic or fuel feedstock channels. Segmentation discipline reveals where margin pools concentrate and which technology investments align with demand trajectories.
Product Type:
Maturity varies from plantation-scale commodity flows to artisanal extraction corridors still scaling toward industrial volumes.
- Vegetable Oils:Triglyceride lipids extracted from soybean, sunflower, and rapeseed through mechanical pressing or solvent extraction, with free fatty acid thresholds below 0.1% for premium food-grade contracts. Nigerian packaged food manufacturers and Ghanaian baking conglomerates anchor procurement volumes, though South African crush capacity deficits force East African buyers into import dependency.
- Palm Oil:Semi-solid carotenoid-rich oil fractionated from Elaeis guineensis mesocarp, differentiated by crude versus refined-bleached-deodorized grades. Refining complexity concentrates margin capture among integrated processors in Côte d'Ivoire and Nigeria, while Malaysian benchmark pricing in ringgit exposes local refiners to currency-driven margin compression.
- Animal Fats:Tallow and lard rendered from cattle and swine processing byproducts, valued for soap manufacturing and select baking applications where saturated fat profiles matter. South African abattoir networks supply the densest regional flows.
- Olive Oil:Monounsaturated oil from Olea europaea cultivation, predominantly imported for North African and South African premium retail segments with minimal domestic crush infrastructure.
Vegetable oils handle the majority of throughput; palm oil is the fastest mover on share.
End User:
Application sophistication separates commodity volume plays from specification-driven premium extraction.
- Food Industry:Deep-frying, baking, and margarine manufacturing absorb the largest volume flows, with Nigerian biscuit and noodle producers driving refined oil procurement at scale. FSSAI-equivalent national standards bodies enforce aflatoxin and adulteration surveillance that shapes processor compliance investments.
- Biofuels:Waste oils and palm fatty acid distillate feed renewable fuel blending mandates in Nigeria and South Africa, creating dedicated offtake channels outside food-grade quality tiers.
- Cosmetics:Shea butter and specialty triglycerides for emollient formulations, with EU Deforestation Regulation due diligence forcing geolocation and chain-of-custody investments across West African cooperative networks.
- Pharmaceuticals:Highly refined excipient-grade oils meeting pharmacopeial standards, a thin volume segment concentrated among South African and Moroccan formulators with import substitution ambitions.
Food industry offtake dominates absolute volume; biofuels is expanding most quickly on policy mandate absorption.
Distribution Channel:
Channel selection maps directly to buyer scale and quality verification requirements.
- Direct Sales:Processor-to-manufacturer contracts with sealed tanker-truck sampling ports, displacing traditional aggregator opacity in Senegal and Ghana food manufacturing corridors.
- Wholesalers:Traditional bulk oil traders handling import flows into Ethiopian and Kenyan markets where domestic crush capacity lags consumption by substantial margins.
- Retail:Packaged edible oil through formal supermarket and informal market channels, with branded 1-5 liter containers penetrating West African urban households.
- E-commerce:Emerging direct-to-consumer channels for premium and specialty oils, still thin volume but capturing affluent urban segments in Lagos, Nairobi, and Johannesburg.
Direct sales captures the steepest expansion trajectory as manufacturers consolidate procurement; wholesalers retain volume leadership in import-dependent East African markets.
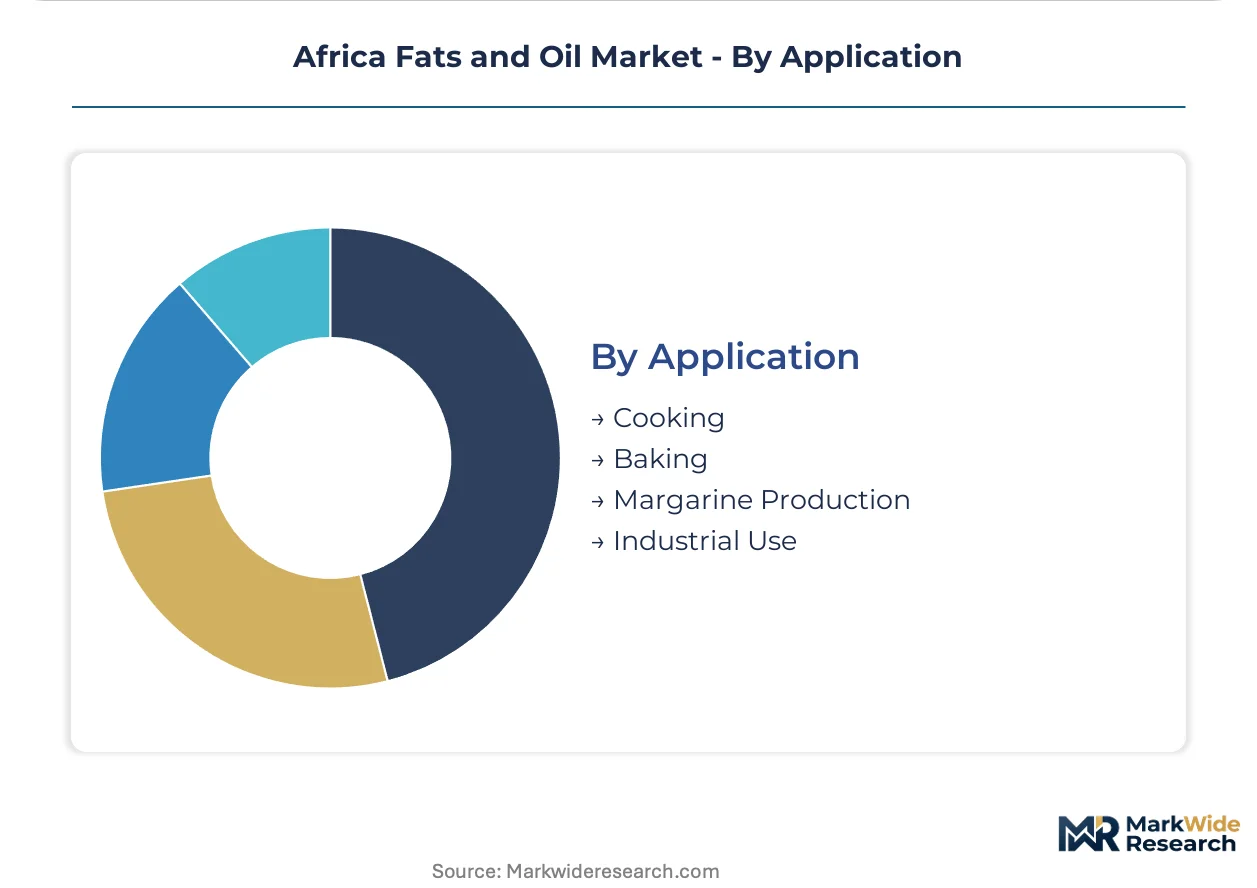
Application:
Temperature performance and oxidative stability requirements segment processing technology investments.
- Cooking:High smoke point oils for deep-frying and sautéing, with palm olein and high-oleic sunflower commanding premium positioning in West African food service.
- Baking:Plastic fat profiles enabling creaming and lamination, where palm-based shortenings displace traditional butter in cost-sensitive Nigerian and Egyptian industrial bakeries.
- Margarine Production:Partially hydrogenated and interesterified fat blends requiring precise solid fat content control, a specification-intensive segment consolidating toward integrated refiners with fractionation capability.
- Industrial Use:Lubricants, surfactants, and chemical feedstocks outside edible applications, absorbing lower-grade fractions and byproduct streams from food-oriented refining.
Cooking applications anchor volume absorption; margarine production is climbing the fastest on processed food manufacturing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
West African food manufacturers and East African importers constitute the dominant buyer archetypes, with procurement patterns diverging sharply between palm oil refining clusters and oilseed crushing deficits.
Nigeria
Nigerian biscuit and noodle producers drive refined vegetable oil procurement at industrial scale, absorbing palm olein and soybean oil derivatives for packaged goods manufacturing. The country's national food safety regulator enforces aflatoxin and adulteration surveillance through BIS-equivalent standards that shape processor compliance investments. Lagos and Kano anchor the densest refining corridors, where integrated processors deploy continuous deodorizer systems to serve bakery and confectionery manufacturers.
South Africa
South African renewable fuel programs absorb waste oils and palm fatty acid distillate, creating dedicated biofuel offtake channels outside food-grade tiers. The country's national standards body conducts routine surveillance that shapes import gatekeeping and processor investment decisions. Gauteng and KwaZulu-Natal concentrate crushing capacity, though rail-logistics bottlenecks expose East African buyers to supply disruption.
Ghana
Ghanaian baking conglomerates and food service operators anchor refined oil consumption, with continuous screw press systems replacing batch hand-pressing to lift oil recovery rates. Government-funded cooperative consolidation programs target quality grading infrastructure for premium cosmetic-grade shea exports. Accra and Tema host the principal refining clusters, where processor-direct contracts displace traditional aggregator networks.
Côte d'Ivoire
Côte d'Ivoire's integrated palm oil processors capture margin pools through refining complexity and regional supply concentration, fractionating crude into specialized olein and stearin grades. The African Organisation for Standardisation harmonizes regional quality benchmarks that facilitate intra-African trade from Abidjan processing hubs. San-Pédro and Abidjan anchor export-oriented refining corridors linking West African origins to international markets.
Ethiopia
Ethiopia's edible oil deficit exceeds domestic production by a factor of four, forcing reliance on wholesale import channels for sunflower and rapeseed oils. The country's national food safety regulator aligns with Codex Alimentarius standards that govern edible oil purity for urban household consumption. Addis Ababa and surrounding highland corridors concentrate demand, attracting import-substitution crushing investment proposals from regional processors.
Africa Fats and Oil Market Competitive Environment
Channel-controlling players compete with product-specialist players across a fragmented vendor base where scale advantages concentrate among integrated refiners with fractionation capability. The market structure favors processors owning upstream crushing assets and downstream distribution networks over pure traders. Three archetypes dominate: plantation-integrated multinationals, regional crusher-refiners with cooperative feedstock ties, and specialty extractors serving cosmetic and pharmaceutical grade tiers. Competitive moves center on backward integration into oilseed origination and technology licensing for continuous pressing systems.
Within the plantation-integrated tier, Wilmar International Ltd and Olam International exemplify archetypes combining upstream asset control with multi-country processing footprints. Cargill Incorporated anchors a position through farmer outreach structures that secure feedstock offtake across origination zones. These entities represent the scale-driven end of competitive positioning, where supply chain control and refining complexity determine margin capture.
| Leading Market Players |
|---|
| Wilmar International Ltd |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Bunge Limited |
| Olam International |
| Fuji Vegetable Oil Inc. |
| Africa Palm Products (pty) Ltd |
| CEOCO (Pty) Ltd |
| Supa Oils |
| Others |
Value Chain & Pricing Dynamics
Malaysian ringgit-denominated palm oil benchmark futures determine both margin compression severity for Nigerian refiners and the geographic relocation of crushing assets toward West African feedstock origins. Currency volatility in input pricing creates tiered spreads between integrated processors capturing refining premiums and import-dependent East African buyers absorbing exchange-rate passthrough.
Pricing Analysis
Cost-plus contracts indexed to Bursa Malaysia Derivatives palm oil futures dominate procurement between West African refiners and food manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates RBD olein with sub-0.1% free fatty acid certification from unrefined crude and waste oil feedstocks. Pricing pressure stems from naira depreciation against dollar-denominated solvent extraction equipment, compressing payback periods for Nigerian processors. Small-scale Ghanaian cooperatives exhibit highest price sensitivity, while integrated Côte d'Ivoire refiners with fractionation capability command premium positioning.
Supply Chain Analysis
Upstream palm fruit bunch availability concentrates in Côte d'Ivoire, Nigeria, and Ghana, with Malaysian and Indonesian crude imports filling South African and East African deficits. Soybean crush draws from South African seed origination, Malawian smallholder networks, and Zambian commercial farms. Single-source vulnerability runs through Johannesburg-Gauteng rail corridors serving Kenyan and Tanzanian buyers. Distribution runs through processor-direct tanker contracts displacing traditional aggregator opacity in Senegal and Ghana.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Deforestation Regulation due diligence obligations are accelerating supply chain restructuring, creating asymmetric advantage for processors with geolocation and blockchain traceability infrastructure already deployed.
For Market Incumbents: Insulate margin pools by securing shea nut and palm fruit offtake through cooperative consolidation programs in Burkina Faso and Côte d'Ivoire. Deploy backward integration into Ethiopian sunflower and rapeseed crushing to capture import-substitution premiums before regional competitors establish footprint. Certification investment for EU cosmetic-grade shea exports represents the critical defensive lever against specialty extractors.
For New Entrants and Emerging Players: Ethiopia's four-to-one edible oil consumption-to-production gap represents the most penetrable entry point for sunflower and rapeseed crushing investments. Kenyan biodiesel offtake channels under Nigerian and South African renewable fuel mandates offer secondary white-space targeting. Go-to-market execution should anchor on processor-direct contracts with sealed tanker-truck sampling ports that satisfy food manufacturer quality verification requirements.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated crusher-refiners with cooperative feedstock ties and fractionation capability. Long-term viability over the next decade hinges on traceability infrastructure deployment ahead of EU enforcement deadlines. Acquisition target archetype: West African processors with geolocated supplier networks and existing cosmetic-grade shea certification. The signal to watch is AfCFTA rules-of-origin finalization accelerating cross-border oilseed movements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Origination | Secures feedstock supply for Nigerian refiners facing Malaysian futures volatility. |
| Blockchain Traceability Deployment | Enables EU Deforestation Regulation compliance for Côte d'Ivoire shea exporters. |
| Continuous Screw Press System Upgrades | Lifts Ghanaian and Ivorian oil recovery rates above traditional hand-pressing yields. |
| Cooperative Consolidation Programs | Captures premium cosmetic-grade shea butter margins for Burkina Faso processors. |
| Import-Substitution Crushing Investment | Addresses Ethiopia's structural edible oil deficit through domestic sunflower processing. |
Study Parameters
A standing panel of refinery operations managers, cooperative federation leaders, food manufacturer procurement directors, and national standards body inspectors provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from customs trade records, African Organisation for Standardisation harmonization documents, AfCFTA negotiation disclosures, and Codex Alimentarius alignment reports. Bottom-up crushing capacity assessments and top-down consumption estimates were triangulated against national food balance sheets.
Scenario-bracketing framed projections across the analysis window, modeling baseline, accelerated AfCFTA integration, and delayed EU regulation enforcement paths. Segmentation dimensions included product chemistry grade, end-use application tier, distribution channel structure, and regional regulatory cluster. CAGRs were derived from trend extrapolation of crush capacity additions, policy mandate absorption rates, and substitution elasticities between palm and soft oils.
Stress conditions across naira-ringgit exchange rate bands, South African rail logistics disruption frequency, and Sahelian aflatoxin contamination incidence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding AfCFTA tariff phase-out adherence and EU deforestation due diligence implementation timelines. Cross-checking against FAO food balance sheet revisions and national crush capacity registry updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Fluid Lecithin Market
Ingredients
Polydextrose Ingredients Market
Ingredients
Lipids Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Global Distillers Grains Market
Ingredients
Protein Ingredients Market
Ingredients
Kilned Malt Market
Ingredients
Zea Mays Starch Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Torula Yeast Market
Ingredients
Arrowroot Starch Market
Ingredients
China Cane Sugar Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Roll-Dried Starch Market
Ingredients
Cocoa Beans Market
Ingredients
Commercial Flour Market