
 Organic Cocoa Market | 2026-2036
Organic Cocoa Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Cocoa Market Analysis
Single-origin bar formats and smaller artisanal pack sizes are realigning how buyers evaluate organic cocoa offerings. Barry Callebaut AG leverages its bean-to-bar infrastructure across multiple continents. The Hershey Company anchors North American retail shelf presence through verified supply chain partnerships. Nestlé S.A. differentiates via Rainforest Alliance co-certification layered on organic base standards.
Organic cocoa comprises Theobroma cacao beans cultivated without synthetic pesticides or fertilizers, processed under temperature-controlled roasting below 120°C to preserve volatile aromatic compounds and antioxidant profiles. The material serves confectionery, bakery, and beverage applications requiring clean-label positioning and traceable origin documentation. Dark chocolate commands the widest organic premium spread due to higher cocoa mass concentration and shorter ingredient lists. Cocoa butter captures margin concentration from cosmetics and pharmaceutical buyers seeking unrefined press cake outputs. Milk chocolate trails in organic conversion because dairy ingredient sourcing adds certification complexity and cost layering.
FDA organic labeling rules, EU Organic Regulation 2018/848, and ISO 17065 accreditation frameworks collectively gate market access for non-compliant processors. EU EFSA pesticide residue thresholds and US NOP pasture requirements shape farm-level compliance investments and third-party audit frequency. Stakeholders must track evolving equivalency agreements between the EU and major producing nations to anticipate supply disruptions or tariff advantages.
Market Dynamics
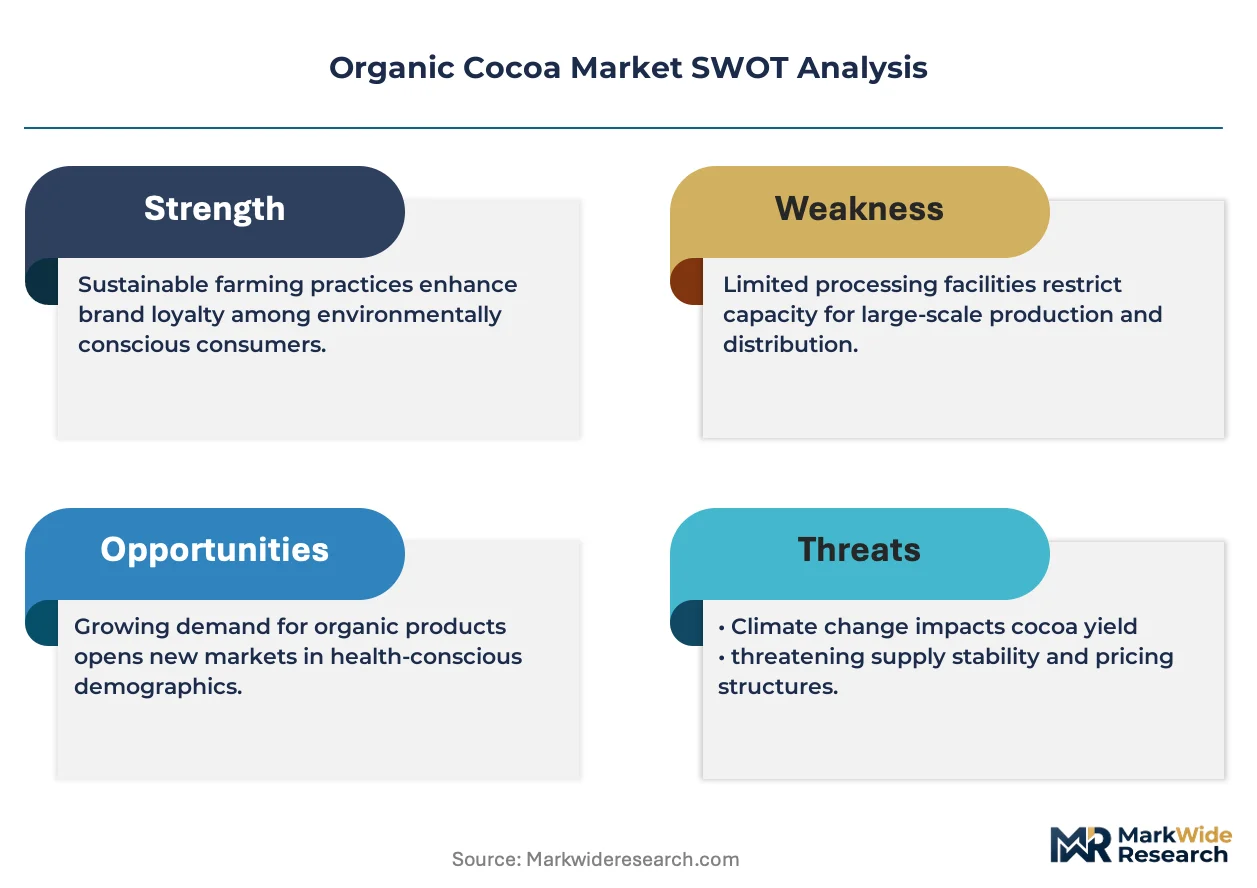
EU Organic Regulation 2018/848 is compressing supply availability as West African smallholders struggle with certification compliance costs and audit frequency requirements, tightening the certified bean pipeline before processing capacity can adapt.
Growth Catalysts
- Clean-label confectionery demand:Bakery and beverage manufacturers in Germany and Switzerland now mandate traceable origin documentation for premium positioning.
- FDA organic labeling alignment:US NOP pasture requirements for dairy inputs are forcing parallel investment in organic cocoa butter certification for milk chocolate variants.
- Bean-to-bar infrastructure:Temperature-controlled roasting below 120°C is preserving volatile aromatic compounds that command specialty dark chocolate premiums.
Market Restraints
- Input cost volatility:Synthetic fertilizer price spikes in conventional cocoa create parallel pressure on organic manure sourcing and compost logistics.
- Supply concentration risk:Ivory Coast and Ghana smallholder cooperatives dominate certified organic bean output, exposing buyers to regional climate shocks.
- Technical limitation:Cocoa butter extraction yields from unrefined press cake remain 15-20% below conventional solvent methods, constraining cosmetics-grade supply.
Strategic Opportunities
- Underpenetrated origin diversification:Peru and Ecuador high-altitude cooperatives are expanding certified hectarage with shorter EU equivalency approval timelines.
- Emerging application:Pharmaceutical encapsulation demand for antioxidant-rich cocoa polyphenols is opening new extraction contracts.
- Regulatory tailwind:EU Green Deal farm-to-fork traceability mandates are accelerating digital ledger adoption for organic cocoa supply chains.
Industry Challenges
- Certification timeline compression:ISO 17065 accreditation audits now require three-year transition documentation that many West African cooperatives cannot assemble.
- Skill gap in agronomy:Organic pest management expertise for black pod disease control remains scarce among extension services in major producing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Cocoa Market |
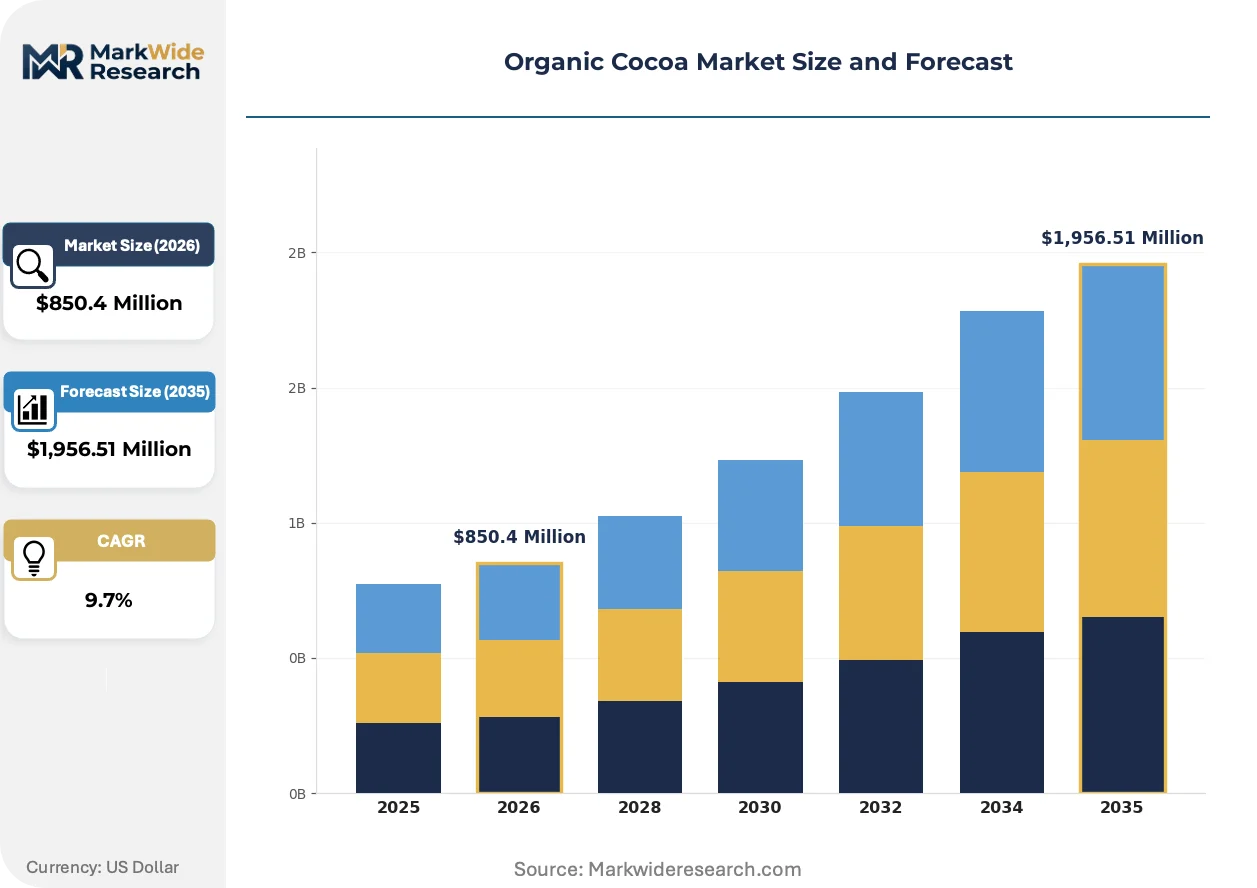
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,956.51 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, Cocoa Powder, Cocoa Butter Packaging Type: Bulk Bags, Retail Packs, Eco-Friendly Packaging, Cans Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Direct Sales End User: Bakers, Confectionery Manufacturers, Food Service Providers, Consumers |
| Companies Covered | Tradin Organic Agriculture B.V., The Hershey Company, Barry Callebaut AG, Mondelēz International, Mars, Incorporated, Cargill, Blommer Chocolate Co., Nestlé S.A., Olam International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Cocoa Market Emerging Trajectories
Processing technology and verification systems are restructuring how organic cocoa moves from farm to finished chocolate, with automation and digital traceability compressing traditional intermediation layers.
Precision fermentation for cocoa pulp control is overtaking conventional post-harvest protocols. Specialty chocolate makers in Belgium and Switzerland now specify microbial starter cultures for consistent flavor precursor development. This biotechnology is enabling smaller batch sizes with reproducible aromatic profiles that previously required multi-ton commodity blending.
EU EFSA pesticide residue thresholds are tightening maximum allowable limits for cadmium and lead in finished chocolate. The industrial consequence is mandatory soil testing and rootstock replacement programs for certified farms. Dark chocolate segments with higher cocoa mass concentration face the steepest compliance investment, pushing some German manufacturers toward lower-percentage formulations.
Direct-origin purchasing contracts are displacing spot-market bean acquisition. Artisanal chocolate makers in Switzerland now source through verified cooperative partnerships rather than commodity brokers. This procurement evolution is most visible in the specialty dark chocolate segment, where single-origin provenance commands measurable shelf price premiums over blended alternatives.
Organic Cocoa Market Segmentation
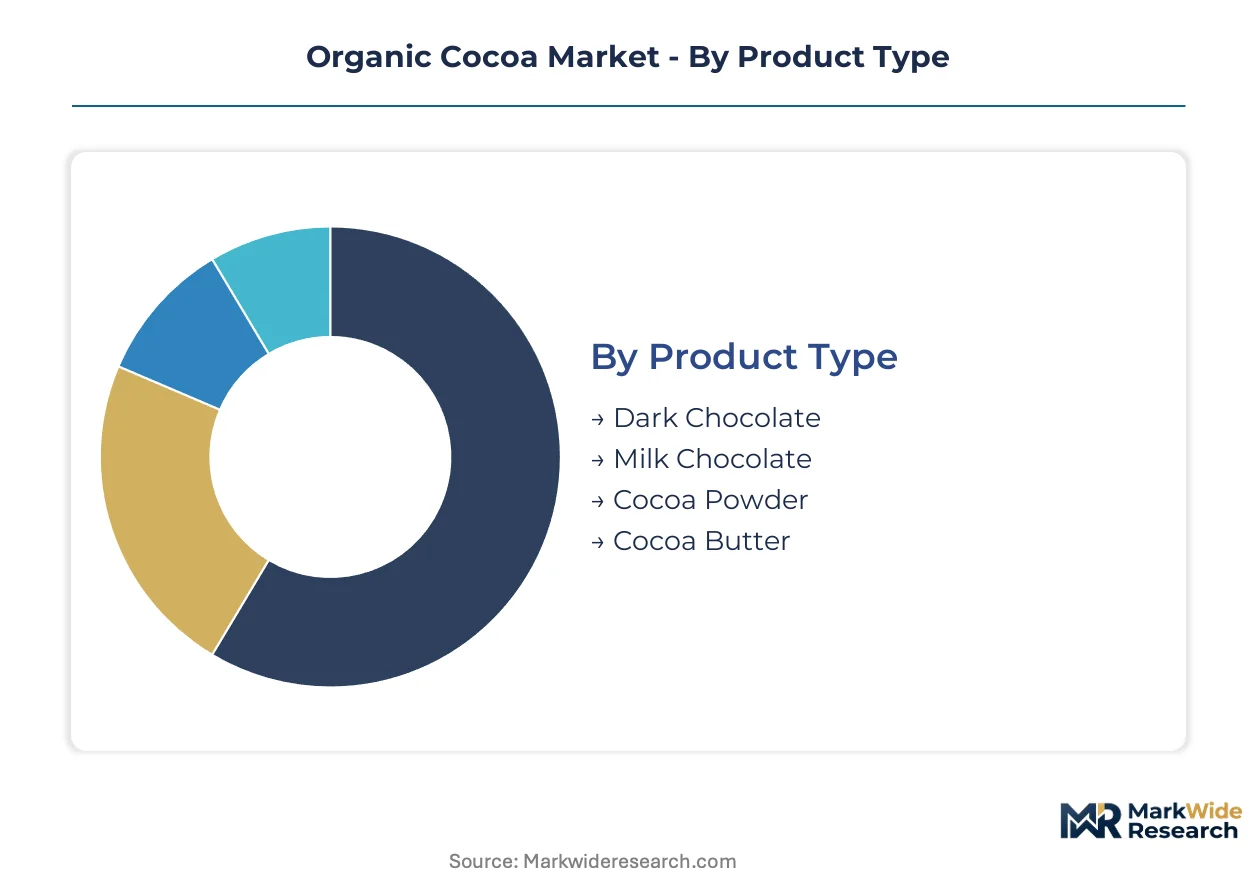
Organic cocoa segmentation reveals how certification requirements, processing specifications, and channel economics fragment addressable demand. Each dimension carries distinct margin profiles and regulatory gatekeeping that reshape competitive positioning across the value chain.
Product Type:
EU EFSA pesticide residue thresholds and US NOP pasture requirements apply differentially across product categories, with higher cocoa mass concentrations triggering stricter heavy metal testing protocols.
- Dark Chocolate:Formulations with 70%+ cocoa mass concentrate volatile aromatic compounds preserved through temperature-controlled roasting below 120°C. German and Swiss specialty makers absorb premium spreads for single-origin bar formats with traceable cooperative documentation.
- Milk Chocolate:Dairy ingredient sourcing layers parallel certification complexity onto cocoa base standards, compressing organic conversion rates. US NOP pasture requirements for milk inputs force synchronized butter certification investments.
- Cocoa Powder:Press cake outputs serve bakery and beverage applications requiring clean-label positioning with antioxidant profile documentation.
- Cocoa Butter:Unrefined extraction yields from organic press cake supply cosmetics and pharmaceutical encapsulation demand for polyphenol-rich outputs.
Dark Chocolate sits at the top of the volume ranking, with Cocoa Butter climbing the fastest.
Packaging Type:
Cost tier stratification separates commodity-scale logistics from artisanal shelf presentation, with sustainability premiums reshaping procurement specifications.
- Bulk Bags:Industrial-scale formats dominate bean-to-bar processor intake and cooperative export consolidation, minimizing per-unit handling costs for high-volume confectionery manufacturers.
- Retail Packs:Smaller artisanal formats command measurable shelf price premiums in Swiss and Belgian specialty channels through single-origin provenance labeling.
- Eco-Friendly Packaging:Compostable and recyclable materials align with EU Green Deal farm-to-fork traceability mandates accelerating digital ledger adoption.
- Cans:Airtight metal containers preserve cocoa powder aromatic stability for extended distribution cycles in humid climates.
Bulk Bags capture the widest volume base, while Eco-Friendly Packaging gains share fastest on regulatory tailwinds.
Distribution Channel:
Channel concentration reflects how traceability requirements and batch size economics reshape intermediary layers between certified farms and finished goods.
- Online Stores:Direct-to-consumer platforms enable artisanal makers to bypass commodity broker markups, with verified cooperative partnerships displacing spot-market acquisition.
- Supermarkets:Mass retail shelf presence requires verified supply chain documentation and Rainforest Alliance co-certification for organic base standard differentiation.
- Specialty Stores:Curated assortments in Germany and Switzerland concentrate demand for single-origin dark chocolate with microbial starter culture specifications.
- Direct Sales:Bean-to-bar infrastructure operators leverage continental processing networks for temperature-controlled roasting consistency.
Supermarkets anchor the volume ranking, with Online Stores expanding most quickly on direct-origin purchasing contract proliferation.
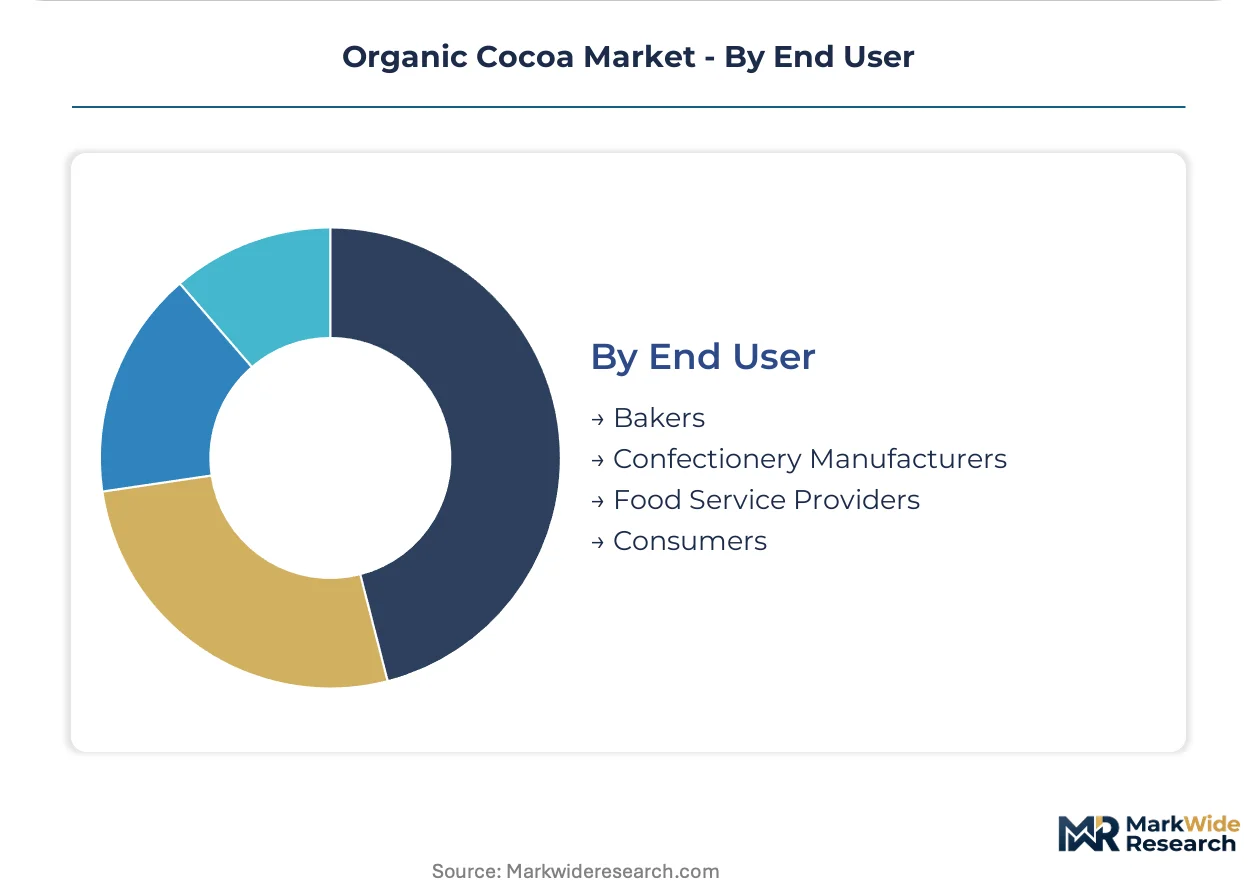
End User:
Application maturity separates established confectionery demand from emerging pharmaceutical extraction contracts reshaping margin capture.
- Bakers:Clean-label positioning requirements in German bakery chains now mandate traceable origin documentation for premium ingredient sourcing.
- Confectionery Manufacturers:Premium chocolate makers in Belgium drive adoption amid tightening EU organic certification standards and cadmium threshold compliance.
- Food Service Providers:High-volume cocoa butter demand from cosmetics and pharmaceutical buyers seeks unrefined press cake outputs with antioxidant concentration verification.
- Consumers:Specialty dark chocolate segments in Switzerland concentrate retail purchasing through verified cooperative partnerships rather than blended alternatives.
Confectionery Manufacturers dominate volume rankings, with Food Service Providers showing the steepest expansion trajectory on pharmaceutical encapsulation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic cocoa cultivation traces its commercial roots to Mesoamerican civilizations, yet contemporary market formation crystallized in Western Europe during the late twentieth century as Swiss and Belgian chocolate houses pioneered certified supply chains for premium dark chocolate production.
Germany
Specialty bakery chains and artisanal confectioners in Cologne and Hamburg now mandate traceable origin documentation for clean-label positioning. EU Organic Regulation 2018/848 enforcement through EFSA cadmium thresholds is forcing soil testing investments across supplier farms. The Cologne-Düsseldorf corridor concentrates bean-to-bar processing infrastructure for temperature-controlled roasting below 120°C.
Switzerland
Geneva and Zurich-based chocolate houses command the steepest single-origin premiums for dark chocolate with microbial starter culture specifications. Swissmedic-aligned quality protocols exceed baseline EU organic standards for pharmaceutical-grade cocoa butter extraction. The Lake Geneva region anchors artisanal retail pack formatting for verified cooperative partnerships.
United States
FDA organic labeling alignment with US NOP pasture requirements is synchronizing dairy input certification for milk chocolate variants. The Hershey Company anchors mass retail shelf presence through Pennsylvania-based processing networks. Greater Boston and San Francisco Bay Area specialty makers are displacing spot-market acquisition with direct-origin purchasing contracts.
Belgium
Brussels and Antwerp processors drive adoption amid tightening EU organic certification standards for 70%+ cocoa mass dark chocolate formulations. EFSA pesticide residue thresholds are compressing allowable heavy metal limits faster than West African smallholders can adapt. The Port of Antwerp consolidates certified organic bean import logistics for continental distribution.
Peru
High-altitude cooperatives in the Cusco and San Martín regions are expanding certified hectarage with shorter EU equivalency approval timelines than West African alternatives. The country's national agricultural regulator is streamlining organic transition documentation for ISO 17065 accreditation. Lima-based exporters are capturing pharmaceutical encapsulation contracts for antioxidant-rich polyphenol outputs.
Organic Cocoa Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tiering and traceability depth, with Rainforest Alliance co-certification and bean-to-bar infrastructure separating price realization levels. The vendor base stratifies into three tiers: multinational processors with continental roasting networks, mid-scale organic specialists with cooperative partnerships, and artisanal makers with single-origin bar formats. Dominant competitive moves include direct-origin purchasing contract proliferation and precision fermentation technology licensing for flavor precursor consistency.
Within the multinational processor tier, Barry Callebaut AG and Nestlé S.A. exemplify divergent certification strategies, with the former leveraging multi-continental bean-to-bar infrastructure and the latter layering Rainforest Alliance co-certification onto organic base standards. The Hershey Company occupies a position anchoring North American retail shelf presence through verified supply chain partnerships. Among trading specialists, Tradin Organic Agriculture B.V. represents the cooperative-partnership archetype for certified bean consolidation.
| Leading Market Players |
|---|
| Tradin Organic Agriculture B.V. |
| The Hershey Company |
| Barry Callebaut AG |
| Mondelēz International |
| Mars, Incorporated |
| Cargill |
| Blommer Chocolate Co. |
| Nestlé S.A. |
| Olam International Limited |
| Others |
Supply Flow & Price Mechanics
Artisanal chocolate makers in Switzerland and Belgium anchor premium-tier pricing power through single-origin provenance requirements, while mass-market confectioners absorb cost compression from West African supply concentration. This buyer-archetype stratification produces divergent margin structures across certification tiers and processing specifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates bean-to-bar specialists from commodity processors and spot-market traders. Price differentiation rests on EU Organic Regulation 2018/848 compliance depth and Rainforest Alliance co-certification layering. Cost compression in standard-tier milk chocolate variants is intensifying because dairy input certification adds parallel NOP pasture requirements. Mass retail buyers show highest price sensitivity, while Swiss pharmaceutical-grade cocoa butter purchasers absorb premium spreads without volume elasticity.
Supply Chain Analysis
Direct-origin purchasing contracts displace traditional commodity broker intermediation for specialty dark chocolate demand. Geographic concentration in Ivory Coast, Ghana, and Peru exposes buyers to regional climate shocks and EU equivalency approval timelines. Raw material flows draw from organic manure sourcing, compost logistics networks, and unrefined press cake outputs. Tariff exposure from evolving EU-West Africa trade agreements presents structural risk for certified bean pipeline stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in organic cocoa rests on pharmaceutical encapsulation demand for antioxidant-rich polyphenol outputs, offsetting input cost volatility in conventional confectionery channels.
For Market Incumbents: To counter Peru and Ecuador high-altitude cooperatives with shorter EU equivalency timelines, Barry Callebaut AG and Nestlé S.A. must deepen backward integration into Cusco and San Martín sourcing networks. Certification investment in ISO 17065 three-year transition documentation capabilities anchors defensive positioning against West African supply compression. For New Entrants and Emerging Players: Artisanal retail channels in the Lake Geneva region offer the most penetrable white-space for microbial starter culture specifications and precision fermentation licensing. Direct-to-consumer online platforms enable bypass of supermarket Rainforest Alliance co-certification requirements. A go-to-market angle centered on pharmaceutical-grade cocoa butter extraction contracts captures premium-margin positioning. For Investors and Strategic Acquirers: Mid-scale organic specialists with verified cooperative partnerships are the most active acquirer targets in this space. Long-term viability over a five-to-ten year horizon hinges on digital ledger adoption for EU Green Deal farm-to-fork traceability mandates. Watch for EFSA cadmium threshold enforcement acceleration as the inflection indicator for soil testing investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Licensing | Belgian and Swiss specialty makers specify microbial starter cultures for flavor precursor consistency. |
| Direct-Origin Purchasing Contracts | Artisanal chocolate makers source through verified cooperative partnerships rather than commodity brokers. |
| Pharmaceutical-Grade Extraction Capacity | Cosmetics and pharmaceutical buyers seek unrefined press cake outputs with antioxidant concentration verification. |
| Digital Ledger Traceability Investment | EU Green Deal farm-to-fork mandates accelerate supply chain transparency for organic certification. |
| High-Altitude Origin Diversification | Peru and Ecuador cooperatives expand certified hectarage with shorter EU equivalency approval timelines. |
Methodological Framework
Coverage spans Western Europe, North America, and Latin America, with primary inputs from each region combined with secondary validation. Interviews with bean-to-bar processing executives, cooperative agronomy extension officers, pharmaceutical procurement managers, and specialty retail category buyers inform demand-side assessments. Secondary sources include EU EFSA residue threshold filings, USDA NOP certification databases, Swissmedic quality protocol documentation, and customs trade data for certified organic bean flows. Bottom-up volume modeling and top-down value reconciliation ensure cross-verified outputs.
Rate-of-change decomposition separates volume drivers from price realization factors across the projection horizon. Segmentation dimensions include product type, packaging format, distribution channel, and end-use application, with additional granularity on certification tier and origin altitude. CAGRs derive from trend extrapolation of clean-label confectionery demand, EU regulatory enforcement intensity, and pharmaceutical encapsulation contract growth. Industry-specific inputs capture precision fermentation adoption curves and digital ledger implementation timelines.
Revisions become necessary when EU-West Africa equivalency agreements shift, EFSA heavy metal thresholds tighten beyond current soil testing capabilities, or West African cooperative certification timelines compress further. Forecasts reflect documented assumptions on regulatory enforcement consistency and climate shock frequency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Global Organic Packaged Food Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Organic Food and Beverages Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Global Natural and Organic Food Market
Organic Food and Beverages
Organic Honey Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
United States Organic Food Market