
 Prenatal Vitamin Ingredients Market | 2026-2036
Prenatal Vitamin Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Prenatal Vitamin Ingredients Market Analysis
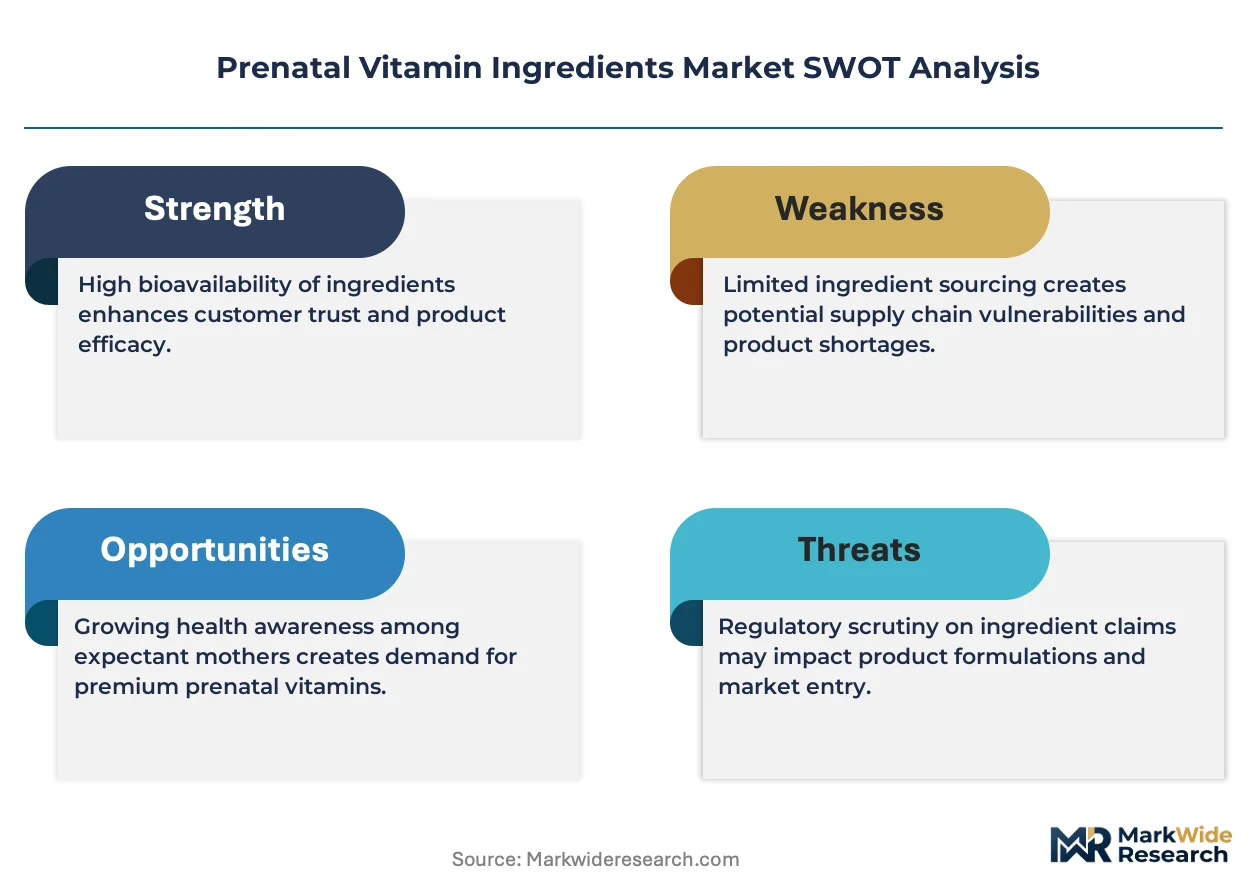
Asset-light contract manufacturing and white-label financing is narrowing the capital barrier for new entrants in prenatal nutrition. DSM leverages its backward integration into algal DHA to sustain margin control across the omega-3 value chain. BASF competes through its vitamin premix specialization, anchoring supply relationships with multinational pharmaceutical formulators. Abbott dominates the clinical channel, extending its reach through hospital-affiliated prenatal programs.
Prenatal vitamin ingredients comprise bioactive compounds including folic acid, iron salts, calcium carbonate, and docosahexaenoic acid (DHA) formulated to support fetal neural development, hematopoiesis, and skeletal formation during gestation. These ingredients typically meet USP or EP monograph specifications for potency, dissolution, and heavy-metal limits before incorporation into finished dosage forms. Folic acid and iron occupy the largest volume positions within the ingredient mix, reflecting their established role in preventing neural tube defects and maternal anemia. DHA represents the fastest-expanding margin pool as algae-derived alternatives displace fish-oil sources in premium formulations. Gummies are gaining share among formulation types, though tablets retain cost advantages in pharmacy and institutional channels.
The US FDA oversees Current Good Manufacturing Practice compliance for dietary supplements, while the EPA monitors heavy-metal thresholds in marine-derived DHA feedstocks. The EU's EFSA health-claims framework restricts how prenatal products communicate benefits, shaping label architecture across export-bound formulations. China's NMPA and India's CDSCO impose distinct purity and stability-testing protocols that fragment registration pathways for multinational suppliers. Stakeholders must monitor evolving methylfolate substitution trends and algae-DHA capacity buildouts to calibrate ingredient portfolios against shifting consumer preference and regulatory acceptance.
Market Dynamics
Algae-derived DHA capacity expansion is compressing omega-3 supply chains and redistributing margin pools away from marine fisheries toward fermentation-based biomanufacturing platforms.
Growth Catalysts
- EFSA health-claims framework:The EU's strict benefit-communication rules force manufacturers toward clinically substantiated ingredient dossiers, elevating demand for USP-grade folic acid and methylfolate variants that withstand regulatory scrutiny.
- Direct-to-consumer subscription models:Expecting mothers in developed markets bypass traditional pharmacy channels, creating pull-through demand for gummy-compatible ingredient formats with enhanced stability profiles.
- Hospital-affiliated prenatal programs:Institutional procurement in the United States concentrates volume around iron salts and calcium carbonate premixes, locking in multi-year supply agreements with qualified ingredient suppliers.
Market Restraints
- Fish-oil DHA price volatility:Marine feedstock costs fluctuate with Peruvian anchovy harvest cycles and El Niño patterns, squeezing margins for manufacturers without algae-DHA alternatives.
- Heavy-metal testing protocols:EPA thresholds for mercury and arsenic in marine-derived omega-3s add compliance layers that delay batch releases and inflate quality-assurance overhead.
- Methylfolate substitution hesitancy:Formulators in cost-sensitive channels resist premium folate variants despite bioavailability advantages, preserving volume share for synthetic folic acid.
Strategic Opportunities
- India's CDSCO registration pathway:Underpenetrated maternal nutrition programs in tier-2 cities create whitespace for iron-fortified premix suppliers willing to navigate localized stability-testing requirements.
- China's NMPA dual-carbon alignment:Algae-DHA fermentation facilities qualify for green manufacturing incentives, lowering effective production costs for export-bound ingredient streams.
- Pharmacy private-label expansion:Retail chains in the United States seek white-label vitamin premix partnerships, opening contract manufacturing slots for specialized formulators with USP certification.
Industry Challenges
- Algal strain optimization talent scarcity:Fermentation specialists capable of scaling DHA yields from Schizochytrium species command premium compensation, constraining capacity buildout timelines.
- Cross-jurisdictional label harmonization:Divergent USP, EP, and Chinese Pharmacopoeia monograph specifications force redundant testing batches, complicating inventory pooling across export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prenatal Vitamin Ingredients Market |
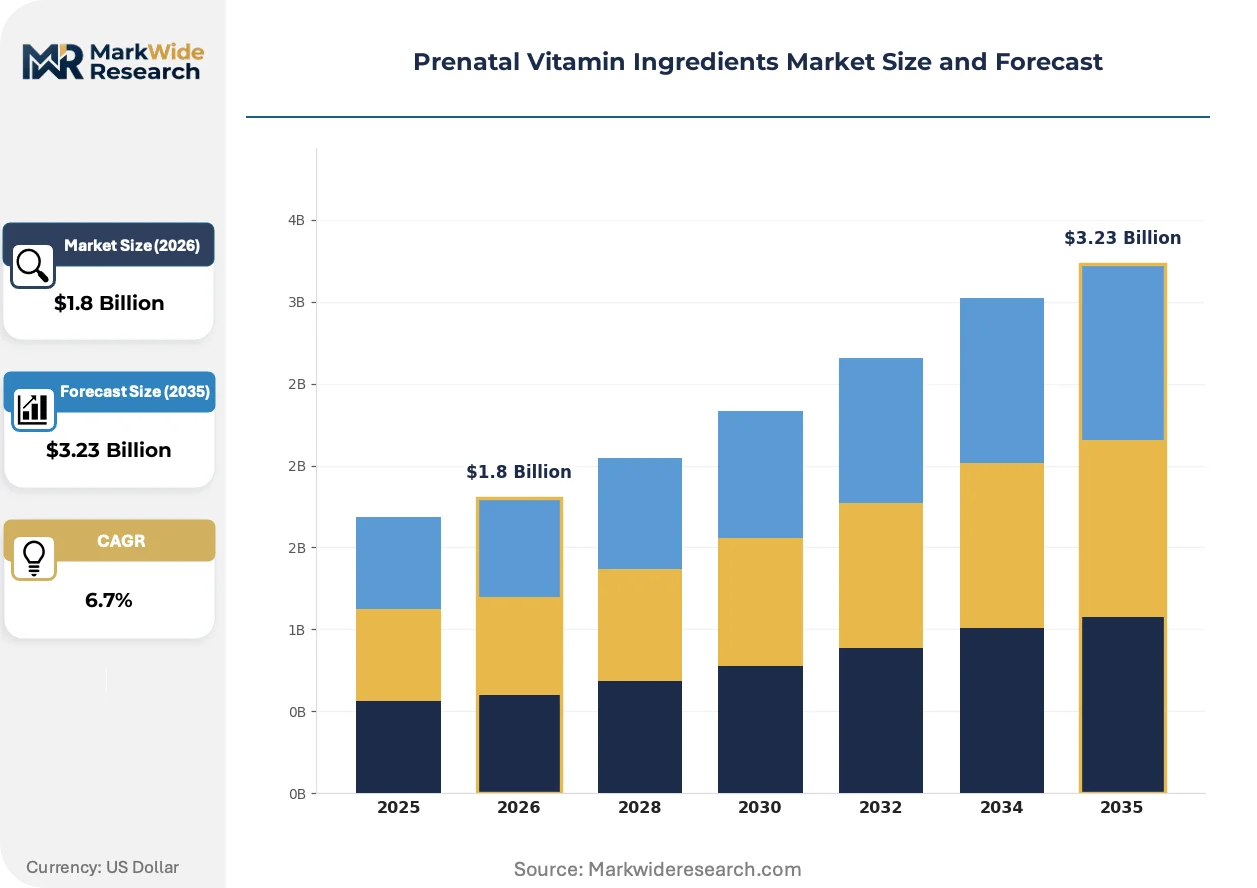
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Folic Acid, Iron, Calcium, DHA Formulation Type: Tablets, Gummies, Powders, Liquid Distribution Channel: Pharmacies, Health Stores, Online Retailers, Supermarkets Target Consumer: Expecting Mothers, Healthcare Providers, Nutritionists, Caregivers |
| Companies Covered | BASF, DSM, Lonza, Merck, Pfizer, Church & Dwight, Abbott, Pharmavite, Garden of Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prenatal Vitamin Ingredients Market Emerging Trajectories
Ingredient sourcing logic is inverting as sustainability credentials displace cost-per-kilogram as the primary procurement filter, reshaping supplier qualification protocols and capital allocation across the value chain.
Fermentation-derived DHA from Schizochytrium and Crypthecodinium strains delivers consistent fatty-acid profiles without marine contaminant risk. Premium gummy and softgel manufacturers in North America and Western Europe are migrating from fish-oil sources to secure clean-label positioning and simplify regulatory compliance. This shift compresses demand for traditional marine rendering operations while expanding bioreactor capacity requirements.
REACH authorization procedures for novel food-contact substances and residual solvents are tightening purity thresholds for excipient suppliers serving European formulators. Manufacturers must now document supply-chain absence of SVHC candidates across vitamin premix inputs. The burden falls heaviest on mid-sized compounders lacking dedicated regulatory-affairs functions, accelerating consolidation around integrated suppliers with in-house toxicology expertise.
Subscription-based prenatal nutrition services bypass wholesale and retail intermediaries, capturing consumer preference data that reshapes ingredient specification. Direct relationships enable real-time formulation feedback, shortening product-development cycles from eighteen months to under six. This pattern concentrates in the United States where insurance reimbursement for telehealth nutritional counseling normalizes digital-first maternal care.
Prenatal Vitamin Ingredients Market Segmentation
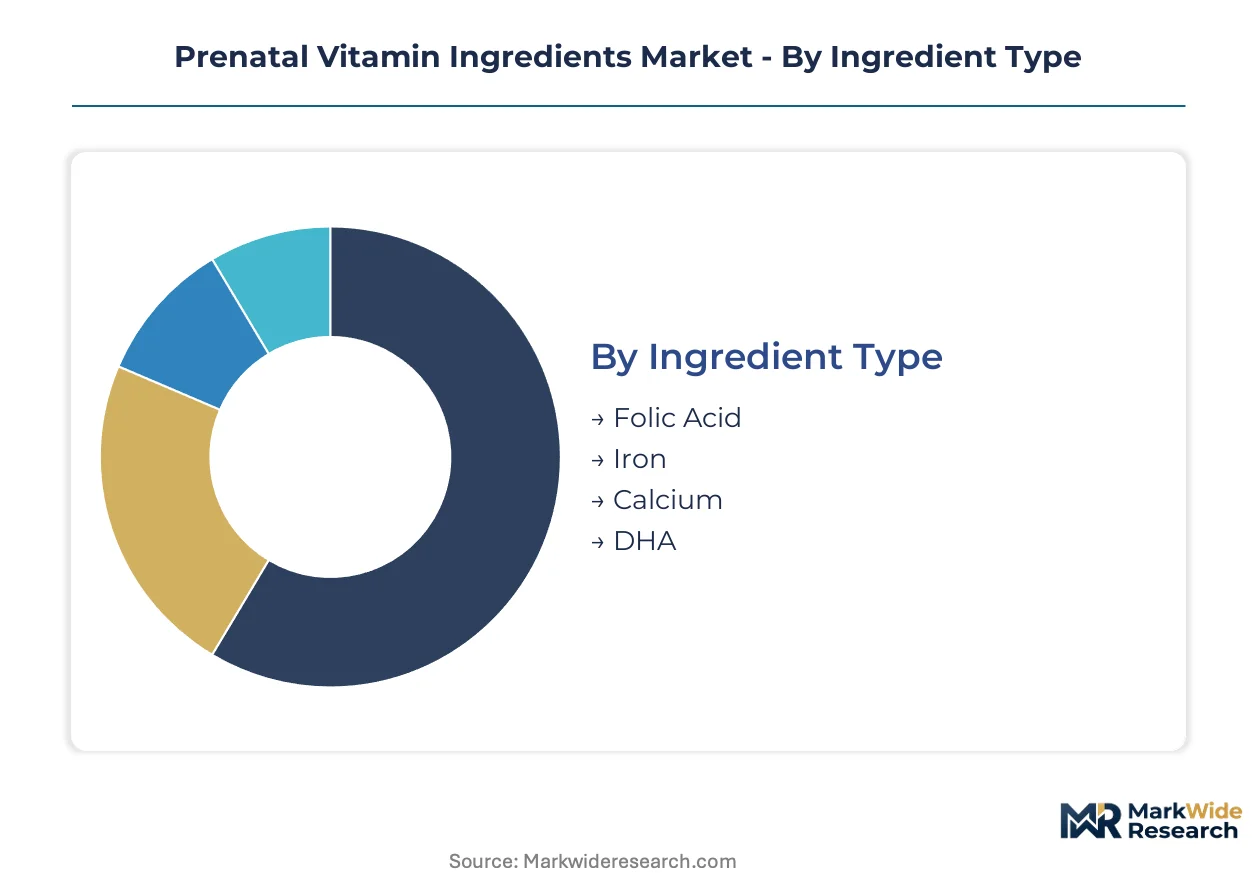
Prenatal vitamin ingredient procurement splits across four structural dimensions. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier qualification protocols.
Ingredient Type:
Cost tier stratification governs procurement behavior across the four active ingredient categories.
- Folic Acid:Synthetic pteroylglutamic acid dominates volume positions due to established neural tube defect prevention protocols. US hospital-affiliated prenatal programs concentrate demand around USP-grade specifications, though methylfolate variants command premium positioning in direct-to-consumer channels.
- DHA:Docosahexaenoic acid sources bifurcate between marine fish oil and fermentation-derived algae. Algae-DHA from Schizochytrium strains eliminates heavy-metal testing overhead while securing EFSA-compliant clean-label positioning for European export formulations.
- Iron:Ferrous salts anchor maternal anemia prevention protocols across pharmacy and institutional channels.
- Calcium:Carbonate and citrate forms support fetal skeletal formation with cost-sensitive positioning in emerging markets.
Folic acid holds installed capacity. DHA is rotating up the share rankings.
Formulation Type:
Application-driven manufacturing requirements fragment equipment investment and stability-testing protocols.
- Tablets:Compressed dosage forms retain cost advantages in pharmacy and hospital procurement. USP dissolution specifications and iron salt compatibility drive excipient selection toward microcrystalline cellulose and croscarmellose sodium systems.
- Gummies:Gelatin and pectin-based chewables capture subscription-model demand from millennial expecting mothers. Stability challenges around moisture-sensitive vitamins force modified atmosphere packaging and shorter shelf-life claims.
- Powders:Sachet formats serve taste-averse consumers in Asia-Pacific markets with flexible dosing.
- Liquid:Suspension vehicles accommodate swallowing difficulties in late-term gestation.
Tablets maintain manufacturing scale. Gummies are climbing the fastest.
Distribution Channel:
Customer type concentration determines pricing power and inventory velocity across four channel structures.
- Pharmacies:Brick-and-mortar retail and institutional dispensing concentrates volume around qualified suppliers with USP certification. Private-label programs at CVS and Walgreens create contract manufacturing slots for specialized vitamin premix formulators.
- Online Retailers:Direct-to-consumer subscription platforms bypass wholesale intermediaries and capture real-time formulation feedback. Amazon and specialized maternal health services shorten product-development cycles through direct consumer relationships.
- Health Stores:Specialty retail emphasizes premium positioning and clean-label credentials.
- Supermarkets:Mass-market placement competes on unit economics and promotional velocity.
Pharmacies anchor volume throughput. Online retailers are gaining share fastest.
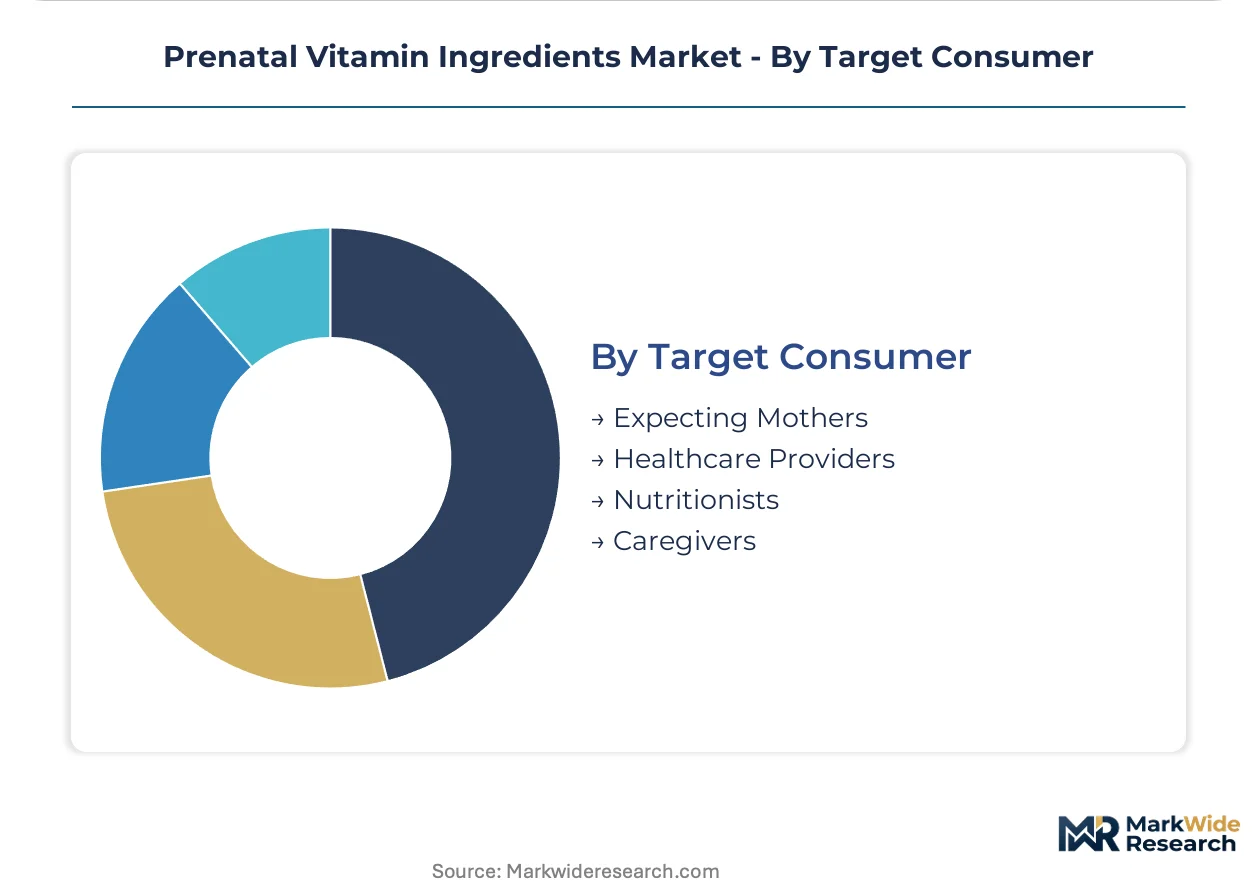
Target Consumer:
Volume concentration varies sharply across four purchaser categories with divergent specification authority.
- Expecting Mothers:End-users drive gummy format preference and algae-DHA clean-label demand through direct purchasing decisions. Subscription retention metrics influence ingredient stability investments.
- Healthcare Providers:Obstetricians and hospital formulary committees lock in multi-year iron and calcium premix agreements. Institutional procurement prioritizes USP monograph compliance over novel bioavailability claims.
- Nutritionists:Licensed practitioners influence methylfolate substitution in reimbursed nutritional counseling.
- Caregivers:Family purchasers respond to palatability and convenience positioning.
Healthcare providers control institutional volume. Expecting mothers are rotating up the influence rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital-affiliated prenatal programs in the United States concentrate institutional procurement volume, while direct-to-consumer subscription models reshape demand patterns among millennial expecting mothers in Western Europe and East Asia.
United States
FDA Current Good Manufacturing Practice compliance requirements elevate supplier qualification barriers for dietary supplement ingredients. Hospital formulary committees lock in multi-year iron salt and calcium carbonate premix agreements with USP-certified manufacturers. DSM maintains backward integration into algal DHA production facilities serving North American gummy and softgel formulators.
Germany
EFSA health-claims framework restricts benefit communication on prenatal product labels, forcing manufacturers toward clinically substantiated methylfolate dossiers. REACH authorization procedures tighten purity thresholds for excipient suppliers serving European formulators. BASF anchors vitamin premix supply relationships from its Ludwigshafen headquarters with multinational pharmaceutical compounders.
China
NMPA dual-carbon alignment incentives accelerate algae-DHA fermentation facility buildouts for export-bound ingredient streams. Tier-2 city maternal nutrition programs remain underpenetrated, creating whitespace for iron-fortified premix suppliers. Zhejiang and Jiangsu provinces concentrate bioreactor capacity expansion for Schizochytrium-derived omega-3 production.
India
CDSCO imposes distinct purity and stability-testing protocols that fragment registration pathways for multinational suppliers. FSSAI fortification guidelines drive public-sector demand for iron and folic acid premixes in national maternal health programs. Maharashtra and Gujarat host contract manufacturing clusters serving domestic pharmacy private-label programs.
Japan
PMDA pharmaceutical-grade specifications govern ingredient sourcing for quasi-drug prenatal formulations. METI green manufacturing incentives support fermentation-based DHA capacity investments. Tokyo-Osaka corridor distributors specialize in premium gummy formats for aging first-time mothers seeking palatable alternatives to tablets.
Prenatal Vitamin Ingredients Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The ingredient supply base organizes around three archetypes: backward-integrated chemical conglomerates with captive fermentation capacity, specialized vitamin premix compounders with USP certification, and asset-light contract manufacturers serving private-label programs. Consolidation pressure concentrates among mid-sized compounders lacking dedicated regulatory-affairs functions. Competitive moves center on algae-DHA capacity expansion and cross-jurisdictional label harmonization investments.
Among chemical conglomerates with fermentation platforms, DSM and BASF exemplify distinct strategic positioning. DSM leverages algal DHA backward integration to sustain margin control across the omega-3 value chain. BASF competes through vitamin premix specialization, anchoring supply relationships with multinational pharmaceutical formulators. Abbott occupies the clinical channel tier, extending reach through hospital-affiliated prenatal programs in the United States.
| Leading Market Players |
|---|
| BASF |
| DSM |
| Lonza |
| Merck |
| Pfizer |
| Church & Dwight |
| Abbott |
| Pharmavite |
| Garden of Life |
| Others |
Supply Flow & Price Mechanics
China's concentration of Schizochytrium fermentation capacity for algae-derived DHA anchors margin pools downstream with North American gummy and softgel formulators seeking clean-label positioning. This upstream consolidation enables premium pricing for USP-certified premix suppliers while compressing margins for fish-oil DHA manufacturers exposed to Peruvian anchovy harvest volatility.
Pricing Analysis
Certification level creates the primary spread across USP-grade, EP-grade, and food-grade ingredient tiers. Pricing stratifies across premium methylfolate variants, standard synthetic folic acid, and economy iron salts with divergent bioavailability profiles. Cost compression in marine-derived DHA is intensifying because algae fermentation capacity expansion eliminates heavy-metal testing overhead. Hospital formulary committees demonstrate lowest price sensitivity while mass-market supermarket channels drive hardest bargain.
Supply Chain Analysis
Peruvian anchovy fisheries, Chinese Schizochytrium bioreactors, and Indian ferrous salt refineries anchor upstream feedstock availability for global prenutrient sourcing. Raw material dependencies center on marine omega-3 oils, fermentation media nutrients, and pharmaceutical-grade excipients. Single-source vulnerability runs through concentrated algae-DHA fermentation platforms in Zhejiang and Jiangsu provinces. Distribution runs through qualified vitamin premix compounders serving pharmacy private-label programs and direct-to-consumer subscription fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prenatal vitamin ingredients sit in early-cycle expansion as direct-to-consumer subscription models normalize digital-first maternal care and pull through demand for stability-engineered gummy formats. Algae-DHA capacity buildouts and methylfolate substitution trends create multiple vectors for supplier repositioning.
For Market Incumbents: Insulate margin positions through backward integration into fermentation capacity and exclusive multi-year premix agreements with hospital-affiliated prenatal programs. DSM's captive Schizochytrium production demonstrates how upstream control neutralizes fish-oil price volatility. BASF's Ludwigshafen vitamin premix specialization locks in pharmaceutical formulator relationships against emerging contract manufacturers. For New Entrants and Emerging Players: India's tier-2 city maternal nutrition programs offer whitespace for iron-fortified premix suppliers willing to navigate CDSCO stability-testing protocols. White-label financing and asset-light contract manufacturing narrow capital barriers for pharmacy private-label entrants. Target CVS and Walgreens vitamin aisle resets with USP-certified tablet and gummy formulations. For Investors and Strategic Acquirers: Capital is best deployed toward specialized vitamin premix compounders with cross-jurisdictional monograph expertise and established hospital formulary access. Long-term viability hinges on regulatory-affairs capabilities that accelerate multi-market registration. Monitor methylfolate substitution rates in reimbursed nutritional counseling as inflection indicator for premium ingredient demand.| Strategic Initiative | Industry Significance |
|---|---|
| Algae-DHA Fermentation Capacity Expansion | Eliminates marine contaminant risk while securing EFSA-compliant clean-label positioning for European exports. |
| USP Certification Investment | Unlocks hospital formulary access and multi-year iron salt premix agreements with institutional procurement committees. |
| Direct-to-Consumer Subscription Launch | Captures real-time formulation feedback from millennial expecting mothers and shortens product development cycles. |
| Cross-Jurisdictional Label Harmonization | Reduces redundant testing batches across USP, EP, and Chinese Pharmacopoeia specifications for inventory pooling efficiency. |
| Pharmacy Private-Label Partnership | Opens contract manufacturing slots for specialized formulators at CVS, Walgreens, and retail chain vitamin programs. |
Methodological Framework
A standing panel of fermentation process engineers, hospital formulary directors, vitamin premix procurement managers, and regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA dietary supplement CGMP guidance documents, EFSA health-claims register entries, NMPA dual-carbon policy circulars, and USP monograph revision notices. Bottom-up ingredient demand modeling and top-down finished product market sizing underwent iterative triangulation.
Scenario bracketing around algae-DHA substitution velocity, methylfolate penetration curves, and subscription-model adoption rates shaped projection boundaries across the analysis window. Segmentation dimensions incorporated ingredient type, formulation format, distribution channel, and target consumer archetype. CAGRs derived from volume trajectory modeling against historical premix consumption patterns and hospital procurement cycle analysis.
Practitioners should monitor regulatory acceptance of methylfolate health claims, fermentation yield breakthroughs, and insurance reimbursement shifts for nutritional counseling as early signals for forecast revision. Cross-checking against hospital procurement database benchmarks and pharmacy private-label program announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Cooking Oils and Fats Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Bread Flour Market
Ingredients
Philippines Edible Oils & Fats Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
Botanical Ingredients Market
Ingredients
Cholesterol API Market
Ingredients
Corn Gluten Meal Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Plant Extracts Market
Ingredients
Mustard Oil Market
Ingredients
Wheat Gluten Market
Ingredients
Bran Market
Ingredients
Edible Peanut Oil and Soybean Oil Market