
 Global Infant Nutrition Ingredients Market | 2026-2036
Global Infant Nutrition Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Infant Nutrition Ingredients Market Analysis
China is reshaping upstream ingredient sourcing through state-backed dairy processing zones in Inner Mongolia and Heilongjiang. BASF SE leverages its synthetic biology platforms to produce omega-3 fatty acids for infant formula applications. Fonterra Co-operative Group Ltd. anchors Oceania's whey protein concentrate exports through vertically integrated dairy cooperatives. Arla Foods amba competes on specialized milk fat globule membrane ingredients for cognitive development positioning.
Infant nutrition ingredients comprise specially processed proteins, lipids, carbohydrates, vitamins, and minerals formulated to match the nutritional profile of human breast milk, typically manufactured through spray-drying, microencapsulation, and enzymatic hydrolysis to achieve specified particle sizes between 10-100 microns and ensure thermal stability during liquid reconstitution. These ingredients serve commercial infant formula producers, clinical nutrition compounders, and private-label baby food manufacturers requiring precise macronutrient ratios for neonatal dietary support. Powdered formulations dominate volume throughput due to extended shelf stability and lower logistics costs, while ready-to-use liquid formats command premium positioning in hospital neonatal intensive care units and convenience-oriented retail channels. Animal-based dairy derivatives retain structural dominance in whey and casein fractions, though plant-sourced alternatives from pea and rice proteins are gaining formulation share in allergen-managed product lines.
The FDA exercises premarket notification authority over infant formula ingredients through its GRAS and food additive petition pathways, while EFSA mandates novel food safety assessments for bioactive compounds like human milk oligosaccharides prior to EU market entry. China's SAMR enforces formula registration requirements that restrict ingredient suppliers to approved domestic facilities, compressing market access for unqualified foreign producers. India's FSSAI has tightened labeling norms for infant foods, directly affecting how imported nutritional powders declare allergen and fortification content. Stakeholders must monitor divergence between Codex Alimentarius guidelines and national implementation gaps to anticipate reformulation costs and registration timelines.
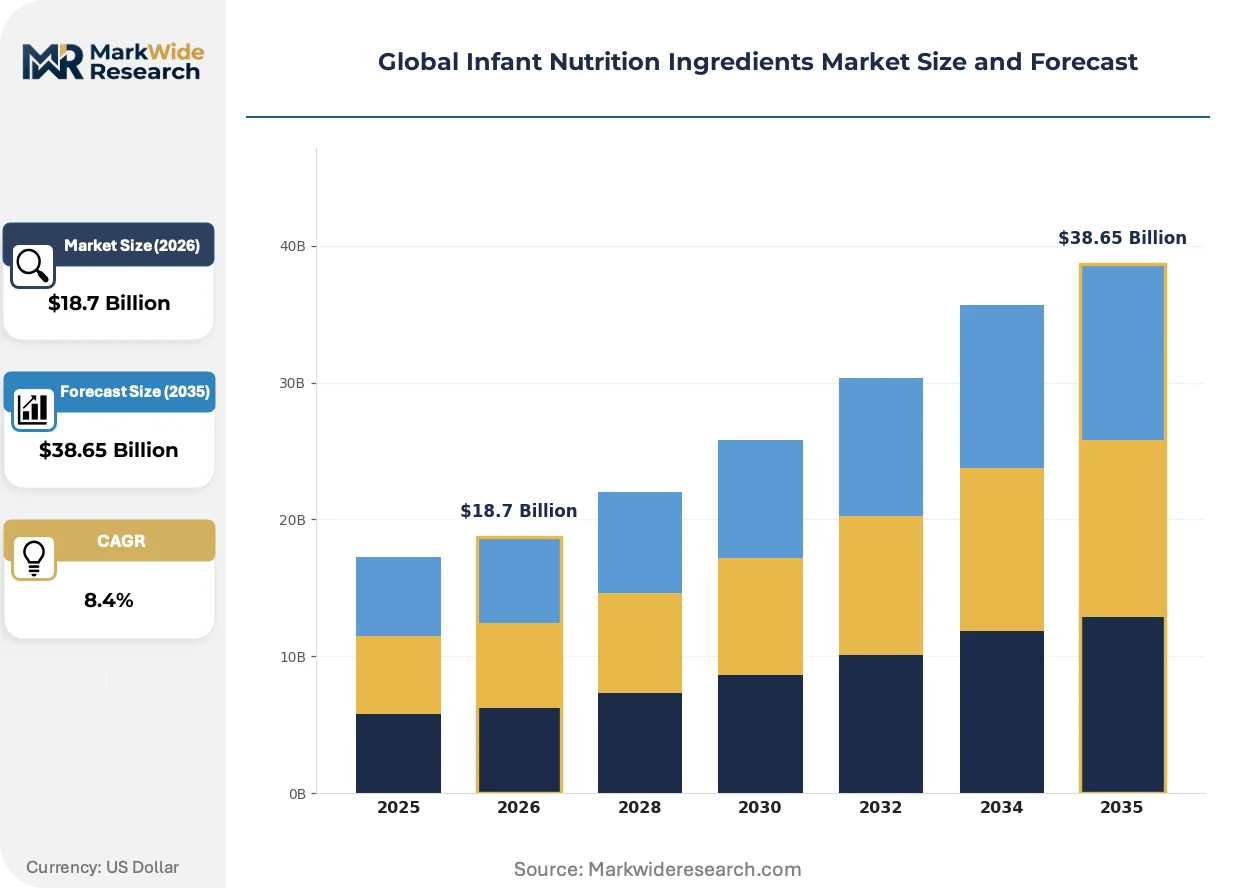
Market Dynamics
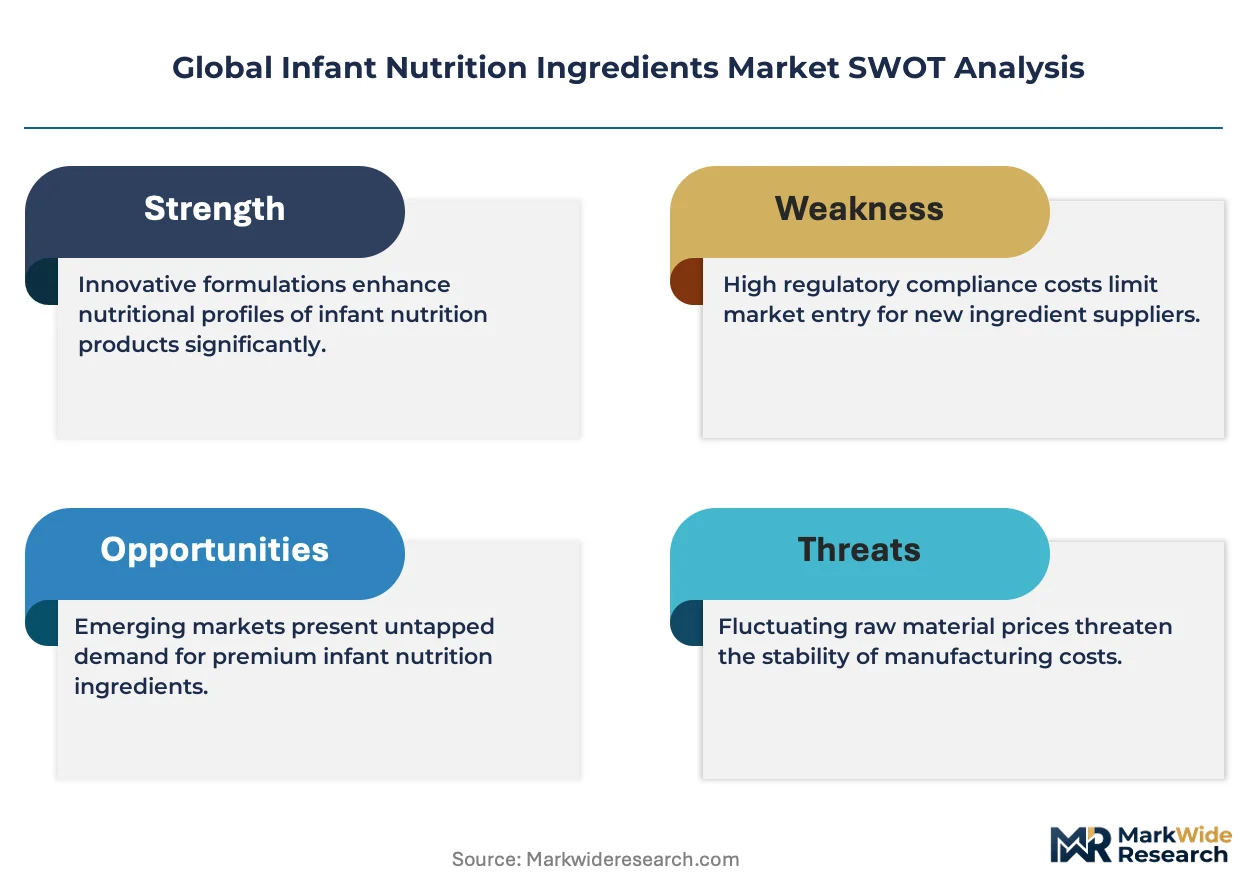
Ingredient purity thresholds are tightening as regulators in China, the EU, and the US impose divergent certification requirements on human milk oligosaccharides and hydrolyzed proteins, forcing suppliers to maintain multiple quality systems simultaneously.
Growth Catalysts
- China's SAMR formula registration:Domestic processing zones in Inner Mongolia and Heilongjiang are capturing state-backed investment, creating captive demand for locally sourced whey fractions.
- EFSA novel food pathways:The EU's authorization framework for 2'-fucosyllactose is accelerating commercial deployment of bioactive carbohydrates in premium formulations.
- Neonatal intensive care liquid formats:Hospital procurement of ready-to-use products is expanding addressable volume beyond traditional powdered retail channels.
Market Restraints
- Whey protein concentrate supply concentration:Oceania's cooperative dairy structures limit alternative sourcing for European and North American formula manufacturers during seasonal shortfalls.
- Enzymatic hydrolysis cost structure:Specialized protease inputs and extended processing cycles inflate unit economics for hypoallergenic product lines.
- Plant protein technical limitations:Pea and rice protein fractions lack complete amino acid profiles, requiring expensive blending protocols to match dairy-based benchmarks.
Strategic Opportunities
- India's FSSAI labeling evolution:New allergen declaration mandates are creating first-mover advantage for suppliers with pre-certified documentation systems.
- Synthetic biology convergence:Precision fermentation platforms are enabling microbial production of omega-3 fatty acids independent of marine supply chains.
- Direct-to-hospital distribution:Bypassing traditional wholesale channels allows ingredient suppliers to capture margin from neonatal unit procurement.
Industry Challenges
- Multi-jurisdiction registration timelines:Simultaneous FDA GRAS petitions, EFSA novel food assessments, and SAMR facility approvals strain regulatory affairs capacity.
- Particle engineering skill scarcity:Spray-drying and microencapsulation expertise for 10-100 micron specifications concentrates in legacy dairy processing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Infant Nutrition Ingredients Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Formula, Baby Cereals, Liquid Concentrates, Nutritional Powders Form: Powdered, Ready-to-Use, Liquid, Granular Source: Animal-Based, Plant-Based, Synthetic, Others Packaging Type: Tetra Packs, Glass Jars, Plastic Containers, Pouches |
| Companies Covered | Koninklijke DSM N.V., BASF SE, Cargill Inc., Fonterra Co-operative Group Ltd., Arla Foods amba, Royal FrieslandCampina N.V., Glanbia plc, AAK AB, Lactalis Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Infant Nutrition Ingredients Market Emerging Trajectories
Process control systems and biosynthetic platforms are reconfiguring how infant nutrition ingredients achieve thermal stability and macronutrient precision, compressing development cycles while multiplying compliance touchpoints.
Precision fermentation is digitizing lipid production for infant formula applications. Specialty manufacturers are adopting microbial cell factories to synthesize DHA and ARA omega-3 fatty acids, eliminating dependency on fish oil supply volatility. This biotechnology is digitizing quality assurance protocols through real-time metabolite monitoring, reducing batch-to-batch variation.
China's GB standards for infant formula are mandating stricter heavy metal thresholds and microbiological surveillance than Codex Alimentarius baselines. Domestic facilities in Heilongjiang province are retrofitting production lines to meet these specifications ahead of foreign competitors. European ingredient exporters face extended SAMR facility audit queues as registration backlogs concentrate approval capacity.
Hospital procurement teams are consolidating supplier relationships around full-service ingredient portfolios spanning proteins, lipids, and bioactive carbohydrates. This buyer concentration is displacing fragmented sourcing from specialized single-category vendors. The shift is most pronounced in North American neonatal intensive care networks, where formulary standardization reduces clinical variation risk.
Global Infant Nutrition Ingredients Market Segmentation
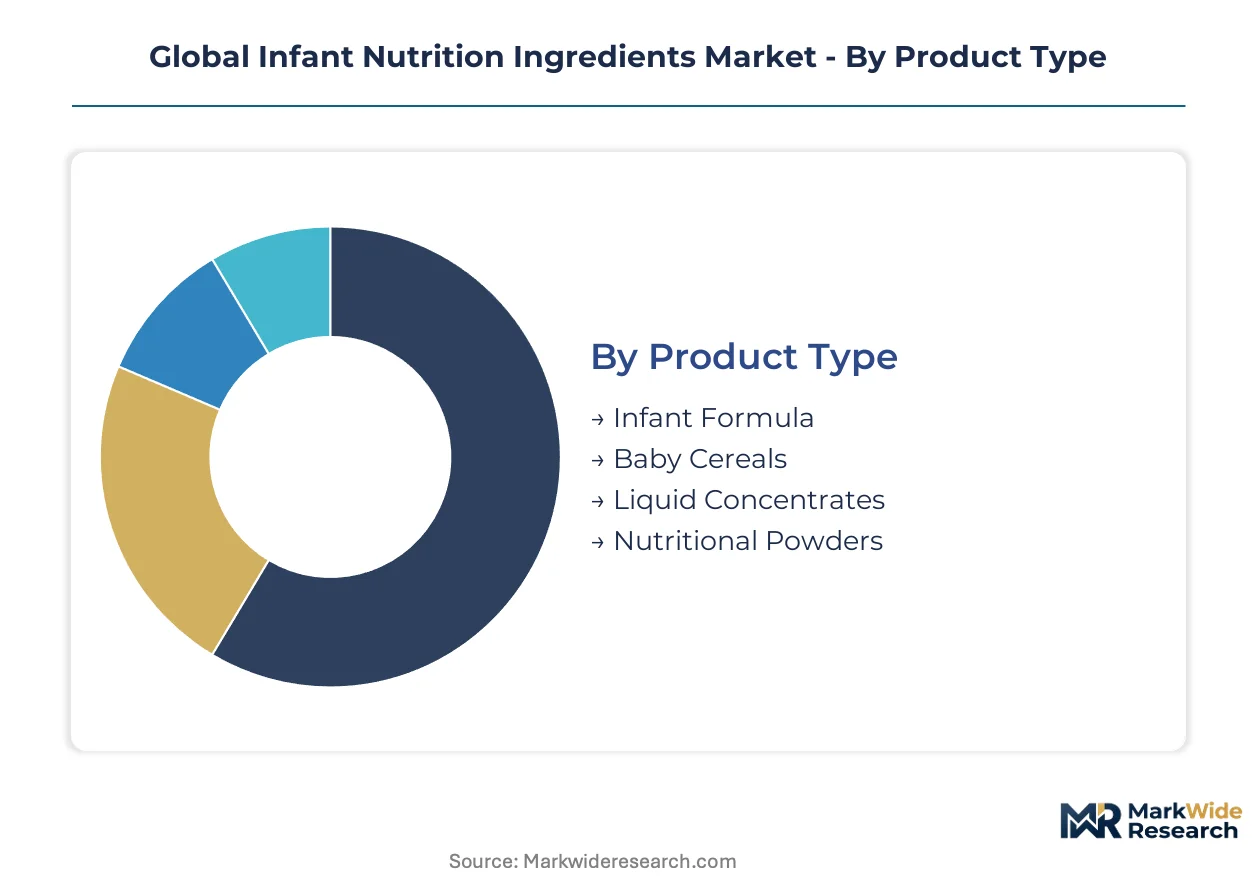
Segmentation in infant nutrition ingredients reveals how formulation requirements, distribution economics, and regulatory compliance intersect to shape supplier strategies. Powdered formats dominate volume throughput due to extended shelf stability, while ready-to-use liquids command premium positioning in hospital neonatal intensive care units. Understanding these divides enables ingredient producers to align thermal stability specifications and particle engineering capabilities with precise customer procurement criteria.
Product Type:
Cost tier differentiation across product categories determines margin capture and regulatory burden for ingredient suppliers, with premium formulations requiring specialized bioactive fortification.
- Infant Formula:Protein-lipid-carbohydrate blends matching human breast milk macronutrient ratios, typically manufactured through spray-drying to achieve 10-100 micron particle specifications. Demand concentrates in China's state-backed Inner Mongolia and Heilongjiang processing zones, where SAMR registration requirements restrict sourcing to approved domestic facilities.
- Baby Cereals:Iron-fortified grain bases requiring precise mineral dispersion and thermal stability during liquid reconstitution. European and North American markets drive clean-label and organic certification requirements, tightening heavy metal thresholds beyond Codex Alimentarius baselines.
- Liquid Concentrates:Pre-diluted formulations reducing preparation errors in clinical settings.
- Nutritional Powders:Modular fortification systems for compounding applications.
Infant formula commands the established base. The steepest expansion runs through liquid concentrates.
Form:
Application context dictates form selection, with hospital procurement prioritizing clinical safety and retail channels optimizing logistics economics.
- Powdered:Dominant volume format leveraging extended shelf stability and lower transportation costs through reduced water weight. Production gravity centers on Oceania's cooperative dairy structures, where Fonterra anchors whey protein concentrate exports through vertically integrated supply chains.
- Ready-to-Use:Sterile liquid formats eliminating reconstitution errors in neonatal intensive care units. North American hospital networks are consolidating supplier relationships around full-service portfolios, displacing fragmented single-category vendors.
- Liquid:Intermediate dilution states requiring refrigerated distribution infrastructure.
- Granular:Rapid-dissolve formats for convenience-oriented feeding systems.
Powdered formats retain volume leadership. The fastest climb occurs in ready-to-use liquids.
Source:
Supply concentration and technical maturity vary sharply across origin categories, determining formulation flexibility and allergen management capabilities.
- Animal-Based:Whey and casein fractions from bovine dairy retaining structural dominance through complete amino acid profiles and established hydrolysis protocols. Germany and Netherlands specialty manufacturers are scaling procurement of whey protein hydrolysates as EFSA novel food pathways accelerate bioactive deployment.
- Plant-Based:Pea and rice protein alternatives gaining share in allergen-managed product lines despite incomplete amino acid profiles requiring expensive blending. India's FSSAI labeling evolution creates first-mover advantage for suppliers with pre-certified allergen documentation.
- Synthetic:Precision fermentation platforms producing omega-3 fatty acids independent of marine supply chains.
- Others:Emerging microbial and algae-derived lipid sources.
Animal-based sources anchor current production. Synthetic biology platforms are gaining share fastest.
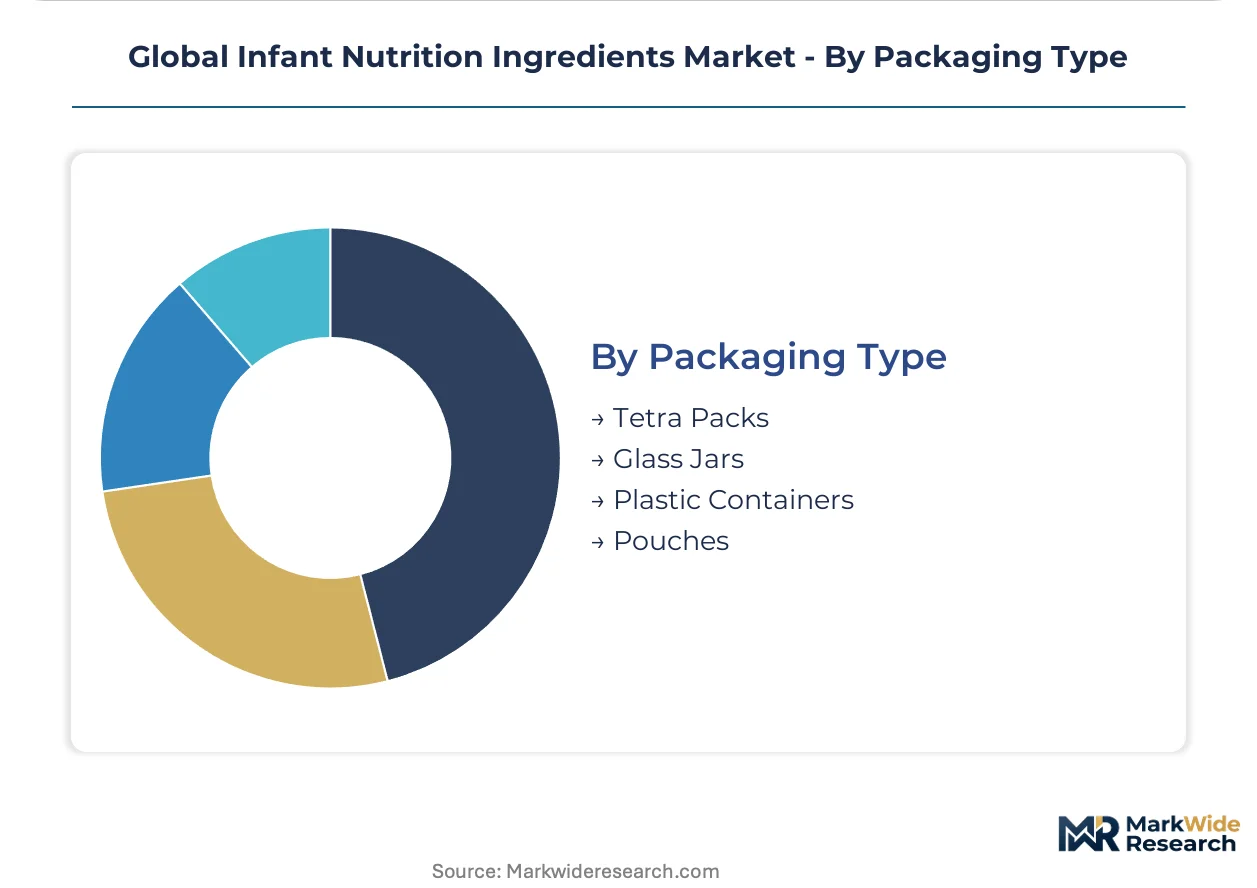
Packaging Type:
Customer type and distribution channel determine packaging selection, with convenience retail and hospital procurement imposing divergent sterility and portability requirements.
- Tetra Packs:Aseptic carton systems dominating liquid format distribution through multi-layer barrier protection and ambient storage compatibility. European retailers favor this format for ready-to-use products targeting convenience-oriented parents.
- Glass Jars:Premium positioning for organic and clean-label powders, particularly in German and Dutch markets where consumer perception favors inert packaging materials.
- Plastic Containers:Cost-optimized dry powder storage with resealability features.
- Pouches:Single-serve portability formats expanding in travel and institutional channels.
Tetra packs hold the volume base. Pouches are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Whey protein concentrate exports flow predominantly through Oceania's cooperative structures, while state-backed processing zones in China's northern provinces are capturing domestic ingredient demand. Divergent regulatory timelines across FDA, EFSA, and SAMR jurisdictions are fragmenting supplier certification requirements.
China
Inner Mongolia and Heilongjiang provinces host state-invested dairy processing clusters where SAMR facility registrations restrict foreign supplier access. GB standards for infant formula impose stricter heavy metal thresholds than Codex Alimentarius baselines, forcing domestic retrofitting ahead of import competition. Heilongjiang production lines are upgrading microbiological surveillance systems to capture premium formulation contracts.
United States
Hospital neonatal intensive care networks are consolidating procurement around full-service ingredient portfolios spanning proteins, lipids, and bioactives. FDA GRAS petitions and food additive notifications govern premarket ingredient authorization, creating multi-year registration timelines. Midwest dairy processing regions retain concentrated spray-drying expertise for 10-100 micron particle specifications.
Germany
Specialty formula manufacturers are scaling whey protein hydrolysate procurement as EFSA novel food pathways accelerate bioactive deployment. EFSA's 2'-fucosyllactose authorization framework tightens purity documentation requirements for human milk oligosaccharide suppliers. Bavarian and North Rhine-Westphalian ingredient compounders are expanding enzymatic hydrolysis capacity for hypoallergenic product lines.
Netherlands
Premium organic and clean-label formulation demand concentrates in Dutch retail channels, tightening heavy metal and contaminant thresholds beyond EU baselines. EFSA novel food assessments for bioactive carbohydrates extend registration timelines for non-EU suppliers. Friesland and Gelderland dairy clusters are vertically integrating into specialized milk fat globule membrane production.
India
FSSAI labeling mandates for allergen declaration and fortification content are creating first-mover advantage for suppliers with pre-certified documentation systems. Formula ingredient imports face tightened customs scrutiny on purity certification. Maharashtra and Gujarat dairy processing zones are developing domestic whey fraction capabilities to reduce import dependency.
Global Infant Nutrition Ingredients Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in protein fractionation and lipid synthesis. The supplier base organizes around three archetypes: diversified nutrition conglomerates with full-service portfolios, dairy cooperative structures with captive whey supplies, and synthetic biology platforms producing microbial lipids. Consolidation pressures are intensifying through hospital procurement centralization and multi-jurisdiction registration cost burdens. Competitive moves cluster on backward integration into dairy processing and precision fermentation capacity expansion.
Among diversified nutrition conglomerates, Koninklijke DSM N.V. and BASF SE occupy positions spanning vitamin fortification and microbial lipid synthesis. Fonterra Co-operative Group Ltd. exemplifies the cooperative archetype with vertically integrated Oceania dairy supply chains. These three entities represent distinct strategic positions: DSM and BASF anchor biotechnology-enabled ingredient platforms, while Fonterra exemplifies raw material backward integration from pasture to processing.
| Leading Market Players |
|---|
| Koninklijke DSM N.V. |
| BASF SE |
| Cargill Inc. |
| Fonterra Co-operative Group Ltd. |
| Arla Foods amba |
| Royal FrieslandCampina N.V. |
| Glanbia plc |
| AAK AB |
| Lactalis Ingredients |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Oceania's whey protein concentrate facilities is compressing spot pricing for standard-grade ingredients while tightening premiums for SAMR-certified supply chains into China. This utilization asymmetry rewards backward-integrated cooperatives with captive milk supplies while forcing merchant processors into extended payment concessions to defend volume commitments.
Pricing Analysis
EFSA novel food authorization pathways dictate the pricing tier structure for bioactive carbohydrates, separating premium 2'-fucosyllactose grades from unapproved commodity lactose. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, with SAMR-registered Chinese facilities commanding 15-20% premia over uncertified competitors. Cost compression in standard whey fractions is intensifying because Fonterra's cooperative structure limits alternative sourcing during seasonal peaks. Hospital procurement teams exhibit the lowest price sensitivity due to formulary standardization requirements, while private-label retail manufacturers face acute margin pressure from ingredient purity mandates.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are emerging as the dominant supplier-financing mechanism among European specialty formula manufacturers facing EFSA registration backlogs. Geographic supply concentrates in New Zealand, Germany, and the Netherlands, with Heilongjiang province capturing state-backed investment for domestic substitution. Raw material dependencies center on bovine whey fractions, marine-derived omega-3 oils, and enzymatic hydrolysis inputs. Single-source vulnerability runs through Oceania's cooperative dairy structures, which control 70% of global whey protein concentrate exports. Distribution runs through vertically integrated ingredient compounders serving hospital networks and retail manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where SAMR facility registrations and EFSA novel food approvals create switching costs that entrench incumbent positions. Network effects concentrate in hospital procurement consolidation around full-service ingredient portfolios.
For Market Incumbents: Harden defensive positioning through captive supply of SAMR-certified whey fractions in Heilongjiang and Inner Mongolia processing zones. Expand enzymatic hydrolysis capacity in Bavaria and North Rhine-Westphalia to capture EFSA-driven demand for hypoallergenic proteins. Precision fermentation platforms for microbial lipids represent the primary substitution threat requiring pre-emptive R&D allocation. For New Entrants and Emerging Players: India's FSSAI labeling evolution represents the most penetrable entry point for suppliers with pre-certified allergen documentation systems. Direct-to-hospital distribution in North American neonatal intensive care networks bypasses wholesale margin capture. Synthetic biology platforms producing omega-3 fatty acids independent of marine supply chains offer the clearest go-to-market differentiation against entrenched dairy cooperatives. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation capacity for microbial lipid production. Long-term viability over the next decade hinges on regulatory entrenchment through multi-jurisdiction registration portfolios. Acquisition targets should prioritize mid-scale ingredient compounders with existing SAMR facility approvals and EFSA novel food dossiers. The signal to monitor is EFSA authorization velocity for bioactive carbohydrates, which determines premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial cell factories eliminate fish oil dependency for DHA and ARA omega-3 production. |
| SAMR Facility Registration | Approved domestic status in Heilongjiang unlocks China's state-backed procurement channels. |
| Enzymatic Hydrolysis Expansion | Specialized protease capacity in Germany captures EFSA-driven hypoallergenic formula demand. |
| Direct-to-Hospital Distribution | Bypassing wholesale channels captures margin from consolidated North American NICU procurement. |
| EFSA Novel Food Dossier Investment | 2'-fucosyllactose authorization creates premium pricing tier for human milk oligosaccharide suppliers. |
Methodological Framework
A spread of perspectives from regulatory affairs directors at infant formula manufacturers, procurement managers at hospital neonatal networks, and technical directors at dairy processing cooperatives converged on the working assumptions. Primary interviews combined with secondary validation from FDA GRAS filings, EFSA novel food assessments, SAMR registration databases, and Fonterra cooperative disclosure documents. Bottom-up volume modeling across ingredient categories triangulated against top-down market sizing from customs trade flows and dairy cooperative export data.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, form, source origin, and packaging configuration alongside regional regulatory cluster alignment. CAGRs were derived from growth driver elasticity analysis and substitution scenario testing. Forecast inputs incorporated EFSA authorization timelines for bioactive carbohydrates and SAMR facility audit queue lengths as structural constraints.
Stress conditions across regulatory approval delays, whey protein concentrate supply disruptions, and precision fermentation yield variability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about registration pathway efficiency and cooperative supply stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Liquid Feed Market
Ingredients
Centella Asiatica Extract Market
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Textured Soy Flour Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Protein Trends and Technologies Market
Ingredients
Roasted Grain Ingredients Market
Ingredients
Protein Ingredients Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
Vital Wheat Gluten Market
Ingredients
PHO Oils Market
Ingredients
Corn Peptide Market
Ingredients
Soy Derivatives Market
Ingredients
Plant Sterols and Esters Market