
 Europe Protein Market | 2026-2036
Europe Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Protein Market Foresight
Precision fermentation is reshaping how alternative proteins achieve functional parity with animal-derived isolates. Roquette Frères leverages its plant-protein extrusion expertise to supply European food manufacturers. Kerry Group anchors its position through integrated taste and nutrition systems. Cargill competes across both commodity soy and emerging pea protein streams.
Europe protein encompasses amino acid chains derived from dairy, legume, and microbial biomass, typically processed through membrane filtration, enzymatic hydrolysis, or dry fractionation to achieve specific protein content, dispersibility, and digestibility scores for human consumption or animal nutrition. Whey protein retains dominance in sports nutrition due to superior leucine bioavailability, while pea protein captures expansion in allergen-free and vegan-positioned formulations. Application through dietary supplements commands premium margin pools, whereas animal feed represents a volume-driven, price-sensitive segment.
EFSA governs novel food approvals for fermentation-derived and insect proteins entering European commerce. REACH and the EU Green Deal impose carbon footprint disclosure and deforestation-free sourcing requirements on soy and dairy supply chains. The F-Gas Regulation indirectly affects cold-chain protein processing costs. Stakeholders must monitor how ECHA substance evaluations and evolving CSRD scope-three reporting obligations will reshape supplier qualification criteria and capital allocation across the value chain.
Market Dynamics
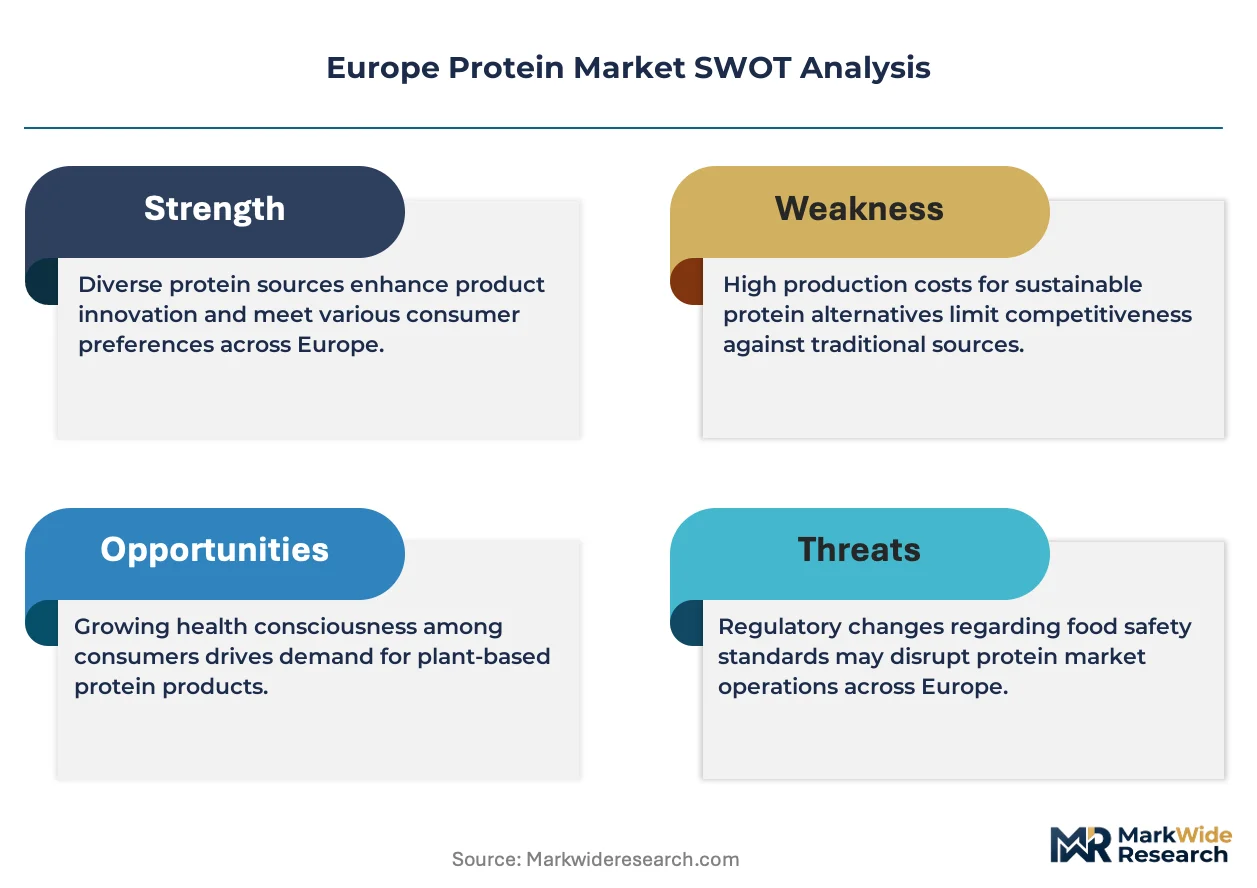
The EU Green Deal and Farm-to-Fork Strategy are forcing protein suppliers to requalify every input source against deforestation-free and carbon-accounting standards, compressing margins for commodity traders while advantaging precision fermentation operators with auditable supply chains.
Growth Catalysts
- CSRD Scope-Three Mandates:Large food manufacturers must now disclose upstream agricultural emissions, creating procurement preference for proteins with verified lifecycle data and traceable farm origins.
- Sports Nutrition Formulation:Athlete-specific positioning drives demand for leucine-optimized isolates and rapid-digestion hydrolysates in ready-to-drink formats across German and Dutch processing clusters.
- Precision Fermentation Scale-Up:Microbial biomass production achieves cost parity with whey isolates for select functional applications, opening formulation access to vegan-positioned brands.
Market Restraints
- Input Cost Volatility:Yellow pea and fava bean prices fluctuate with Black Sea grain flows and Canadian harvest yields, compressing margin predictability for European fractionation operators.
- Regulatory Friction:EFSA novel food approvals for fermentation-derived and insect proteins impose 18-24 month validation timelines, freezing commercial launch schedules for biotech entrants.
- Substitution Threat:Whole-food protein sources and minimally processed legumes capture clean-label preference segments, limiting isolate growth in certain retail categories.
Strategic Opportunities
- Poland and Romania Processing:Underdeveloped extrusion and texturization capacity in Eastern European markets creates first-mover advantage for regional ingredient manufacturing.
- Clinical Nutrition Applications:Medical food and elderly nutrition segments remain underpenetrated by alternative proteins, offering premium pricing for high-digestibility formulations.
- Green Public Procurement:EU member state catering contracts increasingly mandate sustainable protein quotas, creating institutional demand pull for certified suppliers.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:European universities produce insufficient fermentation specialists and downstream processing engineers to staff scaling precision protein facilities.
- Legacy Dairy Infrastructure Lock-In:Existing whey fractionation plants require costly retrofitting to handle alternative feedstocks, slowing capital redeployment toward plant-protein streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Protein Market |
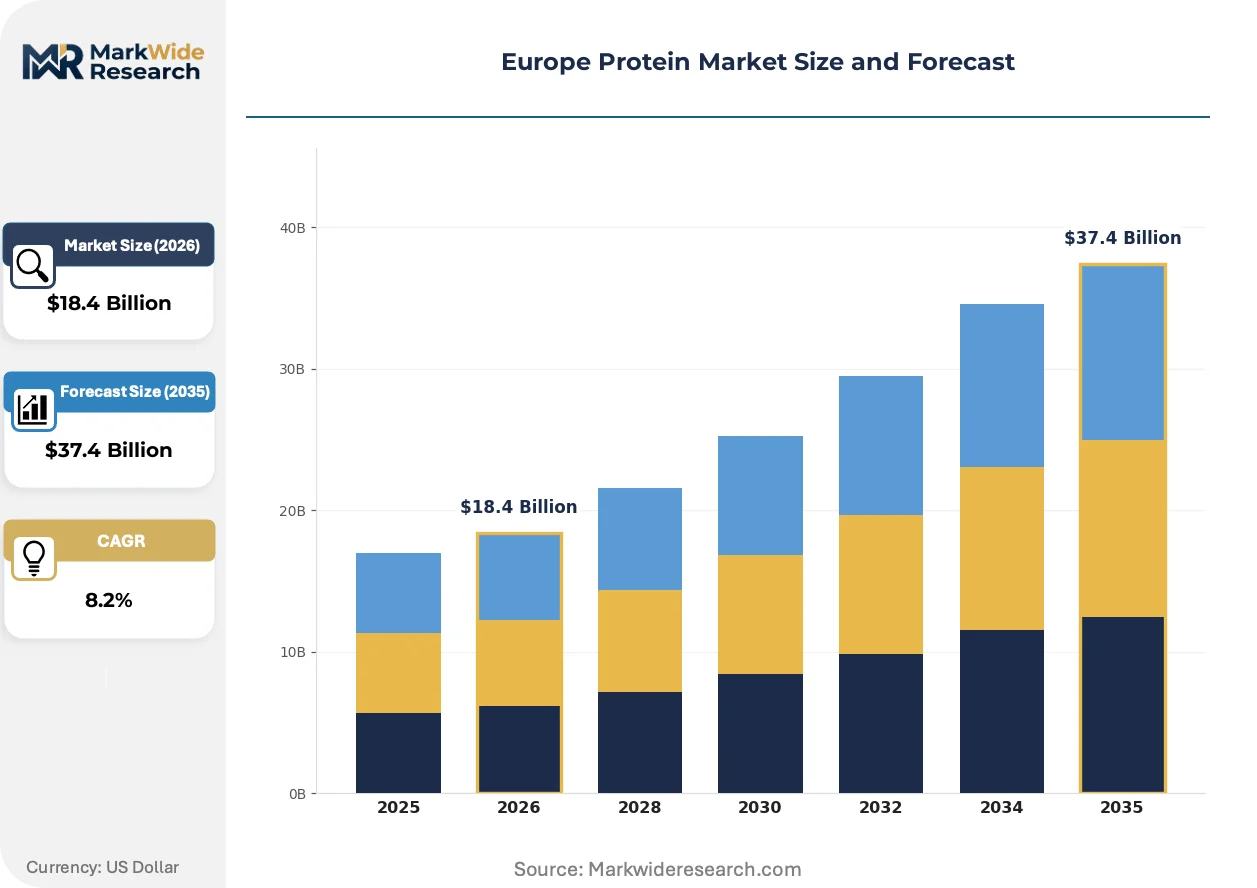
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $37.4 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein Application: Food & Beverage, Dietary Supplements, Animal Feed, Nutraceuticals End User: Health-Conscious Consumers, Athletes, Bodybuilders, Elderly Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | Arla Foods, Royal FrieslandCampina, Archer Daniels Midland Company, Roquette Frères, Kerry Group, Fonterra Co-operative Group, Cargill, Glanbia, Lactalis Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Protein Market Shifts & Advancements
Protein functionality is separating from animal agriculture through bioprocess engineering advances, regulatory carbon accounting, and shifting procurement criteria that reward traceability over commodity sourcing.
Precision fermentation of dairy-identical proteins is rendering obsolete the traditional whey and casein supply chain for specific high-value applications. Specialty nutrition brands in the Netherlands and Denmark are accelerating adoption of these isolates for infant formula and medical nutrition. The technology compresses the supplier base toward biotech licensors with proprietary strain libraries and GMP-compliant manufacturing assets.
REACH substance evaluations and evolving CSRD disclosure obligations are tightening supplier qualification protocols across European food manufacturing. Chemical hazard assessments now extend to processing aids and extraction solvents used in protein isolation. Mid-tier ingredient traders face exclusion from qualified vendor lists as major processors consolidate procurement toward vertically integrated partners with dedicated compliance teams.
Formulation R&D teams are shortening ingredient approval cycles and demanding application-specific performance guarantees from protein suppliers. Sports nutrition brands in Germany now specify dispersibility, foam stability, and flavor masking in procurement contracts rather than accepting standard technical datasheets. This behavior concentrates purchasing power among technical service-oriented suppliers with in-house pilot plants and sensory evaluation capabilities.
Europe Protein Market Segmentation
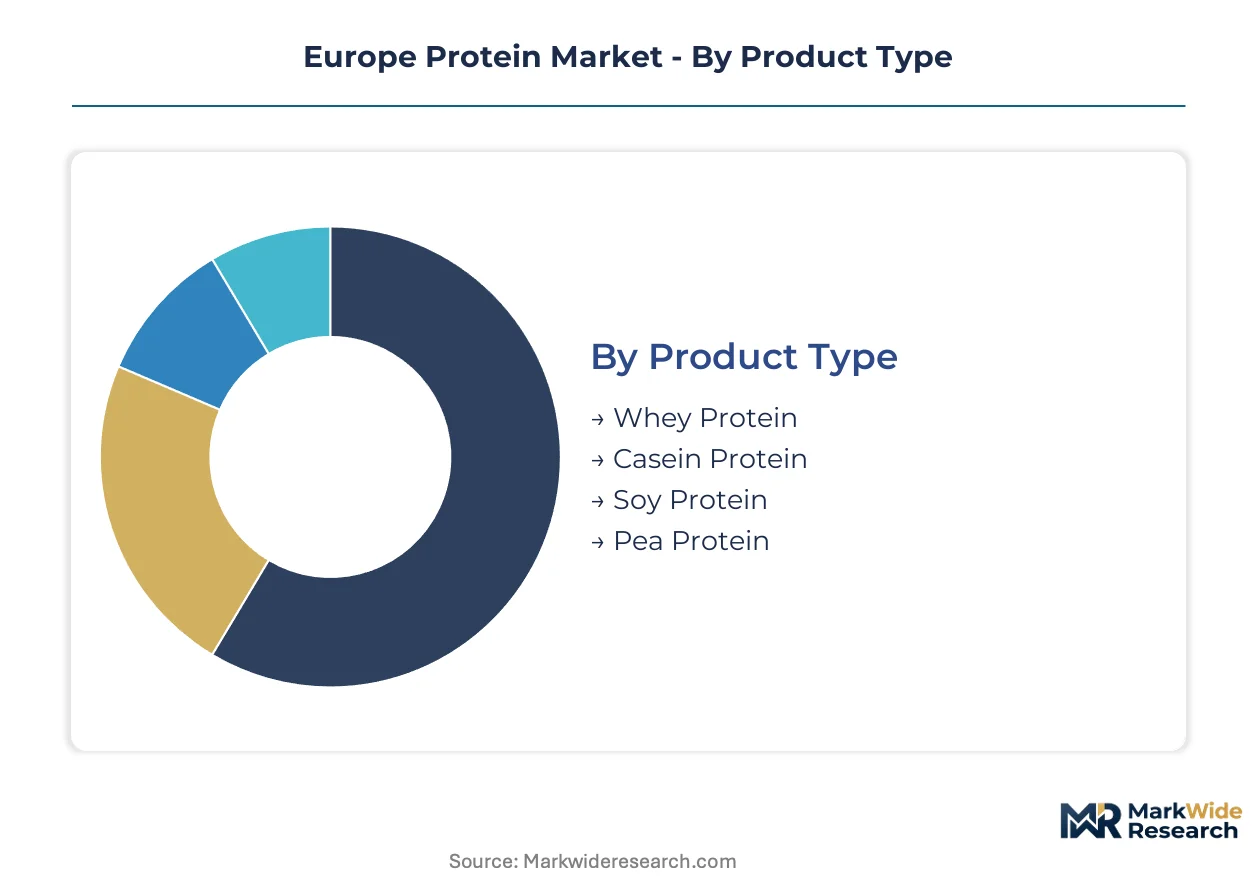
Protein segmentation in Europe reflects divergent technical requirements across sports performance, clinical nutrition, and mass-market food applications. Procurement cycles vary dramatically: sports nutrition brands refresh formulations quarterly, while animal feed contracts lock in annual volumes. Understanding these velocity differences shapes supplier resource allocation and inventory strategy.
Product Type:
Inventory velocity separates these segments. Whey and casein proteins turn over fastest through sports nutrition channels, while plant proteins face longer adoption curves in reformulation pipelines.
- Whey Protein:Rapid-digestion isolates and concentrates derived from cheese manufacturing byproduct, standardized to 80-90% protein content with specified leucine thresholds. German and Dutch sports nutrition clusters drive procurement of hydrolyzed variants for post-workout applications, constrained by dairy herd size limits and volatile milk powder export demand.
- Pea Protein:Dry-fractionated isolates from yellow and fava beans, achieving 85% protein content with improved dispersibility through recent extrusion advances. French and Dutch vegan-positioned brands accelerate adoption, though Black Sea supply disruptions and Canadian harvest variability create margin compression for European fractionators.
- Casein Protein:Slow-digesting micellar structures prized for overnight recovery formulations and medical nutrition applications. Italian and French dairy processors dominate supply, with longer production cycles tied to curd separation timelines.
- Soy Protein:Isolates and concentrates from defatted soybean meal, facing EUDR deforestation-free documentation requirements that extend procurement lead times. Spanish and German food manufacturers retain volume demand for meat analog applications despite clean-label substitution pressure.
Whey protein dominates installed base. Pea protein is where expansion concentrates.
Application:
Margin architecture varies sharply across these demand pools. Dietary supplements capture premium pricing through branded positioning, while animal feed operates on commodity-thin returns.
- Dietary Supplements:Powder and ready-to-drink formats targeting athlete recovery and lean mass preservation, commanding formulation premiums for leucine-optimized and rapid-absorption variants. German contract manufacturers and Dutch brand houses concentrate demand, with EFSA health claim restrictions limiting marketing vocabulary.
- Food & Beverage:Bakery, dairy alternative, and meat analog applications requiring functional properties including emulsification, gelation, and water binding. French and Spanish plant-based food startups drive pea and fava protein adoption, constrained by sensory masking challenges and clean-label formulation requirements.
- Nutraceuticals:Medical food and elderly nutrition segments requiring high digestibility scores and amino acid completeness for sarcopenia management. Underpenetrated by alternative proteins, creating premium pricing opportunity for fermentation-derived isolates with clinical validation.
- Animal Feed:Soy and rapeseed meal proteins for poultry and swine nutrition, price-sensitive and volume-driven with procurement tied to commodity futures. Polish and Romanian compound feed producers represent regional demand concentration.
Food and beverage dominates installed base. Dietary supplements is where expansion concentrates.
End User:
Customer sophistication determines technical service intensity and pricing power. Athletes demand performance verification, while elderly nutrition requires clinical substantiation.
- Athletes:Competitive and recreational performers prioritizing leucine content, digestion speed, and batch-tested certification for banned substance absence. UK and German triathlon and strength sport communities drive premium isolate demand through specialized retail and coaching networks.
- Health-Conscious Consumers:Mass-market buyers seeking convenient protein fortification for weight management and general wellness. Scandinavian and Dutch supermarket channels concentrate demand for clean-label, allergen-free positioning.
- Bodybuilders:Dedicated hypertrophy-focused users consuming high daily protein loads with specific timing protocols. UK and German gym-affiliated supplement retailers serve this segment with bulk-format concentrates and flavor variety.
- Elderly:Aging populations requiring high-quality protein for muscle preservation and functional mobility, often in medical food formats. German and Italian healthcare reimbursement systems influence product accessibility and formulation standards.
Athletes dominate installed base. Health-conscious consumers is where expansion concentrates.
Distribution Channel:
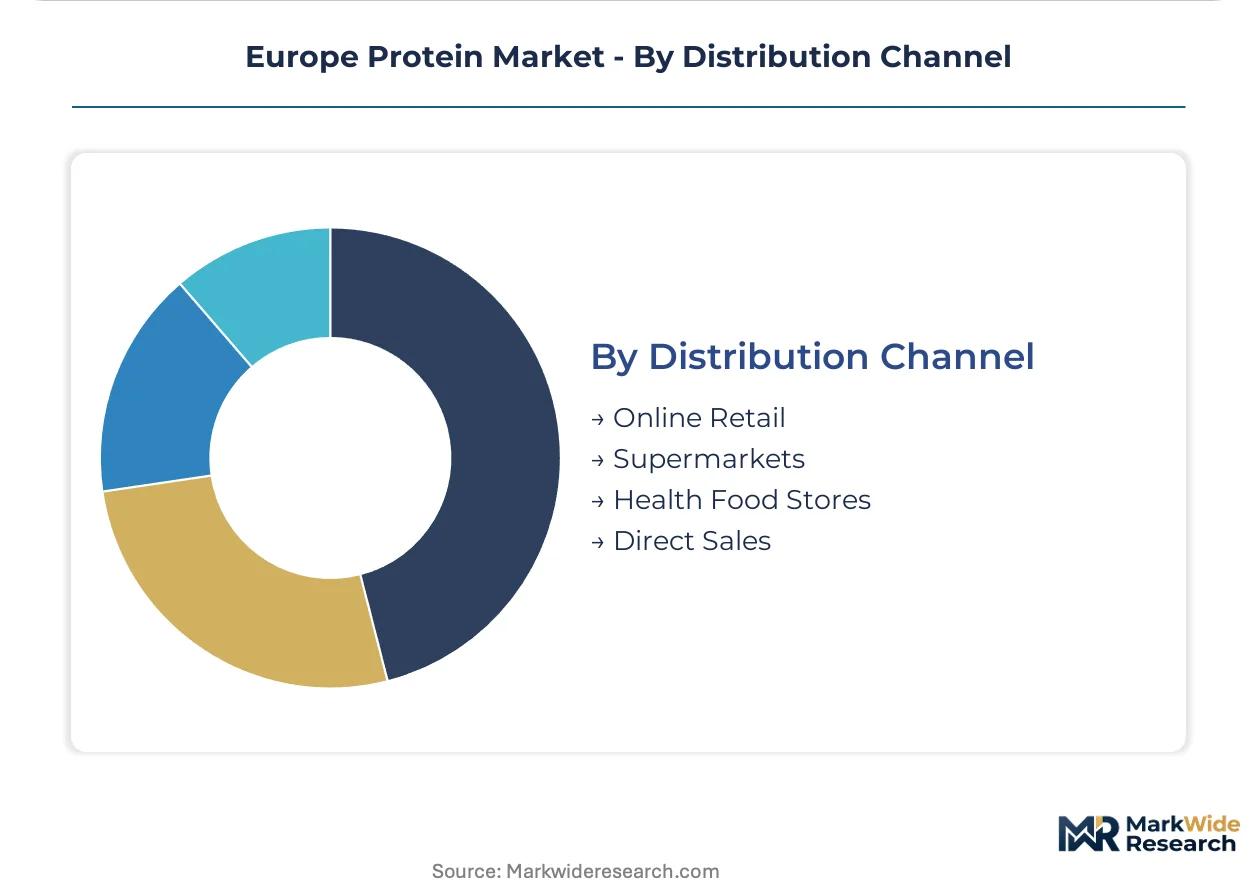
Channel economics reflect customer acquisition costs and loyalty dynamics. Direct relationships yield highest lifetime value, while mass retail demands promotional investment.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription models and personalized nutrition algorithms. UK and German consumers drive highest per-capita spending, with Dutch fulfillment infrastructure supporting cross-border logistics.
- Supermarkets:Mass-market penetration for protein-fortified foods and basic supplement formats, requiring slotting fees and promotional support. French and Spanish retail consolidation limits supplier negotiation leverage.
- Health Food Stores:Specialty retail emphasizing organic, non-GMO, and local sourcing credentials with trained staff consultation. German Reformhaus and Scandinavian independent networks retain loyal customer bases despite online competition.
- Direct Sales:Practitioner and clinical channels for medical nutrition, plus network marketing for lifestyle brands. Italian and Spanish markets maintain stronger direct sales penetration than northern Europe.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Netherlands-based ingredient processors export precision fermentation-derived isolates to German sports nutrition manufacturers, creating a concentrated trade corridor that channels advanced protein technologies across the Rhine-Ruhr industrial belt.
Germany
Rhine-Ruhr contract manufacturers drive demand for hydrolyzed whey isolates and rapid-digestion formulations tailored to strength sport athletes. The German Supply Chain Due Diligence Act mandates deforestation-free documentation for imported soy and pea protein feedstocks. Bavarian dairy processors operate Europe's largest whey fractionation capacity, though retrofitting timelines lag plant-protein expansion needs.
Netherlands
Rotterdam and Amsterdam harbor zones concentrate precision fermentation scale-up facilities serving infant formula and medical nutrition brands. Dutch implementation of EU Green Deal carbon accounting rules accelerates procurement preference for lifecycle-verified proteins. Wageningen University clusters anchor bioprocess engineering talent pipelines for microbial biomass production.
France
Parisian plant-based food startups and Lyon-based dairy processors compete for pea protein isolates with improved dispersibility profiles. French REACH enforcement through ANSM tightens chemical hazard assessments for protein extraction solvents. Roquette Frères operates extrusion facilities in Lestrem supplying European meat analog manufacturers.
United Kingdom
London and Manchester direct-to-consumer brands drive online retail velocity for allergen-free protein formulations targeting triathlon and obstacle course racing communities. UK post-Brexit divergence from EFSA novel food timelines creates regulatory friction for fermentation-derived protein entrants. Cambridge biotech clusters develop strain libraries for dairy-identical protein production.
Italy
Emilia-Romagna and Lombardy dairy cooperatives dominate micellar casein supply for overnight recovery and medical nutrition applications. Italian implementation of CSRD scope-three disclosure rules forces feedstock traceability upgrades across Parmesan and mozzarella supply chains. Bologna processing clusters specialize in slow-release protein matrices for elderly sarcopenia management.
Europe Protein Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. Dairy cooperative conglomerates anchor whey and casein supply through captive milk sourcing relationships. Ingredient technology firms occupy precision fermentation and plant-protein extrusion niches. Competitive moves concentrate on backward integration into feedstock sourcing and application-specific technical service capabilities.
Within the integrated dairy processor tier, Arla Foods, Royal FrieslandCampina, and Fonterra Co-operative Group exemplify cooperative structures leveraging member-farm milk flows. These entities occupy positions where scale advantages in whey fractionation encounter pressure from plant-protein substitution trends. Kerry Group and Roquette Frères represent the ingredient technology archetype, anchoring formulation partnerships with European brand manufacturers through integrated taste and nutrition systems. Cargill and Glanbia sit at the commodity-specialist intersection, spanning both traditional soy supply chains and emerging pea protein streams.
| Leading Market Players |
|---|
| Arla Foods |
| Royal FrieslandCampina |
| Archer Daniels Midland Company |
| Roquette Frères |
| Kerry Group |
| Fonterra Co-operative Group |
| Cargill |
| Glanbia |
| Lactalis Group |
| Others |
Supply & Pricing Matrix
Black Sea grain flow disruptions determine both the spread between premium and commodity protein tiers and the geographic configuration of European fractionation capacity. Input cost volatility from Ukrainian and Canadian pulse harvests compresses margin predictability for plant-protein operators while concentrating pricing power among dairy processors with captive whey streams.
Pricing Analysis
The technology-generation pricing gap between precision fermentation isolates, conventional whey fractions, and commodity soy concentrates structures procurement negotiations across European food manufacturing. Three-tier pricing stratification separates clinical-grade microbial biomass from standard dairy isolates and economy-positioned legume proteins. Price differentiation hinges on EFSA novel food certification status and verified carbon footprint documentation under CSRD scope-three rules. Pricing pressure stems from Black Sea supply disruptions inflating yellow pea and fava bean input costs. Animal feed buyers exhibit highest price sensitivity, while medical nutrition and infant formula segments absorb premium positioning with limited volume elasticity.
Supply Chain Analysis
Tariff exposure between Canada and EU member states dominates risk planning for pea protein fractionators dependent on North American pulse imports. Geographic supply concentration centers on Germany, the Netherlands, and France for dairy-derived proteins, with Canadian and Ukrainian fields anchoring plant-protein feedstocks. Raw material dependencies include whey permeate from cheese manufacturing, yellow pea and fava bean crops, and fermentation feedstocks for microbial biomass production. Single-source vulnerability from concentrated Black Sea grain corridors threatens margin stability for Roquette Frères and competing fractionators. Distribution runs through Rotterdam harbor zones for precision fermentation outputs, Rhine-Ruhr contract manufacturers for sports nutrition, and Parisian plant-based food clusters for meat analog applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe protein market sits in an input-cost cyclical trough driven by Black Sea supply normalization and Canadian harvest recovery, positioning procurement-heavy players for margin expansion as commodity volatility moderates.
For Market Incumbents: Harden defensible positions by retrofitting Bavarian whey fractionation plants for hybrid dairy-plant feedstock flexibility, neutralizing substitution threats from precision fermentation entrants. Secure captive supply of deforestation-free soy and pea proteins through backward integration into Ukrainian and Canadian origination networks ahead of EUDR documentation mandates. Invest in Wageningen-adjacent bioprocess engineering talent pipelines to staff scaling fermentation facilities. For New Entrants and Emerging Players: Clinical nutrition applications for elderly sarcopenia management represent the most penetrable white-space entry point, with medical food segments underpenetrated by alternative proteins and commanding premium pricing for high-digestibility formulations. Poland and Romania processing clusters offer regional manufacturing scale-up opportunities with underdeveloped extrusion capacity and proximity to compound feed demand. Pursue green public procurement certification to access EU member state institutional catering contracts mandating sustainable protein quotas. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors ingredient technology firms with proprietary strain libraries and GMP-compliant fermentation assets over commodity-trading intermediaries. Long-term viability over the coming decade rests on carbon-accounting infrastructure and EFSA regulatory navigation capabilities. Watch for CSRD scope-three disclosure acceleration as the inflection signal triggering procurement preference shifts toward lifecycle-verified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Rotterdam harbor facilities achieve cost parity with whey isolates for vegan-positioned medical nutrition brands. |
| Backward Integration into Pulse Origination | Direct Ukrainian and Canadian field relationships secure deforestation-free documentation required by EUDR compliance. |
| Hybrid Feedstock Retrofit | Bavarian dairy plants gain flexibility to process both whey permeate and plant-protein streams against substitution threats. |
| Green Public Procurement Certification | EU institutional catering contracts create volume anchors for certified sustainable protein suppliers. |
| Clinical Nutrition Validation | Medical food partnerships with Italian and German healthcare systems unlock premium pricing for high-digestibility formulations. |
Research Methodology
Cross-validation between executive interviews at Dutch precision fermentation scale-ups and German sports nutrition contract manufacturers anchors the qualitative findings. Primary fieldwork engaged protein ingredient procurement leads, EFSA regulatory affairs specialists, Wageningen bioprocess engineering faculty, and Rotterdam harbor logistics coordinators. Secondary sources included EFSA novel food approval databases, EU Green Deal implementation guidance, CSRD technical standards documentation, and customs trade data for pea and soy protein flows. Bottom-up volume modeling from fractionation capacity utilization triangulated against top-down demand estimates from sports nutrition and medical nutrition end-use segments.
Calibration against historical whey and plant-protein price series validated elasticity assumptions across the projection horizon. The analytical framework segmented demand by product type, application, end user, and distribution channel, with additional modeling of regulatory approval status for novel protein sources. CAGRs were derived from installed base penetration curves and substitution elasticity parameters. Forecast inputs incorporated EFSA approval timeline distributions, Black Sea supply disruption probability scenarios, and CSRD carbon accounting adoption rates.
Practitioners should monitor EFSA novel food approval acceleration, Ukrainian harvest recovery trajectories, and precision fermentation cost curves for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydrolyzed Oat Protein Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
US Choline Bitartrate Market
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
Elecampane Root Market
Ingredients
Lipids Market
Ingredients
Industrial Sugar Market
Ingredients
US Ingredients Market
Ingredients
Hydrogenated Starch Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
North America Collagen Ingredients Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
Interesterified Fats Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Roll-Dried Starch Market