
 Confectionery Ingredients Market | 2026-2036
Confectionery Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Confectionery Ingredients Market Analysis
West African cocoa processor capacity is hardening as grinderies expand throughput ahead of bean supply constraints. Cargill Incorporated leverages integrated bean-to-liquor operations across Côte d'Ivoire and Ghana to secure origin advantage. Barry Callebaut anchors European premium chocolate ingredient supply through specialized couverture and filling formulations. Olam International competes across origination, processing, and risk management for cocoa derivatives.
Confectionery ingredients comprise functional inputs—cocoa derivatives, sugars and sweeteners, emulsifiers, stabilizers, and flavor systems—formulated to specific particle size, viscosity, and tempering profiles that govern mouthfeel, shelf stability, and visual finish in finished sweets. Cocoa butter equivalents and lecithin emulsifiers typically require 34–36°C melting curves and 0.1% moisture ceilings to prevent fat bloom and texture degradation. Sugars and sweeteners command the largest value pool given volume throughput across chocolate, gummies, and hard candies, though emulsifiers and stabilizers capture disproportionate margin in premium and clean-label applications. Powder and liquid forms split by application viscosity requirements, with syrups dominating gummy manufacturing and granulated formats preferred for pan-coating operations.
EU EFSA and FDA frameworks govern maximum residue limits for heavy metals in cocoa, prop 65 thresholds for acrylamide in roasted ingredients, and GRAS status for novel sweeteners entering formulation pipelines. India's FSSAI enforces labeling and additive permissions that determine which imported emulsifier blends qualify for domestic confectionery production. Stakeholders must monitor evolving clean-label definitions across these jurisdictions, as regulatory divergence between permissive and precautionary standards will increasingly dictate supplier qualification costs and reformulation timelines.
Market Dynamics
Clean-label ingredient sourcing is restructuring supplier qualification across the confectionery ingredients sector, as EU EFSA additive tightening and parallel FDA scrutiny force reformulation cycles that favor vertically integrated processors with captive clean-label portfolios.
Growth Catalysts
- EU EFSA Additive Restrictions:Tightened approvals for synthetic colorants and emulsifiers are accelerating demand for natural alternatives in premium chocolate formulations across Western Europe.
- India Urban Bakery Expansion:Domestic chains and traditional mithai shops are scaling industrial procurement of cocoa derivatives and compound coatings to meet volume throughput targets.
- West African Processing Infrastructure:Expanded grindery capacity in Côte d'Ivoire and Ghana is shortening origin-to-liquor lead times for European couverture manufacturers.
Market Restraints
- Cocoa Butter Price Volatility:Bean supply constraints and speculative futures positioning are compressing margins for compound coating producers dependent on bulk cocoa butter equivalents.
- West African Origin Concentration:Over 70% of global cocoa bean supply originates from Côte d'Ivoire and Ghana, exposing processors to regional climate shocks and political disruption.
- Acrylamide Threshold Compliance:California Prop 65 litigation risk and EU benchmark levels for roasted nut and cocoa ingredients are forcing costly process retrofits on mid-tier suppliers.
Strategic Opportunities
- India FSSAI Clean-Label Window:Regulatory permission gaps for imported emulsifier blends create first-mover advantage for domestic compounders with approved natural stabilizer portfolios.
- Sugar Reduction Formulation:Novel sweetener GRAS petitions before FDA are opening reformulation partnerships between ingredient houses and North American sugar confectionery brands.
- Direct-to-Manufacturer Digital Sourcing:B2B platforms disintermediating traditional ingredient distributors are capturing share among mid-size European craft chocolate makers seeking lot-traceable cocoa.
Industry Challenges
- Clean-Label Reformulation Timelines:Compressed product development cycles to meet EU EFSA transition deadlines are straining R&D bandwidth at mid-tier ingredient houses.
- Integrated Traceability Architecture:Bean-to-bar blockchain verification and mass-balance certification systems require capital deployment that smaller African-origin processors cannot self-finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Confectionery Ingredients Market |
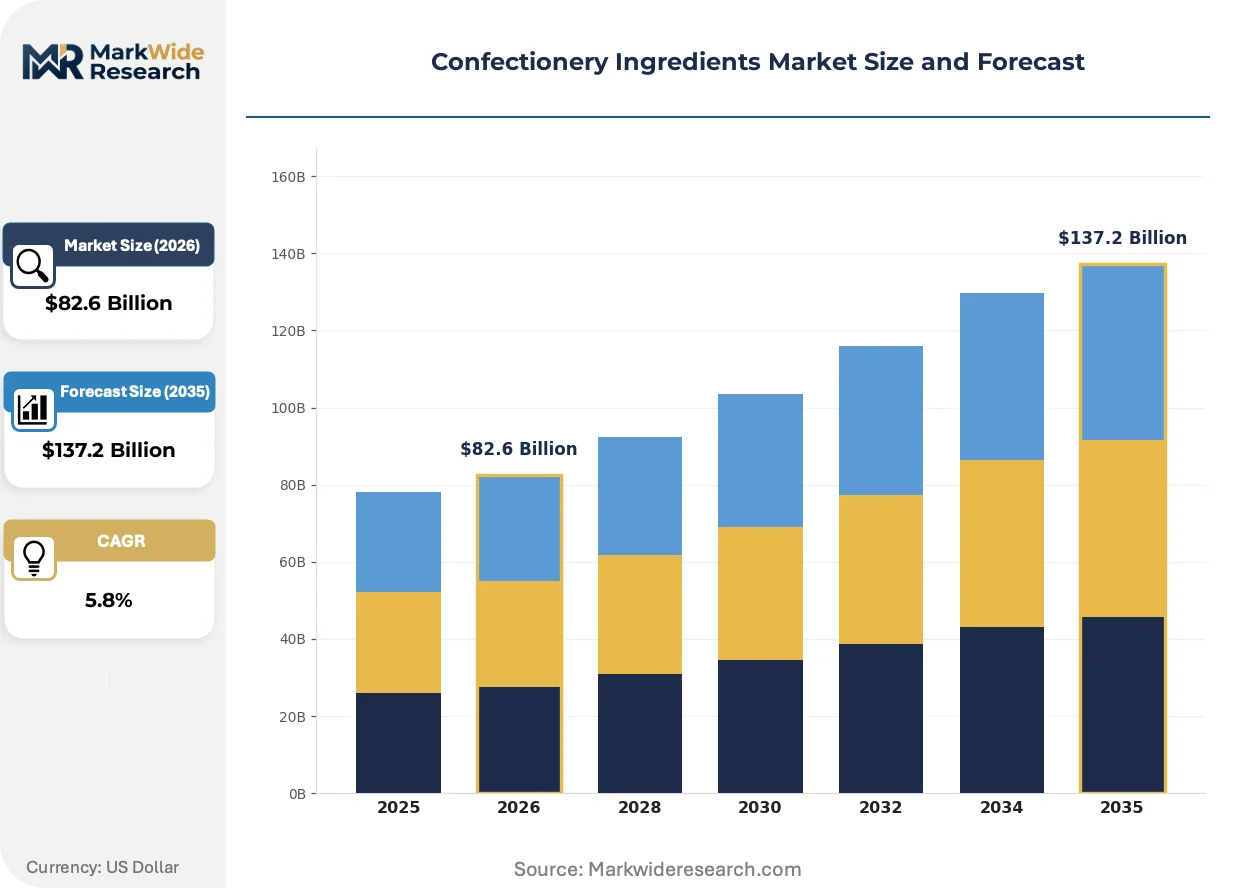
| Market Size in 2026 | $82.6 Billion |
| Market Size in 2035 | $137.2 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sugars, Sweeteners, Emulsifiers, Stabilizers Form: Powder, Liquid, Granulated, Syrup Application: Chocolate, Gummies, Hard Candies, Chewing Gums End User: Retail, Food Service, Bakery, Private Label |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Barry Callebaut, Tate & Lyle, Ingredion Incorporated, Kerry Group, Olam International, AAK AB, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Confectionery Ingredients Market Emerging Trajectories
Ingredient functionality is converging with sustainability verification and digital traceability, compressing the traditional separation between commodity supply and branded ingredient positioning. Three developments are restructuring competitive advantage.
Precision fermentation-derived cocoa butter alternatives are consolidating technical credibility in premium chocolate applications. Specialty couverture manufacturers in Belgium and Switzerland are adopting microbial lipid formulations at pilot scale. This technology is consolidating the addressable market for plant-based cocoa equivalents by matching crystallization behavior without agricultural land-use constraints.
EU EFSA's 2023-2025 re-evaluation cycle for food additives is tightening maximum residue limits for heavy metals in cocoa powders and liquors. European compound coating producers are reformulating supply bases to origin-verified low-cadmium bean programs. Premium chocolate segments in Germany and France are responding fastest, with clean-label certifications becoming mandatory for retail listing.
Urban bakery chains in Mumbai, Delhi, and Bangalore are consolidating procurement through centralized ingredient specifications rather than traditional spot-market purchasing. Regional distributors are losing share to direct mill relationships for bulk sweeteners and emulsifiers. This concentration is most visible in Western India, where industrial mithai producers are adopting chocolate enrobing at scale.
Confectionery Ingredients Market Segmentation
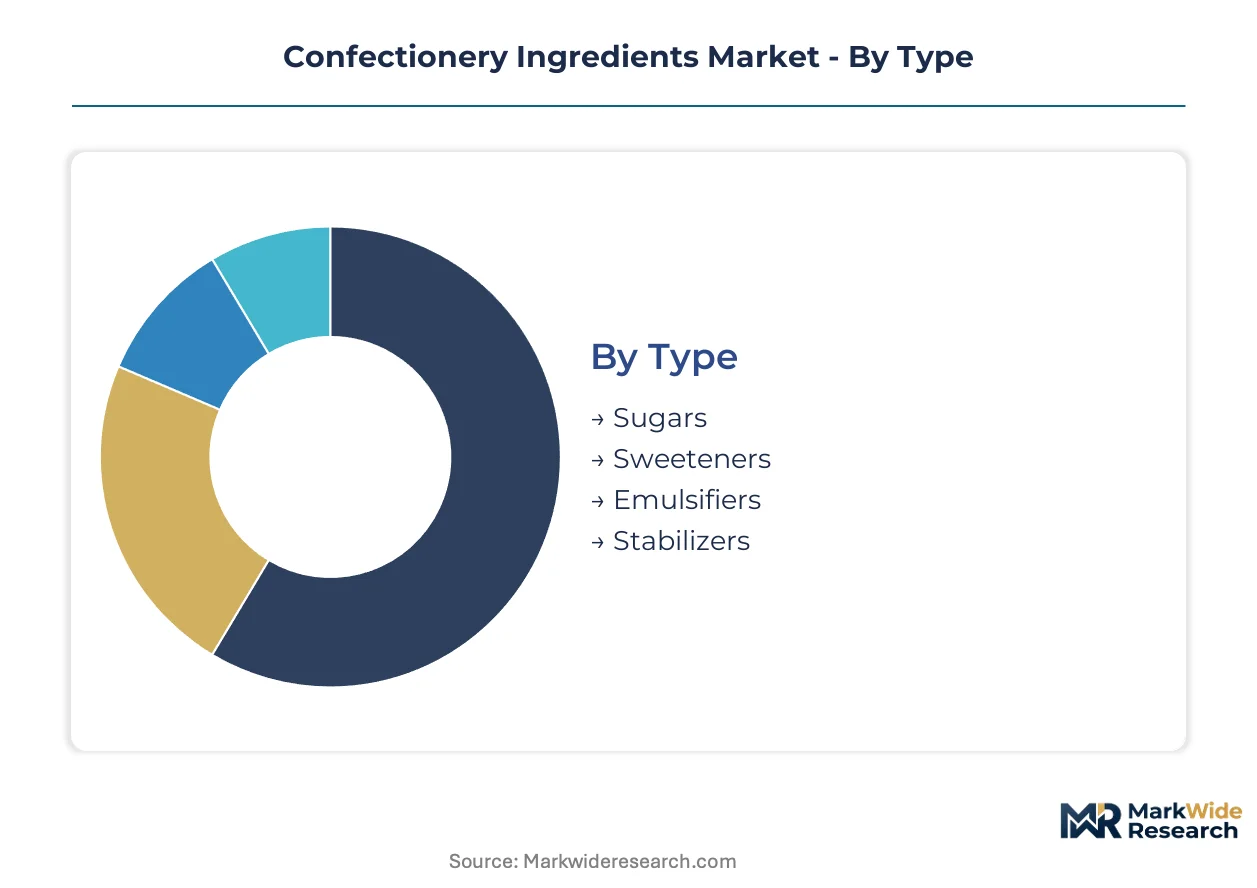
Ingredient specification varies dramatically across confectionery formats, with chocolate couverture demanding precise tempering profiles while gummy matrices require hydrocolloid stabilization. Segmentation reveals how procurement patterns split between commodity bulk inputs and specialized functional systems that command formulation partnerships.
Type:
Standardization dominates sugars and bulk sweeteners, while emulsifiers and stabilizers concentrate customization intensity around clean-label reformulation cycles.
- Sugars:Granulated sucrose and glucose syrups constitute the volume foundation across chocolate, hard candy, and pan-coating operations. Indian urban bakery chains and traditional mithai producers are consolidating bulk procurement through direct mill relationships rather than spot-market purchasing.
- Sweeteners:Novel polyol and high-intensity formulations are displacing sucrose in sugar-reduction pipelines, with FDA GRAS petitions determining which entrants qualify for North American formulation partnerships. Maltitol and erythritol blends dominate functional candy applications where cooling effects and laxation thresholds govern acceptability.
- Emulsifiers:Lecithin and polyglycerol polyricinoleate (PGPR) manage viscosity and fat bloom resistance in chocolate systems. EU EFSA additive re-evaluations are forcing origin-verified low-cadmium sourcing for lecithin derived from cocoa processing streams.
- Stabilizers:Pectin, gelatin, and modified starches structure gummy and chewy candy matrices. India's FSSAI labeling requirements determine which imported hydrocolloid blends qualify for domestic confectionery production.
Most installed capacity flows through Sugars. Expansion is steepest in Sweeteners.
Form:
Application viscosity requirements and processing equipment compatibility drive format selection, with powder handling infrastructure favoring economies of scale.
- Powder:Cocoa powders, dry sweetener blends, and encapsulated flavor systems serve chocolate compound and dry mix applications. Belgian and Swiss couverture manufacturers specify particle size distributions below 20 microns for mouthfeel optimization in premium enrobing.
- Liquid:Cocoa liquors, liquid glucose, and oil-based flavor concentrates integrate into continuous processing lines. Cargill's integrated bean-to-liquor operations across Côte d'Ivoire and Ghana shorten lead times for European liquid cocoa supply.
- Granulated:Crystalline sucrose and sugar replacers feed pan-coating and hard candy cooking operations. Western European clean-label chocolate makers are specifying unrefined cane sugar with origin documentation for retail certification compliance.
- Syrup:Glucose, invert sugar, and high-fructose formulations dominate gummy manufacturing where moisture management and texture development require precise solids control. Mumbai and Delhi bakery chains are consolidating syrup procurement through centralized specifications.
Powder formats handle the greatest tonnage. Liquid is climbing the fastest on premium chocolate demand.
Application:
Chocolate applications concentrate value capture, while gummy and hard candy segments drive volume throughput with thinner margin structures.
- Chocolate:Couverture, compound coatings, and filling formulations require precise tempering curves and fat bloom resistance. Barry Callebaut anchors European supply through specialized cocoa butter equivalent portfolios tailored to clean-label premium positioning.
- Gummies:Gelatin and pectin-based matrices demand hydrocolloid stabilization and moisture control through shelf life. Bangalore industrial mithai producers are adopting chocolate enrobing at scale, bridging traditional sweet formats with Western confectionery techniques.
- Hard Candies:High-temperature cooking processes and glass transition management govern sucrose and glucose syrup formulation. Amorphous sugar structures require precise moisture ceilings below 2% to prevent cold flow and crystallization.
- Chewing Gums:Gum base polymers, plasticizers, and encapsulation systems for flavor release dominate technical specification. Polyol sweetener selection drives sugar-free positioning while managing chewing texture and shelf stability.
Chocolate commands the highest value per kilogram. Gummies are expanding most quickly in India.
End User:
Private label and retail channels concentrate specification power, while food service and bakery segments fragment procurement across regional distributor networks.
- Retail:Branded confectionery manufacturers dictate ingredient certification requirements including mass-balance cocoa and clean-label emulsifier status. German and French premium chocolate segments mandate origin-verified supply for retail listing.
- Food Service:Hotels, restaurants, and institutional catering purchase compound coatings and dessert bases through regional distributors. Specification flexibility allows cost-optimized formulations with shorter shelf life requirements.
- Bakery:Industrial and artisanal bakers integrate confectionery ingredients into decorated cakes, pastries, and filled products. Western India bakery chains are bypassing traditional distributors for direct relationships with bulk sweetener and emulsifier suppliers.
- Private Label:Retailer-controlled brands leverage ingredient house formulation partnerships to match national brand performance at price-tiered positioning. Clean-label credentials are becoming mandatory for private label chocolate entry in EU markets.
Retail channels absorb the largest ingredient value. Private label is gaining share fastest on supermarket consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and India present contrasting procurement patterns—German chocolate makers enforce strict origin-verified supply chains while Indian urban bakeries prioritize volume throughput through centralized mill relationships.
Germany
Premium couverture manufacturers in Cologne and Hamburg mandate mass-balance cocoa certification for retail listing. EFSA additive re-evaluations are forcing reformulation of lecithin emulsifiers to low-cadmium sourcing standards. The Rhineland industrial corridor hosts specialized compound coating facilities serving private label chocolate brands.
United States
FDA GRAS petitions for novel sweeteners are accelerating sugar-reduction partnerships between ingredient houses and confectionery brands. California Prop 65 litigation risk is driving acrylamide compliance retrofits on roasted nut and cocoa processing lines. Chicago and Pennsylvania chocolate clusters are adopting blockchain traceability for bean-to-bar verification.
India
Urban bakery chains in Mumbai, Delhi, and Bangalore are consolidating procurement through direct relationships with bulk sweetener suppliers. FSSAI labeling requirements determine which imported emulsifier blends qualify for domestic mithai production. Western India industrial zones are scaling chocolate enrobing operations for traditional sweet shops.
Switzerland
Specialty couverture producers in Zurich and Vevey specify particle size distributions below 20 microns for premium mouthfeel optimization. Swissmedic food safety standards align with EU EFSA precautionary thresholds for heavy metal residues. The Swiss chocolate cluster maintains captive cocoa butter equivalent formulation capabilities.
Brazil
Domestic confectionery brands in São Paulo and Minas Gerais are expanding compound coating production for regional sugar candy markets. ANVISA additive permissions govern which imported stabilizer systems enter gummy manufacturing lines. The Southeast industrial belt concentrates grinding and processing infrastructure for Latin American cocoa derivatives.
Confectionery Ingredients Market Vendor Landscape
West African processors anchor one tier; European specialists hold formulation-intensive positions in premium chocolate ingredients. The market structure splits between consolidated commodity grinders with integrated bean-to-liquor operations and fragmented regional compounders serving local bakery and confectionery channels. Two archetypes dominate: vertically integrated origin processors with captive African supply chains, and European ingredient houses with specialized clean-label portfolios. Competitive moves concentrate on backward integration into cocoa processing and strategic partnerships for novel sweetener development.
Within the integrated processor tier, Cargill Incorporated exemplifies bean-to-liquor control across Côte d'Ivoire and Ghana. Barry Callebaut occupies a position anchoring European premium supply through specialized couverture formulations. Olam International sits within the risk-management archetype, competing across origination, processing, and cocoa derivatives trading.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Barry Callebaut |
| Tate & Lyle |
| Ingredion Incorporated |
| Kerry Group |
| Olam International |
| AAK AB |
| DuPont |
| Others |
Supply Flow & Price Mechanics
Clean-label certification tiers split procurement economics between premium origin-verified cocoa derivatives and commodity compound coatings. This bifurcation concentrates pricing power with vertically integrated West African processors commanding long-term offtake premiums, while spot-market buyers absorb volatility in cocoa butter equivalent markets.
Pricing Analysis
Distributor margin compression runs through mid-tier European compound coating supply as direct-to-manufacturer digital platforms disintermediate traditional channel layers. Three-tier pricing structure across premium, standard, and economy levels separates mass-balance certified couverture from origin-documented artisan grades and bulk industrial inputs. Price differentiation hinges on cadmium compliance certification and bean-to-bar traceability documentation. Pricing pressure stems from cocoa butter futures volatility squeezing compound coating margins. Industrial bakery chains in India exhibit highest price sensitivity, while Swiss specialty couverture houses prioritize particle-size specification over cost.
Supply Chain Analysis
Reverse-logistics flows for cocoa bean mass-balance certification and re-tempering of off-specification couverture create secondary material loops in European processing hubs. Supply concentrates in Côte d'Ivoire, Ghana, and Indonesia for bean origination, with Belgian and Swiss facilities anchoring finished couverture production. Raw material dependencies center on cocoa liquor, cocoa butter, and lecithin emulsifier streams. Single-source vulnerability from West African origin concentration exposes processors to regional climate disruption. Distribution runs through integrated processor-direct relationships for premium tiers and regional distributor networks for commodity industrial supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as EU EFSA additive tightening and clean-label retail mandates concentrate demand toward certified origin-verified supply chains.
For Market Incumbents: Hedge against cocoa butter price volatility through long-term offtake agreements with Côte d'Ivoire and Ghana grinderies. Deepen backward integration into low-cadmium bean programs to preempt EFSA heavy metal threshold compliance costs. Reinforce formulation partnerships with Indian FSSAI-approved domestic compounders to defend position against natural stabilizer entrants. For New Entrants and Emerging Players: Precision fermentation-derived cocoa butter alternatives offer technology-first wedge into Belgian and Swiss specialty couverture pilot programs. Target white-space in India's Western industrial zones where centralized bakery procurement bypasses traditional distributor layers. Pursue direct digital sourcing platforms with lot-traceable cocoa for mid-size European craft chocolate makers as go-to-market anchor. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional compounders lack capital for integrated traceability architecture and blockchain verification systems. Five-to-ten year viability favors processors with captive African supply chains and clean-label formulation portfolios. Acquire mid-tier ingredient houses with approved natural emulsifier blends and FSSAI-compliant stabilizer systems. Monitor EU EFSA transition deadline compliance rates as inflection signal for supplier qualification cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into West African Processing | Cargill's bean-to-liquor operations across Côte d'Ivoire and Ghana secure origin advantage against supply shocks. |
| Clean-Label Emulsifier Portfolio Development | Barry Callebaut's specialized couverture formulations align with EFSA additive re-evaluation cycles in premium segments. |
| Direct-to-Manufacturer Digital Sourcing Platform | B2B platforms capture share among European craft chocolate makers seeking lot-traceable cocoa with reduced distributor layers. |
| FSSAI-Compliant Domestic Compounding | Indian regulatory permission gaps create first-mover positioning for approved natural stabilizer portfolios in mithai production. |
| Precision Fermentation Pilot Scale-Up | Microbial lipid formulations match cocoa butter crystallization behavior without agricultural land-use constraints in Belgian facilities. |
Methodological Framework
Multiple input streams — executive interviews with cocoa processing plant managers, procurement leads at European couverture manufacturers, and FSSAI regulatory affairs specialists — were reconciled against secondary validation from customs trade data, SEC processor filings, and EU EFSA additive re-evaluation documentation. Bottom-up triangulation across ingredient type, application format, and end-user channel dimensions was cross-checked with top-down market sizing from grinder capacity announcements and regional distributor network mapping.
Data-stream reconciliation anchored volume and value outputs across the analysis window through segmented modeling of cocoa derivatives, sweeteners, emulsifiers, and stabilizers by powder, liquid, granulated, and syrup formats. CAGRs were derived from historical grinder throughput trends projected against urban bakery expansion trajectories in India and clean-label reformulation cycles in Western Europe. Industry-specific forecast inputs incorporated cocoa butter futures positioning and FSSAI labeling permission timelines.
The model holds under stable EU EFSA regulatory transition schedules and consistent West African bean supply flows; deviation in origin concentration shocks or accelerated additive ban implementations would shift trajectory. Forecasts embed assumptions regarding precision fermentation scale-up rates and Indian centralized procurement adoption curves. Practitioners should monitor EFSA compliance deadline adherence and Ghana-Côte d'Ivoire grindery expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Resistant Starch Market
Ingredients
India Gelatin Market
Ingredients
Textured Wheat Protein Market
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
Asia Pacific Feed Yeast Market
Ingredients
Cooking Oil Market
Ingredients
Europe Fats and Oil Market
Ingredients
Africa Food Ingredients Market
Ingredients
Coconut Flour Market
Ingredients
Europe Edible Oil Market
Ingredients
Low Fat Oil Market
Ingredients
Freeze-Dried Vegetable Powder Market
Ingredients
Africa Plant Protein Ingredients Market
Ingredients
Microparticulated Egg White Protein Market
Ingredients
Casein Glycomacropeptide Market