
 Thinned Starch Market | 2026-2036
Thinned Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Thinned Starch Market Analytics
ISO 22000 certification is bifurcating the competitive landscape between qualified suppliers and commodity producers. Cargill Inc leverages its integrated grain origination network to secure cost-advantaged feedstock positions across multiple continents. Ingredion Inc differentiates through specialty modified starch R&D pipelines targeting pharmaceutical-grade specifications. Tate & Lyle Inc anchors its position in European food and beverage channels with deep technical service capabilities.
Thinned starch denotes starch derivatives that have undergone controlled hydrolysis or physical modification to achieve reduced viscosity at standard solids concentration, typically measured in Brookfield viscosity ranges of 50-500 cP for industrial applications. The primary commercial purpose centers on enabling high-solids processing in food systems, paper coating formulations, and pharmaceutical binders without excessive thickness or pumpability constraints. Modified starch and pregelatinized starch variants command the dominant margin pools due to their functional customization and premium pricing relative to native alternatives. Powder form dominates current volume flows, though liquid starch is gaining traction in continuous-process paper mills and ready-to-use food manufacturing lines where hydration steps add cost.
The FDA governs food-grade starch specifications through 21 CFR 172.892, while the EPA regulates wastewater discharge from wet-milling operations under Clean Water Act permits. In Europe, EFSA evaluates novel starch modifications for food safety, and REACH compliance requirements constrain chemical cross-linking agents used in certain modified starch grades. Stakeholders must monitor evolving clean-label definitions and biobased certification schemes, as these standards increasingly determine customer qualification and contract renewal outcomes.
Market Dynamics
Clean-label formulation mandates from the EU Green Deal are forcing food and beverage manufacturers to reformulate with thinned starch derivatives, reshaping raw material qualification protocols and supplier selection criteria across the value chain.
Growth Catalysts
- EU Green Deal agricultural standards:Tightening processing requirements are accelerating thinned starch adoption in European clean-label food systems as manufacturers seek compliant texturizing alternatives.
- Pharmaceutical excipient demand in India:Domestic pharmaceutical manufacturing expansion is scaling consumption of pharmaceutical-grade thinned starch for tablet binding and controlled-release formulations.
- High-solids processing technology:Continuous-process paper mills are converting to liquid thinned starch systems to eliminate hydration steps and reduce energy consumption.
Market Restraints
- Maize price volatility:Feedstock cost fluctuations constrain margin predictability for wet-milling operations dependent on grain origination networks.
- REACH compliance burden:Chemical cross-linking agent restrictions in Europe limit modification pathways for certain specialty starch grades.
- Native starch substitution:Unmodified native starches compete in cost-sensitive applications where functional performance requirements permit lower specification materials.
Strategic Opportunities
- India food processing corridor:Underpenetrated domestic snack and convenience food sectors offer expansion potential for modified starch technical service providers.
- Biobased certification schemes:Emerging sustainability standards create qualification premiums for certified thinned starch in European contract manufacturing.
- Ready-to-use liquid formats:Channel innovation toward pre-hydrated starch systems addresses continuous-process manufacturing lines seeking operational simplification.
Industry Challenges
- ISO 22000 certification timelines:Extended audit and documentation requirements delay supplier qualification for food safety-critical applications.
- Modified starch R&D capex intensity:Pharmaceutical-grade specification development demands sustained investment in analytical capabilities and pilot-scale equipment.
- Legacy hydration infrastructure:Paper mill retrofit requirements create friction in liquid starch adoption despite operational benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thinned Starch Market |
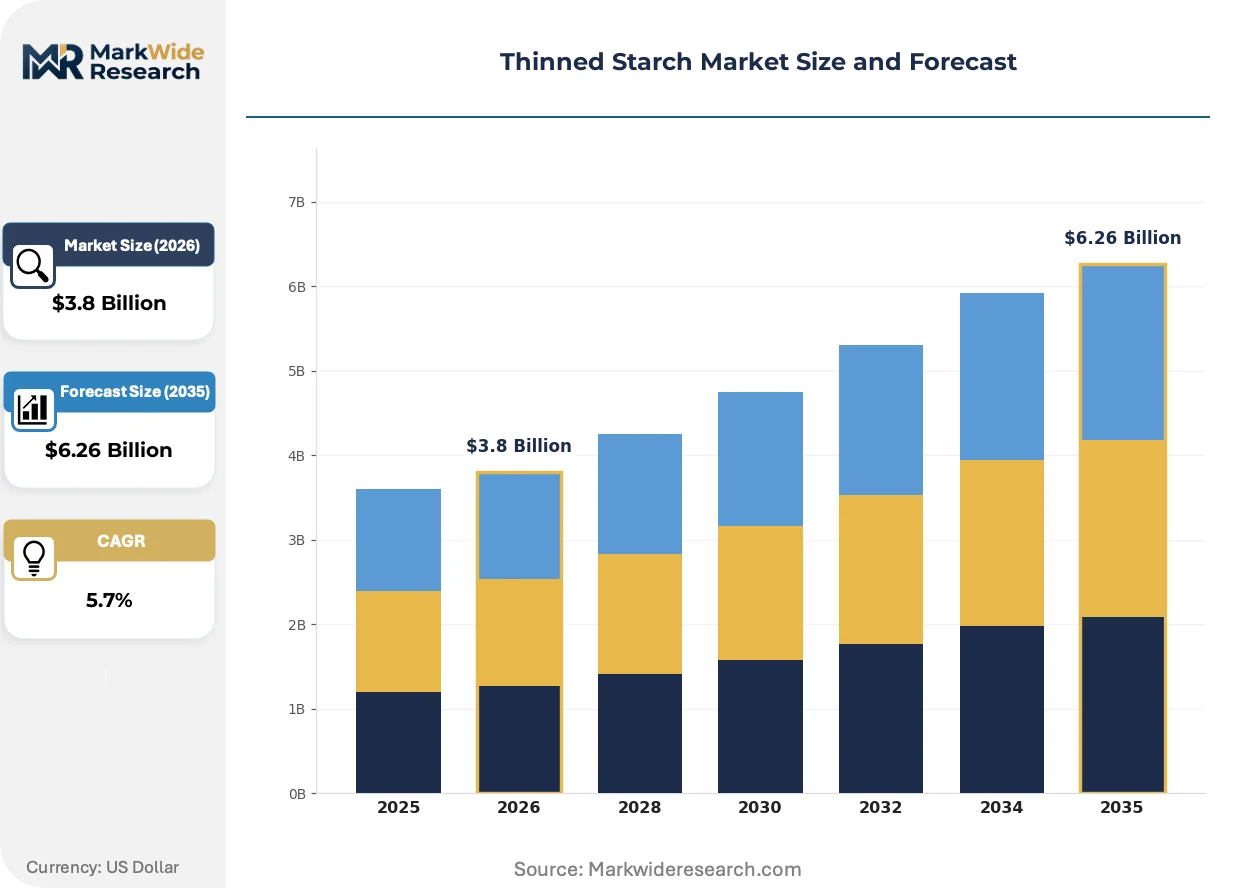
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Pregelatinized Starch, Native Starch, Liquid Starch End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Paper & Packaging Form: Powder, Liquid, Granules, Gel Application: Thickening Agent, Stabilizer, Binder, Coating Agent |
| Companies Covered | Cargill Inc, Ingredion Inc, Tate & Lyle Inc, Roquette Freres, Archer Daniels Midland Company, Agrana Starke GmbH, Grain Processing Corporation, Everest Starch India Pvt. Ltd, SPAC Starch Products Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thinned Starch Market Evolving Landscape
Enzymatic hydrolysis control systems are reshaping precision in viscosity targeting, while regulatory tightening on chemical modifications and shifting procurement patterns toward certified sustainable supply chains are redefining competitive differentiation.
Enzyme-catalyzed hydrolysis with real-time viscosity monitoring is bifurcating the technical capabilities of thinned starch producers. Food and beverage manufacturers with stringent clean-label requirements are prioritizing enzymatically processed grades over acid-thinned alternatives. This technology is compressing the performance gap between premium modified starches and lower-cost hydrolyzed options.
REACH restrictions on epichlorohydrin and other cross-linking agents are constraining chemical modification pathways in European manufacturing. Wet-milling operators are redirecting capital toward physical modification and enzymatic process equipment to maintain product portfolio breadth. Modified starch grades with reduced chemical additive profiles are commanding qualification premiums in pharmaceutical and infant nutrition applications.
Certification-driven procurement is displacing spot-market purchasing for food-grade thinned starch in European and North American channels. Large food manufacturers are consolidating supplier panels around ISO 22000-certified processors with documented sustainability credentials. This pattern concentrates contract volumes with integrated grain processors capable of traceability documentation from farm to finished ingredient.
Thinned Starch Market Segmentation
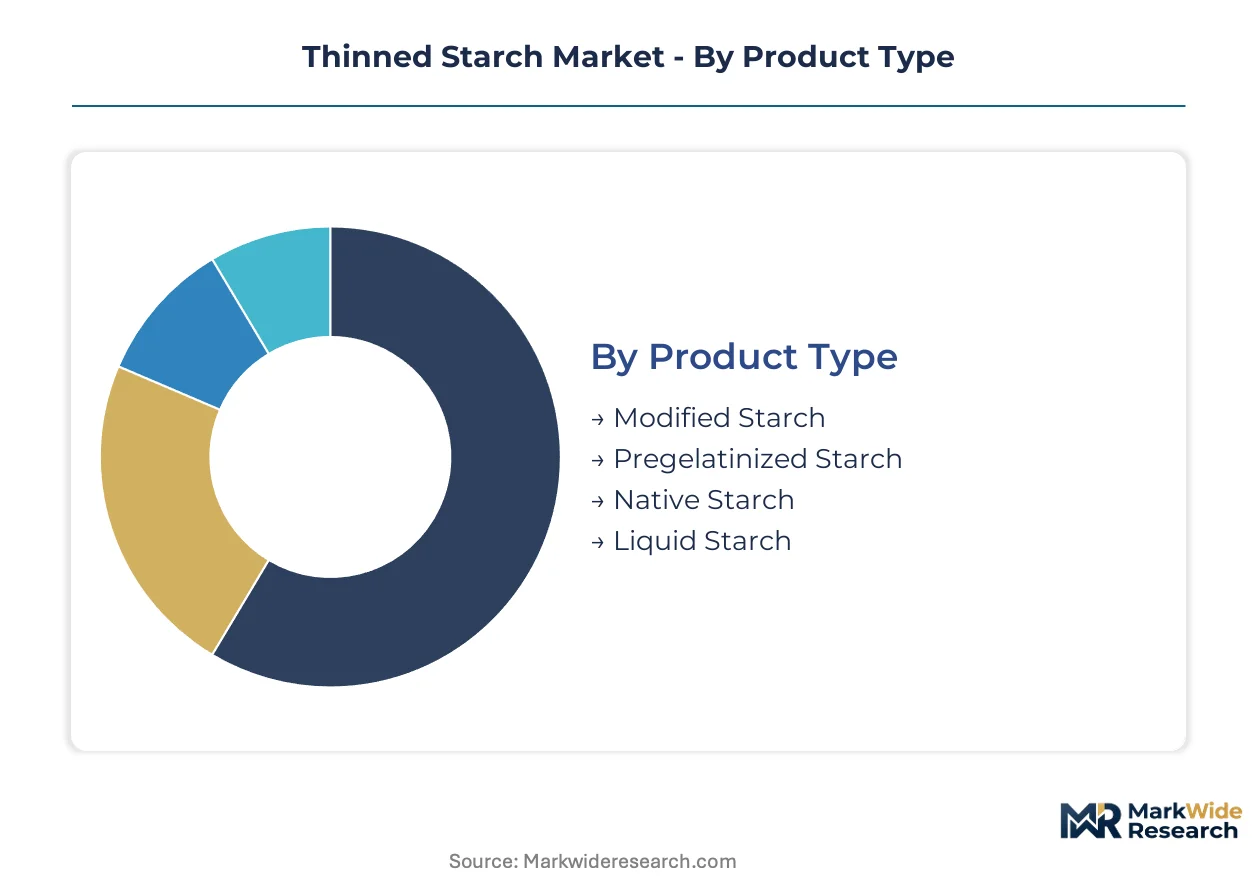
Thinned starch segmentation reflects divergent regulatory pathways across product categories, with modified and pregelatinized grades facing stricter EFSA and FDA scrutiny than native alternatives. Form and application dimensions further stratify the market by operational requirements and end-use qualification standards.
Product Type:
FDA 21 CFR 172.892 governs food-grade modified starch specifications, while EFSA novel food assessments constrain enzymatic and chemical modification pathways in European supply chains.
- Modified Starch:Chemical or enzymatic alteration of native starch polymers creates controlled viscosity profiles and enhanced freeze-thaw stability. Pharmaceutical tablet binding and EU clean-label sauce formulations concentrate demand, though REACH restrictions on epichlorohydrin cross-linkers constrain certain European production pathways.
- Pregelatinized Starch:Pre-cooked starch granules hydrate in cold water, eliminating heat-processing steps for manufacturers. Instant food applications and ready-to-use bakery premixes drive volume, with FSSAI certification requirements shaping supplier qualification in India's expanding processed food corridor.
- Native Starch:Unmodified extraction from maize, tapioca, or potato sources serves cost-sensitive applications where functional performance requirements remain minimal.
- Liquid Starch:Pre-hydrated slurry format eliminates on-site hydration infrastructure for continuous-process paper mills and high-throughput food manufacturing lines.
Modified starch handles the majority of throughput; liquid starch is expanding most quickly on share as paper mills retrofit for energy efficiency.
End Use Industry:
Customer procurement patterns diverge sharply by sector, with pharmaceutical and food manufacturers imposing ISO 22000 and pharmaceutical-grade documentation requirements that commodity paper processors rarely demand.
- Food & Beverage:Clean-label mandates from the EU Green Deal are reformulating texturizer procurement across sauce, dairy, and bakery applications. Manufacturers prioritize enzymatically processed grades with documented supply chain traceability.
- Pharmaceuticals:Tablet binders and controlled-release excipients require USP-NF conformance and low-microbial specifications. CDSCO and FDA cGMP compliance create qualification barriers that concentrate contract volumes with certified processors.
- Personal Care:Cosmetic thickeners and film-forming agents in skin and hair products utilize pharmaceutical-grade starch derivatives for regulatory safety margins.
- Paper & Packaging:Surface sizing and coating applications consume high volumes of lower-specification native and acid-thinned starches where cost efficiency dominates procurement criteria.
Food and beverage absorbs the largest volume base; pharmaceuticals is climbing the fastest as India scales domestic manufacturing.
Form:
Physical state determines logistics economics and manufacturing integration requirements, with powder formats benefiting from established bulk handling infrastructure while liquid systems reduce downstream capital intensity.
- Powder:Spray-dried or drum-dried particulate dominates current shipment volumes, leveraging existing bulk storage and pneumatic conveying systems across food and paper mills.
- Liquid:Pre-hydrated slurries reduce energy consumption and eliminate hydration bottlenecks in continuous-process environments, though shorter shelf life constrains distribution radius.
- Granules:Intermediate particle size offers controlled dissolution kinetics for specific pharmaceutical and instant food applications requiring staged hydration.
- Gel:Highly concentrated aqueous preparations serve specialized pharmaceutical and personal care formulations demanding precise viscosity control.
Powder maintains the dominant share position; liquid is gaining share fastest on paper mill conversion activity.
Application:
Functional role in finished products determines specification intensity, with binders and stabilizers facing stricter purity requirements than basic thickening applications.
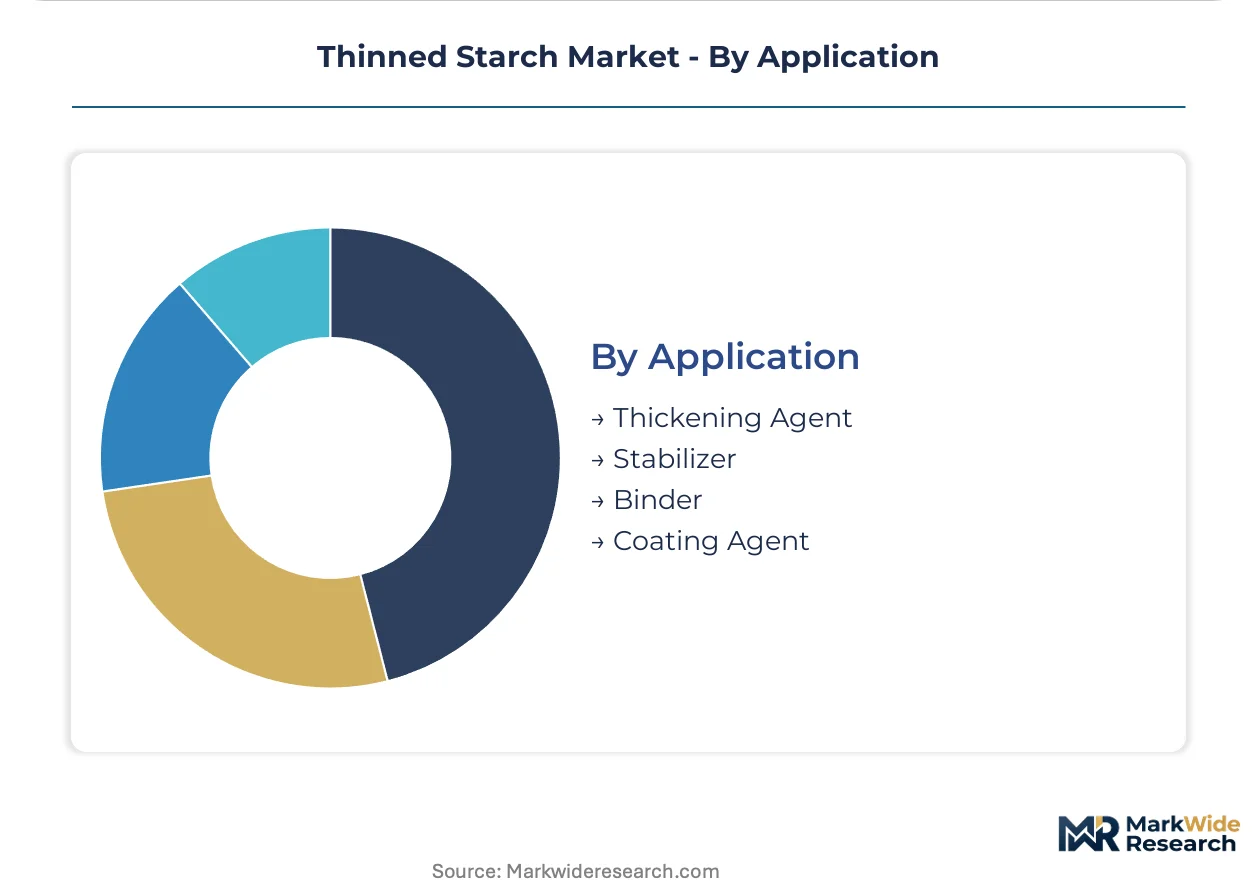
- Thickening Agent:Viscosity modification in sauces, soups, and dairy products represents the foundational volume application, with clean-label enzymatic grades displacing acid-thinned alternatives in premium formulations.
- Stabilizer:Freeze-thaw protection and emulsion maintenance in processed foods and cosmetics requires modified starch with specific substitution patterns and cross-linking densities.
- Binder:Tablet compression and granulation in pharmaceutical manufacturing demands low-microbial, high-purity grades with documented excipient compliance.
- Coating Agent:Surface treatment for paper gloss and pharmaceutical tablet film-coating utilizes specialized viscosity grades with controlled film-forming characteristics.
Thickening agent carries the volume base; binder is the steepest expansion trajectory on pharmaceutical excipient demand growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food and beverage manufacturers in Germany, India, and the United States concentrate procurement volumes, while paper mills in China and pharmaceutical formulators in Switzerland drive specialized grade demand.
Germany
EU Green Deal clean-label mandates reshape sauce and dairy texturizer procurement. EFSA novel food assessments constrain enzymatic modification pathways for imported starch derivatives. The Rhine-Ruhr industrial corridor hosts reformulation labs where manufacturers test reduced-chemical additive profiles.
India
Domestic pharmaceutical excipient manufacturing scales tablet binder consumption. FSSAI certification requirements shape supplier qualification in processed food corridors. Gujarat's starch processing belt expands modified starch capacity to serve snack and convenience food sectors.
United States
FDA 21 CFR 172.892 governs food-grade modified starch specifications for sauce and bakery applications. EPA Clean Water Act permits regulate wet-milling wastewater discharge from Iowa and Illinois grain processing facilities. The Midwest corn belt anchors feedstock origination networks supplying North American modified starch production.
China
Paper mills retrofit continuous-process lines for liquid thinned starch systems to reduce energy consumption. SAMR food additive standards govern modified starch safety assessments for domestic food manufacturing. Shandong Province concentrates wet-milling capacity serving packaging and corrugated board producers.
Switzerland
Pharmaceutical-grade excipient demand concentrates among tablet binders and controlled-release formulation specialists. Swissmedic GMP compliance creates qualification barriers that filter contract volumes toward certified processors. Basel's pharmaceutical cluster sources low-microbial starch derivatives for European export markets.
Thinned Starch Market Competitive Landscape
Player mix skews toward integrated grain processors with captive origination networks. The vendor base separates into three tiers: multinational wet-millers with continental coverage, regional specialists with technical service depth, and commodity producers competing on feedstock proximity. Strategic moves concentrate on backward integration into grain origination and portfolio diversification toward pharmaceutical-grade specifications.
Within the integrated processor tier, Cargill Inc and Archer Daniels Midland Company exemplify scale-driven origination models, while Ingredion Inc occupies a position emphasizing specialty modification capabilities. Tate & Lyle Inc represents the European technical service archetype with deep food and beverage channel relationships. Roquette Freres anchors the European pharmaceutical and plant-based ingredient vector.
| Leading Market Players |
|---|
| Cargill Inc |
| Ingredion Inc |
| Tate & Lyle Inc |
| Roquette Freres |
| Archer Daniels Midland Company |
| Agrana Starke GmbH |
| Grain Processing Corporation |
| Everest Starch India Pvt. Ltd |
| SPAC Starch Products Ltd |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with maize price indexation lock in feedstock access for wet-millers while capping margin exposure against grain origination volatility. These structures concentrate pricing power with integrated processors capable of backward integration into Iowa and Illinois grain networks, leaving toll processors exposed to spot-market maize differentials.
Pricing Analysis
Cost-plus contracts indexed to CBOT maize futures dominate thinned starch procurement, with ISO 22000-certified grades commanding premiums over commodity alternatives. Price differentiation rests on certification tier and enzymatic processing depth, with pharmaceutical-grade specifications fetching the widest spreads. Cost compression in acid-thinned segments is intensifying because native starch substitutes erode specification premiums. Paper and packaging buyers exhibit the highest price sensitivity, while pharmaceutical formulators prioritize compliance documentation over unit economics.
Supply Chain Analysis
The United States and India anchor global maize wet-milling capacity, with Gujarat's processing belt expanding modified starch output for domestic food corridors. Feedstock supply draws from Iowa corn belt origination networks and Indian seasonal harvest cycles, while enzymatic processing enzymes and cross-linking agents feed from European and Chinese chemical manufacturers. Single-source vulnerability concentrates in epichlorohydrin supply for chemical modification pathways constrained by REACH. Distribution runs through bulk rail and tanker networks serving continuous-process paper mills and pharmaceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening as EU Green Deal clean-label mandates splinter demand across enzymatic modification specialists, pharmaceutical-grade processors, and regional toll millers. This demand-side shift creates niche positions for technical service providers capable of bridging certification gaps.
For Market Incumbents: Shield margin pools by deepening backward integration into Ukrainian and Brazilian grain origination networks to offset Iowa supply concentration. Accelerate ISO 22000 certification coverage across Indian joint venture assets before FSSAI mandates harden qualification barriers. Native starch substitution in Asian paper markets represents the priority threat requiring specification differentiation investment.
For New Entrants and Emerging Players: Lead with enzymatic hydrolysis capabilities targeting European clean-label sauce and dairy reformulation demand, where EFSA novel food assessments filter out acid-thinned competitors. India's underpenetrated snack processing corridor offers the most penetrable geography, with technical service partnerships providing the critical go-to-market angle against established millers.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap wet-millers with dormant pharmaceutical-grade capacity and existing ISO 22000 infrastructure, positioned for excipient demand inflection. Long-term viability across the analysis window favors processors with dual food-pharma qualification pathways. The signal to watch is CDSCO cGMP enforcement intensity in Gujarat, which would accelerate contract consolidation toward certified processors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Captive maize supply from Iowa and Brazilian networks insulates margin volatility from CBOT price swings. |
| Pharmaceutical-Grade Capacity Conversion | USP-NF compliant equipment captures tablet binder demand scaling from India's CDSCO-regulated manufacturing expansion. |
| Enzymatic Process Equipment Deployment | Real-time viscosity control systems satisfy EFSA clean-label requirements displacing acid-thinned alternatives in European sauces. |
| ISO 22000 Certification Acceleration | Food safety documentation unlocks contract manufacturing volumes from consolidating European and North American buyer panels. |
| Ready-to-Use Liquid Format Expansion | Pre-hydrated slurry systems reduce energy consumption for continuous-process paper mills retrofitting in Shandong Province. |
Research Methodology
Cross-validation between wet-miller procurement directors and pharmaceutical formulator technical sourcing managers anchors the qualitative findings in operational reality. Primary interviews with grain origination specialists, FSSAI compliance officers, and paper mill energy managers combined with secondary validation from FDA 21 CFR 172.892 filings, EFSA novel food assessment databases, and Indian customs starch trade data. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates across enzymatic and acid-thinned processing routes.
Sensitivity analysis on maize price volatility and REACH cross-linker restriction scenarios tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product type hierarchy, end-use industry qualification tiers, form factor logistics economics, and regional regulatory cluster intensity. CAGRs derive from installed capacity utilization trends and customer procurement pattern shifts documented through the primary fieldwork. Forecast inputs incorporate EU Green Deal implementation pacing and Indian pharmaceutical excipient localization targets.
Forecasts assume regulatory continuity in FDA food additive specifications and EFSA novel food pathways; material policy shifts in REACH chemical restrictions or FSSAI mandatory fortification rules would require re-modeling. Specific risks include epichlorohydrin supply disruption, monsoon-driven Indian maize harvest variance, and paper mill retrofit acceleration beyond baseline assumptions. Recalibration cycles align with material shifts in clean-label procurement mandates and pharmaceutical cGMP enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Potato Protein Market
Ingredients
Egg Membrane Powder Market
Ingredients
Roll-Dried Starch Market
Ingredients
North America Agar Market
Ingredients
Food Ingredients Market
Ingredients
Dry Mixes Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
Prenatal Vitamin Ingredients Market
Ingredients
Animal-Derived Ingredients Market
Ingredients
APAC Savoury Ingredients Market
Ingredients
Ice Cream Bases Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Europe Insoluble Dietary Fibers Market
Ingredients
Rennet Market
Ingredients
Global Malt and Malt Extracts Market