

Rice Bran Fatty Alcohols Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Bran Fatty Alcohols Market Insights
Personal care formulators is rotating away from synthetic emollients toward rice bran-derived fatty alcohols as clean-label positioning hardens into a procurement mandate. NOF CORPORATION leverages captive rice bran oil refining in Japan to secure feedstock continuity. Oryza Oil & Fat Chemical anchors its competitive stance through deep specialization in rice-derived oleochemistry. Eastman Chemical Company competes by extending its biosurfactant portfolio into Asia-Pacific supply chains.
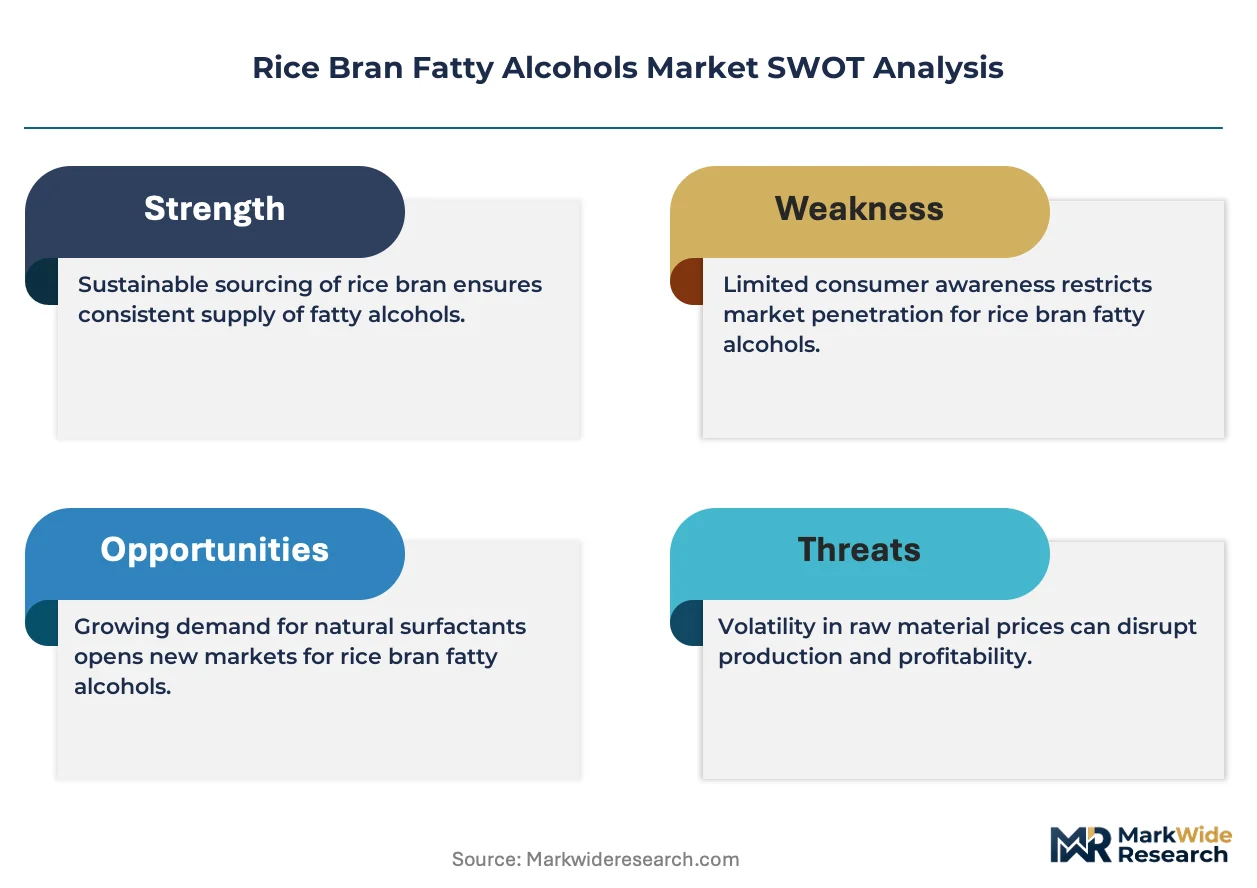
Rice bran fatty alcohols comprise C16-C20 aliphatic alcohols extracted via saponification and distillation of rice bran wax, valued for their emollient properties and low melting-point profiles in cosmetic formulations. Primary fatty alcohols dominate volume flows due to established surfactant demand, while branched-chain alcohols capture widening margin pools in premium lubricant applications. Emollients within the cosmetics and personal care end-user industry lead current offtake, though pharmaceutical-grade specifications are tightening as a faster-growing adjacent channel.
REACH registration in Europe and FDA cosmetic ingredient guidance in the United States shape purity thresholds and traceability requirements for rice bran fatty alcohol imports. BIS standards in India and China's GB standards for cosmetic raw materials add further compliance layers for suppliers seeking multi-market access. Stakeholders must monitor regulatory divergence between jurisdictions while building backward integration into rice bran wax supply to defend margin structures against feedstock volatility.
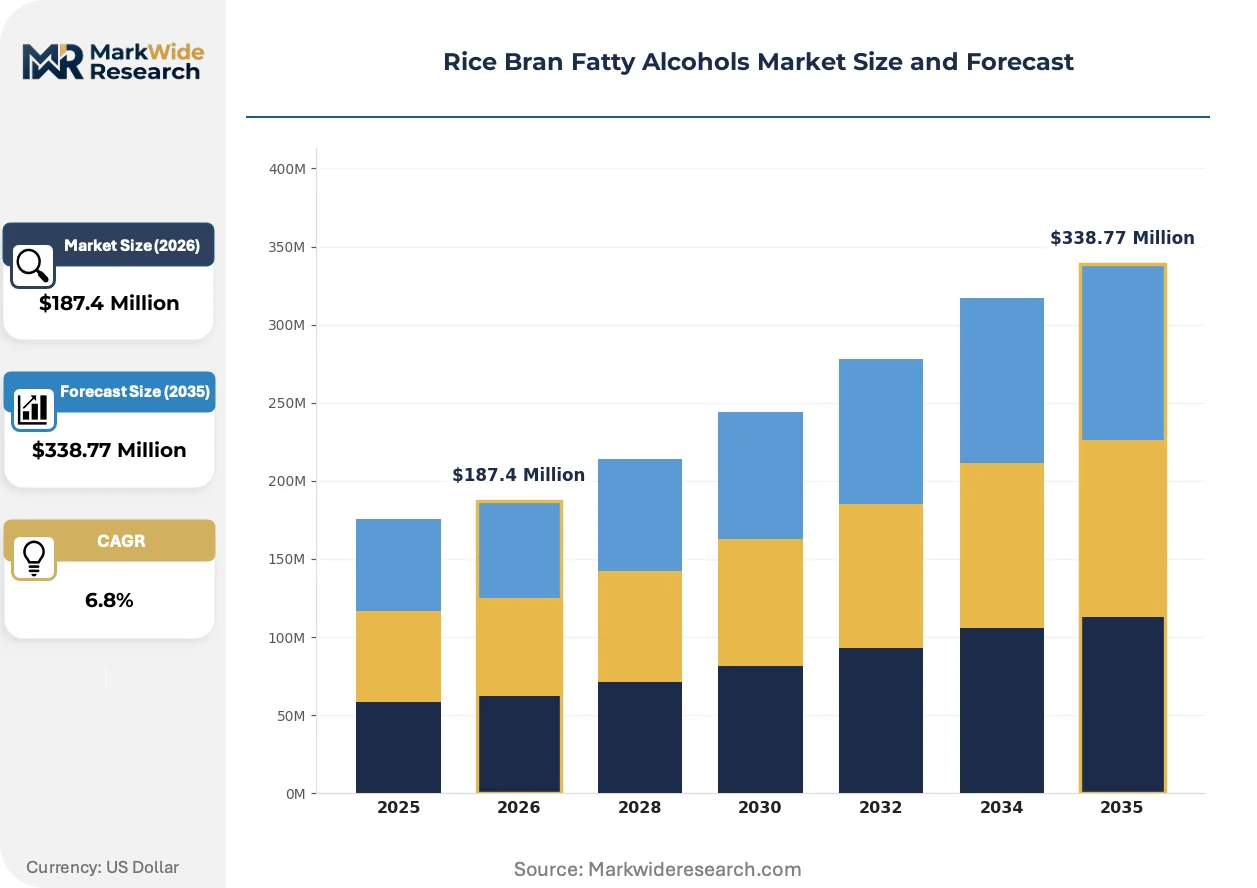
Market Dynamics
REACH registration deadlines in Europe are compressing supplier timelines while Southeast Asian processors consolidate rice bran wax supply chains to capture margin from personal care formulators.
Growth Catalysts
- REACH Phase-In Substances Registration:European ECHA deadlines for C16-C20 fatty alcohols are forcing formulators to validate compliant suppliers, accelerating procurement from integrated rice bran processors.
- Clean-Label Cosmetic Mandates:Personal care brands are embedding plant-derived emollients into product architecture, pulling volume from petrochemical fatty alcohols toward rice bran-derived alternatives.
- Southeast Asian Processing Cluster Concentration:Thailand and Vietnam are consolidating rice bran oil refining with downstream alcohol distillation, shortening feedstock-to-product lead times.
Market Restraints
- Rice Bran Oil Price Volatility:Feedstock costs fluctuate with rice milling seasonality and competing food-oil demand, squeezing alcohol producer margins.
- Single-Source Geography Risk:Over 70 percent of rice bran wax supply concentrates in East and Southeast Asian agricultural zones, exposing buyers to climate and logistics disruptions.
- Cetanol Purity Ceiling:Current saponification-distillation yields struggle to meet pharmaceutical-grade specifications without prohibitively expensive secondary refining.
Strategic Opportunities
- Indian Pharmaceutical-Grade Channel:CDSCO tightening of excipient standards creates first-mover advantage for suppliers achieving certified purity tiers.
- Brazilian Bio-Lubricant Formulation:ANVISA approval pathways for plant-derived base stocks open adjacent demand outside cosmetics saturation.
- Supercritical CO2 Extraction Convergence:Combining non-thermal wax recovery with membrane filtration enables cold-process certification for premium organic labels.
Industry Challenges
- Oleochemical Process Engineering Talent Gap:Specialized expertise in rice bran wax saponification and molecular distillation is scarce outside Japanese and Thai technical institutes.
- Multi-Jurisdiction Certification Timelines:Simultaneous pursuit of ISO 16128 natural cosmetics certification and FDA cosmetic ingredient listing extends product launch cycles.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Bran Fatty Alcohols Market Trends and Innovations
Process intensification and regulatory tightening are converging to reshape how rice bran fatty alcohols are produced, certified, and procured across end-use verticals.
Supercritical CO2 extraction is supplanting conventional hexane-based rice bran oil recovery in premium-tier facilities. Japanese and South Korean cosmetic ingredient suppliers are adopting the technology at pilot scale. The shift is compressing solvent residue compliance costs while enabling cold-process claims for organic formulation segments.
ECHA REACH authorization requirements for C16-C18 fatty alcohols are tightening impurity thresholds for polycyclic aromatic hydrocarbons and pesticide residues. European personal care formulators are now demanding batch-level traceability documentation from Asian suppliers. The compliance burden is favoring backward-integrated processors with captive rice bran supply over merchant distillers.
Long-term offtake contracting is displacing spot-market purchasing among multinational personal care brands. Procurement teams at major formulators are locking eighteen-to-twenty-four-month supply agreements to secure REACH-compliant volumes. The pattern is most pronounced in German and French headquarters operations where sustainability audit requirements now mandate supplier relationship depth over price arbitrage.
Rice Bran Fatty Alcohols Market Segmentation
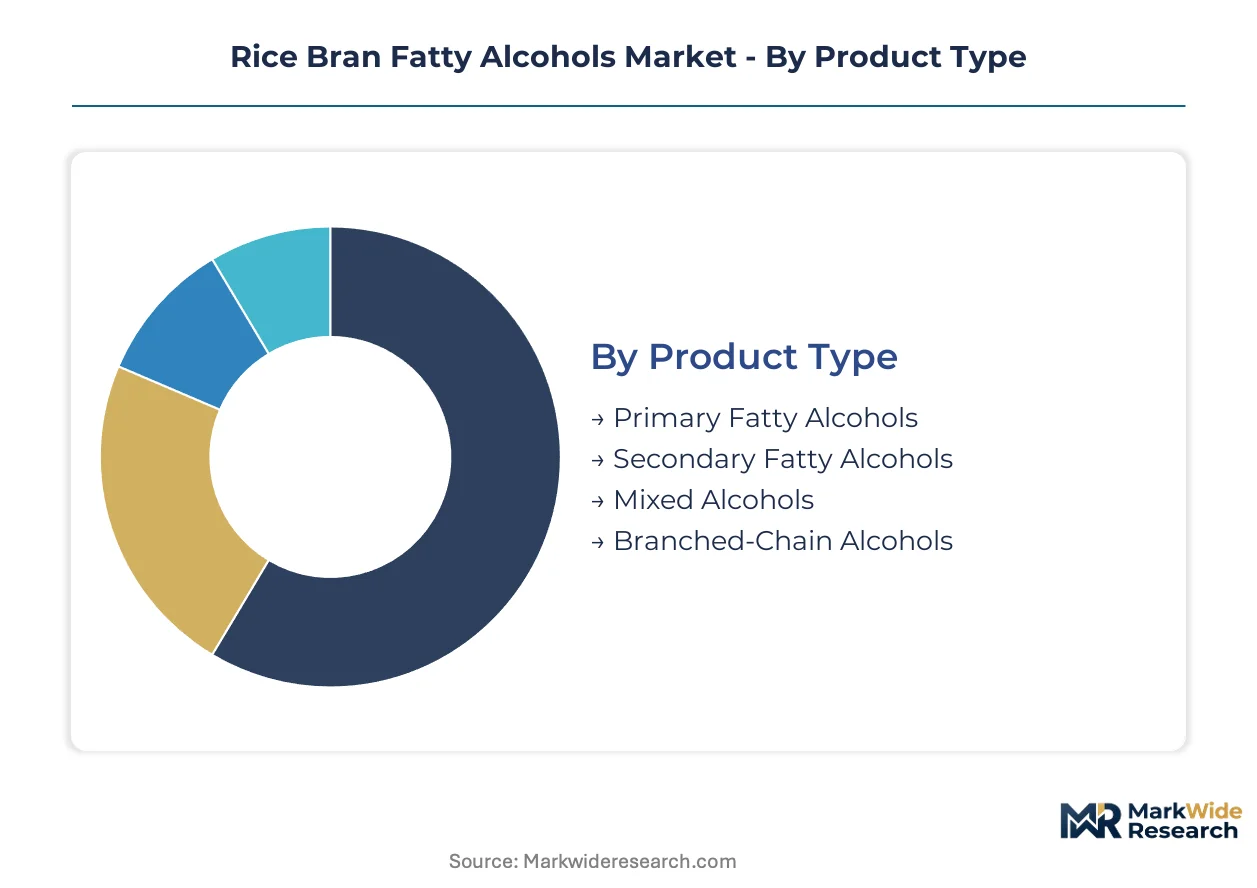
Rice bran fatty alcohols serve divergent performance specifications across cosmetic, pharmaceutical, and industrial channels. Segment boundaries reflect purity thresholds, processing intensity, and regulatory certification tiers rather than simple commodity grades.
Product Type:
Geographic demand patterns split sharply: primary fatty alcohols flow predominantly to domestic Asian surfactant manufacturers, while branched-chain and specialty grades command export premiums to European and North American formulators.
- Primary Fatty Alcohols:Linear C16-C18 alcohols derived from direct saponification of rice bran wax, prized for consistent hydrophobic tail length in anionic surfactant synthesis. Thai and Vietnamese oleochemical refiners concentrate capacity here, feeding regional detergent and personal care manufacturing clusters with REACH-registered volumes.
- Branched-Chain Alcohols:Iso- and anteiso-structured C18-C20 alcohols offering superior oxidative stability and low-temperature fluidity. German and Japanese lubricant formulators absorb premium-priced offtake for synthetic ester base stocks, though production remains constrained by molecular distillation bottlenecks at Japanese technical institutes.
- Secondary Fatty Alcohols:Ketone-reduction products with asymmetric hydroxyl placement, finding niche use in fragrance fixative applications.
- Mixed Alcohols:Broad-cut distillation fractions serving cost-sensitive industrial emulsifier markets without pharmaceutical-grade certification requirements.
Primary fatty alcohols command the established base. The steepest expansion runs through branched-chain alcohols.
Application:
Cost-tier stratification separates pharmaceutical-grade emollients from commodity surfactant feedstocks, with lubricant and plasticizer applications occupying a mid-tier technical performance band.
- Emollients:High-purity C18 alcohols formulated into skin-conditioning agents for clean-label cosmetics. South Korean and French personal care brands specify batch-level PAH documentation, tightening supplier qualification to backward-integrated rice bran processors.
- Surfactants:Volume-dominant application for primary alcohol sulfates and ethoxylates in household and industrial detergents. Indonesian and Indian formulators drive procurement through spot-market purchasing, though this is accelerating toward contract-based sourcing under ECHA compliance pressure.
- Lubricants:Synthetic ester base stocks leveraging branched-chain alcohols for biodegradability compliance in marine and aviation applications.
- Plasticizers:Secondary alcohol phthalate alternatives for PVC compounding in regulated construction and medical device markets.
- Adhesives:tackifier modifiers in hot-melt formulations requiring low-color and low-odor specifications.
Surfactants anchor volume throughput. Emollients generate the fastest margin expansion.
End User Industry:
Customer-type concentration distinguishes multinational cosmetics houses with eighteen-month procurement contracts from fragmented agricultural chemical blenders purchasing on specification.
- Cosmetics & Personal Care:Clean-label positioning mandates plant-derived emollient sourcing, with German and Japanese headquarters operations auditing supplier relationship depth. ISO 16128 natural cosmetics certification is becoming a non-negotiable entry ticket.
- Pharmaceuticals:Excipient-grade fatty alcohols for topical ointment bases and transdermal delivery systems. CDSCO tightening of Indian pharmaceutical standards is compressing qualified supplier lists toward certified-purity tiers.
- Paints & Coatings:Coalescing agents and pigment dispersants where VOC regulations are shifting preference toward bio-based alternatives.
- Agriculture Chemicals:Surfactant adjuvants for pesticide emulsion concentrates, price-sensitive and specification-tolerant.
- Polymers:Internal and external lubricants for PVC and engineering thermoplastics processing.
Cosmetics and personal care dominates procurement sophistication. Pharmaceuticals presents the steepest certification barrier and corresponding margin upside.
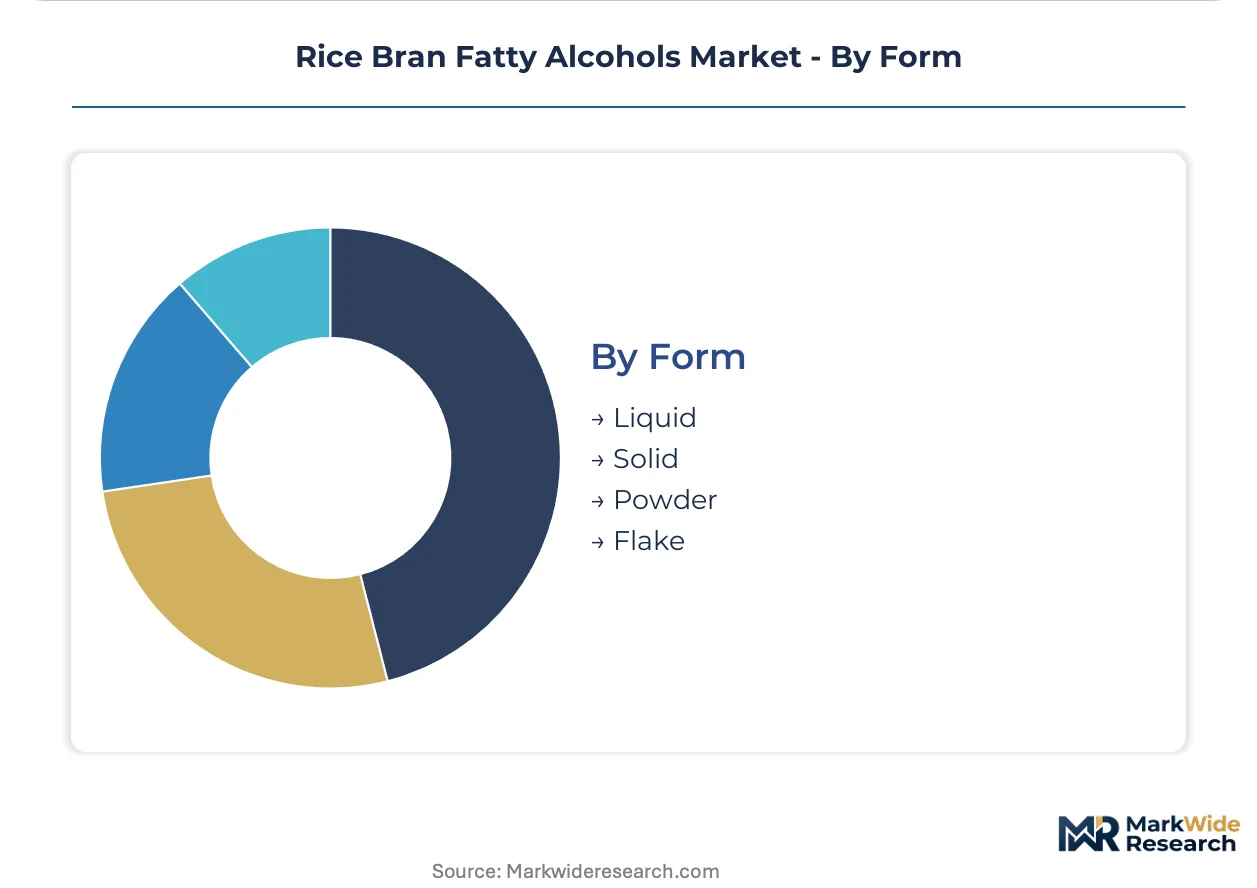
Form:
Supply concentration in Southeast Asian processing clusters favors liquid and flake formats for export efficiency, while powder grades serve specialized pharmaceutical packaging requirements.
- Flake:Standardized solid form for bulk surfactant manufacturing, enabling automated handling at scale. Thai and Vietnamese refiners optimize flake production for containerized export to European detergent compounders.
- Liquid:Molten or solvent-dissolved delivery for direct formulation integration, preferred by high-throughput personal care manufacturers seeking process energy reduction.
- Solid:Pressed blocks for industrial lubricant and plasticizer compounders with heated mixing equipment.
- Powder:Micronized grades for pharmaceutical tableting and premium cosmetic powder formulations, commanding purity premiums and specialized packaging.
Flake format holds the volume base. Powder grades climb fastest on pharmaceutical and premium cosmetic specification pull.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational personal care formulators concentrate procurement teams in Germany, Japan, and South Korea where clean-label mandates drive plant-derived emollient sourcing. REACH compliance deadlines and ISO 16128 certification requirements are reshaping supplier qualification toward backward-integrated rice bran processors.
Japan
Captive rice bran oil refining secures feedstock continuity for cosmetic ingredient suppliers serving domestic and export markets. METI industrial standards and PMDA pharmaceutical-grade specifications tighten purity documentation requirements. Tokyo-Osaka corridor hosts specialized oleochemical technical institutes advancing molecular distillation capabilities.
Germany
Personal care headquarters operations mandate eighteen-to-twenty-four-month supply agreements with REACH-registered Asian suppliers. ECHA authorization deadlines for C16-C18 fatty alcohols compress procurement timelines toward compliant processors. Frankfurt and Düsseldorf procurement hubs audit supplier relationship depth under sustainability frameworks.
Thailand
Rice bran oil refining clusters integrate downstream alcohol distillation to shorten feedstock-to-product lead times. National industrial standards align with export market requirements for cosmetic and surfactant applications. Bangkok-Rayong processing corridor concentrates flake-format production for containerized European export.
United States
FDA cosmetic ingredient guidance shapes import purity thresholds for rice bran fatty alcohol formulations. Clean-label positioning among mass-market personal care brands pulls volume toward plant-derived emollient alternatives. New Jersey and California formulation centers specify batch-level traceability documentation.
India
CDSCO tightening of excipient standards creates first-mover advantage for suppliers achieving certified purity tiers in pharmaceutical applications. BIS standards for cosmetic raw materials add compliance layers for multi-market access. Maharashtra and Gujarat processing zones develop pharmaceutical-grade distillation capacity.
Rice Bran Fatty Alcohols Market Competitive Landscape
Player mix skews toward Asian specialists with captive rice bran supply and Western diversified chemical houses extending biosurfactant portfolios. Market structure concentrates around Japanese and Thai backward-integrated processors and multinational oleochemical divisions. Strategic archetypes include rice-derived oleochemistry pure-plays, diversified surfactant suppliers, and regional wax refiners. Competitive moves center on long-term offtake contracting and supercritical CO2 extraction technology licensing.
Among Japanese specialists, NOF CORPORATION and Oryza Oil & Fat Chemical occupy positions exemplifying captive feedstock integration and deep rice-derived oleochemistry specialization. Eastman Chemical Company represents the diversified chemical house archetype competing through Asia-Pacific supply chain extension. These three anchors illustrate the competitive tension between regional feedstock control and global formulation reach.
| Leading Market Players |
|---|
| NOF CORPORATION |
| Oryza Oil & Fat Chemical |
| SVR Gaia |
| Shanghai Lithy One Health Group Technology |
| Wuyi Zhenwei Biological Science and Technology |
| Xian Tianbao Bio-Tech |
| Huzhou Shengtao Biotech |
| Shaanxi Yuan Bang BIO-TECH |
| Eastman Chemical Company |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracting with rice bran oil indexation locks in feedstock access and price visibility for European personal care formulators facing ECHA REACH compliance deadlines. This contract structure compresses spot-market liquidity while concentrating procurement power among backward-integrated Thai and Japanese processors with captive wax supply.
Pricing Analysis
Cost-plus contracts with rice bran oil futures indexation dominate procurement between Southeast Asian refiners and European surfactant manufacturers. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade certification levels reflects purity documentation burdens. Price differentiation hinges on REACH registration status and batch-level PAH traceability. Pricing pressure stems from competing food-oil demand during rice milling seasonality. Agricultural chemical blenders exhibit highest price sensitivity; pharmaceutical excipient buyers accept premium tiers for certified purity.
Supply Chain Analysis
Thailand, Vietnam, and Japan anchor rice bran fatty alcohol production through integrated oil refining and molecular distillation clusters. Feedstock supply draws from rice milling byproduct streams, hexane or supercritical CO2 extraction solvents, and hydrogenation catalysts for alcohol conversion. Single-source geography risk concentrates in flood-prone Mekong Delta agricultural zones. Distribution runs through containerized flake export to Rotterdam and Hamburg, with liquid bulk delivery to South Korean cosmetic manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rice bran fatty alcohols occupy an early-cycle expansion phase as clean-label cosmetic mandates accelerate plant-derived emollient penetration beyond niche organic segments.
For Market Incumbents: Secure captive rice bran wax supply through tolling agreements with Thai rice millers before CDSCO pharmaceutical-grade certification tightens qualified supplier lists. Invest in supercritical CO2 extraction licensing to defend margin structures against hexane residue compliance cost escalation. Molecular distillation capacity expansion at Japanese technical institutes represents the priority capability anchor. For New Entrants and Emerging Players: Pharmaceutical-grade excipient certification gaps in Indian and Brazilian markets present white-space entry points where incumbent coverage remains thin. Target CDSCO-registered purity tiers for topical ointment bases ahead of excipient standard tightening. Pursue joint development agreements with South Korean cosmetic houses seeking cold-process organic certification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among backward-integrated processors with eighteen-to-twenty-four-month offtake contracts from German personal care headquarters operations. Long-term viability over the next decade hinges on REACH-registered capacity positions in Thailand and Vietnam. Monitor ECHA authorization timeline acceleration as the inflection signal for procurement consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rice Bran Wax Supply | Captive feedstock secures margin defense against milling seasonality and food-oil competition. |
| Supercritical CO2 Extraction Licensing | Non-thermal recovery enables cold-process certification for premium organic cosmetic labels. |
| Long-term Supply Agreement with European Formulators | Eighteen-month contracts lock in REACH-compliant volumes ahead of authorization deadlines. |
| Pharmaceutical-Grade Distillation Capacity Addition | CDSCO tightening in India compresses qualified supplier lists toward certified-purity tiers. |
| Joint Venture with Thai Rice Milling Consortiums | Bangkok-Rayong corridor integration shortens feedstock-to-product lead times for export markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with oleochemical plant managers, procurement leads at personal care OEMs, distribution channel partners, and technical R&D directors; and secondary validation through customs/trade data, REACH registration databases, SEC 10-K filings of listed chemical houses, and ISO 16128 certification records. Bottom-up volume modeling triangulated against top-down market sizing across grade tiers and end-use verticals.
Across the analysis window, the forecast framework segmented by product type, application, end-user industry, and regional production hub to capture purity-premium dynamics. CAGRs were derived from regression analysis of historical price-volume relationships and forward projection of regulatory compliance cost absorption. Key inputs included rice bran oil futures volatility patterns and ECHA authorization timeline scenarios.
Underlying assumptions cover REACH registration completion rates, rice milling byproduct availability, and supercritical CO2 extraction adoption curves, with deviation risk concentrated in climate disruption to Southeast Asian agricultural zones and pharmaceutical-grade yield ceiling constraints. Recalibration cycles align with material shifts in ECHA enforcement intensity and CDSCO excipient standard implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.