
 Global Butter Market | 2026-2036
Global Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Butter Market Analysis
Asset-light dairy processing arrangements are narrowing the capital barrier for regional creameries to challenge incumbents. Fonterra Co-operative Group leverages its New Zealand grass-fed supply base to command premium export pricing. Arla Foods anchors its competitive position through farmer-owned cooperative governance across Northern Europe. Groupe Lactalis dominates continental European retail channels with vertically integrated cream sourcing.
Butter is a water-in-fat emulsion derived from churned cream, typically containing 80-82% milk fat, 16-18% moisture, and trace milk solids, produced through batch or continuous phase-inversion churning for culinary, industrial baking, and direct consumption applications. Salted butter occupies the largest volume share in retail due to extended shelf stability and flavor preference, while organic butter captures expanding margin pools as certification premiums widen. Clarified butter concentrates within food service and confectionery channels where higher smoke points and longer fry-life justify unit price premiums.
The EU Green Deal and F-Gas Regulation constrain energy-intensive churning operations, while FDA standards in the United States enforce minimum milk-fat thresholds that define grade labeling and interstate commerce eligibility. India's FSSAI implements progressively stricter adulteration testing that reshapes import acceptance criteria for foreign butter suppliers. Stakeholders must monitor diverging carbon-accounting rules and fat-standard enforcement as these frameworks increasingly determine market access rather than merely product composition.
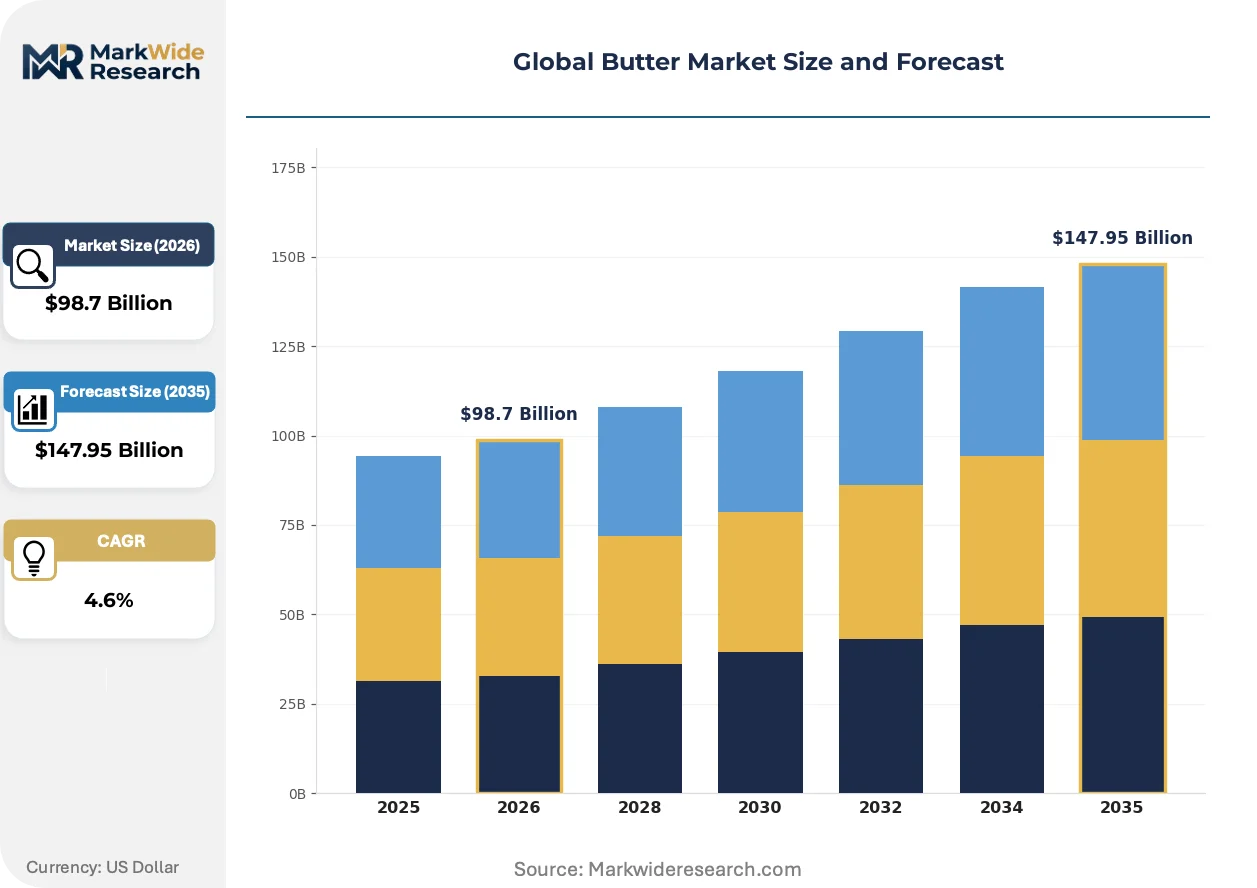
Market Dynamics
The EU F-Gas Regulation is compressing margins across energy-intensive churning operations while simultaneously accelerating capital redeployment toward low-carbon creamery retrofits. This regulatory pressure intersects with grass-fed certification premiums that now command measurable price separation in export markets.
Growth Catalysts
- EU Green Deal carbon-accounting mandates:Clean-label requirements are forcing food service operators to expand butter procurement for premium menu items, directly lifting volume through verified supply chains.
- Traditional creamery operations in France:Continental supply concentration around heritage churning methods creates authenticated provenance that retail buyers leverage for private-label differentiation.
- Continuous phase-inversion churning technology:Industrial bakeries are adopting automated churning systems that reduce batch variability and extend production runs for frozen dough applications.
Market Restraints
- Milk fat input volatility:Cream supply fluctuations in New Zealand and Australia transmit directly to butterfat pricing, compressing processor margins during drought cycles.
- Supply concentration in Northern European cooperatives:Farmer-owned governance structures limit spot market liquidity and constrain price discovery for non-member buyers.
- Plant-based fat emulsion substitution:High-oleic sunflower and coconut oil blends are displacing clarified butter in commercial frying applications where smoke point is the primary selection criterion.
Strategic Opportunities
- Underpenetrated organic certification in Poland and Romania:Eastern European dairy herds transitioning to pasture-based systems can capture widening EU organic premiums before supply saturation.
- Direct-to-chef distribution platforms:Specialty food service aggregators are bypassing traditional wholesale channels to connect artisan creameries with restaurant procurement teams.
- Convergence of blockchain traceability with carbon labeling:Integrated verification systems enable real-time methane accounting that commands separate pricing tiers in German and Dutch retail.
Industry Challenges
- Retrofit engineering expertise scarcity:Low-temperature churning upgrades require process engineers familiar with both dairy microbiology and heat-pump integration, a skill combination concentrated in Denmark and the Netherlands.
- FSSAI adulteration testing compliance timelines:Indian import acceptance criteria now mandate third-party laboratory certification that extends shipment clearance by 14-21 days.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Butter Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $147.95 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salted, Unsalted, Organic, Clarified Application: Baking, Cooking, Spreading, Saucing Packaging Type: Blocks, Tubs, Sticks, Sachets Customer Type: Retail, Food Service, Confectionery, Dairy Processors |
| Companies Covered | Fonterra Co-operative Group, Arla Foods, Groupe Lactalis, Dairy Farmers of America, Ornua Co-operative Ltd., Land O'Lakes, Inc., Koninklijke FrieslandCampina NV, Saputo Inc., Nestlé SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Butter Market Emerging Trajectories
Digital twin technology is virtualizing creamery operations while regulatory carbon-accounting frameworks harden into market access requirements. These forces are compressing the advantage window for incumbent processors that lag in data infrastructure.
Continuous butter-making systems equipped with inline moisture sensors and automated fat-standard adjustment are virtualizing quality control that previously required manual sampling and laboratory verification. Large-scale industrial bakeries in Germany and Japan are adopting these systems to reduce batch rejection rates and harmonize output across multi-site production networks. The technology is virtualizing the role of experienced churn operators, compressing labor cost structures while raising capital barriers for smaller creameries.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in dairy refrigeration, forcing processors to retrofit cold-chain infrastructure with ammonia or CO2 systems. This industrial consequence is concentrating investment among cooperatives with balance-sheet capacity to absorb upfront capital costs. French and Irish creameries are responding fastest, leveraging national green-transition credit facilities that reduce payback periods for energy-efficient churning and storage equipment.
Food service procurement teams are consolidating supplier relationships around single-source butter contracts that bundle volume commitments with carbon-intensity reporting. This buying-pattern change is displacing spot-market purchasing that previously dominated restaurant and hotel supply chains. The shift is most visible in Nordic countries where municipal procurement guidelines now require documented climate footprints for all dairy inputs in public sector catering contracts.
Global Butter Market Segmentation
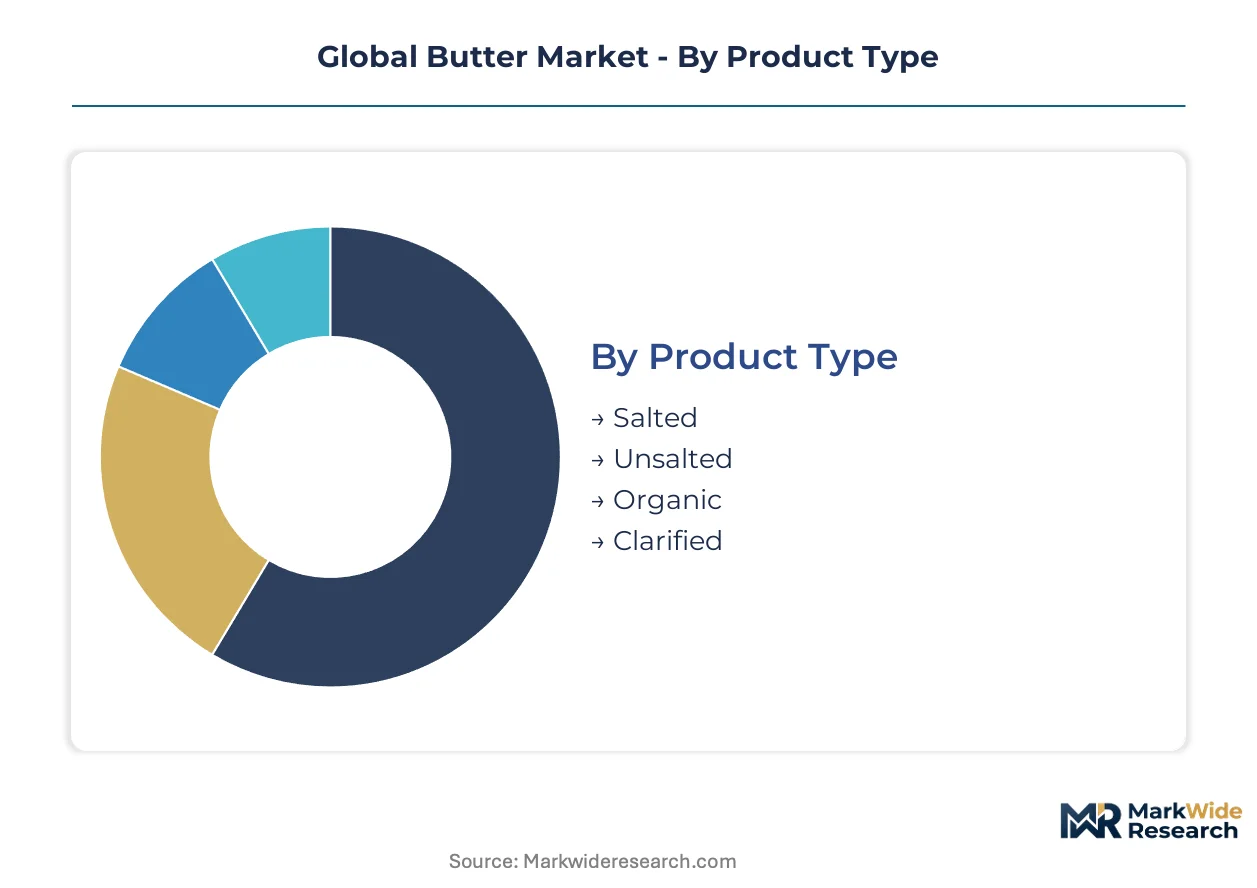
Butter segmentation reveals how product specifications, packaging formats, and channel requirements fragment procurement patterns across the value chain. Technical standards for milk-fat content, moisture thresholds, and salt levels create distinct supply streams that processors must maintain in parallel.
Product Type:
After-sales service intensity varies sharply across product types, with clarified butter demanding technical consultation on smoke-point performance while salted variants require minimal post-sale support.
- Salted:Contains 1.5-2.5% added sodium chloride, extending shelf stability through microbial inhibition. Retail channels in France and Ireland concentrate volume around heritage churning methods that leverage regional salt-cure traditions for private-label differentiation. Salted butter holds the largest share; momentum sits with organic certification tiers.
- Unsalted:Maintains 80-82% milk fat without sodium additives, serving industrial bakeries where recipe-controlled salt levels are mandatory. German and Japanese frozen dough manufacturers specify unsalted grades to harmonize multi-site production consistency across automated mixing systems.
- Organic:Certified pasture-based production with documented feed and veterinary protocols. Polish and Romanian dairy herds are transitioning to capture widening EU organic premiums before supply saturation.
- Clarified:Water and milk solids removed through controlled heating, yielding 99%+ milk fat with smoke points exceeding 250°C. Food service frying operations in commercial kitchens specify clarified grades where extended fry-life justifies unit price premiums.
Cost tier separation runs deepest in product type, with organic and clarified commanding measurable premiums over commodity salted grades.
Application:
Volume concentration patterns diverge by application, with baking absorbing industrial-scale output while saucing retains artisan production footprints.
- Baking:Industrial manufacturers of croissants, puff pastry, and laminated doughs require consistent plasticity and fat crystallization behavior. Continuous phase-inversion churning systems with inline moisture sensors are reducing batch rejection rates across German production networks.
- Cooking:Restaurant and hotel kitchens specify butter for sautéing, pan-searing, and sauce emulsification where flavor transfer is critical. Nordic municipal procurement guidelines now mandate documented climate footprints for all dairy inputs in public sector catering contracts.
- Spreading:Direct consumer consumption favors spreadability at refrigeration temperatures, driving demand for modified fat-crystal structures. Tub formats dominate this application through whipped and softened formulations.
- Saucing:Classical French technique demands precise emulsion stability for beurre blanc and hollandaise preparations. Direct-to-chef distribution platforms are connecting artisan creameries with restaurant procurement teams bypassing wholesale channels.
Baking holds the largest share; saucing is gaining share fastest through premium channel expansion.
Packaging Type:
Customer type dictates packaging selection, with food service operators prioritizing portion control while retail channels emphasize shelf presence and resealability.
- Blocks:Traditional 250g and 500g formats wrapped in foil or parchment, standard for European retail and professional kitchens. French creameries anchor continental supply around heritage-wrapped blocks that signal authenticated provenance.
- Tubs:Wider-mouth containers for whipped, spreadable, and blended butter variants. Japanese retail channels favor tub formats for consumer convenience and refrigeration optimization.
- Sticks:Elongated 113g (4oz) units standard in North American retail, pre-measured for recipe compliance. Stick formats support precise portioning in home baking applications.
- Sachets:Single-serve 8-10g portions for airline, hotel, and institutional food service. Sachet demand concentrates in travel and hospitality sectors where hygiene and waste reduction are prioritized.
Blocks hold the largest share; sachets are climbing the fastest through travel sector recovery.
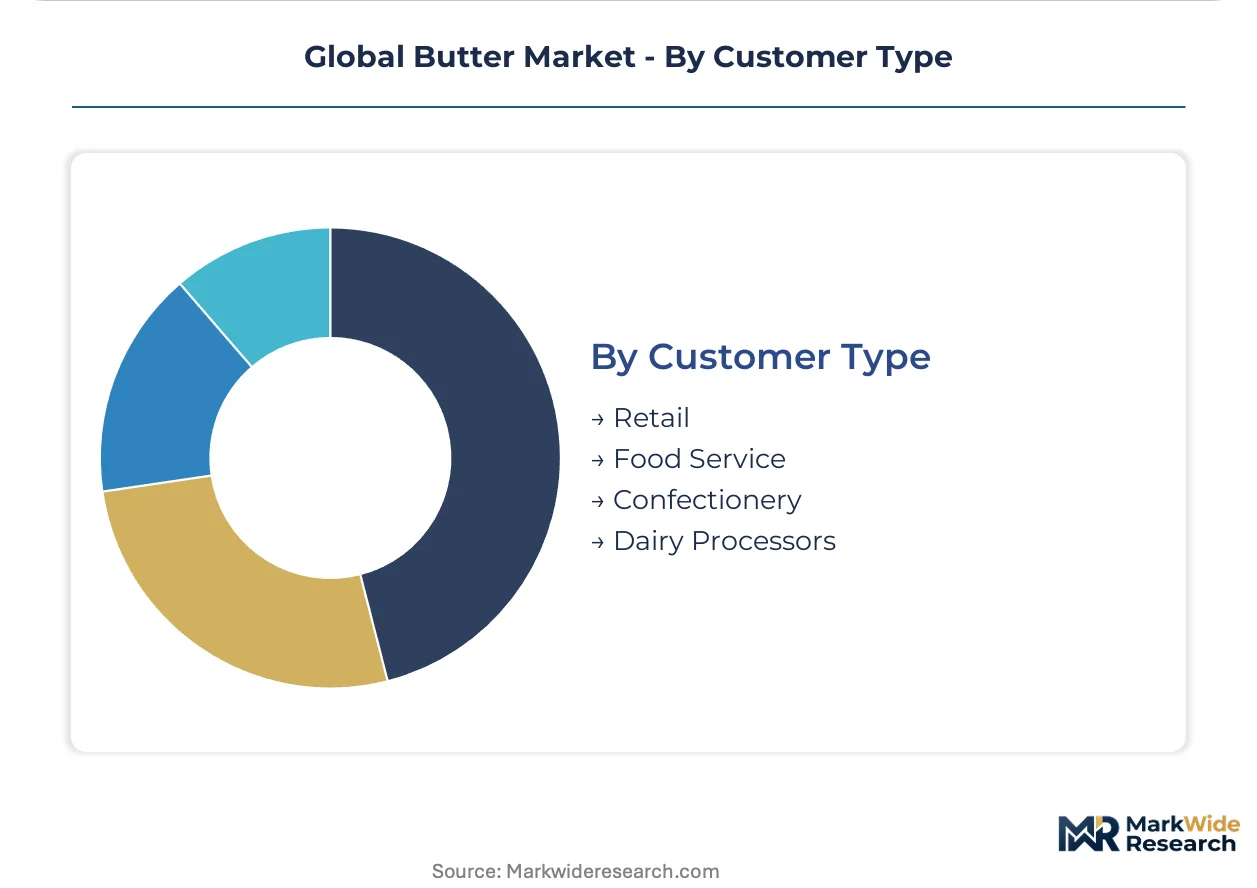
Customer Type:
Margin structure varies by customer type, with confectionery channels capturing certification premiums while dairy processors drive volume through backward integration.
- Retail:Supermarkets, hypermarkets, and specialty food stores stocking branded and private-label butter. German and Dutch retail buyers leverage blockchain traceability with carbon labeling for real-time methane accounting that commands separate pricing tiers.
- Food Service:Restaurants, hotels, catering operations, and institutional kitchens. Procurement teams are consolidating around single-source contracts bundling volume commitments with carbon-intensity reporting, displacing spot-market purchasing.
- Confectionery:Chocolate manufacturers and candy producers requiring specific fat crystallization properties for tempering and mouthfeel. Clarified butter concentrates in this channel where precise fat specifications justify technical premiums.
- Dairy Processors:Secondary manufacturers incorporating butter into ice cream, processed cheese, and recombined dairy products. Fonterra's New Zealand grass-fed supply base commands premium export pricing to this processor segment.
Retail holds the largest share; food service shows the steepest expansion trajectory through contract consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal carbon-accounting mandates are redirecting capital toward low-carbon creamery retrofits across multiple jurisdictions, while national green-transition credit facilities accelerate regional differentiation in processing capacity.
France
Heritage churning methods in Normandy and Brittany drive authenticated provenance demand from retail buyers seeking private-label differentiation. The French national green-transition credit facility reduces payback periods for energy-efficient churning equipment. Traditional creamery operations in the northwest concentrate continental supply around grass-fed certification premiums.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia specify unsalted butter grades for automated mixing system harmonization. The EU F-Gas Regulation compels refrigeration retrofits with ammonia or CO2 systems across dairy cold-chain infrastructure. Blockchain traceability with carbon labeling commands separate pricing tiers in Frankfurt and Düsseldorf retail channels.
United States
FDA minimum milk-fat thresholds enforce grade labeling that defines interstate commerce eligibility for creamery output. The Inflation Reduction Act provisions support agricultural processor energy efficiency upgrades in Wisconsin and California dairy corridors. Stick-format pre-measured packaging dominates home baking applications from Midwest production clusters.
India
FSSAI adulteration testing mandates reshape import acceptance criteria with third-party laboratory certification extending shipment clearance timelines. The country's PLI scheme for food processing incentivizes domestic butterfat capacity expansion in Gujarat and Maharashtra. Clarified butter demand concentrates in Rajasthan and Punjab commercial kitchen supply chains.
New Zealand
Grass-fed certification premiums command measurable price separation in export markets for Fonterra's cooperative members. The country's national dairy regulator enforces pasture-based production documentation for premium tier eligibility. Canterbury and Waikato processing clusters anchor Asia-Pacific export volume through dedicated cold-chain logistics.
Global Butter Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Cooperative governance structures dominate Northern European supply while publicly traded processors anchor North American retail distribution. Three archetypes prevail: farmer-owned cooperatives with balance-sheet capacity for infrastructure retrofits, vertically integrated dairy conglomerates with captive cream sourcing, and asset-light regional creameries leveraging contract manufacturing. Competitive moves concentrate on single-source contract consolidation bundling volume commitments with carbon-intensity reporting, and low-temperature churning technology licensing from Danish and Dutch engineering clusters.
Within the cooperative archetype, Fonterra Co-operative Group and Arla Foods exemplify farmer-owned governance structures that limit spot market liquidity while securing premium export positioning. Groupe Lactalis occupies a position as a vertically integrated processor with continental European retail channel control. These three entities anchor competitive dynamics through divergent capital structures rather than convergent strategic postures.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Arla Foods |
| Groupe Lactalis |
| Dairy Farmers of America |
| Ornua Co-operative Ltd. |
| Land O'Lakes, Inc. |
| Koninklijke FrieslandCampina NV |
| Saputo Inc. |
| Nestlé SA |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance costs dominate margin calculations across energy-intensive churning operations, compressing spreads between commodity and premium tiers while forcing capital redeployment toward low-carbon retrofits that reshape continental supply geography.
Pricing Analysis
Certification level creates the primary spread between organic pasture-based grades and conventional commodity butter. Three-tier pricing structure across organic, grass-fed, and standard levels reflects feed documentation costs and carbon-accounting verification. Cost compression in standard grades is intensifying because of milk fat input volatility from New Zealand and Australian drought cycles. Industrial bakeries in Germany and Japan show lowest price sensitivity due to formula-locked procurement contracts, while food service spot buyers face highest exposure to cream supply fluctuations.
Supply Chain Analysis
Single-source dependency on Northern European cooperatives concentrates churning capacity in Denmark, the Netherlands, and France. Raw material flows draw from New Zealand grass-fed herds, German and Polish dairy farms, and French Normandy creameries. Supply chain risk centers on farmer-owned governance structures that limit spot market liquidity and constrain price discovery for non-member buyers. Distribution runs through cooperative-controlled cold-chain networks for export volumes, with direct-to-chef platforms emerging as alternative channels for artisan creameries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across Eastern European organic transition zones as clean-label procurement requirements from the EU Green Deal create certified supply shortages that regional entrants can capture.
For Market Incumbents: Build regulatory compliance moats through low-temperature churning technology licensing from Danish and Dutch engineering clusters. Absorb upfront F-Gas retrofit costs using national green-transition credit facilities before smaller competitors face capital barriers. Anchor continental retail positioning through backward integration into pasture-based cream sourcing that locks in grass-fed certification premiums. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian organic certification tiers where pasture-based herd transitions lag Western European saturation. Target direct-to-chef distribution platforms that bypass cooperative-controlled wholesale channels for artisan butter volumes. Lead with blockchain-enabled carbon accounting that commands separate pricing tiers in German and Dutch retail procurement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors asset-light regional creameries with retrofit engineering partnerships. Long-term viability over the next decade rests on carbon-intensity reporting capabilities that determine contract eligibility in Nordic municipal procurement. Watch for FSSAI adulteration testing compliance delays as signal for India import opportunity windows.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Carbon Churning Retrofit | EU F-Gas Regulation mandates ammonia or CO2 refrigeration systems that concentrate investment among balance-sheet-capable cooperatives. |
| Organic Certification Expansion | Eastern European pasture-based herd transitions capture widening EU organic premiums before supply saturation in Poland and Romania. |
| Direct-to-Chef Platform Launch | Specialty food service aggregators bypass traditional wholesale channels to connect artisan creameries with restaurant procurement teams. |
| Blockchain Carbon Labeling Integration | Real-time methane accounting systems command separate pricing tiers in German and Dutch retail channels. |
| Single-Source Contract Consolidation | Food service procurement teams bundle volume commitments with carbon-intensity reporting that displaces spot-market purchasing. |
Methodological Framework
Initial hypotheses were tested against primary input from creamery operations managers, food service procurement directors, dairy cooperative board members, and retail category buyers and refined through secondary validation against Fonterra and Arla Foods cooperative disclosures, EU F-Gas regulatory filings, FSSAI import testing protocols, and customs trade data. Bottom-up volume modeling from churning capacity installations triangulated with top-down value estimates from export pricing benchmarks.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across product type, application, packaging format, and customer channel. CAGRs derived from installed churning capacity growth rates, organic certification enrollment trajectories, and food service contract volume commitments. Forecast inputs incorporated EU Green Deal carbon-accounting mandate implementation timelines and F-Gas phase-down schedules.
Sensitivities concentrate around milk fat input volatility from Oceania drought cycles, FSSAI laboratory certification clearance delays, and cooperative governance decisions on spot market liquidity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Greek Yogurt Market
Dairy Products
Milk Protein Crisps Market
Dairy Products
Dairy Blends Market
Dairy Products
United States Dairy Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
Milk Mineral Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
Ghee Market
Dairy Products
GCC UHT Milk Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
North America Cheese Market