
 Alcohol Ingredients Market | 2026-2036
Alcohol Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol Ingredients Market Analysis
European yeast and enzyme producers is repositioning capacity toward specialty fermentation aids for craft distilleries. Givaudan leverages its flavor science portfolio to anchor premium positioning in mixology applications. Kerry Group competes through integrated beverage solutions that span brewing to ready-to-drink formulations. DSM sustains R&D intensity in yeast extracts tailored for low-alcohol fermentation protocols.
Alcohol ingredients encompass flavoring agents, preservatives, colorants, and fermentation aids that modify the sensory profile, stability, and production efficiency of alcoholic beverages. These inputs typically operate at inclusion rates between 0.01% and 5% by volume, depending on functional category and target beverage matrix. Flavoring agents command the deepest margin pools as distilleries and mixology programs chase differentiated taste profiles. Fermentation aids represent the fastest-expanding category as brewers adopt accelerated yeast strains to compress production cycles. Preservatives remain structurally mature in winemaking, where sulfur dioxide alternatives face slow technical validation.
The FDA governs alcohol ingredient safety through food additive petitions and GRAS self-affirmation pathways, while the EPA regulates effluent from fermentation aid manufacturing facilities. The EU's REACH framework and F-Gas Regulation constrain preservative chemistries and processing aids entering European beverage supply chains. Stakeholders must monitor how divergent transatlantic approval timelines for novel fermentation substrates reshape sourcing geography and inventory strategy.
Market Dynamics
Accelerated yeast strain development is compressing fermentation cycles across craft and industrial brewing operations, forcing ingredient suppliers to reposition R&D portfolios toward performance-optimized fermentation aids rather than commodity inputs.
Growth Catalysts
- EU F-Gas Regulation phase-down:Brewers in Germany and Belgium are accelerating adoption of natural refrigerant-based cold stabilization methods, creating pull for compatible fermentation aid chemistries.
- Craft distillery expansion:Small-batch producers in the United States are scaling premium flavoring agent procurement as differentiated spirit portfolios multiply.
- Non-alcoholic beer protocols:Controlled fermentation technologies are unlocking new formulation possibilities for zero-ABV products targeting health-conscious demographics.
Market Restraints
- Hop and grain input volatility:Climate-induced supply fluctuations for barley and aromatic hops are compressing margin predictability for malt-based fermentation aid producers.
- REACH compliance costs:European preservative and colorant suppliers face extended validation timelines for novel chemistries entering beverage supply chains.
- Sulfur dioxide substitution limits:Technical performance gaps in alternative wine preservatives are slowing displacement of traditional stabilizers despite regulatory pressure.
Strategic Opportunities
- India FSSAI modernization:Streamlined food additive approval pathways are opening access for international fermentation aid suppliers to serve emerging domestic brewing capacity.
- Ready-to-drink channel expansion:Canned cocktail and hard seltzer formats are creating dedicated demand for shelf-stable flavoring agent systems with extended stability profiles.
- Low-alcohol fermentation convergence:Yeast extract and enzyme technology integration is enabling precise alcohol content control for mid-strength beer and wine categories.
Industry Challenges
- Bioprocess engineering talent scarcity:Specialized expertise in strain optimization and metabolic pathway engineering is concentrating at a limited set of research institutions and commercial laboratories.
- Multi-jurisdiction certification lag:Divergent FDA and EFSA approval timelines for novel fermentation substrates are forcing suppliers to maintain parallel inventory and documentation systems.
- Legacy equipment retrofit complexity:Traditional brewhouses and distilleries face capital-intensive upgrades to deploy precision fermentation monitoring and automated dosing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol Ingredients Market |
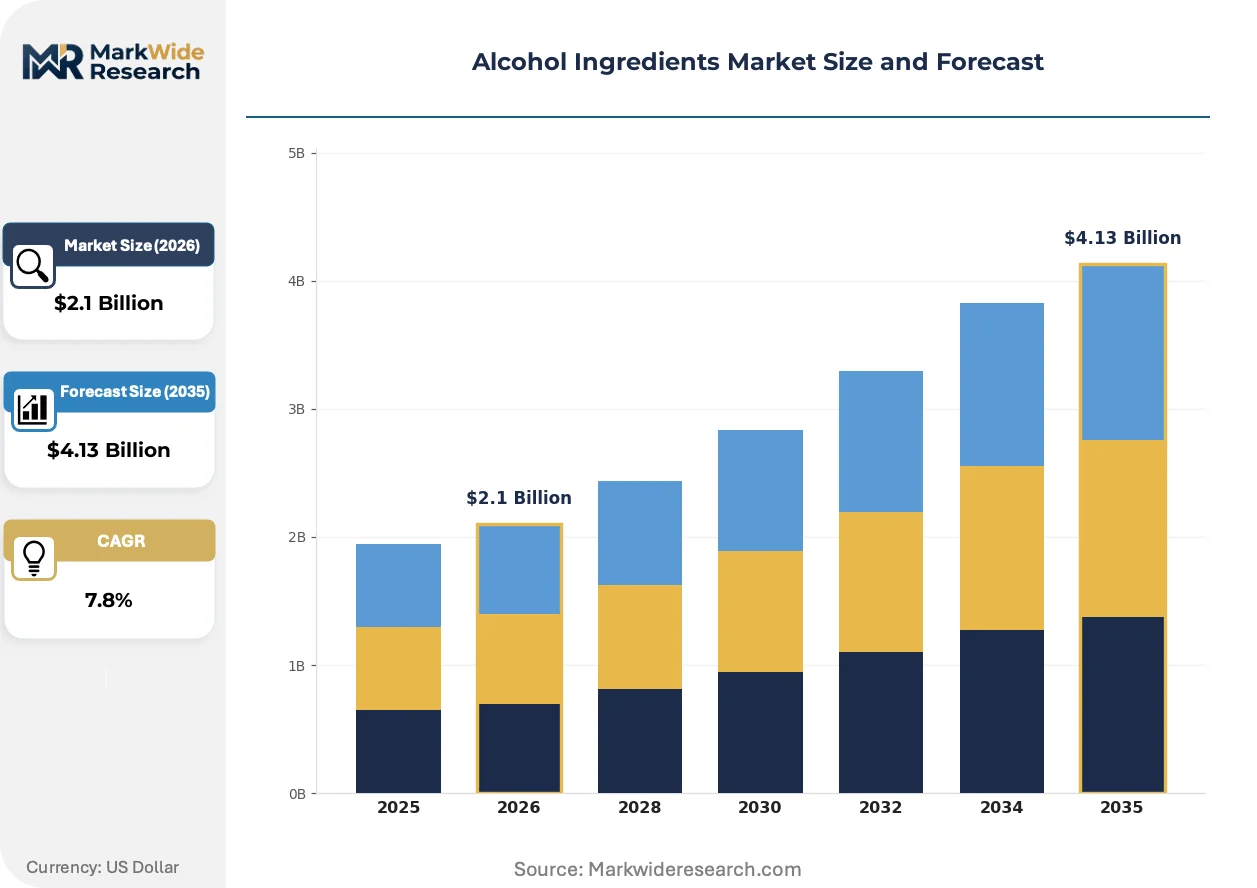
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Flavoring Agents, Preservatives, Colorants, Fermentation Aids End User: Beverage Manufacturers, Bakeries, Distilleries, Food Processors Application: Brewing, Distillation, Winemaking, Mixology Packaging Type: Bottles, Kegs, Cans, Pouches |
| Companies Covered | Givaudan, Firmenich, Kerry Group, DSM, Sensient Technologies, Cargill, ADM, Chr. Hansen, AngelYeast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol Ingredients Market Emerging Trajectories
Precision fermentation and bioengineered inputs are redefining how alcoholic beverages achieve sensory differentiation and production efficiency, compressing the gap between craft authenticity and industrial scale.
CRISPR-edited yeast strains with enhanced ester production profiles are electrifying flavor development timelines for craft distilleries and specialty brewers. These engineered organisms enable targeted aromatic compound generation without extended aging or adjunct loading. Small-batch producers in Oregon and Scotland are adopting these strains at pilot scale, compressing product development cycles from months to weeks while preserving label claims around traditional methods.
The FDA's updated GRAS self-affirmation pathway for novel fermentation substrates is accelerating commercialization timelines for bio-based processing aids. This regulatory streamlining reduces petition preparation costs and enables faster market entry for suppliers with robust safety documentation. Craft and mid-size brewers in the United States are the primary beneficiaries, gaining access to enzyme and yeast extract innovations previously delayed by procedural bottlenecks.
Direct-to-producer ingredient sourcing is displacing traditional distributor intermediaries in specialty flavoring agent procurement. Distilleries with established mixology programs are building captive relationships with botanical suppliers and extraction specialists, unbundling quality control and traceability from conventional wholesale channels. This pattern is most pronounced in California and Kentucky, where provenance marketing and terroir claims drive formulation decisions.
Alcohol Ingredients Market Segmentation
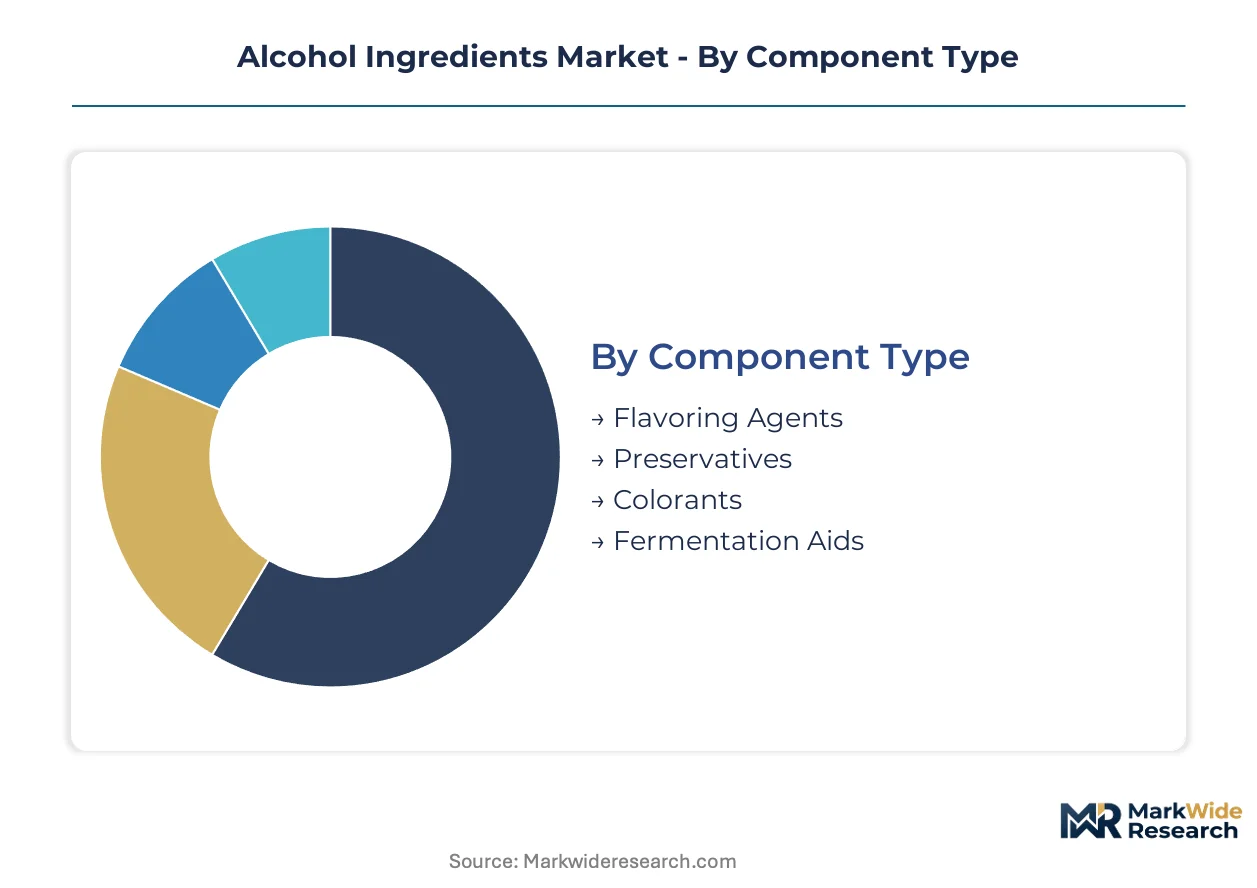
Ingredient buyers in alcoholic beverages prioritize functional performance, regulatory compliance, and sensory differentiation across distinct procurement channels. Segmentation reveals how supplier portfolios must align with divergent technical requirements between industrial-scale brewing and craft distillery operations.
Component Type:
Procurement decisions in this category pivot on margin contribution and formulation complexity, with premium positioning commanding deeper supplier relationships.
- Flavoring Agents:Botanical extracts, essential oils, and synthetic aromatic compounds modify taste profiles at inclusion rates between 0.01% and 0.5% by volume. Distilleries in Kentucky and Scotland concentrate demand here as provenance marketing and terroir claims drive formulation investments.
- Preservatives:Sulfur dioxide, sorbates, and dimethyl dicarbonate chemistries stabilize finished beverages against microbial spoilage and oxidation. Winemakers in France and Italy represent the core demand base, though technical validation gaps for sulfur dioxide alternatives constrain substitution timelines.
- Colorants:Caramel, anthocyanin, and synthetic dye formulations adjust visual presentation across beer, spirits, and ready-to-drink categories.
- Fermentation Aids:Yeast strains, enzymes, and yeast extracts accelerate or control metabolic pathways during production.
Flavoring agents lead on scale; fermentation aids lead on momentum.
End User:
Volume concentration and technical sophistication diverge sharply across buyer types, dictating differentiated sales and service models from suppliers.
- Beverage Manufacturers:Large-scale brewers and diversified drinks companies procure fermentation aids and preservatives through long-term supply agreements with stringent quality specifications. Industrial facilities in Germany and the United States dominate volume offtake, compressing ingredient margins through consolidated procurement.
- Distilleries:Small-batch and industrial spirit producers source flavoring agents and specialized fermentation aids for differentiated product portfolios. Craft operations in Oregon and Islay, Scotland, prioritize botanical traceability and strain provenance over unit cost.
- Bakeries:Cross-over demand for fermentation aids supports alcohol-adjacent applications in yeast-leavened products.
- Food Processors:Industrial kitchens and prepared food manufacturers utilize alcohol-based flavoring systems in sauces and marinades.
Beverage manufacturers anchor procurement volume; distilleries drive premium segment expansion.
Application:
Process chemistry and regulatory exposure vary by production method, shaping ingredient specification requirements and approval pathway complexity.
- Brewing:Malt-based fermentation relies on enzyme adjuncts and accelerated yeast strains to compress cycle times and standardize output. Brewers in Belgium and the Czech Republic concentrate demand for traditional lager protocols, while German facilities pioneer non-alcoholic beer fermentation controls.
- Distillation:Column and pot still operations require specialized yeast extracts and flavoring agents that survive high-temperature separation. Scottish and American whiskey producers represent the most technically demanding customer segment for fermentation aid suppliers.
- Winemaking:Grape must fermentation and post-fermentation stabilization depend on sulfur dioxide and emerging alternative preservatives.
- Mixology:Bar programs and ready-to-drink formulations source concentrated flavoring agents and colorants for cocktail consistency.
Brewing commands the largest ingredient volume; distillation extracts the highest per-unit value.
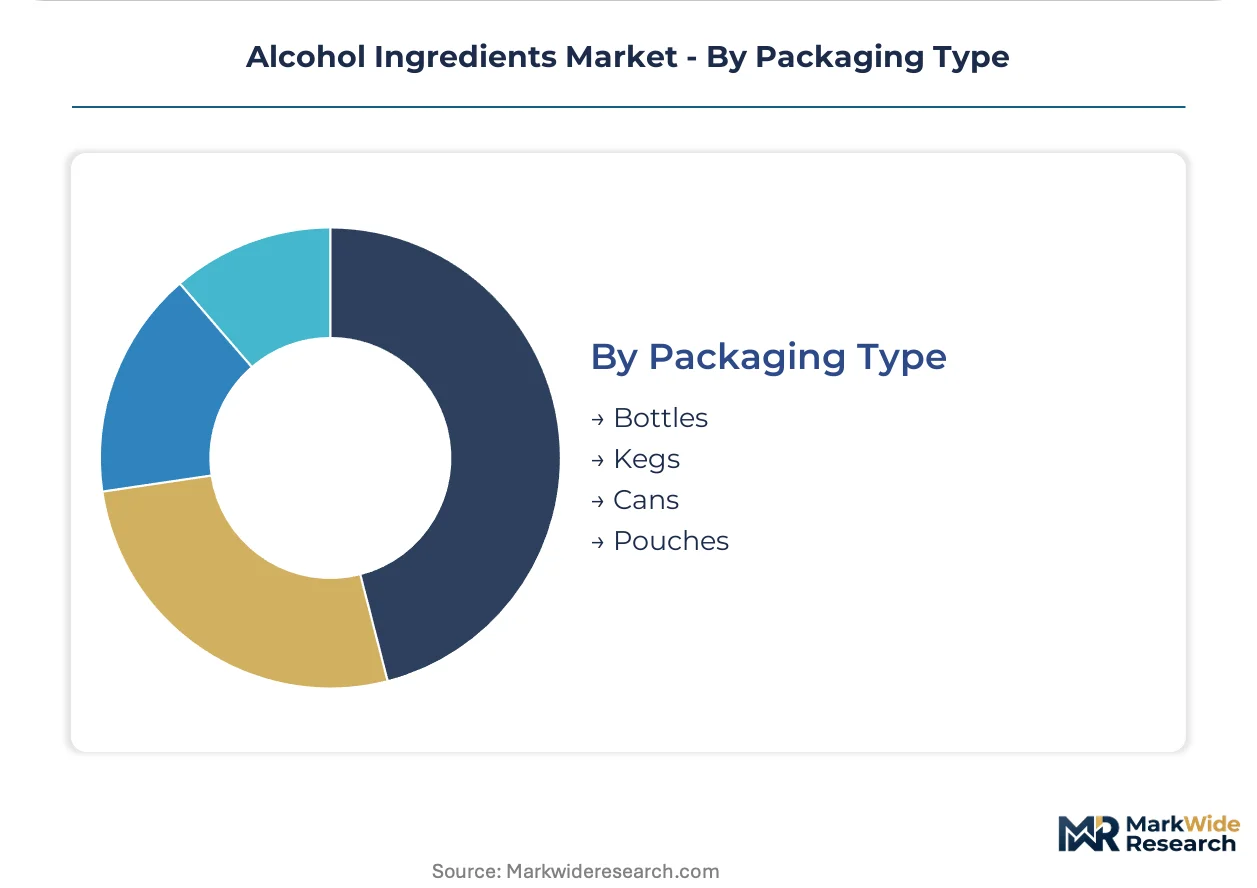
Packaging Type:
Stability requirements and shelf-life specifications dictate ingredient selection, with portable formats imposing the most demanding technical constraints.
- Cans:Aluminum formats require oxygen-scavenging preservatives and light-stable colorants to prevent metallic off-flavors and photochemical degradation. Hard seltzer and canned cocktail producers in the United States drive fastest-expanding demand for compatible stabilization chemistries.
- Bottles:Glass packaging accommodates broader ingredient tolerances but still requires sulfur dioxide or sorbate preservation for wines and some spirits. Traditional wineries in France and Italy remain anchored to bottle formats with established closure and preservation protocols.
- Kegs:Draft dispensing systems demand microbial stability without pasteurization, favoring specific fermentation aid and preservative combinations.
- Pouches:Flexible packaging for ready-to-drink cocktails requires barrier-compatible flavoring agents with extended stability profiles.
Bottles retain volume leadership; cans gain share fastest in flavoring agent procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge sharply in ingredient procurement priorities, with German brewers driving non-alcoholic fermentation innovation while American distilleries chase premium flavor differentiation.
United States
Craft distillery proliferation in Kentucky and Oregon concentrates demand for botanical traceability and terroir-linked flavoring agents. The FDA's streamlined GRAS self-affirmation pathway accelerates novel fermentation substrate approvals. California's mixology-forward producers are building direct sourcing relationships with extraction specialists, bypassing traditional wholesale channels.
Germany
Traditional brewing culture in Bavaria intersects with zero-ABV innovation as controlled fermentation protocols gain commercial traction. The EU F-Gas Regulation phase-down pushes breweries toward natural refrigerant-compatible cold stabilization chemistries. Cologne and Düsseldorf anchor industrial-scale procurement for malt-based fermentation aids serving both domestic and export markets.
Belgium
Specialty beer producers in Flanders and Wallonia concentrate demand for accelerated yeast strains that compress traditional lambic and Trappist production cycles. REACH compliance requirements extend validation timelines for novel preservative chemistries entering beverage supply chains. Brussels hosts regulatory expertise clusters that advise ingredient suppliers on multi-jurisdiction certification strategies.
India
Domestic brewing capacity expansion in Maharashtra and Karnataka creates pull for international fermentation aid suppliers. FSSAI modernization streamlines food additive approval pathways previously constrained by procedural bottlenecks. Bangalore's emerging craft beer scene drives pilot-scale procurement of enzyme adjuncts and specialty yeast extracts.
France
Winemakers in Bordeaux and Burgundy remain anchored to sulfur dioxide preservation despite regulatory pressure for alternatives. EFSA validation timelines for novel wine stabilizers lag FDA counterparts, slowing chemistry substitution. Champagne houses are testing precision fermentation monitoring systems that integrate with legacy cellar infrastructure.
Alcohol Ingredients Market Vendor Landscape
European producers anchor the premium-tier ingredient segment; North American specialists hold scale advantages in fermentation aid manufacturing. The vendor base splits between consolidated flavor science portfolios and fragmented strain optimization laboratories. Three archetypes dominate: integrated beverage solution providers, precision fermentation technology developers, and botanical extraction specialists. Capacity expansion and direct-to-producer sourcing relationships constitute the primary competitive vectors reshaping supplier positioning.
Within the integrated solution tier, Kerry Group and DSM exemplify portfolio breadth spanning brewing to ready-to-drink applications. Givaudan occupies a position representing flavor science depth for mixology and premium spirit applications. These three entities anchor the competitive structure without exhausting the vendor landscape, as regional yeast producers and specialty extraction houses occupy adjacent market positions.
| Leading Market Players |
|---|
| Givaudan |
| Firmenich |
| Kerry Group |
| DSM |
| Sensient Technologies |
| Cargill |
| ADM |
| Chr. Hansen |
| AngelYeast |
| Others |
Supply Flow & Price Mechanics
Barley futures volatility cascades through malt supply chains into three-tier pricing stratification across premium craft, standard industrial, and economy bulk fermentation aid tiers, compressing margin buffers for mid-tier suppliers caught between provenance premiums and volume discounts.
Pricing Analysis
Distributor margins of 15-25 percent separate direct-to-distillery procurement from wholesale channel pricing, with premium botanical extracts commanding certification-grade premiums while commodity yeast extracts face cost compression from consolidated brewery procurement. Price differentiation hinges on organic certification status and strain traceability documentation. Margins are tightening in standard-tier fermentation aids as accelerated yeast R&D costs outpace volume scaling. Craft distilleries exhibit lowest price sensitivity; economy-tier beverage manufacturers anchor procurement to spot-market commodity indexes.
Supply Chain Analysis
India's FSSAI domestic-content preferences for food additive approvals are reshaping sourcing patterns for international suppliers seeking market access. Manufacturing concentrates in Germany, the United States, and China, with specialty strain development anchored in European biotechnology clusters. Raw material flows draw from Argentinian barley, Chinese sorghum, and European hop derivatives. Single-source vulnerability concentrates in CRISPR-edited yeast strain IP held by limited research institutions. Distribution runs through regional beverage ingredient distributors with direct-to-producer bypass emerging in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in fermentation aid premiumization and supply chain digitization, with automated dosing system adoption reducing per-batch labor costs across craft and industrial operations.
For Market Incumbents: Deepen captive relationships with craft distillery clusters in Kentucky and Oregon through integrated strain development and flavor science partnerships. Expand backward integration into botanical extraction to defend margin position against direct-to-producer sourcing trends. Prioritize FDA GRAS self-affirmation pathway investments to accelerate novel substrate commercialization timelines.
For New Entrants and Emerging Players: The premium-to-economy price gap in fermentation aids offers entry space for mid-tier suppliers with specialized strain optimization capabilities. Target India's emerging craft brewing capacity in Maharashtra and Karnataka with pilot-scale enzyme adjunct offerings. Pursue regulatory-first go-to-market positioning by securing FSSAI approvals ahead of manufacturing scale commitments.
For Investors and Strategic Acquirers: Consolidation pressure builds where strain optimization IP concentrates at limited research institutions and commercial laboratories. Long-term viability favors vertically integrated platforms spanning extraction to fermentation aid manufacturing. Watch FDA-EFSA approval timeline convergence as signal for geographic sourcing strategy inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | CRISPR-edited yeast strain production compresses craft distillery product development cycles. |
| Direct-to-Producer Sourcing Platform | California mixology programs bypass distributors for botanical traceability and terroir claims. |
| Regulatory Certification Fast-Track | FDA GRAS self-affirmation investments accelerate novel fermentation substrate market entry. |
| Backward Integration into Extraction | Captive botanical supply secures margin pools in premium flavoring agent categories. |
| Joint Venture with Research Institutions | Strain optimization partnerships address bioprocess engineering talent scarcity constraints. |
Methodological Framework
Direct dialogue with fermentation aid procurement managers, craft distillery operations heads, regulatory affairs specialists at ingredient suppliers, and brewery technical directors grounded qualitative findings in operational reality. Secondary validation drew from FDA GRAS notification databases, EFSA food additive opinions, FSSAI approval registers, and customs trade flow records. Bottom-up strain-level demand estimates triangulated against top-down beverage production volume projections.
Segmented outputs across component type, end user, application, and packaging format dimensions calibrated penetration assumptions throughout the projection horizon. CAGRs derived from historical price-volume relationships and forward-looking regulatory impact assessments. Forecast inputs incorporated EU F-Gas Regulation phase-down timelines and India brewing capacity expansion trajectories.
Caveats apply where FDA-EFSA approval timeline divergence or climate-induced barley supply disruptions could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Chewing Gum Base Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Europe Dairy Ingredients Market
Ingredients
Rendered Products Market
Ingredients
Egg Yolk Powder Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Potato Flour Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
Jojoba Oil Market
Ingredients
Homecare Ingredients Market
Ingredients
Global Starch Derivatives Market
Ingredients
Ingredients Market
Ingredients
Moringa Ingredients Market
Ingredients
Honey Powder Market
Ingredients
Spain Sodium Reduction Ingredient Market