
 Africa Compound Chocolate Market | 2026-2036
Africa Compound Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Compound Chocolate Market Outlook
Cold-pressing and enzymatic refining is narrowing the sensory gap between compound chocolate and couverture across African processing lines. Cargill Incorporated leverages its Ghanaian cocoa sourcing infrastructure to anchor regional supply security. The Barry Callebaut Group competes through technical service partnerships with industrial bakeries in Nigeria and Kenya. Nestle SA dominates ready-to-use compound coatings for ice cream and biscuit applications through its East African manufacturing footprint.
Africa compound chocolate replaces cocoa butter with vegetable fats such as palm oil or shea stearin, typically containing 5-35% cocoa powder and achieving melting profiles between 32°C and 38°C for tropical stability. Milk Compound leads product type demand due to its cost position and compatibility with mass-market confectionery, while Dark Compound captures premium positioning in South African specialty channels. Hypermarkets and Supermarkets anchor distribution volume, though Online Retail records the fastest expansion as Nigerian and Kenyan e-grocery platforms build ambient confectionery logistics.
Ghana's Food and Drugs Authority and Nigeria's NAFDAC enforce compositional labeling that separates compound from chocolate, compelling manufacturers to reformulate for compliance. South Africa's Department of Health applies FSSC 22000-aligned safety audits to imported coatings, raising barriers for non-certified Asian suppliers. East African Community harmonization talks on confectionery standards remain unresolved, leaving Kenya, Tanzania, and Uganda with divergent import protocols. Stakeholders must monitor regulatory convergence timelines and shea butter supply volatility as dual determinants of formulation strategy.
Market Dynamics
Industrial bakeries across West Africa are accelerating compound chocolate procurement as a cocoa butter substitute, while shea stearin supply volatility and divergent East African Community labeling standards force continuous formulation recalibration.
Growth Catalysts
- NAFDAC Labeling Mandates:Nigeria's enforcement of compositional separation between compound and pure chocolate compels manufacturers to standardize formulations, creating compliant volume demand.
- Urban Bakery Chain Expansion:Lagos and Accra-based industrial bakeries scale output for snack and biscuit lines, pulling compound coatings into centralized procurement.
- Shea Butter Fractionation:Cold-pressing advances in Burkina Faso and Mali improve shea stearin yields, tightening the sensory gap with cocoa butter at lower input cost.
Market Restraints
- Palm Oil Price Volatility:Malaysian and Indonesian palm oil futures swing compound chocolate input costs, compressing margin predictability for Nigerian converters.
- Asian Supplier Certification Gap:South Africa's FSSC 22000-aligned import audits block non-certified Asian coating shipments, limiting supply source diversification.
- Cocoa Powder Quality Variance:Inconsistent alkalization levels from Ivorian and Ghanaian processors create batch-to-batch viscosity control failures in industrial lines.
Strategic Opportunities
- Kenya E-Grocery Logistics:Jumia and Glovo ambient confectionery fulfillment networks open direct-to-bakery distribution channels bypassing traditional wholesale layers.
- Tanzania Confectionery Underpenetration:Dar es Salaam's nascent industrial bakery sector offers first-mover positioning for compound coating technical service partnerships.
- East African Community Harmonization:Pending regional standards convergence would eliminate Kenya-Tanzania-Uganda import protocol friction, enabling centralized manufacturing scale.
Industry Challenges
- Food Technologist Scarcity:Nigerian and Ghanaian universities produce insufficient lipid chemistry specialists for tropical fat formulation optimization.
- Dual Certification Burden:Exporters to South Africa must simultaneously satisfy FSSC 22000 and Department of Health safety audit timelines, extending market entry cycles.
- Legacy Equipment Retrofit Costs:Confectionery lines engineered for cocoa butter require temperature control modifications to process shea stearin-based compounds without bloom defects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Compound Chocolate Market |
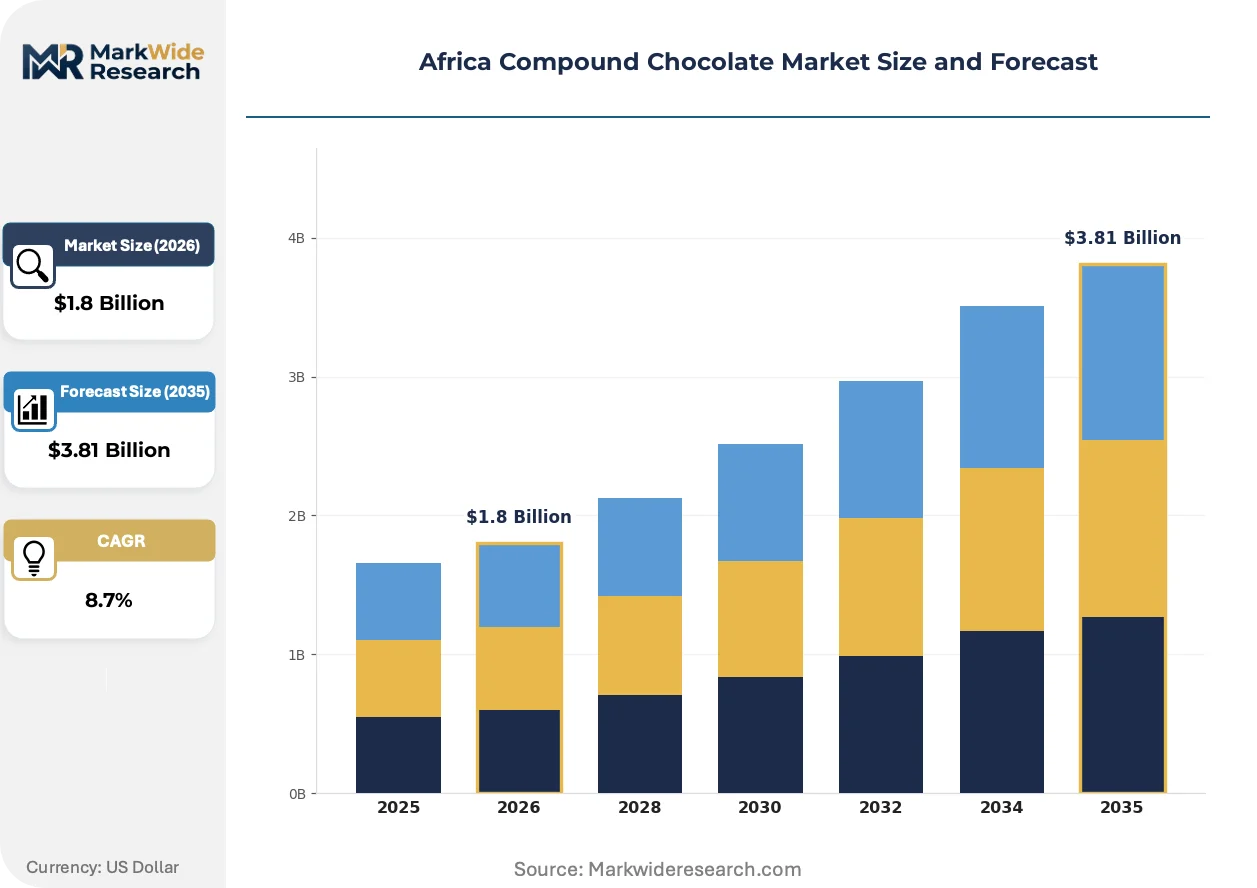
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Compound, Milk Compound, White Compound, Flavored Compound Application: Baking, Confectionery, Dairy Products, Snacks Distribution Channel: Hypermarkets, Supermarkets, Online Retail, Specialty Stores End User: Manufacturers, Bakers, Restaurants, Retailers |
| Companies Covered | Cargill Incorporated, Puratos, The Barry Callebaut Group, Aalst Wilmar Pte Ltd, The Bühler Holding AG, Mondelez International, Nestle SA, Cocoa Processing Company Limited, Tulip Cocoa Processing Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Compound Chocolate Market Strategic Shifts
Enzymatic refining and digital process control are compressing the quality differential between compound coatings and couverture, while regulatory divergence across African economic blocs forces adaptive formulation strategies.
Enzymatic interesterification is digitizing fat blend consistency in Ghanaian and Nigerian processing plants. Industrial bakeries in Lagos and Accra adopt sensor-controlled refiners at accelerating pace. This technology is digitizing real-time viscosity adjustment, reducing batch rejection rates and enabling just-in-time coating production for seasonal confectionery peaks.
Ghana's Food and Drugs Authority tightened compositional labeling thresholds for vegetable fat content in 2023, compelling reformulation of existing product lines. Manufacturers serving both Ghana and Nigeria must now maintain dual label inventories. Milk Compound segments targeting premium South African channels absorb the highest compliance cost burden.
Bakery procurement managers in Nairobi and Lagos consolidate supplier relationships around technical service capability rather than price alone. Single-source compound coating partnerships displace fragmented multi-vendor purchasing. Kenya's industrial biscuit producers exhibit the most concentrated buyer behavior, negotiating annual volume contracts with embedded formulation support.
Africa Compound Chocolate Market Segmentation
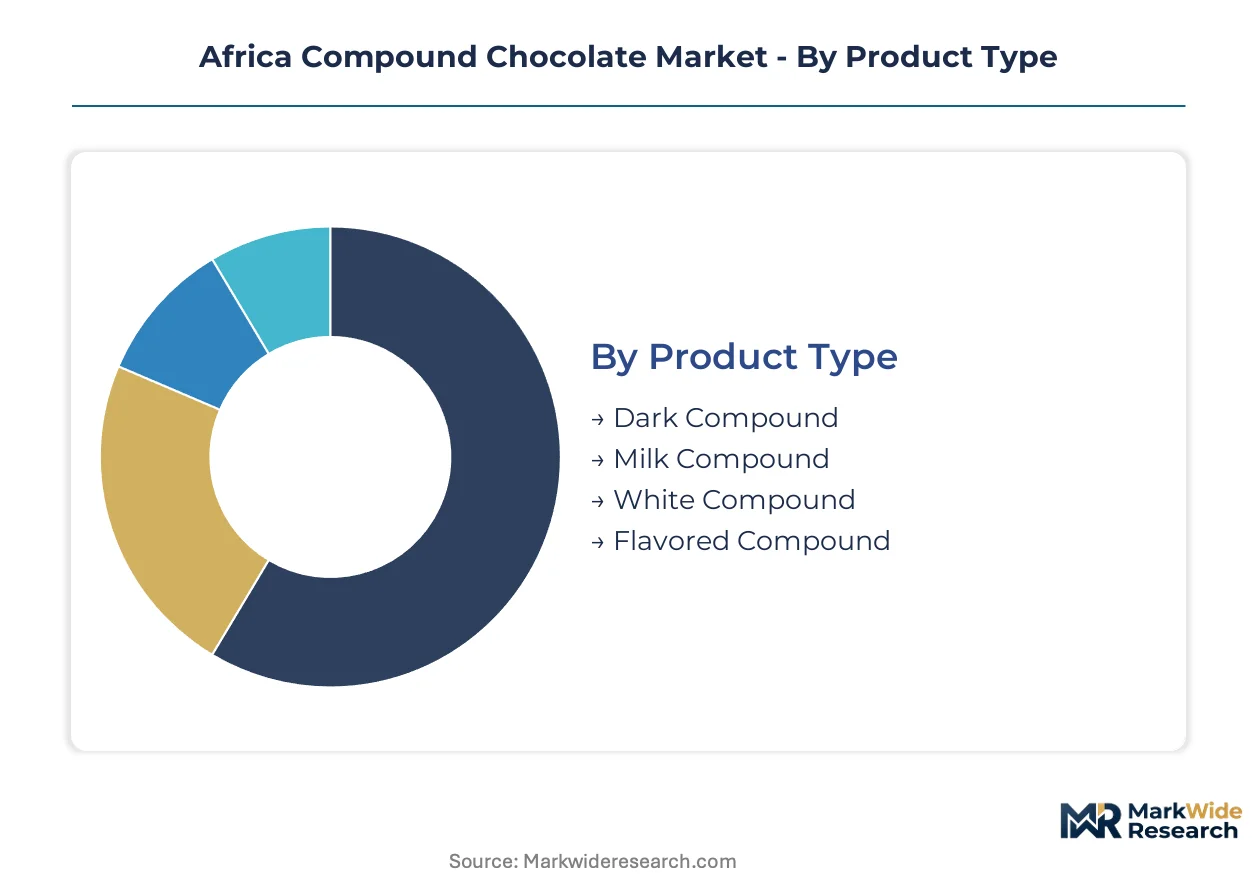
Compound chocolate formulation choices across Africa track divergent cost pressures, tropical climate requirements, and regulatory labeling mandates. Procurement managers in Lagos and Accra calibrate segment selection against shea stearin availability and cocoa powder quality variance.
Product Type:
Industrial applications span from mass-market biscuit coatings to premium confectionery shells, with vegetable fat selection driving thermal stability and mouthfeel differentiation.
- Milk Compound:Contains 5-12% cocoa powder with milk solids and hydrogenated palm oil or shea stearin as the primary fat base. Nigerian industrial bakeries in Lagos pull this segment for cost-optimized biscuit and snack coatings where mild cocoa flavor suffices. Procurement concentrates around annual volume contracts with embedded technical service support.
- Dark Compound:Formulated with 15-35% cocoa powder and higher shea stearin ratios to approximate couverture snap and gloss. South African specialty confectionery channels in Johannesburg and Cape Town absorb this segment for premium positioning despite vegetable fat content. Cold-pressing advances in Burkina Faso are tightening sensory gaps with cocoa butter.
- White Compound:Cocoa butter-free formulation relying on deodorized vegetable fats, milk powder, and sugar for confectionery shell applications.
- Flavored Compound:incorporates mint, orange, or nut profiles for seasonal and novelty confectionery production in Kenyan and Ghanaian processing lines.
The dominant share belongs to Milk Compound, while Dark Compound is closing the gap fastest.
Application:
End-use concentration reflects the scale of industrial bakery infrastructure versus artisanal production across West and East African urban corridors.
- Baking:Industrial biscuit and cracker manufacturers in Accra and Lagos deploy compound coatings for enrobing and bottoming applications where tropical heat resistance trumps cocoa butter luxury. Sensor-controlled refiners reduce batch rejection rates for seasonal production peaks. Ghana's FDA labeling mandates compel reformulation of existing bakery lines to distinguish compound from pure chocolate.
- Confectionery:Mass-market chocolate bar and praline producers substitute compound for couverture in price-sensitive Nigerian and Kenyan retail channels. Barry Callebaut technical service partnerships support viscosity control in Lagos processing plants. Enzymatic interesterification is digitizing fat blend consistency for this segment.
- Dairy Products:Ice cream manufacturers source ready-to-use compound coatings for stick and cone dipping applications.
- Snacks:Cereal bar and coated nut producers in Nairobi industrial parks absorb compound for ambient-stable confectionery layers.
Baking commands the largest volume position, with Confectionery expanding most quickly as urban bakery chains scale output.
Distribution Channel:
Channel selection determines cold chain requirements, technical service access, and compliance documentation burden for compound coating procurement.
- Hypermarkets:Shoprite and Spar networks in South Africa and Nigeria stock bulk compound for artisanal bakers and small confectioners with immediate formulation needs. Shelf-stable packaging eliminates refrigeration costs for ambient tropical storage. Procurement managers consolidate supplier relationships around technical service capability rather than price alone.
- Online Retail:Jumia and Glovo ambient confectionery fulfillment networks in Nigeria and Kenya open direct-to-bakery distribution channels bypassing traditional wholesale layers. E-grocery logistics investment enables just-in-time coating procurement for seasonal peaks without inventory carrying costs.
- Supermarkets:Mass-market retail chains in Accra and Dar es Salaam serve small-scale bakers with pre-packaged compound formats.
- Specialty Stores:Professional bakery supply outlets in Johannesburg and Cape Town cater to premium confectionery producers requiring custom fat blend specifications.
Hypermarkets anchor current volume, though Online Retail is gaining share fastest as Nigerian and Kenyan e-grocery platforms mature.
End User:
Customer type dictates order scale, formulation complexity, and supplier relationship structure across the procurement spectrum.
- Manufacturers:Industrial confectionery and biscuit producers in Lagos, Accra, and Nairobi negotiate annual volume contracts with embedded formulation support and real-time viscosity adjustment services. Kenya's industrial biscuit producers exhibit the most concentrated buyer behavior, displacing fragmented multi-vendor purchasing with single-source partnerships. Cargill leverages Ghanaian cocoa sourcing infrastructure to anchor supply security for this segment.
- Bakers:Urban bakery chains scaling output for snack and biscuit lines pull compound coatings into centralized procurement with technical service requirements.
- Restaurants:Hotel and catering operations in Cape Town and Johannesburg source compound for dessert garnish and plating applications.
- Retailers:Independent confectionery shops in Dar es Salaam and Kampala absorb smaller-format compound for artisanal production.
Manufacturers hold the dominant procurement position, while Bakers are climbing the fastest as Lagos and Accra-based chains expand centralized purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for vegetable fats and cocoa powder shapes procurement patterns across African compound chocolate markets, while export-oriented processing in West Africa generates regional supply asymmetries. Nigeria and Ghana absorb the dominant procurement volumes, with East African markets exhibiting faster demand acceleration from lower bases.
Nigeria
Lagos-based industrial bakeries scale compound chocolate procurement for biscuit and snack enrobing applications. NAFDAC enforces compositional labeling thresholds that separate compound from pure chocolate, compelling manufacturers to reformulate existing product lines. The Lagos-Accra corridor concentrates procurement managers negotiating annual volume contracts with embedded technical service support.
Ghana
Urban bakery chains in Accra pull milk compound coatings for cost-optimized confectionery production where tropical heat resistance trumps cocoa butter luxury. The Food and Drugs Authority tightened vegetable fat content labeling mandates in 2023, forcing dual label inventories for cross-border suppliers. Tema's processing infrastructure anchors regional supply security through Cargill's cocoa sourcing operations.
South Africa
Johannesburg and Cape Town specialty confectionery channels absorb dark compound for premium positioning despite vegetable fat content. The Department of Health applies FSSC 22000-aligned safety audits to imported coatings, blocking non-certified Asian supplier shipments. Gauteng's industrial bakery clusters exhibit concentrated buyer behavior toward single-source technical service partnerships.
Kenya
Nairobi industrial biscuit producers displace fragmented multi-vendor purchasing with consolidated supplier relationships around formulation capability. Divergent East African Community labeling standards leave Kenya with unresolved import protocol friction against Tanzania and Uganda. Jumia's e-grocery fulfillment networks enable direct-to-bakery distribution channels bypassing traditional wholesale layers.
Tanzania
Dar es Salaam's nascent industrial bakery sector offers first-mover positioning for compound coating technical service partnerships. Pending East African Community harmonization talks would eliminate Kenya-Tanzania-Uganda import protocol barriers. Local procurement managers calibrate shea stearin availability against cocoa powder quality variance from regional processors.
Africa Compound Chocolate Market Competitive Environment
On the supply side, the industry is consolidating around integrated cocoa processors and specialized confectionery ingredient suppliers with regional manufacturing footprints. The vendor base separates into three strategic archetypes: cocoa-origin integrated processors, European technical service specialists, and diversified multinational confectionery manufacturers. Competitive moves center on backward integration into shea butter fractionation and technical service partnerships with industrial bakeries.
Within the cocoa-origin integrated tier, Cargill Incorporated and The Barry Callebaut Group represent supply security anchors leveraging West African sourcing infrastructure. Among diversified multinationals, Nestle SA occupies a position exemplifying ready-to-use compound coating scale for ice cream and biscuit applications. These three companies sit within distinct competitive vectors—origin integration, technical service depth, and end-use manufacturing scale—rather than direct segment overlap.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Puratos |
| The Barry Callebaut Group |
| Aalst Wilmar Pte Ltd |
| The Bühler Holding AG |
| Mondelez International |
| Nestle SA |
| Cocoa Processing Company Limited |
| Tulip Cocoa Processing Ltd |
| Others |
Value Chain & Pricing Dynamics
The Lagos-Tema maritime corridor anchors cost dynamics across West African compound chocolate procurement, with freight volatility amplifying price differentiation between bulk industrial buyers and fragmented artisanal channels while shea stearin supply concentration in Burkina Faso and Mali shapes upstream negotiation leverage.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Nigerian and Ghanaian bakery clusters. Price differentiation hinges on FSSC 22000 certification tier and annual volume scale, with certified manufacturers commanding premium positioning against uncertified Asian competitors. Cost compression in milk compound tiers is intensifying because Malaysian palm oil futures transmit directly into converter margins. Artisanal bakers in Dar es Salaam and Kampala exhibit highest price sensitivity, while South African specialty confectioners absorb premium dark compound with minimal elasticity.
Supply Chain Analysis
Shea stearin supply volatility between Burkina Faso and Mali dominates risk profiles for West African compound chocolate processors. Geographic supply concentration centers on Ghana, Nigeria, and Côte d'Ivoire for cocoa powder, with Malaysia and Indonesia anchoring palm oil feedstocks. Raw material dependencies rest on shea butter fractionation yields, deodorized vegetable fat streams, and alkalized cocoa powder consistency. Distribution runs through Tema and Lagos port clusters into industrial bakery zones, with sensor-controlled refiner deployments compressing batch rejection exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around Lagos and Accra-based industrial bakery chains, with procurement managers displacing fragmented multi-vendor relationships through single-source technical service partnerships that embed formulation support into annual volume contracts.
For Market Incumbents: Pre-empt shea stearin supply disruption by securing backward integration into Burkina Faso cold-pressing infrastructure before competitors lock fractionation capacity. Anchor supply security through captive shea butter sourcing while accelerating enzymatic interesterification deployment to tighten sensory gaps with couverture and defend premium positioning against emerging Asian coating suppliers. For New Entrants and Emerging Players: Tanzania's nascent industrial bakery sector in Dar es Salaam represents the most penetrable entry point for compound coating technical service partnerships before regional standards harmonization eliminates import protocol friction. Kenya's e-grocery logistics networks offer direct-to-bakery distribution channels bypassing wholesale layers. Lead with embedded formulation support and real-time viscosity adjustment capabilities rather than price competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified multinational confectionery parents seeking to divest non-core compound coating units lacking technical service depth. Long-term viability hinges on backward integration into shea butter fractionation and regional manufacturing footprint scale across the analysis window. Monitor East African Community harmonization timeline acceleration as inflection signal for centralized production economics.| Strategic Initiative | Industry Significance |
|---|---|
| Shea Butter Fractionation Integration | Cold-pressing advances in Burkina Faso tighten sensory gaps with cocoa butter at lower input cost. |
| Enzymatic Interesterification Deployment | Digital fat blend consistency reduces batch rejection rates for seasonal production peaks. |
| FSSC 22000 Certification Investment | South Africa's Department of Health audits block non-certified Asian supplier shipments. |
| Technical Service Partnership Expansion | Barry Callebaut's Lagos processing plant support anchors industrial bakery loyalty. |
| E-Grocery Logistics Channel Development | Jumia's ambient confectionery fulfillment networks enable just-in-time coating procurement. |
Study Parameters
A spread of perspectives from plant managers at Nigerian industrial bakeries, procurement leads at Ghanaian confectionery manufacturers, lipid chemistry specialists at West African universities, and distribution channel partners converged on the working assumptions. Secondary validation drew from Ghana Food and Drugs Authority labeling directives, NAFDAC compositional thresholds, customs and trade data across the Lagos-Tema corridor, and SEC filings of listed cocoa processors. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include product type tier, application end-use, distribution channel format, and regional regulatory cluster. CAGRs derived from weighted average growth trajectories across shea stearin availability scenarios and cocoa powder quality variance assumptions. Industry-specific forecast inputs incorporated enzymatic refining adoption curves and East African Community harmonization probability assessments.
Practitioners should monitor shea butter supply volatility, palm oil futures trajectory, and regional standards convergence timelines for early signals. Forecasts reflect documented assumptions on shea stearin yield advances and regulatory enforcement intensity. Material shifts in East African Community harmonization outcomes or Burkina Faso fractionation capacity expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Citrus Gummies Market
Confectionery
Gum Base Candy Market
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
UK Chocolate Market
Confectionery
North America Confectionery Market
Confectionery
Chocolate Couverture Market
Confectionery
Italy Chocolate Market
Confectionery
Jellies and Gummies Market
Confectionery
Confectionery Fats Market
Confectionery
Infused Fruits Jellies Market
Confectionery
North America Gummy Market
Confectionery
Licorice Candy Market
Confectionery
United Arab Emirates Sugar Confectionery Market
Confectionery
Confectionery Fillings Market