
 India Protein Market | 2026-2036
India Protein Market Size, Share, and Industry Trends Forecast 2026-2036
India Protein Market Foresight
Multi-source procurement of imported whey isolate and domestic soy concentrate is pivoting toward captive pea-protein extraction as tariff volatility rises. MuscleBlaze anchors its position through backward integration into flavor-system manufacturing. AS-IT-IS Nutrition competes on unflavored, single-ingredient SKUs with minimal processing claims. True Elements differentiates via clean-label positioning and heritage-grain protein blends.
India protein encompasses nitrogenous macromolecules—whey, casein, soy, and pea isolates typically delivering 80-90% protein content by dry weight—formulated into powders, bars, ready-to-drink beverages, and capsules for muscle synthesis, weight management, and geriatric nutrition. Whey protein leads volume due to established gym-channel penetration and superior leucine bioavailability, while pea protein claims the fastest expansion trajectory as vegan formulations displace dairy in metro health stores. The powder form dominates absolute rupee sales, though ready-to-drink formats command premium shelf positioning in airport kiosks and corporate cafeterias.
FSSAI mandates protein-content verification and allergen disclosure on all packaged supplements, compressing margins for unorganized labelers while advantaging certified manufacturers. BIS standards for soy-protein isolate and CDSCO oversight of medical-nutrition claims create layered compliance thresholds that filter market entrants. India's PLI scheme for food processing incentivizes domestic isolate capacity, yet stakeholders must monitor how state-level GST enforcement on e-commerce protein shipments reshapes channel economics.
Market Dynamics
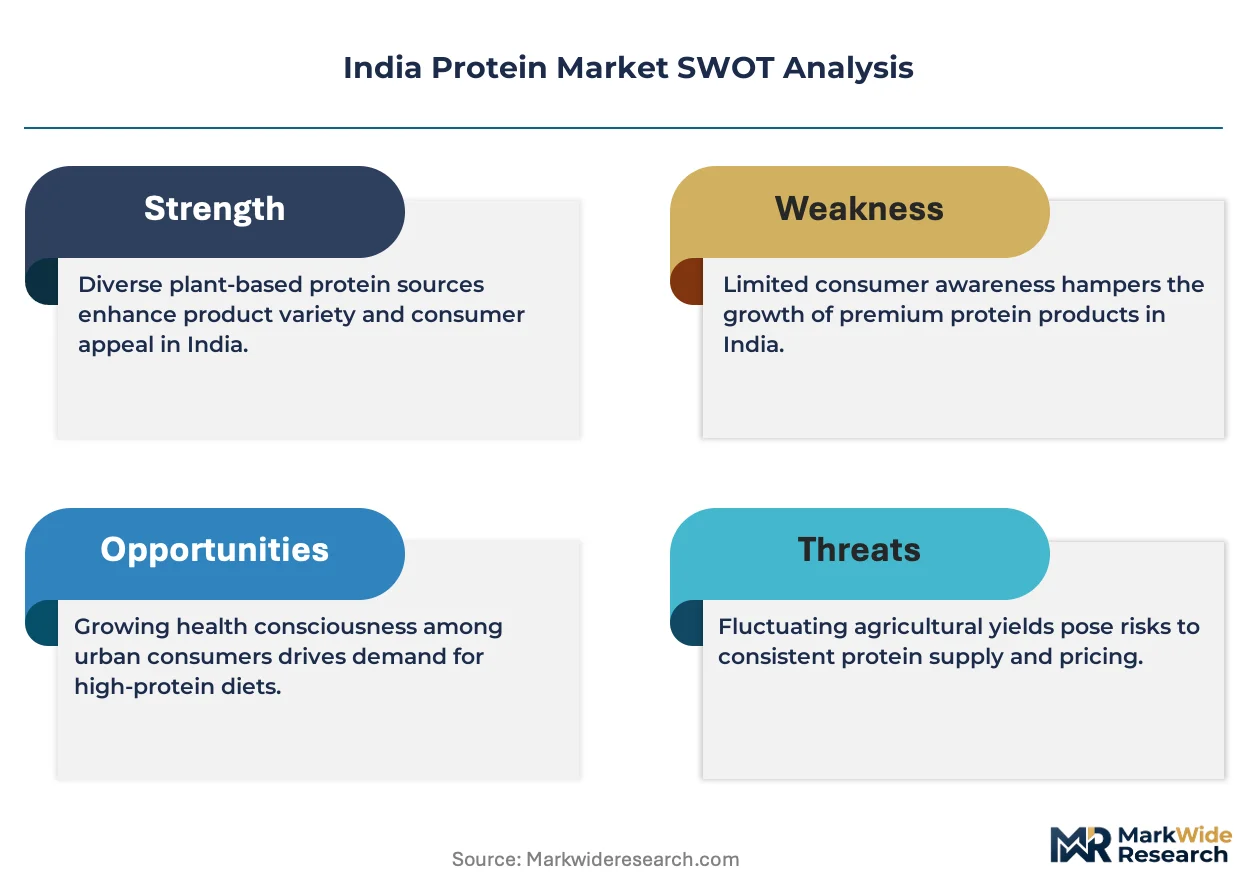
FSSAI's tightened protein-labeling norms are compressing margins for unorganized labelers while advantaging certified manufacturers with backward-integrated quality systems. This regulatory pressure is the dominant structural force reshaping competitive positioning across India's protein value chain.
Growth Catalysts
- PLI scheme for food processing:Domestic isolate capacity receives production-linked incentives that reduce import dependency for whey and soy concentrates. Maharashtra and Gujarat manufacturing clusters capture the bulk of allocated subsidies.
- Tier-2 city gym penetration:Amateur athletes in Surat, Indore, and Coimbatore drive powder volume through localized supplement retail networks. These cities now outpace metro growth for unflavored whey SKUs.
- Pea-protein extraction technology:Captive processing infrastructure is modularizing supply chains as tariff volatility on imported isolates accelerates backward integration investments.
Market Restraints
- Import tariff volatility:Whey isolate shipments from the United States and Europe face unpredictable duty swings that erode margin predictability for brands without captive extraction.
- FSSAI compliance layering:BIS standards for soy-protein isolate and CDSCO oversight of medical-nutrition claims create multi-threshold entry barriers that filter small labelers.
- Leucine bioavailability gap:Plant-based isolates require amino acid fortification to match dairy protein efficacy, adding formulation cost and sensory complexity.
Strategic Opportunities
- Geriatric nutrition protocols:Medical-nutrition claims under CDSCO guidelines open institutional channels for high-protein clinical formulations in Kerala and Tamil Nadu healthcare networks.
- Ready-to-drink airport positioning:Corporate cafeterias and transit hubs in Bengaluru and Hyderabad create premium shelf space for single-serve protein beverages with clean-label credentials.
- Heritage-grain protein blends:Millet and amaranth formulations align with FSSAI's push for indigenous ingredient valorization in functional foods.
Industry Challenges
- Flavor-system R&D talent scarcity:Masking plant-protein off-notes requires food technologists with cross-category experience that concentrates in Mumbai and Delhi NCR labs.
- GST enforcement fragmentation:State-level e-commerce shipment taxation creates channel economics uncertainty that complicates direct-to-consumer scaling.
- Allergen disclosure precision:FSSAI mandates for soy and dairy traceability demand supply chain visibility investments that strain mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Protein Market |
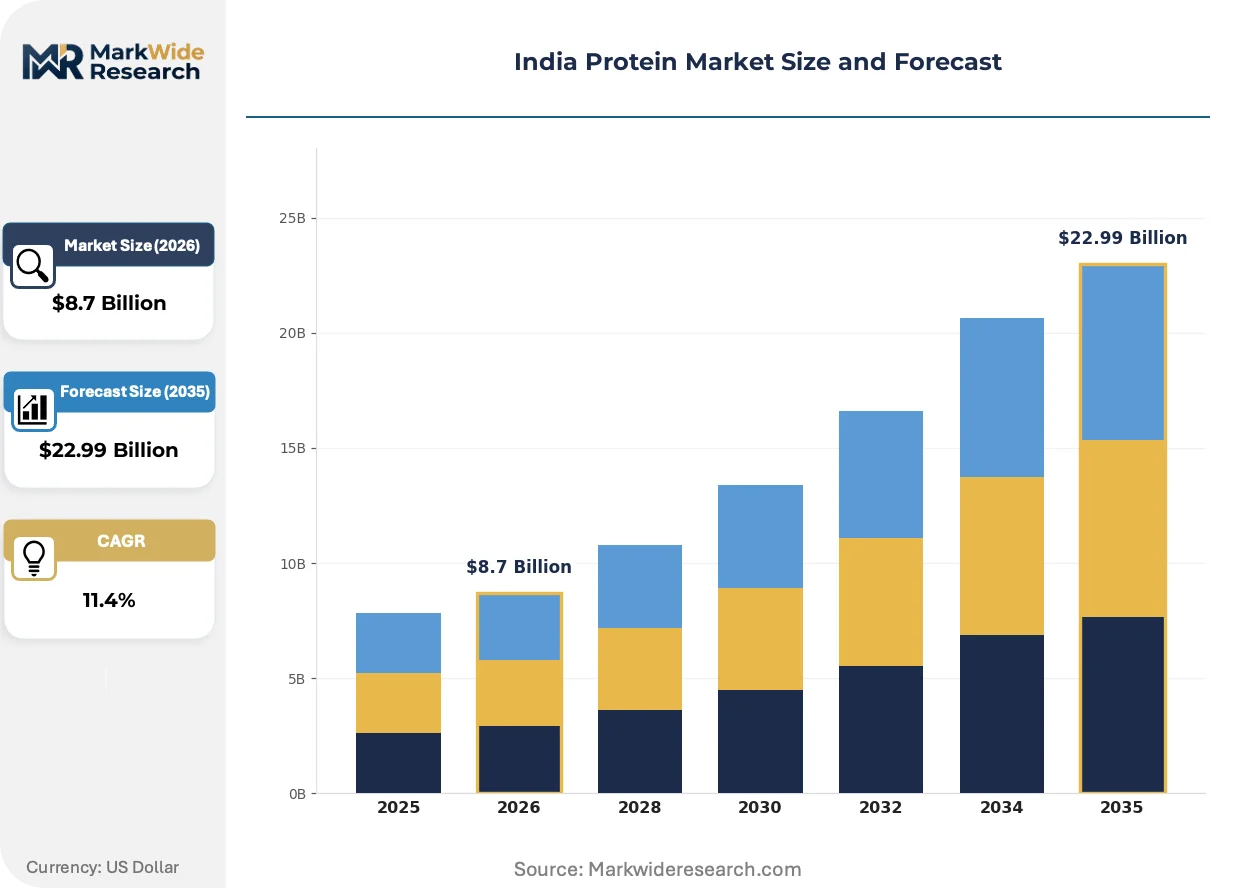
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein End User: Bodybuilders, Athletes, Weight Watchers, Seniors Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Form: Powder, Bar, Ready-to-Drink, Capsules |
| Companies Covered | Bigmuscles Nutrition, MyFitness, MuscleBlaze, Pintola, True Elements, Optimum Nutrition, Herbalife Nutrition India, AS-IT-IS Nutrition, Nestlé India Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Protein Market Shifts & Advancements
Reformulation investments are accelerating as brands respond to regulatory compression and shifting procurement patterns. Three distinct vectors are reshaping how protein products are developed, positioned, and distributed across Indian consumer segments.
Pea-protein extraction infrastructure is modularizing supply chain architecture for mid-tier manufacturers previously dependent on volatile import streams. Domestic processors in Gujarat are deploying scalable fractionation units that reduce batch-to-batch variability. This technology compression is enabling smaller brands to launch vegan formulations without legacy dairy supply relationships.
FSSAI's 2024 allergen disclosure amendments are forcing label redesigns across the powder and bar categories. Manufacturers must now verify protein content through third-party assay and declare cross-contamination risks for soy-dairy co-packing facilities. The ready-to-drink segment faces the steepest compliance timeline due to shorter shelf-life documentation requirements.
Amateur athletes in tier-2 cities are bypassing traditional gym-channel intermediaries through direct-to-consumer subscription models. Indore and Lucknow now represent the fastest-growing pin codes for unflavored isolate shipments via quick-commerce platforms. This channel rotation is compressing brand loyalty cycles and rewarding SKUs with minimal processing claims over established flavor portfolios.
India Protein Market Segmentation
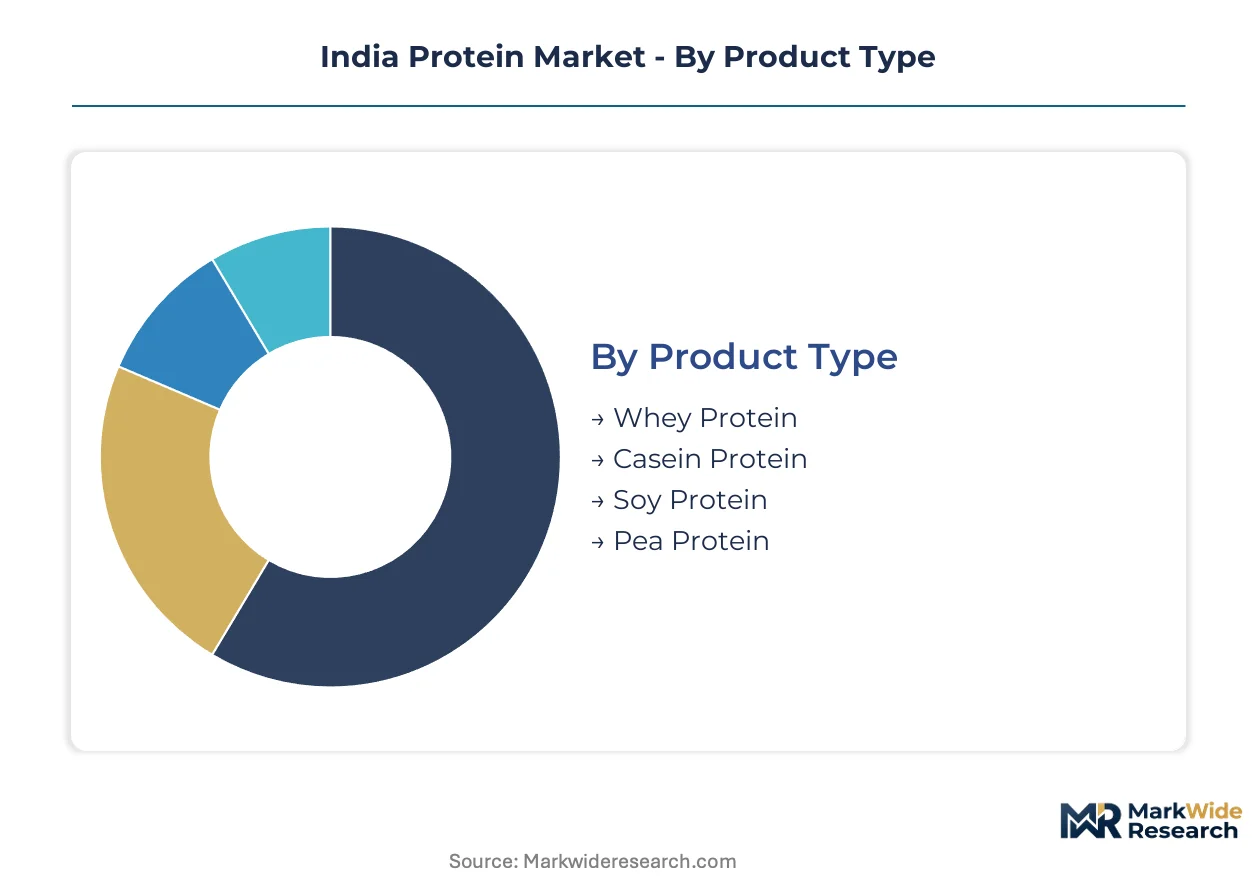
India's protein market segments along four intersecting dimensions that determine margin capture, channel economics, and regulatory exposure. Understanding these splits reveals where FSSAI compliance costs concentrate and where captive extraction investments yield the highest returns.
Product Type:
Whey dominates absolute rupee volume while pea commands the steepest expansion trajectory as tariff volatility reshapes procurement economics.
- Whey Protein:Isolates and concentrates delivering 80-90% protein by dry weight with superior leucine bioavailability. Demand concentrates in Maharashtra and Karnataka gym channels where amateur athletes prioritize muscle synthesis efficacy. FSSAI protein-content verification mandates compress margins for unorganized labelers lacking third-party assay capabilities.
- Pea Protein:Yellow pea isolates requiring amino acid fortification to match dairy efficacy. Gujarat captive extraction facilities are modularizing supply chains for mid-tier manufacturers previously dependent on volatile import streams. Vegan formulation demand in metro health stores accelerates backward integration investments.
- Casein Protein:Slow-digesting micellar structures favored for overnight recovery protocols. Night-time consumption rituals among serious bodybuilders sustain niche positioning despite higher price points.
- Soy Protein:Isolate and concentrate forms governed by BIS standards with established institutional procurement in Kerala healthcare networks. Allergen disclosure requirements strain mid-tier manufacturers lacking supply chain visibility.
Mature deployment sits with whey protein across established gym retail. Newer deployment is concentrated in pea protein as vegan formulations displace dairy in metro health stores.
End User:
Amateur athlete segments in tier-2 cities outpace metro growth while geriatric nutrition opens institutional channels under CDSCO oversight.
- Bodybuilders:High-volume consumers prioritizing unflavored isolates with minimal processing claims. Surat and Indore retail networks now surpass Mumbai and Delhi NCR in absolute powder volume for this segment.
- Athletes:Amateur competitors in Coimbatore and Lucknow driving quick-commerce subscription models. Direct-to-consumer platforms compress brand loyalty cycles and reward single-ingredient SKUs over flavor portfolios.
- Weight Watchers:Calorie-conscious consumers seeking meal replacement integration. Corporate cafeteria procurement in Bengaluru creates premium positioning for portion-controlled formats.
- Seniors:Geriatric nutrition protocols under CDSCO medical-nutrition claims. Tamil Nadu healthcare networks institutionalize high-protein clinical formulations for sarcopenia management.
Volume concentration rests with bodybuilders through traditional gym-channel intermediaries. Fastest adoption is emerging among seniors as clinical validation expands reimbursement pathways.
Distribution Channel:
Channel economics fragment across state-level GST enforcement patterns that complicate direct-to-consumer scaling for protein shipments.
- Online Retail:Quick-commerce platforms and subscription models dominating tier-2 city penetration. State-level e-commerce taxation creates margin unpredictability for brands without localized warehousing.
- Supermarkets:Mass-market powder and bar placement with FSSAI-compliant labeling as table stakes. Shorter shelf-life documentation requirements compress compliance timelines for ready-to-drink introductions.
- Health Stores:Metro health stores in Hyderabad and Bengaluru commanding premium positioning for clean-label and vegan formulations. Heritage-grain protein blends align with indigenous ingredient valorization priorities.
- Specialty Shops:Gym-affiliated retail in Maharashtra and Gujarat manufacturing clusters. Localized supplement networks in tier-2 cities bypass traditional distributor markups.
Established volume flows through specialty shops with deep gym-channel relationships. Channel expansion is accelerating via online retail as quick-commerce platforms penetrate Indore and Lucknow pin codes.
Form:
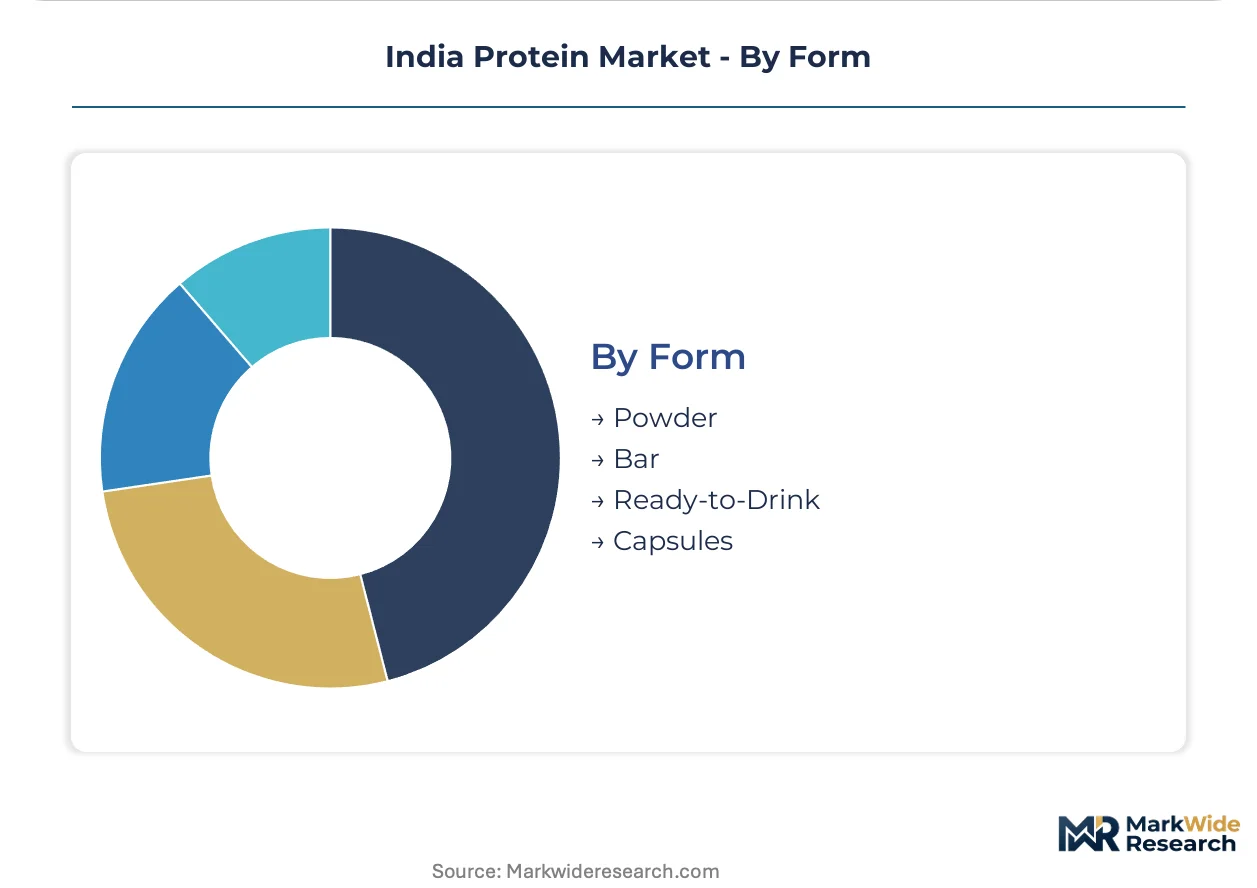
Powder commands absolute rupee sales while ready-to-drink formats capture premium shelf positioning in transit and corporate environments.
- Powder:Dominant format with established manufacturing infrastructure and flavor-system R&D concentration in Mumbai and Delhi NCR labs. Unflavored isolates gain share fastest in tier-2 city amateur athlete segments.
- Ready-to-Drink:Single-serve beverages commanding airport kiosk and corporate cafeteria premiums in Bengaluru and Hyderabad. Clean-label credentials and shorter shelf-life documentation requirements create compliance complexity.
- Bar:Convenience format with FSSAI allergen disclosure amendments forcing label redesigns. Soy-dairy co-packing cross-contamination risks demand supply chain visibility investments.
- Capsules:Medical-nutrition positioning under CDSCO oversight for targeted amino acid delivery. Kerala and Tamil Nadu healthcare procurement favors institutional packaging formats.
Volume leadership remains with powder across gym and retail channels. Premium positioning is concentrating in ready-to-drink as transit hub and corporate cafeteria penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yellow pea cultivation in Madhya Pradesh and Rajasthan anchors India's emerging plant-protein supply base, while dairy whey processing clusters concentrate in the western and southern manufacturing belts. State-level FSSAI enforcement and PLI subsidy allocation are redrawing competitive maps across sub-national markets.
Maharashtra
Mumbai and Pune gym channels drive unflavored whey isolate volume among amateur bodybuilders seeking minimal processing claims. FSSAI's 2024 protein-content verification mandates compress margins for unorganized labelers lacking third-party assay capabilities. Manufacturing clusters in Thane and Nashik capture PLI scheme subsidies for domestic isolate capacity expansion.
Gujarat
Captive pea-protein extraction facilities in Ahmedabad and Vadodara are modularizing supply chains for mid-tier manufacturers previously dependent on volatile import streams. BIS standards for soy-protein isolate create compliance thresholds that filter small entrants. Anand and Surat specialty retail networks bypass traditional distributor markups for tier-2 city athletes.
Karnataka
Bengaluru corporate cafeterias and airport kiosks create premium shelf positioning for ready-to-drink protein beverages with clean-label credentials. CDSCO oversight of medical-nutrition claims opens institutional channels for geriatric formulations in Bengaluru healthcare networks. Mysuru flavor-system R&D labs concentrate talent for masking plant-protein off-notes.
Tamil Nadu
Chennai and Coimbatore healthcare networks institutionalize high-protein clinical formulations for sarcopenia management under CDSCO guidelines. Kerala and Tamil Nadu together represent the fastest-growing pin codes for quick-commerce protein subscriptions among amateur athletes. Hosur manufacturing plants supply capsule formats for targeted amino acid delivery.
Delhi-NCR
Gurgaon and Noida direct-to-consumer platforms compress brand loyalty cycles through subscription models targeting weight-watchers. State-level GST enforcement on e-commerce shipments creates channel economics uncertainty that complicates scaling. Faridabad warehousing clusters serve as distribution nodes for northern tier-2 city penetration.
India Protein Market Competitive Landscape
Backward integration into captive extraction and flavor-system manufacturing dominates the current landscape as brands defend margin positions against tariff volatility and regulatory compression. The vendor base stratifies across three tiers: global dairy processors with established gym-channel relationships, domestic mid-caps pursuing vertical integration, and direct-to-consumer specialists competing on minimal processing claims. Two strategic archetypes are emerging: PLI-subsidized domestic manufacturers with modular pea-protein infrastructure, and quick-commerce-native brands leveraging tier-2 city subscription velocity. Competitive moves concentrate on capacity expansion in Gujarat extraction facilities and strategic partnerships with state-level distributors bypassing traditional intermediaries.
Within the domestic mid-cap tier, MuscleBlaze exemplifies backward integration into flavor-system manufacturing, while AS-IT-IS Nutrition occupies a position anchored on unflavored, single-ingredient SKUs with minimal processing claims. True Elements represents the clean-label archetype through heritage-grain protein blends targeting metro health stores. These three anchors illustrate how FSSAI compliance investments and procurement pattern shifts are redrawing competitive positioning across India's protein value chain.
| Leading Market Players |
|---|
| Bigmuscles Nutrition |
| MyFitness |
| MuscleBlaze |
| Pintola |
| True Elements |
| Optimum Nutrition |
| Herbalife Nutrition India |
| AS-IT-IS Nutrition |
| Nestlé India Limited |
| Others |
Supply & Pricing Matrix
PLI-subsidized domestic manufacturers and family-owned mid-caps in Gujarat and Maharashtra exercise pricing discipline through captive extraction infrastructure that buffers against import tariff swings. FSSAI compliance investments function as a de facto entry fee, compressing margins for unorganized labelers while allowing certified players to maintain premium positioning.
Pricing Analysis
Third-party assay bundling separates FSSAI-verified isolates from unverified alternatives, with certification-grade protein commanding measurable premiums over commodity powder. Price differentiation rests on leucine bioavailability documentation and allergen disclosure precision, with tier-2 city amateur athletes showing highest sensitivity to per-serving cost. Cost compression in unflavored whey concentrates is intensifying as quick-commerce platforms compress distributor markups.
Supply Chain Analysis
Dual-sourcing mandates from Maharashtra and Karnataka gym chains require brands to qualify both domestic soy concentrate and imported whey isolate suppliers. Procurement draws from United States dairy processors, Gujarat pea fractionation units, and Madhya Pradesh yellow pea cultivation belts. Tariff exposure on whey isolate shipments creates margin unpredictability for brands lacking captive extraction. Distribution runs through gym-affiliated specialty retail in manufacturing clusters and quick-commerce platforms penetrating tier-2 pin codes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI's layered compliance thresholds have erected a cost-of-compliance moat that advantages certified manufacturers with backward-integrated quality systems. This regulatory architecture filters small labelers while rewarding players with assay capabilities and allergen traceability infrastructure.
For Market Incumbents: To counter quick-commerce subscription models compressing brand loyalty cycles, incumbents should deepen channel control through direct-to-consumer warehousing in Delhi-NCR and Faridabad distribution nodes. Capacity addition in Gujarat extraction facilities anchors supply security against whey isolate tariff volatility. For New Entrants and Emerging Players: Tier-2 city amateur athletes in Indore and Lucknow represent an underserved buyer archetype with fastest-growing pin code velocity. White-space targets include unflavored isolate SKUs with minimal processing claims and heritage-grain protein blends for metro health stores. Go-to-market execution favors quick-commerce platform partnerships over traditional gym-channel intermediaries. For Investors and Strategic Acquirers: Distressed-cycle entries favor PLI-subsidized domestic manufacturers with modular pea-protein infrastructure in Gujarat. Long-term viability across the analysis window hinges on regulatory compliance scalability and captive extraction economics. The signal to watch is FSSAI enforcement intensity on e-commerce shipments as a channel economics inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Pea-Protein Extraction | Modular Gujarat facilities reduce import dependency as tariff volatility rises. |
| FSSAI Certification Investment | Third-party assay capabilities create barrier-to-entry moats against unorganized labelers. |
| Quick-Commerce Platform Partnership | Tier-2 city subscription velocity in Indore and Lucknow compresses traditional distributor economics. |
| Heritage-Grain Protein Formulation | Millet and amaranth blends align with FSSAI indigenous ingredient valorization priorities. |
| Flavor-System R&D Expansion | Mumbai and Delhi NCR lab concentration addresses plant-protein off-note masking talent scarcity. |
Research Methodology
Regulatory filings from FSSAI and CDSCO, BIS standards documentation, and PLI scheme allocation records formed the secondary backbone for compliance cost modeling. Primary interviews with protein brand procurement heads, gym-channel distributors in Maharashtra and Karnataka, flavor-system R&D directors, and quick-commerce platform category managers validated demand patterns and channel economics. Bottom-up and top-down triangulation reconciled isolate shipment volumes with retail audit data.
Bottom-up volume modeling segmented by protein source, end-user archetype, distribution channel, and geographic cluster anchored the analytical lens. CAGRs were derived from fitted growth curves across the projection horizon, with inputs including FSSAI enforcement intensity indices, tariff rate volatility bands, and tier-2 city gym penetration trajectories.
Revisions become necessary when FSSAI allergen disclosure amendments tighten or PLI subsidy allocation shifts materially alter domestic capacity economics. Forecasts reflect assumptions about regulatory enforcement continuity and import tariff stability. A model refresh is warranted upon material change in quick-commerce platform taxation policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
Plant Based Ingredients Market
Ingredients
Starch Market
Ingredients
Cholesterol API Market
Ingredients
North America Sodium Reduction Ingredients Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Mung Bean Protein Market
Ingredients
Liquid Feed Market
Ingredients
Konjac Flour Market
Ingredients
Europe Fermented Ingredients Market
Ingredients
Asia-Pacific Soy Protein Concentrate Market
Ingredients
Precision Fermentation Ingredient Supplier Market
Ingredients
High Oleic Oil Market
Ingredients
Oak Chips White Extract Market
Ingredients
Fruit Powder Market
Ingredients
North America Dairy Ingredients Market