
 Smoke Ingredients for Food Market | 2026-2036
Smoke Ingredients for Food Market Size, Share, and Industry Trends Forecast 2026-2036
Smoke Ingredients for Food Market Intelligence
The replacement of traditional wood-chip smoking with purified liquid smoke applications is broadening the addressable market for food processors. Kerry Group leverages its extensive food ingredient portfolio to integrate smoke flavors into complete savory systems. Red Arrow specializes in liquid smoke technology, controlling a significant portion of the North American market through its focused expertise. ProFagus sustains its market position through its unique production of beechwood-derived smoke products.
Smoke ingredients for food are concentrated flavorings derived from the controlled pyrolysis of wood, which are then purified to remove undesirable or harmful compounds like PAHs. Their primary commercial purpose is to impart characteristic smoke flavor, color, and antimicrobial properties to food products without direct exposure to smoke. Liquid smoke formats command the largest share due to their versatility and ease of integration into industrial food production lines. While meat products remain the dominant application, the snacks and sauces categories are showing significant development activity.
Regulatory frameworks from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) heavily influence product composition, particularly regarding maximum levels for benzo[a]pyrene. These regulations mandate rigorous testing and purification processes, creating high barriers to entry for new market participants. Ingredient manufacturers must now decide whether to invest in advanced purification technologies or focus on natural flavor systems that fall outside of stricter smoke flavor classifications.
Market Dynamics
The market's central dynamic is the regulatory-driven substitution of traditional smoking. Strict limits on polycyclic aromatic hydrocarbons (PAHs) by authorities like EFSA force a systemic shift toward purified, industrial-grade liquid smoke applications across the food industry.
Growth Catalysts
- Processed Meat Demand:Sustained consumption of sausages and bacon provides a high-volume, stable demand base for smoke flavorings.
- Regulatory Mandates:Stricter EFSA and FDA laws on PAHs create a non-discretionary need for purified smoke ingredients, displacing traditional methods.
- Application Diversification:Expansion into categories like vegan snacks and savory sauces broadens the total addressable market for suppliers.
Market Restraints
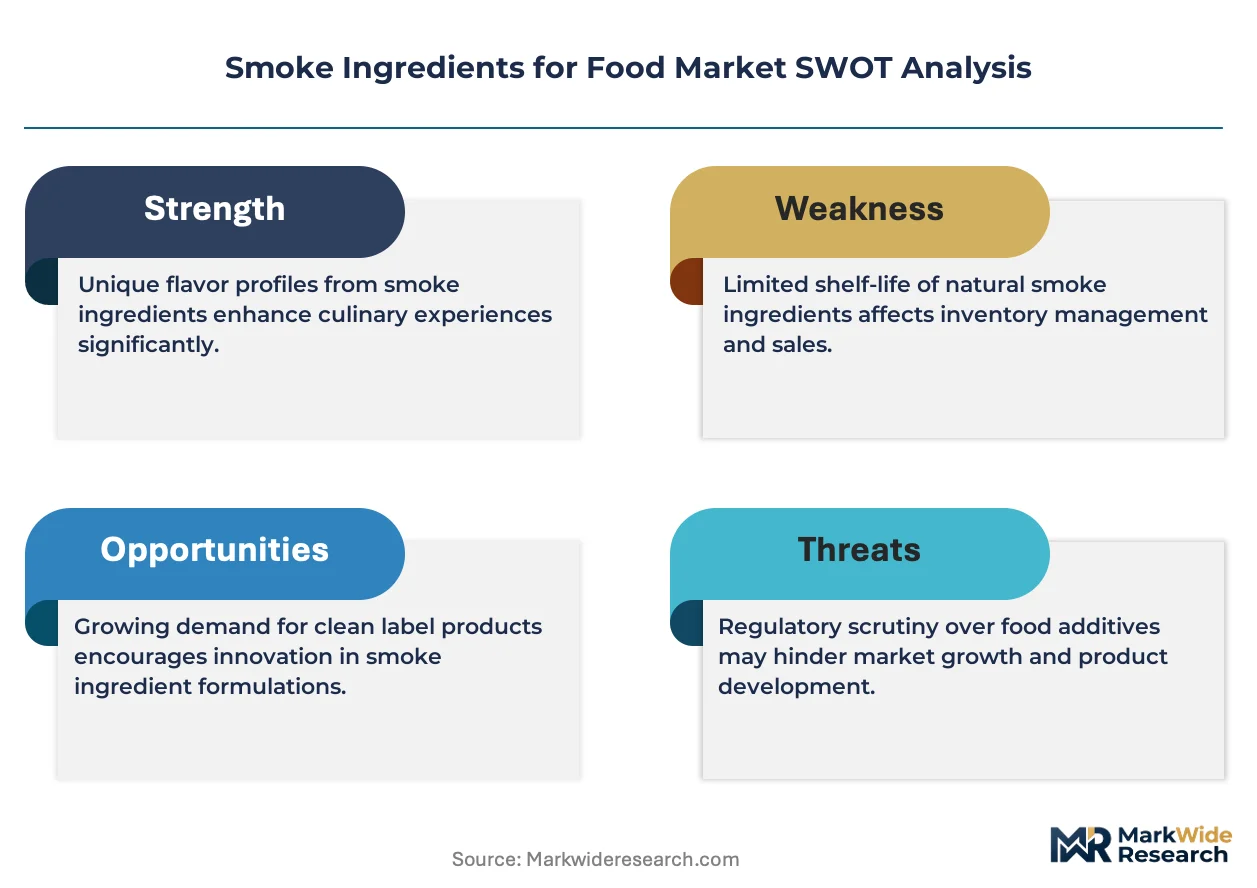
- High Purification Costs:Capital expenditure for advanced filtration technologies to meet PAH limits creates a significant barrier to entry.
- Raw Material Volatility:Dependence on specific wood types, like beechwood, exposes producers to regional supply disruptions and price fluctuations.
- Flavor Substitution:Competition from natural flavor systems like yeast extracts provides smoke-like notes without the regulatory burden of smoke classification.
Strategic Opportunities
- Plant-Based Alternatives:Developing smoke flavors for plant-based meats to mimic traditionally smoked animal proteins represents a major growth vector.
- Emerging Market Penetration:Expanding into Asia-Pacific and Latin American markets where processed food consumption is rising offers volume growth potential.
- Encapsulation Technology:Using micro-encapsulation to create powdered, controlled-release smoke flavors opens new applications in dry mixes and seasonings.
Industry Challenges
- Regulatory Fragmentation:Manufacturers must navigate disparate PAH regulations between key markets like the European Union and United States, increasing compliance costs.
- Consumer Perception:Overcoming skepticism about "liquid smoke" and educating consumers on the safety benefits of purified ingredients remains a challenge.
- Certification Timelines:The lengthy, expensive process for achieving regulatory approvals from bodies like EFSA or the FDA delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoke Ingredients for Food Market |
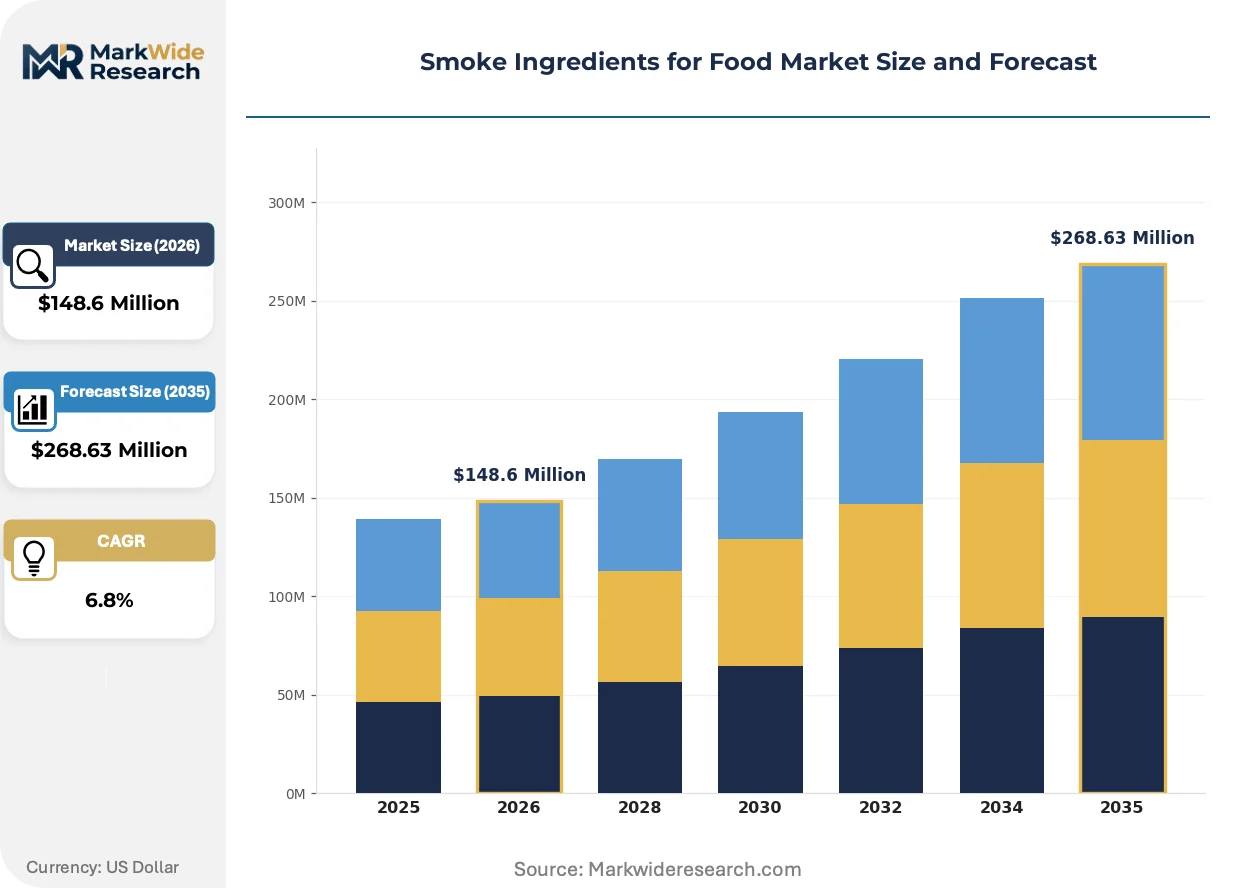
| Market Size in 2026 | $148.6 Million |
| Market Size in 2035 | $268.63 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Liquid Smoke, Smoke Seasoning, Smoke Powder, Essential Oils Source: Natural, Artificial, Organic, Non-Organic Application: Meat Products, Dairy, Sauces, Snacks Distribution Channel: Online, Retail, Wholesale, Food Service |
| Companies Covered | Besmoke, WIBERG, Kerry Group, FRUTAROM Savory Solutions GmbH, Associated British Foods, Red Arrow, ProFagus, Dempsey Corporation, MSK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoke Ingredients for Food Market Strategic Shifts & Innovations
The industrialization of flavor is the primary theme, transforming an artisanal process into a precise, science-driven ingredient category. This evolution prioritizes safety and consistency, moving smoke flavor far beyond its traditional applications in meat preservation and coloring.
Micro-encapsulation technology converts liquid smoke into stable powders, protecting volatile flavor compounds until release by heat or moisture. Food processors in the snack and bakery sectors are adopting these powders for dry-mix applications and seasonings. This technology is decentralizing smoke application from dedicated smoking chambers to standard mixing lines within a factory.
The European Food Safety Authority (EFSA) is enforcing stricter maximum levels for polycyclic aromatic hydrocarbons (PAHs) in smoke flavorings. This rule compels manufacturers to invest in advanced filtration to remove carcinogens like benzo[a]pyrene, increasing production costs. The meat processing sector in Germany and Poland is most affected, accelerating its transition to compliant, purified liquid smoke.
A shift toward clean-label ingredients is altering procurement criteria for smoke flavors. Food manufacturers now prioritize suppliers providing products from certified sustainable wood sources, often requiring detailed documentation. This behavior is most visible in the premium sauces and marinades segment within North American and Western European markets.
Smoke Ingredients for Food Market Segmentation
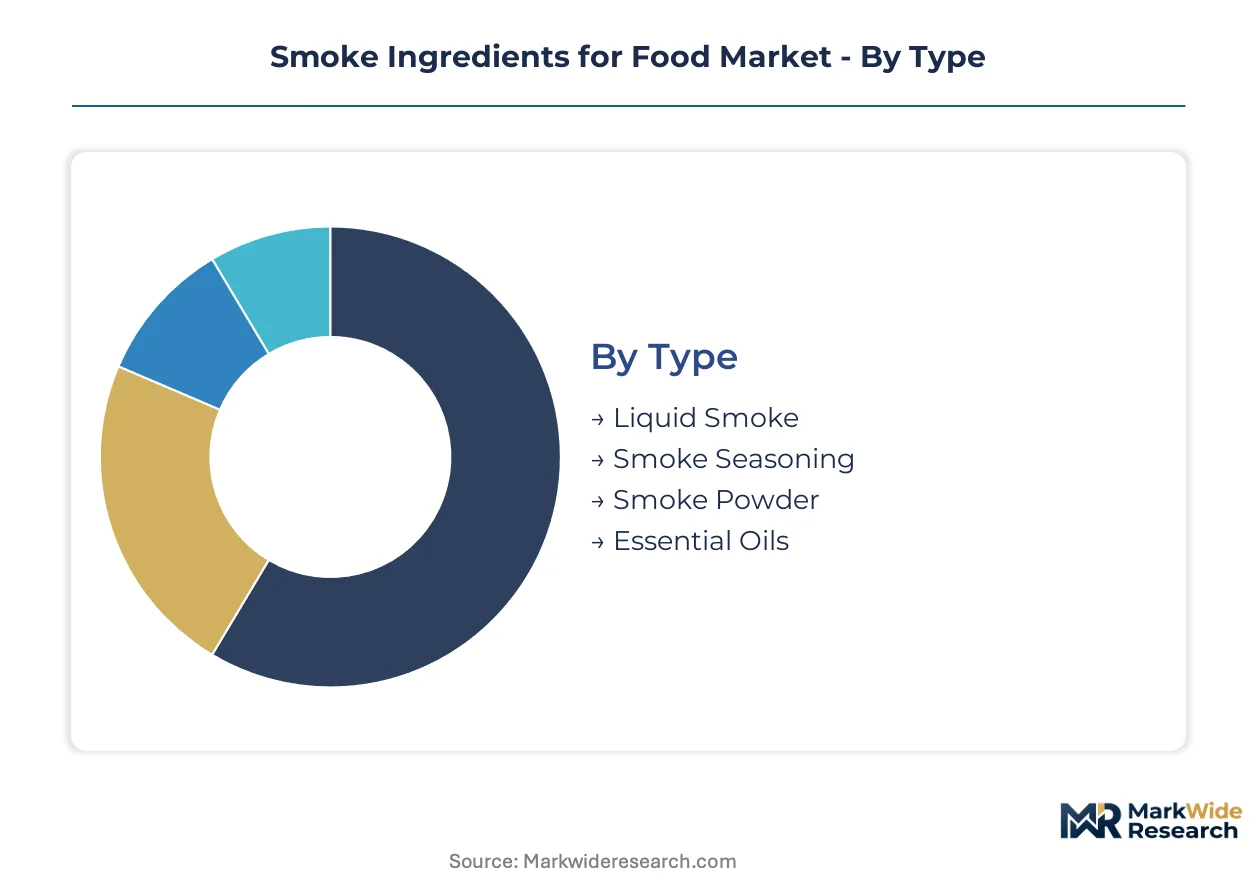
The Smoke Ingredients for Food Market's segmentation highlights the diverse forms and applications through which smoke flavor is integrated into food products. Understanding these categories reveals how technological advancements and consumer preferences shape ingredient procurement and product development across the food industry.
Type:
Ingredient type often dictates the depth of integration into food processing lines, from standalone flavor additions to embedded savory systems.
- Liquid Smoke:This purified ingredient is derived from controlled wood pyrolysis, then condensed and filtered to remove undesirable compounds. Demand concentrates in processed meat products across mature markets like Germany and the United States, driven by stringent EFSA and FDA regulations on PAHs.
- Smoke Powder:Micro-encapsulation technology converts liquid smoke into stable, free-flowing powders that protect volatile flavor compounds. Food processors in the snacks and bakery sectors adopt these powders for dry-mix applications and seasonings, expanding smoke flavor use beyond traditional wet systems.
- Smoke Seasoning:These blended products combine smoke flavors with other spices and ingredients for direct application. They cater to convenience food manufacturers seeking pre-mixed flavor profiles.
- Essential Oils:Certain essential oils can provide smoky notes, offering natural alternatives for specific flavor profiles. These are often used in premium beverage or confectionery applications.
Liquid Smoke leads volumes today; Smoke Powder is gaining share fastest.
Source:
The source of smoke ingredients reflects varying customer preferences and regulatory compliance needs, particularly regarding "clean label" demands.
- Natural:These ingredients are directly derived from the thermal decomposition of wood, purified to meet safety standards. Procurement for natural smoke flavors is shifting towards certified sustainable wood sources, especially in premium sauces and marinades within North American and Western European markets.
- Organic:Organic smoke ingredients originate from wood sources certified as organic, adhering to strict agricultural and processing standards. Niche health food brands and specialty retailers drive demand for these certified products, appealing to consumers seeking fully transparent ingredient lists.
- Artificial:These are chemically synthesized flavor compounds designed to mimic smoke notes. They offer cost-effectiveness and consistent flavor profiles for mass-market food products.
- Non-Organic:This category encompasses natural smoke ingredients not certified as organic, representing the standard commercial offering. Large-scale industrial food manufacturers widely utilize these for their cost efficiency and broad availability.
Natural sources command the largest market share; organic variants are experiencing the steepest expansion trajectory.
Application:
The application segments reveal the primary end-uses for smoke ingredients, highlighting both established markets and areas of new development.
- Meat Products:This segment represents the largest application for smoke ingredients, imparting characteristic flavor, color, and antimicrobial properties to items like sausages and bacon. Sustained consumption of processed meats, particularly in European markets such as Germany and Poland, provides a high-volume demand base.
- Snacks:Smoke ingredients enhance savory snack profiles, including chips, nuts, and extruded products. Diversification into categories like vegan snacks broadens the total addressable market for suppliers, leveraging micro-encapsulated powders for dry applications.
- Sauces:Smoke flavors are integrated into barbecue sauces, marinades, and condiments to add depth and complexity. The premium sauces segment in North America and Western Europe shows strong demand for sustainably sourced smoke flavors.
- Dairy:Smoke flavors find niche applications in dairy products such as smoked cheeses or flavored yogurts. This segment represents a smaller but growing area for product innovation.
Meat Products remain the dominant application; Snacks are climbing the fastest in adoption.
Distribution Channel:
Distribution channels illustrate how smoke ingredients reach food manufacturers and end-consumers, reflecting varied supply chain strategies.
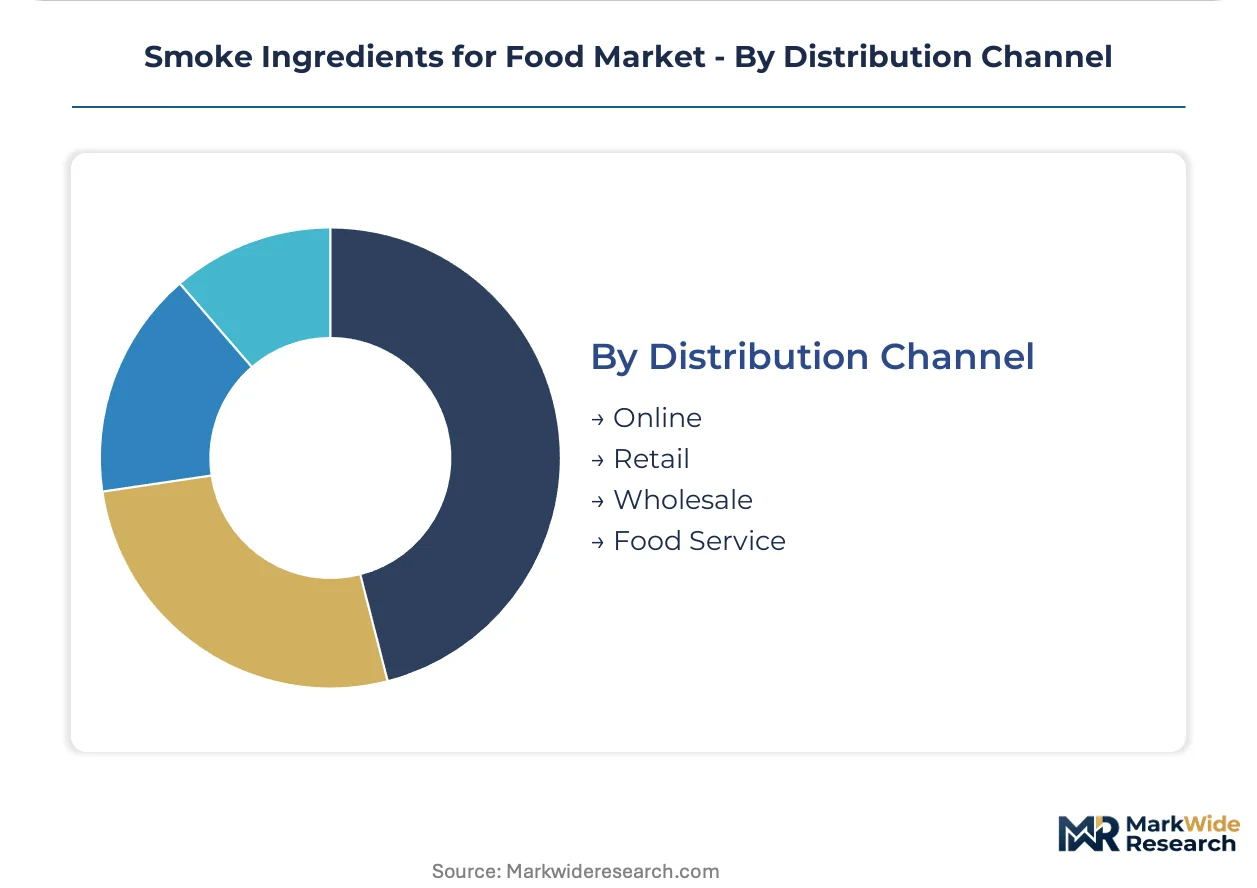
- Wholesale:This channel involves bulk sales of smoke ingredients directly to large-scale food manufacturers and industrial processors. Wholesale distribution is critical for supplying the high-volume processed meat sector and other industrial food production lines.
- Food Service:Food service channels supply smoke ingredients to restaurants, catering companies, and institutional kitchens. These customers often require specialized formulations or ready-to-use solutions for consistent flavor application in prepared meals.
- Online:Online platforms facilitate sales of smoke ingredients, particularly for smaller food businesses, specialty producers, or culinary enthusiasts. This channel offers accessibility and a broader product range for niche applications.
- Retail:Retail channels include grocery stores and specialty food shops where smoke ingredients, often in consumer-friendly formats, are sold directly to the public. These products cater to home cooks and small-batch food producers.
Wholesale distribution handles the largest volumes; Online sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processed meat product manufacturers, particularly in Europe and North America, drive substantial demand for purified smoke ingredients. Stricter regulatory frameworks from bodies like the European Food Safety Authority (EFSA) and the U.S. Food and Drug Administration (FDA) shape product composition. This global market sees diverse regional dynamics influencing adoption and innovation.
United States
Demand for smoke ingredients in the United States stems from its large processed meat sector and expanding savory snacks category. FDA regulations on polycyclic aromatic hydrocarbons (PAHs) necessitate rigorous testing and purification processes for smoke flavorings. Food manufacturing hubs in the Midwest, including Chicago, integrate liquid smoke into high-volume industrial production lines for various food applications.
Germany
Germany maintains robust demand for smoke ingredients due to its high consumption of traditional sausages and bacon. EFSA mandates for maximum PAH levels accelerate the transition towards compliant, purified liquid smoke applications. Meat processing centers in Bavaria and North Rhine-Westphalia actively focus on sourcing ingredients that meet stringent European safety standards.
Poland
Poland's significant meat processing sector, serving both domestic and European export markets, provides a stable demand base for smoke flavorings. Compliance with EFSA standards for smoke flavorings is a critical factor for market access. Industrial food production facilities around Warsaw and Poznan increasingly invest in advanced purification technologies to meet these regulatory requirements.
Brazil
Brazil's expanding processed food consumption and rising demand for savory snacks offer significant growth potential for smoke ingredients. National food safety agencies in Brazil are increasingly aligning with international standards, influencing ingredient specifications. Food processing zones in São Paulo and Minas Gerais explore diversified applications for smoke flavors beyond traditional meat products.
China
Rapid urbanization in China fuels substantial growth in processed food and convenience meal categories, creating new opportunities for smoke ingredients. China's national food safety standards are evolving, influencing ingredient composition and purification requirements. Major food manufacturing centers in the Yangtze River Delta integrate smoke ingredients into new product development for local and export markets.
Smoke Ingredients for Food Market Key Industry Players
Global majors compete with regional champions across product specialization and geographic reach. The market exhibits a tiered structure, with large ingredient conglomerates alongside specialized smoke flavor producers. These archetypes include broad-portfolio ingredient suppliers, dedicated liquid smoke technology specialists, and niche natural smoke producers. Companies engage in strategic partnerships to expand application areas and invest in advanced purification technologies to meet regulatory demands.
Specialists in liquid smoke technology, such as Red Arrow and ProFagus, exemplify focused expertise within the market. Red Arrow controls a significant portion of the North American market through its concentrated liquid smoke technology. ProFagus sustains its market position through unique beechwood-derived smoke products. These companies anchor the specialized segment, emphasizing proprietary production methods and deep product knowledge.
| Leading Market Players |
|---|
| Besmoke |
| WIBERG |
| Kerry Group |
| FRUTAROM Savory Solutions GmbH |
| Associated British Foods |
| Red Arrow |
| ProFagus |
| Dempsey Corporation |
| MSK |
| Others |
Cost & Logistics Intelligence
The shift towards purified liquid smoke applications simultaneously reshapes cost economics and supply concentration for food ingredient manufacturers. This transition necessitates significant capital expenditure in advanced purification technologies, impacting pricing structures and influencing the geographic clustering of production capabilities.
Pricing Analysis
Input costs for advanced filtration technologies are passed through, influencing the final pricing of purified smoke ingredients. Pricing stratifies across premium, standard, and economy tiers based on purification level and regulatory compliance, particularly for EFSA and FDA standards. Price differentiation also stems from certified sustainable wood sourcing and volume scale for industrial buyers. Pricing pressure stems from the high capital investment required for purification, while competition from natural flavor systems provides a downward force. Mass-market food product manufacturers exhibit the highest price sensitivity, whereas premium sauces and marinades producers prioritize quality and compliance over lowest cost.
Supply Chain Analysis
Logistics and freight costs for specialized wood types, like beechwood, contribute to regional supply chain complexities. Supply concentration for purified smoke ingredients centers in Germany, the United States, and Poland, reflecting established processed food industries and regulatory compliance. The supply chain relies on specific wood types and advanced filtration chemicals as key dependencies. Raw material volatility, particularly for specific wood sources, presents a structural supply chain risk. Distribution runs through wholesale channels, directly supplying large-scale food manufacturers and industrial processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a stable compounder, driven by the non-discretionary need for regulatory-compliant smoke flavors in processed food. Sustained consumption of traditional products and expansion into new categories provides consistent growth.
For Market Incumbents: Extend investment in advanced purification technologies to maintain regulatory compliance and product quality standards across all key markets. Focus R&D efforts on developing smoke flavors specifically tailored for plant-based meat alternatives to counter competition from natural flavor systems. Consolidate market share through strategic partnerships that expand geographic reach into emerging markets like Asia-Pacific.
For New Entrants and Emerging Players: Distribution partners offer a viable entry point for specialized smoke ingredient formulations. Target the vegan snacks and premium sauces segments, which demonstrate lower price sensitivity and higher demand for novel flavors. A go-to-market angle emphasizing clean-label, sustainably sourced products can differentiate offerings in North American and Western European markets. Emerging markets in Latin America present an opportunity for volume growth.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists lacking the capital for advanced purification technology upgrades. The long-term viability of this market is strong, given the sustained demand for processed foods and the expansion into diverse applications. Target specialized liquid smoke technology firms with proprietary purification intellectual property or strong positions in niche segments. The signal to watch is the pace of new EFSA or FDA regulatory updates, which can trigger further consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Purification Technology | Ensures compliance with stricter PAH regulations, maintaining market access in Europe and North America. |
| Develop Plant-Based Smoke Flavors | Captures growth in the expanding vegan food sector, broadening the addressable market for suppliers. |
| Expand into Emerging Markets | Accesses new consumer bases with rising processed food consumption, driving volume growth. |
| Micro-encapsulation Technology Adoption | Creates stable powdered smoke flavors for dry-mix applications, opening new snack and bakery markets. |
| Secure Sustainable Wood Sourcing | Meets clean-label demands from premium segment buyers, enhancing brand reputation and product differentiation. |
Research Approach
Bottom-up application modeling reconciled against top-down supply-side tracking forms the analytical core for this market study. The approach combines extensive primary interviews with food R&D directors, procurement managers, and regulatory compliance officers across key geographies. Secondary validation draws from EFSA reports, FDA guidance documents, industry association publications, and company financial filings.
Historical trendline analysis provides the foundation for projecting market dynamics across the analysis window. The forecast framework segments the market by ingredient type, source, application, distribution channel, and regional regulatory compliance. Compound annual growth rates were derived from historical growth patterns and future projections, incorporating key industry-specific forecast inputs like processed meat consumption trends and PAH regulatory thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving regulatory interpretations, raw material supply disruptions, and consumer perception shifts. Forecasts reflect assumptions documented in the full report, acknowledging inherent uncertainties. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Pumpkin Seed Protein Market
Ingredients
Marine Protein Market
Ingredients
PHO Oils Market
Ingredients
Zero-Calorie Oil Market
Ingredients
Baobab Ingredient Market
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Fish Gelatin Market
Ingredients
Global Amaranth Oil Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Savory Ingredients Market
Ingredients
Campesterol Market
Ingredients
Camelina Oil Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
Europe Soy Protein Market
Ingredients
Sunflower Meal Market
Ingredients
Europe Fats and Oil Market