
 Sesame Seed Extract Market | 2026-2036
Sesame Seed Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Sesame Seed Extract Market Insights
Cosmetic brands is hardening their share of sesame seed extract offtake as formulators pivot from synthetic emollients toward plant-derived alternatives. Dipasa Group leverages its vertically integrated Latin American seed sourcing to secure consistent raw material flows. McCormick & Company, Inc. anchors its position through flavor-house relationships that lock in multi-year extract supply contracts. Sabinsa competes on phytochemical standardization, publishing peer-reviewed sesamin and sesamolin potency data that cosmetic and nutraceutical buyers require for label claims.
Sesame seed extract comprises bioactive compounds—primarily lignans (sesamin, sesamolin, sesaminol), tocopherols, and unsaturated fatty acids—recovered from Sesamum indicum seeds through cold-pressing or solvent extraction, then refined for oxidative stability and specified purity grades. Its primary commercial purpose centers on delivering antioxidant, anti-inflammatory, and emollient functionality across topical, ingestible, and culinary applications. Oil and powder product types lead current revenue contribution, with oil commanding premium pricing in pharmaceutical-grade specifications while powder gains traction in protein-fortified food matrices. Nutraceuticals application is the fastest-expanding segment, driven by clinical validation of sesame lignans for lipid metabolism support, though food and beverage still occupies the largest absolute volume position due to tahini and condiment manufacturing scale.
EFSA maintains maximum residue limits for polycyclic aromatic hydrocarbons in edible vegetable oils, directly shaping extract refining investments and third-party testing protocols for European market access. India's FSSAI and CDSCO jointly govern sesame extract deployment in functional foods and Ayurvedic drug formulations, creating dual compliance pathways that domestic processors must navigate. The USDA and FDA oversee import inspections and GRAS notification requirements for sesame-derived ingredients entering United States food channels. Stakeholders should monitor evolving lignan concentration standards across these jurisdictions, as harmonization or divergence will determine which extraction technologies justify capital deployment.
Market Dynamics
REACH and EFSA contaminant thresholds are forcing extractors to retool refining infrastructure, compressing margins for non-compliant suppliers while rewarding processors with in-house chromatographic purification.
Growth Catalysts
- Clean-label formulation mandates:Functional food manufacturers are substituting synthetic antioxidants with sesame lignan concentrates to meet retailer clean-label requirements in Western European markets.
- Ayurvedic nutraceutical export protocols:India's CDSCO and FSSAI dual-track approvals are accelerating sesame extract deployment in standardized herbal drug formulations bound for North American and European markets.
- Supercritical CO2 extraction adoption:This solvent-free technology is recovering sesamin at higher purity grades than hexane methods, unlocking pharmaceutical-grade certifications previously unattainable for botanical processors.
Market Restraints
- PAH contamination thresholds:EFSA maximum residue limits for polycyclic aromatic hydrocarbons in edible oils force third-party testing protocols that add 12-18% to unit processing costs for European market access.
- Seed supply concentration:Over 60% of global sesame cultivation concentrates in Sudan, Ethiopia, and Myanmar, exposing processors to climate-induced yield volatility and currency fluctuation risks.
- Substitution by synthetic tocopherols:DL-alpha-tocopheryl acetate offers equivalent antioxidant functionality at 40-60% lower input cost, pressuring sesame extract pricing in mass-market food applications.
Strategic Opportunities
- Underpenetrated Latin American nutraceutical channels:Brazil's ANVISA is streamlining botanical ingredient notifications, creating first-mover advantage for sesame lignan suppliers targeting the region's expanding functional supplement retail sector.
- Cosmeceutical emollient convergence:Formulators are blending sesame oil with ceramide complexes for barrier-repair topical applications, opening premium positioning in dermatological skincare lines.
- India PLI scheme alignment:The government's production-linked incentive program for active pharmaceutical ingredients is subsidizing extraction capacity expansion for export-oriented sesame processors.
Industry Challenges
- Analytical chemistry talent scarcity:Phytochemical standardization requires HPLC-UV and LC-MS/MS competency that exceeds current technical training pipeline output in major processing regions.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of USDA Organic, EU Organic, and India Organic equivalency approvals extends product launch cycles by 14-22 months.
- Legacy solvent extraction asset stranding:Hexane-based facilities face accelerated depreciation as brand-owners impose solvent residue specifications below detectable thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sesame Seed Extract Market |
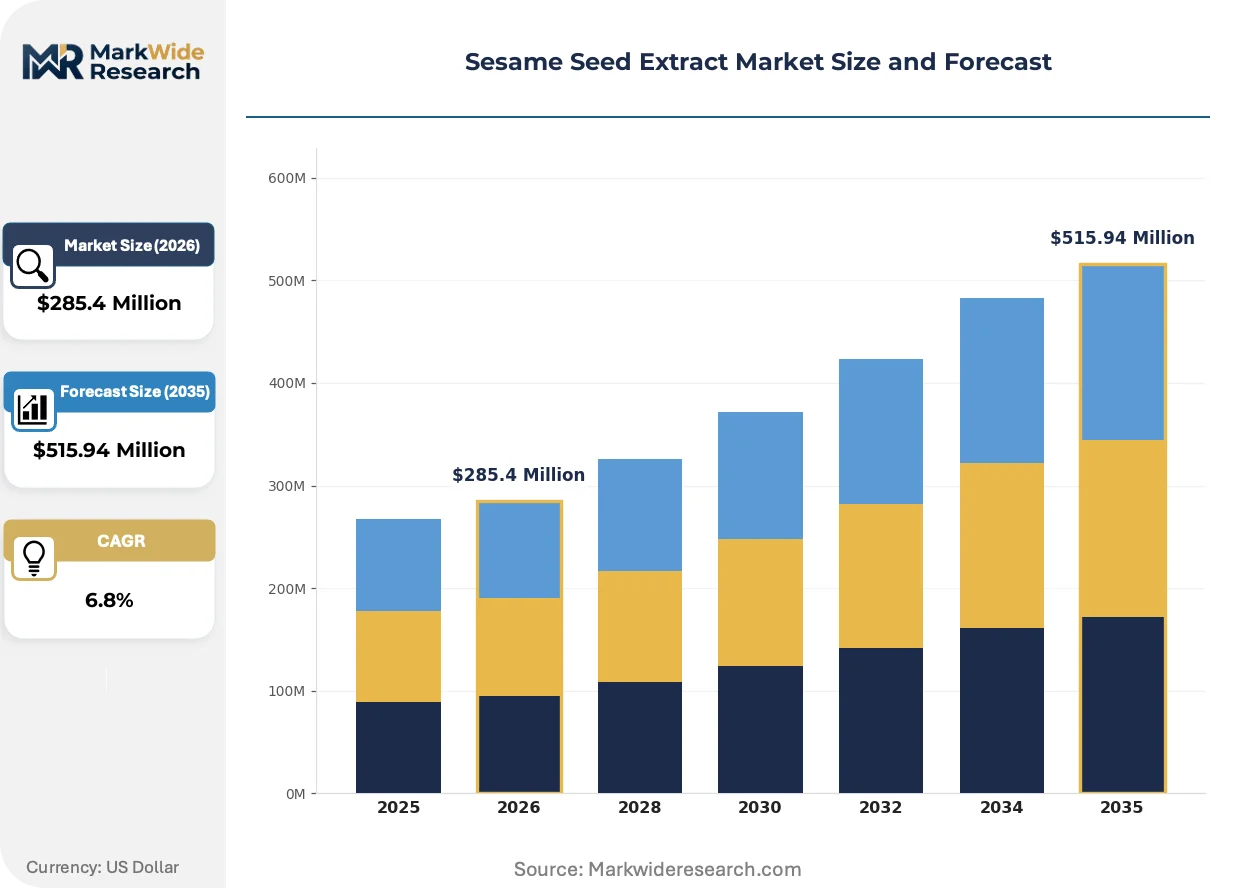
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Powder, Paste, Extract Application: Food & Beverage, Cosmetics, Nutraceuticals, Pharmaceuticals Form: Liquid, Solid, Semi-Solid, Gel End User: Food Manufacturers, Cosmetic Brands, Supplement Producers, Hospitals |
| Companies Covered | Dipasa Group, McCormick & Company, Inc., AGT Food & Ingredients, Grain Millers, Inc., The Hain Celestial Group, Sabinsa, Cargill Inc., Archer Daniels Midland Company, Phyto Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sesame Seed Extract Market Trends and Innovations
Extraction technology maturation and regulatory precision are converging to reshape competitive capabilities, with process control and certification speed emerging as decisive differentiators.
Supercritical CO2 extraction systems are integrating automated in-line monitoring of sesamin and sesamolin concentrations, enabling real-time purity adjustments. Pharmaceutical-grade oil manufacturers in Germany and Switzerland are adopting these systems to compress batch release timelines from weeks to days. The technology is integrating quality assurance directly into production flow, eliminating separate laboratory validation steps that previously bottlenecked export shipments.
EFSA's tightened polycyclic aromatic hydrocarbon limits are mandating activated carbon filtration and short-path distillation investments for European market entry. Refiners without these capabilities are losing shelf space in German and French retail channels. Sesame oil destined for infant formula and medical nutrition applications now requires documented PAH levels below 0.5 micrograms per kilogram, a specification only supercritical and molecular distillation methods reliably achieve.
Direct-procurement contracting is displacing spot-market purchasing among major flavor houses and cosmetic formulators. Buyers are locking in multi-year supply agreements with processors demonstrating chromatographic fingerprinting capabilities and batch-to-batch consistency. This pattern concentrates procurement volume with vertically integrated processors in India and Latin America, marginalizing traders lacking technical documentation infrastructure.
Sesame Seed Extract Market Segmentation
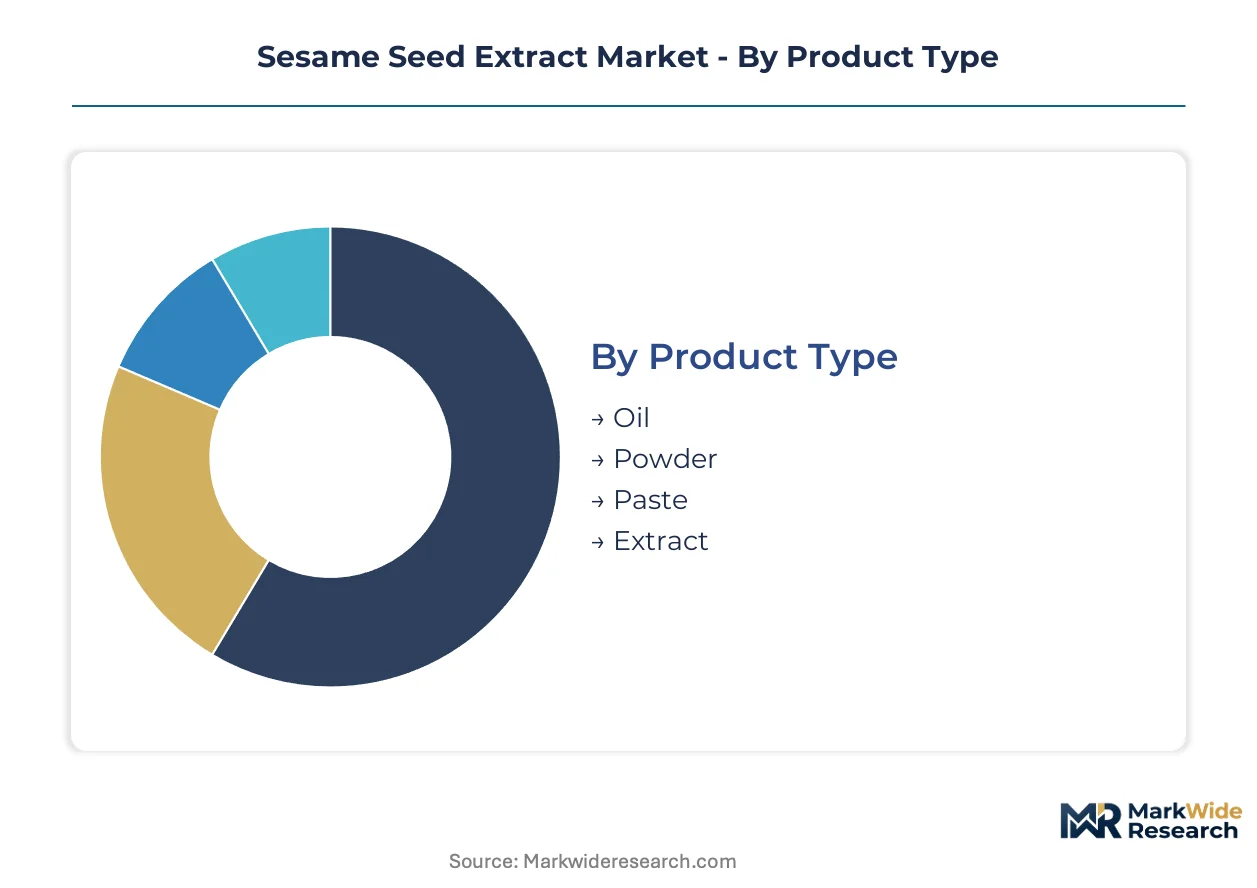
Segmentation in sesame seed extract markets reveals how processing technology and end-use specifications fragment procurement requirements. Buyers in pharmaceutical channels demand chromatographic purity certifications unavailable to food-grade purchasers. Formulators across cosmetics and nutraceuticals impose divergent lignan concentration thresholds that reshape extraction investment priorities.
Product Type:
Supply concentration in sesame seed extract production varies sharply by physical form, with oil commanding dedicated refining infrastructure while powder leverages shared protein processing assets.
- Oil:Cold-pressed or solvent-extracted liquid containing lignans, tocopherols, and unsaturated fatty acids at specified oxidative stability grades. Pharmaceutical-grade specifications in Germany and Switzerland require supercritical CO2 extraction with documented PAH levels below 0.5 micrograms per kilogram, compressing qualified supplier pools.
- Powder:Spray-dried or freeze-dried particulate form integrating into protein-fortified food matrices and encapsulated supplements. Demand concentrates in India's Ayurvedic nutraceutical export sector, where CDSCO and FSSAI dual-track approvals accelerate standardized herbal drug formulations.
- Paste:Semi-processed intermediate retaining seed particulate matter for tahini and condiment manufacturing. Middle Eastern and Mediterranean food processors dominate offtake.
- Extract:Refined concentrate standardized to specified sesamin and sesamolin potencies for label claims. Cosmetic formulators in France and Germany require peer-reviewed phytochemical documentation.
Oil absorbs the bulk of installed capacity; powder is expanding most quickly.
Application:
Application-driven demand fragmentation creates distinct certification burdens, with nutraceutical and pharmaceutical channels imposing analytical chemistry requirements that food and beverage buyers rarely specify.
- Food & Beverage:Tahini production, condiment manufacturing, and clean-label antioxidant substitution in Western European retail channels. EFSA maximum residue limits for polycyclic aromatic hydrocarbons force activated carbon filtration investments.
- Nutraceuticals:Lipid metabolism support supplements leveraging clinical validation of sesame lignans. India's export-oriented processors align with PLI scheme subsidies for active pharmaceutical ingredient extraction capacity.
- Cosmetics:Plant-derived emollient formulations displacing synthetic alternatives in barrier-repair skincare. Brazilian ANVISA streamlining of botanical ingredient notifications creates first-mover positioning opportunities.
- Pharmaceuticals:Medical nutrition and infant formula applications requiring molecular distillation methods for contaminant thresholds unattainable through conventional refining.
Food & Beverage retains the largest absolute volume position; nutraceuticals represent the steepest expansion trajectory.
Form:
Physical state determines packaging, stability, and dosing flexibility across divergent manufacturing workflows.
- Liquid:Bulk oil deliveries to flavor houses and cosmetic formulators with multi-year supply agreements locking in chromatographic fingerprinting capabilities.
- Solid:Powder and granule formats for tablet compression and dry blending in supplement manufacturing.
- Semi-Solid:Paste intermediates for tahini processors and ethnic food manufacturers.
- Gel:Structured delivery systems for topical dermatological applications and cosmeceutical emollient convergence with ceramide complexes.
Liquid dominates current procurement volume; gel formats are gaining share fastest in premium skincare channels.
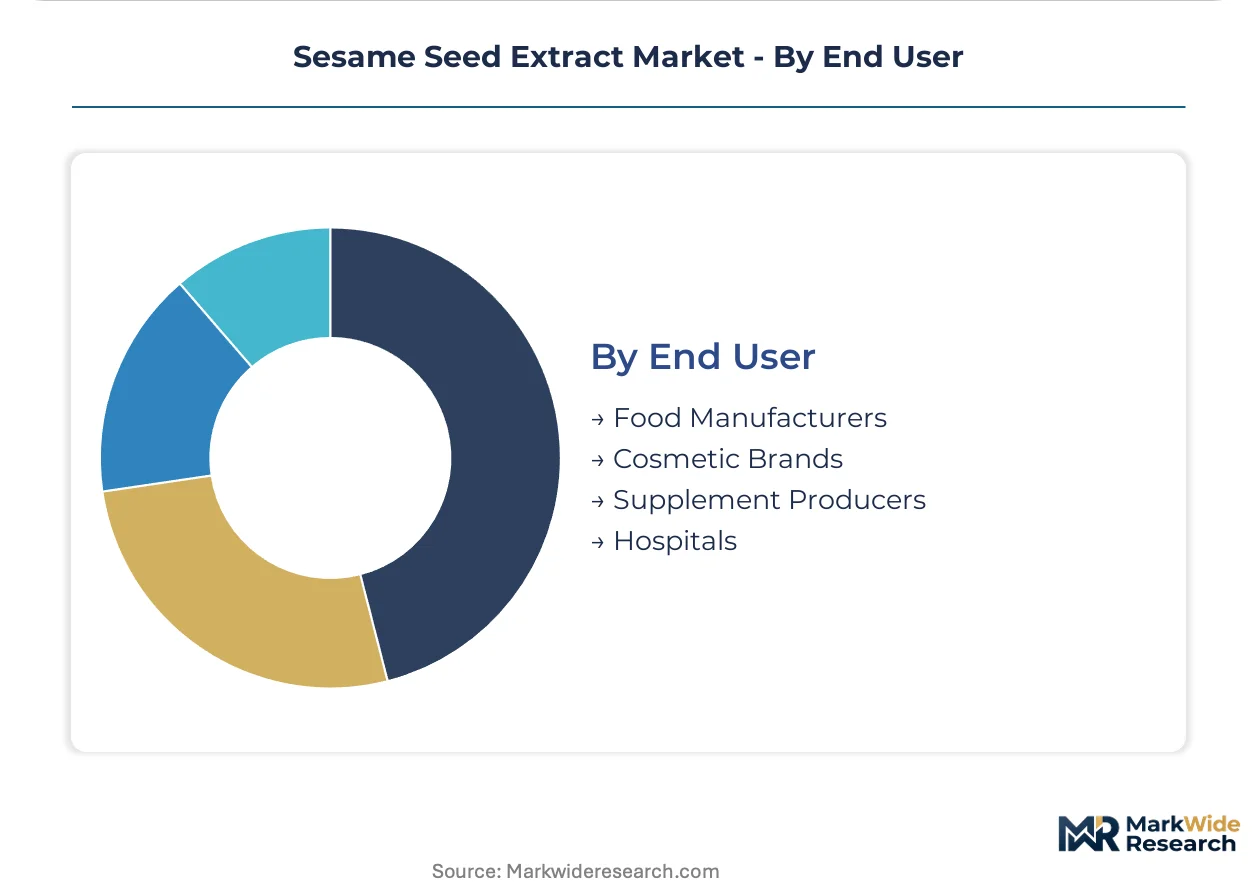
End User:
End-user concentration patterns reveal how direct-procurement contracting displaces spot-market purchasing among technically sophisticated buyers.
- Food Manufacturers:Tahini and condiment producers in Sudan, Ethiopia, and Myanmar sourcing from concentrated cultivation regions exposed to climate-induced yield volatility.
- Cosmetic Brands:Formulators pivoting from synthetic emollients toward plant-derived alternatives with documented batch-to-batch consistency.
- Supplement Producers:Ayurvedic and standardized herbal drug manufacturers navigating India's dual compliance pathways for functional food and drug formulations.
- Hospitals:Medical nutrition procurement requiring pharmaceutical-grade certifications with compressed batch release timelines from automated in-line monitoring systems.
Food Manufacturers absorb the bulk of raw material throughput; cosmetic brands are expanding specification requirements most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones for pharmaceutical ingredients concentrate sesame extract processing capacity near Hyderabad and Visakhapatnam, attracting PLI-linked investment from export-oriented refiners.
India
Ayurvedic nutraceutical exports and domestic oilseed processing expansion drive extract demand. FSSAI and CDSCO dual-track approvals create compliance complexity for functional food and drug formulations. Gujarat and Maharashtra house the largest concentration of cold-pressing and solvent extraction facilities serving European and North American buyers.
Germany
Pharmaceutical-grade oil procurement for medical nutrition and infant formula commands premium pricing. EFSA polycyclic aromatic hydrocarbon limits below 0.5 micrograms per kilogram mandate supercritical CO2 and molecular distillation investments. Hamburg and Frankfurt processing clusters specialize in contaminant-free refining for pediatric and geriatric applications.
United States
Clean-label antioxidant substitution in functional foods and flavor-house procurement sustain volume demand. FDA GRAS notification requirements and USDA import inspections govern sesame-derived ingredient entry. Chicago and New Jersey flavor manufacturing hubs lock in multi-year supply agreements with documented chromatographic fingerprinting.
Brazil
ANVISA streamlining of botanical ingredient notifications opens functional supplement retail channels previously blocked by regulatory friction. São Paulo and Rio de Janeiro nutraceutical distributors are establishing first-mover relationships with lignan concentrate suppliers. Domestic cosmetic formulators are testing sesame-ceramide blends for dermatological skincare lines.
Switzerland
Swissmedic pharmaceutical certifications and compressed batch release timelines attract supercritical extraction technology deployment. Basel and Zurich house automated in-line monitoring systems that compress laboratory validation from weeks to days. Medical nutrition manufacturers source exclusively from processors achieving documented PAH thresholds unattainable through conventional refining.
Sesame Seed Extract Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with flavor houses and cosmetic formulators favoring direct procurement while food processors rely on trader intermediaries. The supplier base concentrates around vertically integrated seed processors and phytochemical standardization laboratories. Three archetypes dominate: Latin American seed-to-extract integrators, Indian Ayurvedic ingredient platforms, and European pharmaceutical-grade refiners. Capacity expansion and chromatographic certification investments represent the dominant competitive moves as buyers impose solvent-residue specifications below detectable thresholds.
Among vertically integrated processors, Dipasa Group anchors the Latin American sourcing archetype through captive seed production. McCormick & Company, Inc. occupies the flavor-house relationship position with locked-in multi-year supply structures. Sabinsa exemplifies the phytochemical standardization tier, competing on peer-reviewed sesamin and sesamolin potency documentation that cosmetic and nutraceutical buyers require for label claims.
| Leading Market Players |
|---|
| Dipasa Group |
| McCormick & Company, Inc. |
| AGT Food & Ingredients |
| Grain Millers, Inc. |
| The Hain Celestial Group |
| Sabinsa |
| Cargill Inc. |
| Archer Daniels Midland Company |
| Phyto Life Sciences |
| Others |
Pricing and Supply Chain Analysis
Multi-year supply agreements locking in chromatographic fingerprinting capabilities are forcing processors to invest in supercritical CO2 infrastructure, compressing margins for hexane-dependent refiners while rewarding those achieving pharmaceutical-grade certifications. This procurement shift concentrates pricing power with vertically integrated suppliers in India and Latin America who can document batch-to-batch lignan consistency.
Pricing Analysis
Compressed batch release timelines command premium positioning, with pharmaceutical-grade oil buyers paying substantial markups for automated in-line monitoring systems that validate sesamin potency within days rather than weeks. Three-tier pricing structure across premium, standard, and economy levels separates supercritical-extracted pharmaceutical grades from cold-pressed food grades and solvent-extracted commodity tiers. Cost compression in the standard tier is intensifying because synthetic tocopherol substitutes offer equivalent antioxidant functionality at substantially lower input costs. Mass-market food manufacturers exhibit the highest price sensitivity, while cosmetic formulators and medical nutrition buyers prioritize certification documentation over unit cost.
Supply Chain Analysis
EFSA polycyclic aromatic hydrocarbon thresholds below 0.5 micrograms per kilogram function as qualification gates that exclude conventional hexane refiners from German and Swiss pharmaceutical channels. Raw material flows draw from Sudan, Ethiopia, and Myanmar, where over 60% of global sesame cultivation concentrates, creating exposure to climate-induced yield volatility and currency fluctuation risks. Activated carbon filtration and short-path distillation equipment dependencies tether downstream pharmaceutical certification to specialized refining infrastructure investments. Single-source vulnerability runs through concentrated cultivation regions lacking diversified agricultural insurance mechanisms. Distribution runs through direct-procurement contracting with flavor houses and cosmetic formulators displacing spot-market trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is accelerating into a vertical-integration race, with players pursuing upstream control over seed sourcing to secure consistent raw material flows against climate and currency risks.
For Market Incumbents: Anchor procurement relationships through locked-in multi-year supply agreements that specify chromatographic fingerprinting capabilities and documented PAH thresholds. Invest in supercritical CO2 extraction capacity to defend against synthetic tocopherol substitution threats in mass-market food applications. Expand backward integration into captive seed production in Latin America to mitigate supply concentration risks in Sudan and Ethiopia. For New Entrants and Emerging Players: E-commerce nutraceutical distribution channels offer lower barriers to entry than established flavor-house procurement networks dominated by incumbents. Target Brazil's ANVISA-streamlined botanical ingredient notification pathway as the most penetrable regulatory environment for first-mover lignan concentrate positioning. Pursue direct-to-supplement-brand relationships emphasizing peer-reviewed sesamin potency documentation as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors Indian Ayurvedic ingredient platforms with dual FSSAI-CDSCO compliance capabilities and existing PLI scheme alignment. Long-term viability rests on extraction technology transitions from legacy hexane assets to solvent-free supercritical systems. Monitor EFSA lignan concentration standard harmonization initiatives as the critical inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Unlocks pharmaceutical-grade certifications for EFSA-compliant European market access. |
| Backward Integration into Seed Sourcing | Secures consistent raw material flows against climate volatility in Sudan and Ethiopia. |
| Chromatographic Certification Investment | Enables batch-to-batch consistency documentation required by cosmetic formulators. |
| ANVISA Regulatory Pathway Entry | Captures first-mover positioning in Brazil's expanding functional supplement retail sector. |
| PLI Scheme Capacity Alignment | Accesses Indian government subsidies for export-oriented extraction infrastructure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with extraction plant managers, cosmetic formulator procurement leads, Ayurvedic drug manufacturers, and flavor-house supply chain directors. EFSA contaminant threshold documentation, FSSAI functional food approvals, CDSCO drug formulation registrations, and USDA import inspection records provided cross-jurisdictional validation. Bottom-up capacity assessments across Indian Special Economic Zones and Latin American seed processing clusters were triangulated against top-down demand estimates from nutraceutical and cosmeceutical end-use sectors.
Segmentation granularity extended to product type, application, physical form, and end-user archetype, with additional modeling of extraction technology tier and certification grade as industry-specific dimensions. CAGRs were derived from fitted growth curves applied to historical volume trajectories and projected procurement shifts across the analysis window. Forecast inputs incorporated supercritical CO2 adoption rates, EFSA PAH limit enforcement intensity, and PLI scheme subsidy disbursement patterns as sector-specific variables.
The model holds under stable regulatory enforcement and continued clean-label procurement preferences; deviation in EFSA lignan standard harmonization or synthetic tocopherol cost compression would shift volume trajectories. Forecasts reflect documented assumptions regarding technology adoption curves and certification timeline durations. A model refresh is warranted upon material change in REACH contaminant threshold revisions or ANVISA botanical ingredient notification streamlining.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Astragalus Root Extract Market
Ingredients
Terminalia Extract Market
Ingredients
Olive Leaf Extract Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Starch Market
Ingredients
Commercial Amino Acids Market
Ingredients
Fats and Oils Market
Ingredients
Europe Fats and Oil Market
Ingredients
Plant-Based API Market
Ingredients
Passion Fruit Powder Market
Ingredients
Hydroxytyrosol Market
Ingredients
Low Calorie Olive Oil Market
Ingredients
Sunflower Lecithin Market
Ingredients
Asia-Pacific Bakery Ingredients Market
Ingredients
Psyllium Products Market
Ingredients
Malted Wheat Flour Market