
 Asia-Pacific Carrageenan Market | 2026-2036
Asia-Pacific Carrageenan Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Carrageenan Market Outlook
Indonesia's seaweed processing corridor is reshaping regional supply dynamics. MCPI Corporation leverages integrated cultivation-to-extraction operations across the Philippine archipelago. Cargill, Incorporated anchors industrial-scale refining capacity with backward integration into red algae sourcing. W Hydrocolloids, Inc. competes on specialized kappa grades for dairy applications.
Carrageenan comprises sulfated polysaccharides extracted from Rhodophyceae seaweed, with kappa, iota, and lambda variants distinguished by ester sulfate content and calcium sensitivity; manufacturers deploy alkaline modification to control gel strength for targeted food system functionality. Kappa carrageenan dominates volume owing to its irreversible gelation with potassium, locking in margin pools for meat and dairy formulators. Refined grades command premium positioning as pharmaceutical and personal care end users reject semi-refined alternatives for injectable and topical applications. Powder form leads industrial handling efficiency, though gel suspensions gain traction in ready-to-drink beverage systems.
Philippine FDA labeling requirements and Indonesia's national food and drug regulator enforce additive declaration standards that filter non-compliant imports from regional trade channels. EFSA-aligned safety assessments from Australian and New Zealand food standards bodies influence formulation choices for export-oriented processors. China's SAMR maintains distinct GB standards for carrageenan purity that create separate qualification pathways for foreign suppliers. Stakeholders must monitor regulatory divergence between ASEAN harmonization talks and country-specific enforcement to optimize multi-territory product registration strategies.
Market Dynamics
Processed meat manufacturers across Southeast Asia are expanding carrageenan procurement for texture stabilization, tightening supply availability for dairy and pharmaceutical formulators competing for the same refined-grade pool.
Growth Catalysts
- Indonesia's labeling rule tightening:The national food safety authority's stricter additive declaration standards are pushing formulators toward refined carrageenan grades, creating quality-tier demand separation.
- Seaweed farming cooperatives:Philippine archipelago cultivation clusters now supply major extraction facilities with predictable raw material flows, reducing input volatility for regional processors.
- Potassium-gelation functionality:Kappa carrageenan's irreversible gelation properties lock in formulation stability for meat and dairy applications, sustaining procurement priority among food manufacturers.
Market Restraints
- Red algae supply concentration:Raw material sourcing clusters heavily in Philippine and Indonesian coastal zones, exposing processors to climate disruption and seasonal harvest variability.
- Semi-refined grade rejection:Pharmaceutical and personal care end users now reject semi-refined carrageenan for injectable and topical applications, compressing the addressable market for lower-grade producers.
- Lambda variant substitution:Lambda carrageenan's non-gelling properties limit its deployability in structured food systems, constraining volume growth outside beverage stabilization uses.
Strategic Opportunities
- Vietnam's underdeveloped extraction infrastructure:Limited domestic refining capacity creates white space for toll-processing partnerships or greenfield facility investment serving ASEAN export channels.
- Ready-to-drink beverage gel suspensions:Liquid carrageenan delivery formats are gaining traction among beverage formulators seeking streamlined handling versus powder reconstitution.
- Australian and New Zealand EFSA-aligned assessments:These safety evaluations influence formulation choices for export-oriented processors targeting premium-positioned dairy applications.
Industry Challenges
- Alkaline modification expertise scarcity:Controlling gel strength through precise alkaline processing requires specialized technical talent that extraction facilities struggle to recruit and retain.
- Multi-territory registration complexity:Divergent purity standards between China's SAMR GB requirements and ASEAN harmonization talks force suppliers to maintain parallel qualification pathways.
- Legacy powder handling infrastructure:Industrial-scale dairy and meat plants built around dry ingredient systems face retrofit costs to accommodate emerging gel suspension formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Carrageenan Market |
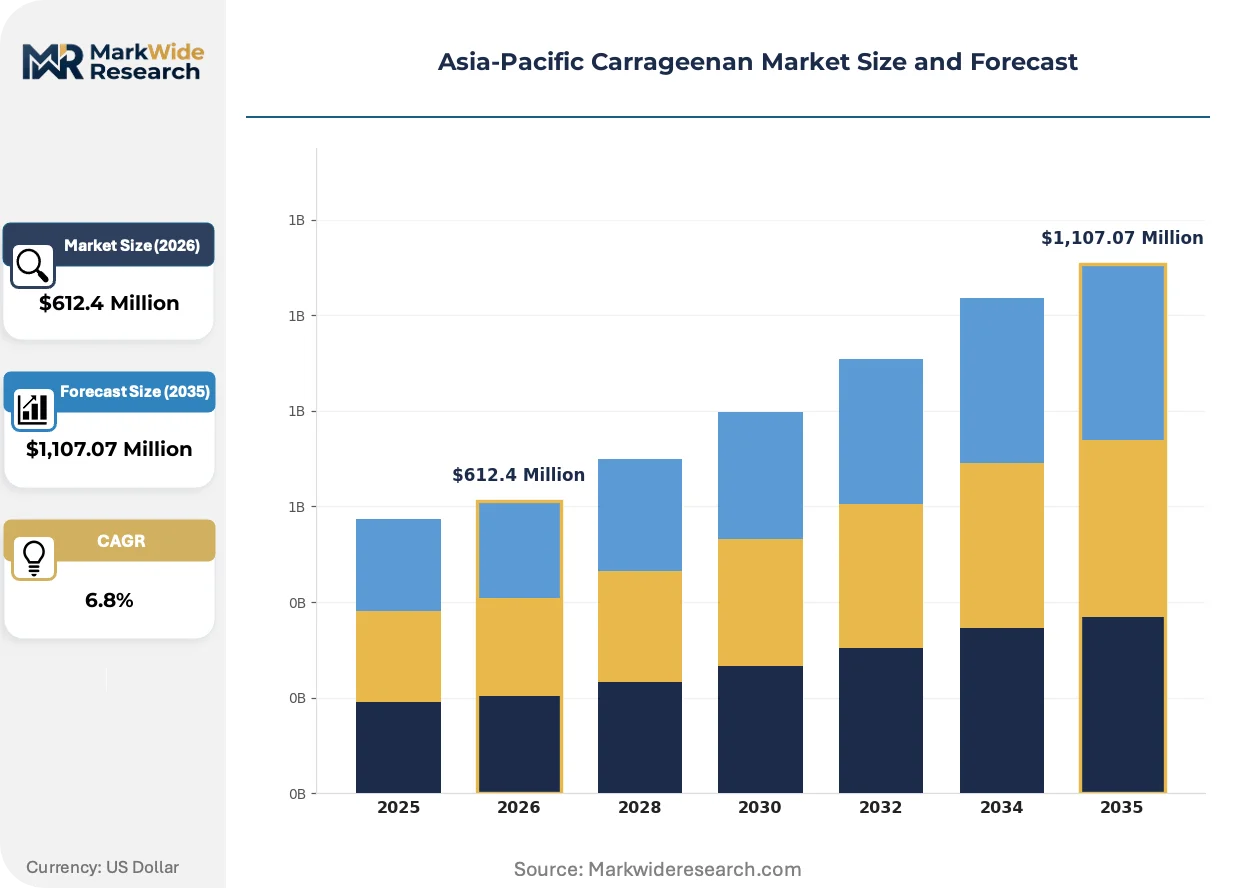
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kappa, Iota, Lambda, Refined End Use Industry: Food, Pharmaceuticals, Personal Care, Pet Food Form: Powder, Gel, Flake, Liquid Source: Red Algae, Green Algae, Brown Algae, Others |
| Companies Covered | Cargill, Incorporated, MCPI Corporation, Accel Carrageenan Corporation, Marcel Carrageenan, Caldic B.V., TBK Manufacturing Corporation, W Hydrocolloids, Inc., Ina Food Industry Co., Ltd., Shanghai Brilliant Gum, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Carrageenan Market Strategic Shifts
Alkaline modification protocols and hybrid extraction technologies are compressing grade differentiation in the Asia-Pacific carrageenan supply base, while regulatory divergence between national food safety bodies fragments compliance pathways.
Enzyme-assisted extraction is hybridizing traditional alkaline processing methods in Philippine and Indonesian facilities. Mid-scale processors are adopting enzymatic pre-treatment to improve yield rates and reduce chemical residue burdens. The technology is hybridizing competitive positioning between integrated cultivator-extractors and standalone refining operations by narrowing the efficiency gap.
China's SAMR maintains distinct GB standards for carrageenan purity that create separate qualification pathways for foreign suppliers. These technical specifications diverge from EFSA-aligned assessments used in Australian and New Zealand markets, forcing multi-territory suppliers to run parallel certification tracks. Refined-grade exporters targeting both markets face extended compliance timelines and duplicated testing expenditure.
Formulators are consolidating supplier relationships around integrated cultivator-extractors with captive seaweed supply. Dairy and meat manufacturers now prioritize procurement contracts with Philippine archipelago operations controlling their own red algae farming cooperatives. This preference shift is most visible in processed meat corridors across Indonesia, Thailand, and Vietnam, where supply security trumps spot-price optimization.
Asia-Pacific Carrageenan Market Segmentation
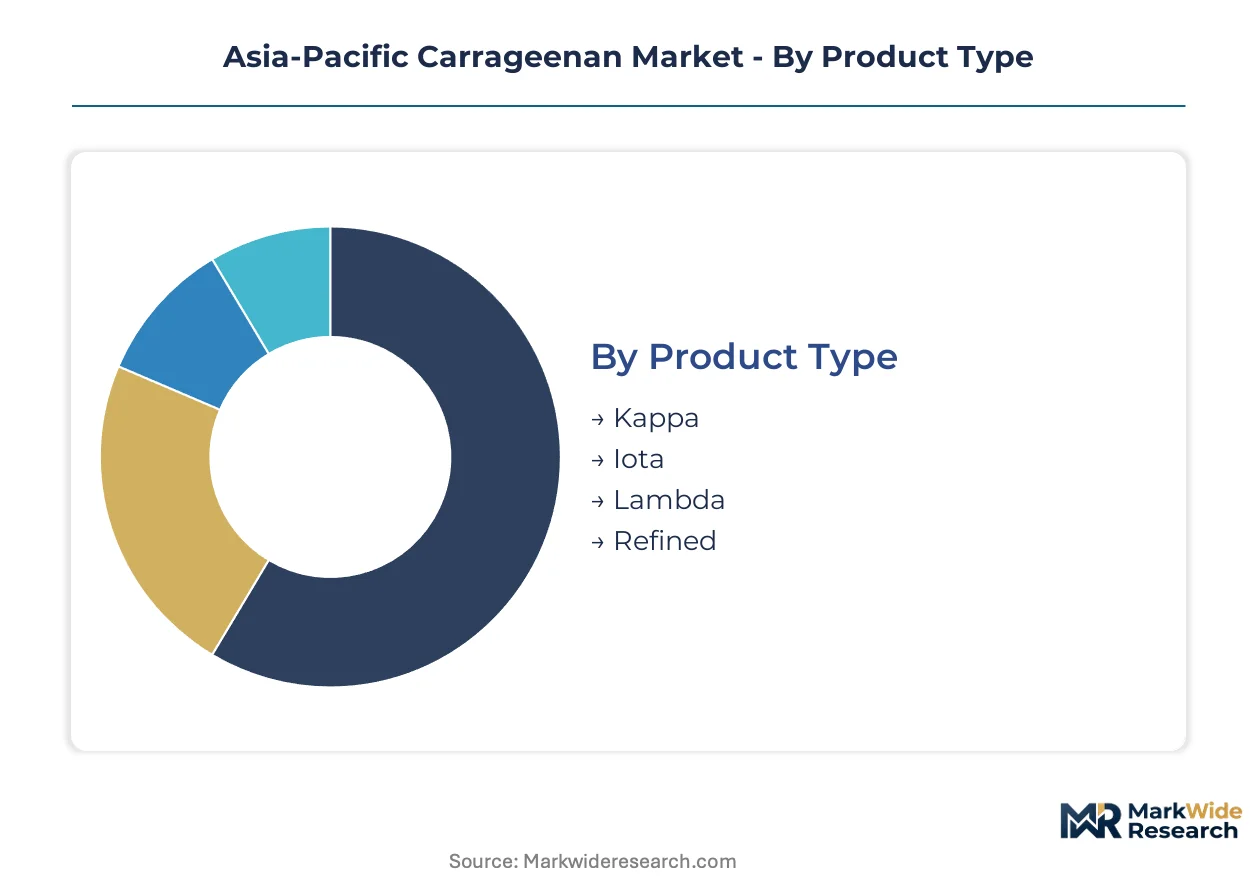
Carrageenan procurement patterns diverge sharply across product grades, end-use specifications, and delivery formats. Formulators in Southeast Asia select segments based on gelation kinetics, regulatory acceptance tiers, and handling infrastructure compatibility.
Product Type:
Kappa and refined grades turn inventory fastest in Philippine extraction facilities, while lambda variants sit longer due to narrower application windows. Iota occupies the middle ground with steady dairy sector offtake.
- Kappa:Sulfated polysaccharide with irreversible potassium-induced gelation dominates meat and dairy stabilization. Philippine processed meat corridors absorb the largest volumes, with Indonesia's labeling rule tightening reinforcing procurement priority for this grade.
- Refined:Higher-purity extraction yielding lower microbial and ash content qualifies for pharmaceutical injectables and premium personal care. Australian and New Zealand EFSA-aligned assessments drive demand concentration among export-oriented formulators seeking multi-territory registration efficiency.
- Iota:Calcium-reversible gelation suits soft dairy textures and water-dessert applications. Indonesian and Thai dairy processors favor this grade for cultured product stabilization.
- Lambda:Non-gelling thickener limited to beverage and sauce viscosity modification. Philippine ready-to-drink manufacturers represent the primary offtake channel.
Kappa anchors the volume base while refined grades gain share at the steepest rate.
End Use Industry:
Food manufacturers command the largest procurement volumes with shortest contract cycles, while pharmaceutical qualification timelines stretch 18-24 months for refined grade certification.
- Food:Processed meat stabilization across Indonesia, Thailand, and Vietnam consumes the majority of kappa supply. Dairy applications in the Philippines and Australia follow closely, with texture control requirements driving grade-specific sourcing.
- Pharmaceuticals:Injectable and topical formulation standards reject semi-refined alternatives, compressing the qualified supplier pool to integrated Philippine cultivator-extractors with captive red algae supply and documented traceability.
- Personal Care:Toothpaste gelling and cosmetic emulsion stabilization demand refined grades with controlled sulfate content. Australian formulators lead regional offtake for this segment.
- Pet Food:Canned meat analog texture modification represents a price-sensitive volume outlet for semi-refined kappa grades with less stringent purity requirements.
Food applications anchor the volume base while pharmaceutical qualification represents the steepest expansion trajectory for margin-accretive refined grades.
Form:
Powder dominates industrial handling infrastructure across legacy dairy and meat plants, while gel suspensions require shorter production cycles for beverage formulators seeking streamlined reconstitution.
- Powder:Spray-dried standard format compatible with existing dry ingredient handling systems throughout Indonesian and Vietnamese processing corridors. Bulk density and flowability specifications vary by end-use hydration requirements.
- Gel:Pre-hydrated suspensions reduce processing time for ready-to-drink beverage manufacturers in the Philippines and Thailand. Cold-soluble variants target temperature-sensitive applications.
- Flake:Intermediate moisture format favored by smaller-scale extractors for regional trade. Limited industrial adoption outside artisanal food processing.
- Liquid:Concentrated solutions for automated dosing systems in large-scale dairy operations. Australian processors lead adoption for continuous production line integration.
Powder anchors the volume base while gel suspensions climb the fastest among format conversions.
Source:
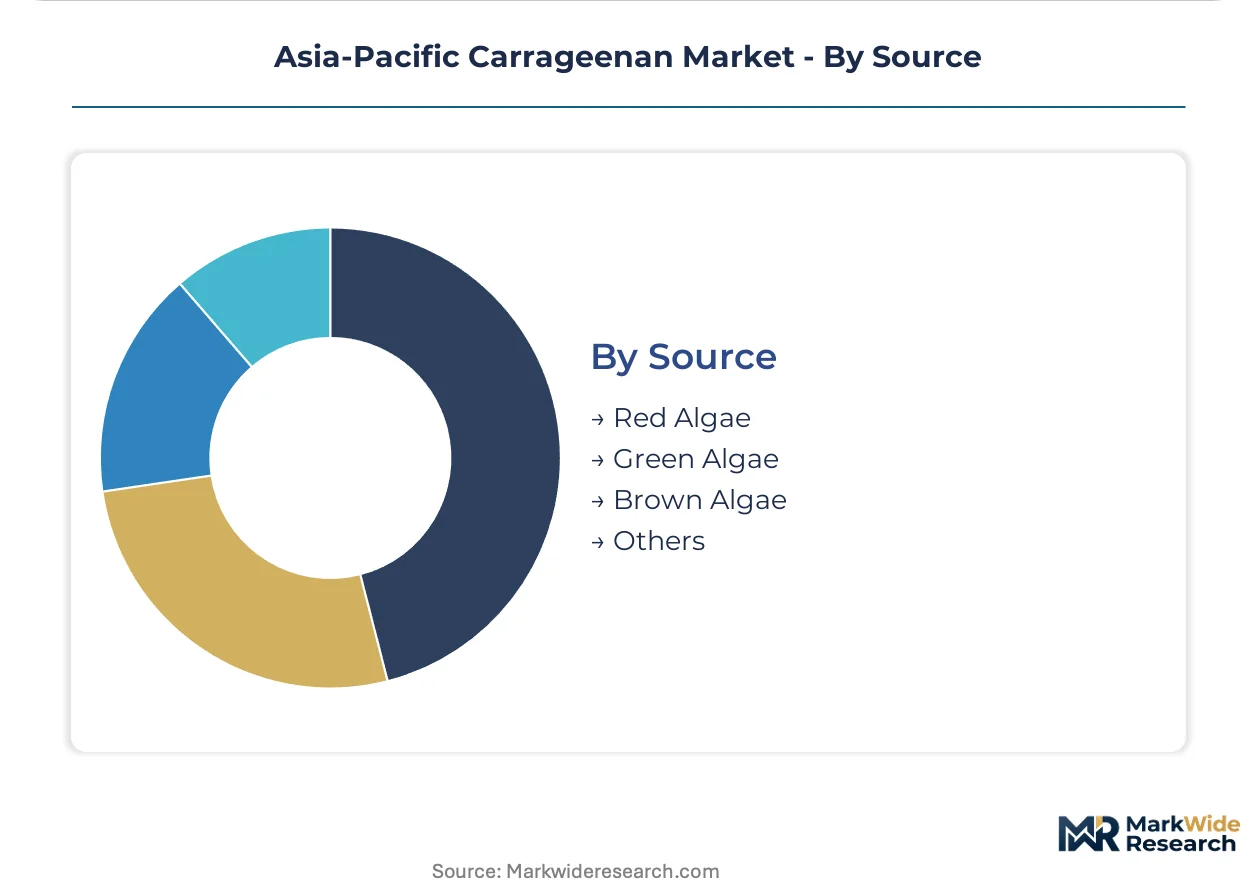
Red algae harvest cycles concentrate in Philippine and Indonesian coastal zones with 45-60 day seasonal variability, while alternative seaweed sources remain experimental with longer development timelines.
- Red Algae:Rhodophyceae species Eucheuma cottonii and Kappaphycus alvarezii supply kappa and iota fractions. Philippine archipelago farming cooperatives deliver predictable raw material flows to major extraction facilities.
- Green Algae:Chlorophyta-derived polysaccharides with distinct rheological properties. Limited commercial extraction at scale; research-stage applications in alternative stabilizer development.
- Brown Algae:Phaeophyceae sources yield alginates rather than true carrageenan; occasional misclassification in regional trade documentation creates qualification friction for importers.
- Others:Hypnea and Gigartina species with specialized sulfate patterns. Niche sourcing for lambda fraction enrichment in Philippine laboratory-scale extraction.
Red algae anchors the volume base while green algae research programs represent the longest-cycle development bet.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Asia-Pacific carrageenan market diverge sharply by end-use priority. Philippine processors prioritize dairy and pharmaceutical grades, while Indonesian manufacturers concentrate on processed meat stabilization. Australian formulators emphasize export-grade refined specifications aligned with EFSA assessments.
Philippines
Seaweed farming cooperatives in the Philippine archipelago supply major extraction facilities with predictable raw material flows. The Philippine FDA enforces additive declaration standards that filter non-compliant imports from regional trade channels. Cebu and Mindanao processing corridors absorb the largest kappa volumes for domestic dairy and meat applications.
Indonesia
Processed meat manufacturers across Java and Sumatra are expanding carrageenan procurement for texture stabilization. The national food safety authority tightened additive labeling rules, pushing formulators toward refined grades. The seaweed processing corridor from Sulawesi to East Java is reshaping regional supply dynamics through integrated cultivation-to-extraction operations.
China
Domestic dairy processors drive refined-grade demand for cultured product stabilization. SAMR maintains distinct GB standards for carrageenan purity that create separate qualification pathways for foreign suppliers. Shandong and Fujian extraction clusters serve both food and industrial applications with differentiated grade outputs.
Australia
Export-oriented dairy formulators prioritize EFSA-aligned safety assessments for multi-territory registration efficiency. Food Standards Australia New Zealand influences formulation choices for premium-positioned applications. Victorian and New South Wales processing plants lead regional adoption of gel suspension formats for continuous production line integration.
Vietnam
Limited domestic refining capacity creates white space for toll-processing partnerships serving ASEAN export channels. Processed meat corridors in the Mekong Delta absorb semi-refined kappa grades for canned product texture modification. Ho Chi Minh City logistics hubs facilitate re-export to Thai and Cambodian formulators.
Asia-Pacific Carrageenan Market Competitive Environment
Capability concentration sits with integrated cultivator-extractors; scale advantage sits with diversified agribusiness conglomerates. Philippine archipelago operations controlling captive red algae supply lock in procurement priority from risk-averse formulators. Three archetypes dominate: integrated seaweed-to-refinery operators, standalone toll processors, and diversified hydrocolloid portfolios. Competitive moves center on backward integration into farming cooperatives and alkaline modification capacity expansion.
Within the integrated tier, MCPI Corporation and Cargill, Incorporated exemplify divergent scale positions. MCPI leverages archipelago cultivation clusters for supply security. Cargill anchors industrial-scale refining with upstream control over red algae sourcing. W Hydrocolloids, Inc. occupies a specialized position among mid-scale Philippine processors competing on kappa grade differentiation for dairy applications.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| MCPI Corporation |
| Accel Carrageenan Corporation |
| Marcel Carrageenan |
| Caldic B.V. |
| TBK Manufacturing Corporation |
| W Hydrocolloids, Inc. |
| Ina Food Industry Co., Ltd. |
| Shanghai Brilliant Gum |
| Others |
Value Chain & Pricing Dynamics
Underutilized refining capacity in Vietnam's Mekong Delta is compressing spot-market premiums for semi-refined kappa grades while tightening contract terms for Philippine refined supply. This utilization asymmetry rewards integrated cultivator-extractors with captive seaweed flows while squeezing standalone toll processors dependent on variable raw material procurement.
Pricing Analysis
Long-term offtake agreements dominate procurement between Philippine integrated operators and Indonesian processed meat manufacturers, locking in volume commitments that insulate against spot volatility. Price differentiation separates pharmaceutical-grade refined carrageenan with documented traceability from semi-refined kappa used in pet food applications. Pricing pressure stems from lambda variant substitution in beverage stabilization, where guar gum alternatives erode volume commitment leverage. Dairy formulators in Australia exhibit lowest price sensitivity due to EFSA-aligned registration requirements that limit qualified supplier pools, while Vietnamese canned meat processors negotiate aggressively on semi-refined grades.
Supply Chain Analysis
Export-control regimes on red algae germplasm limit technology transfer between Philippine farming cooperatives and prospective Vietnamese cultivation ventures, constraining supply base expansion. Raw material sourcing concentrates in Philippine archipelago waters and Indonesia's Sulawesi-to-East Java corridor, with extraction capacity clustering in Cebu and Mindanao. The supply chain rests on seasonal harvest cycles of Eucheuma cottonii and Kappaphycus alvarezii with 45-60 day variability, creating single-source vulnerability during monsoon disruption. Distribution runs through Ho Chi Minh City logistics hubs for ASEAN re-export, with direct vessel chartering from Mindanao to Jakarta bypassing intermediate consolidation for large meat processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Indonesian and Vietnamese processed meat manufacturers consolidating procurement through multi-year framework agreements with Philippine integrated suppliers. This consolidation fragments pricing leverage for standalone extractors lacking captive seaweed supply.
For Market Incumbents: Entrench supply security through backward integration into Mindanao farming cooperatives, securing germplasm access that emerging Vietnamese competitors cannot replicate. Expand alkaline modification capacity in Cebu to capture pharmaceutical-grade margin pools before regulatory divergence between China's SAMR and ASEAN harmonization talks hardens qualification barriers. Prioritize certification investment for EFSA-aligned assessments that lock in Australian dairy formulator relationships against mid-scale Philippine rivals. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's toll-processing white space by partnering with Mekong Delta semi-refined operators lacking refining technology. Target gel suspension format conversion for Thai ready-to-drink beverage manufacturers seeking streamlined handling versus powder reconstitution. Pursue a go-to-market angle emphasizing cold-soluble variant development for temperature-sensitive dairy applications in Australia's Victorian processing corridor. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated cultivator-extractors with captive red algae supply and multi-year offtake agreements with Indonesian meat processors. Long-term viability across the analysis window favors Philippine archipelago operations controlling farming cooperative relationships against standalone refining assets vulnerable to raw material volatility. Watch for inflection in China's SAMR enforcement posture toward foreign carrageenan suppliers, which would compress qualified supplier pools and elevate acquisition premiums for GB-certified operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Farming | Captive supply of Eucheuma cottonii insulates Philippine extractors from monsoon-driven harvest volatility. |
| Alkaline Modification Capacity Expansion | Gel strength control capabilities unlock pharmaceutical-grade qualification with Australian TGA-aligned formulators. |
| Gel Suspension Format Development | Pre-hydrated delivery reduces Thai beverage manufacturer processing time versus powder reconstitution systems. |
| EFSA-Aligned Certification Investment | Multi-territory registration efficiency attracts Australian dairy processors exporting to European markets. |
| Toll-Processing Partnership in Vietnam | Underutilized Mekong Delta refining capacity offers ASEAN export channel access without greenfield capital deployment. |
Study Parameters
Desk research of trade flow databases, customs declarations, and regulatory filing repositories preceded structured interviews with Philippine extraction facility technical directors, Indonesian processed meat procurement managers, Australian dairy formulator regulatory affairs leads, and Vietnamese toll-processing operators. Secondary validation drew from ASEAN food additive harmonization documentation, China's SAMR GB standard publications, and EFSA safety assessment archives. Bottom-up volume modeling across cultivation area yields and extraction facility throughput triangulated against top-down demand aggregation by end-use industry.
Assumptions held fixed include current regulatory divergence between China's SAMR and ASEAN harmonization frameworks, existing Philippine-Indonesia raw material flow patterns, and prevailing alkaline modification technology yields. Segmentation dimensions modeled span product grade tier, end-use industry application, delivery format, and regional production hub concentration. CAGRs derived from slope analysis of historical volume trajectories adjusted for capacity expansion announcements and cultivation area development timelines. Industry-specific forecast inputs incorporated seaweed farming cooperative yield variability and pharmaceutical qualification timeline durations.
Macroeconomic conditions sit as an overlay; deviation in regional currency volatility, maritime freight rates, or red algae commodity pricing would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Material shifts in Philippine FDA enforcement posture, Indonesian labeling rule implementation stringency, or Chinese import qualification pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Textured Milk Protein Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Pet Food Premix Market
Ingredients
North America Prebiotic Ingredients Market
Ingredients
Europe Sodium Reduction Ingredient Market
Ingredients
Caramel Malt Market
Ingredients
Middle East Feed Palatability Enhancers Market
Ingredients
Calendula Oil Market
Ingredients
Salad Oil Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Citrus Pectin Market
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Middle East and Africa Dairy Ingredients Market
Ingredients
US Ingredients Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Industrial and Bar-B-Que Charcoal Market