
 Middle East and Africa Dairy Protein Ingredients Market | 2026-2036
Middle East and Africa Dairy Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Dairy Protein Ingredients Market Foresight
A capital-intensity divergence between integrated dairy processors and ingredient traders is bifurcating competitive dynamics in the Middle East and Africa Dairy Protein Ingredients Market. Fonterra Co-operative Group leverages its New Zealand-sourced whey streams to anchor supply security for Gulf nutraceutical customers. Almarai Company sustains captive milk supplies across Saudi Arabia, allowing backward integration into milk protein isolate production. Baladna Food Industries competes on scale in Qatar, where state-backed dairy infrastructure supports casein protein output for regional export.
Dairy protein ingredients comprise concentrated or isolated protein fractions extracted from bovine milk through ultrafiltration, ion exchange, or enzymatic hydrolysis, typically yielding protein contents from 35% to 90% depending on processing intensity; these ingredients function as emulsifiers, gelling agents, and nutritional fortifiers across formulated food systems. Whey protein concentrate occupies the largest volume share due to its cost-performance ratio in sports nutrition applications, while hydrolyzed whey commands premium positioning among allergen-sensitive infant formula manufacturers. Milk protein isolate concentrates margin pools where clean-label dairy claims support functional foods positioning in South African and UAE retail channels.
Saudi Food and Drug Authority protein labeling standards and South African Department of Health fortification regulations shape product formulation requirements across the region, with Gulf Cooperation Council technical barriers affecting import access for non-compliant suppliers. ISO 17025 accreditation and halal certification protocols from bodies such as Emirates Authority for Standardization and Metrology further filter market participation. Stakeholders must monitor evolving Gulf nutrition claims enforcement and local dairy self-sufficiency targets that could redirect import dependency patterns.
Market Dynamics
Backward integration into captive milk supply chains is bifurcating competitive positioning between integrated Saudi processors and import-dependent traders across the Middle East and Africa Dairy Protein Ingredients Market.
Growth Catalysts
- Sports nutrition expansion:Fitness culture proliferation in UAE and Saudi Arabia drives whey protein concentrate absorption across gym chains and e-commerce platforms. Protein fortification mandates from South African Department of Health accelerate industrial demand.
- SFDA enforcement tightening:Saudi Food and Drug Authority protein content verification requirements filter non-compliant imports, creating quality-tier differentiation that rewards accredited suppliers.
- Halal certification protocols:Emirates Authority for Standardization and Metrology accreditation opens Gulf Cooperation Council procurement channels for compliant ingredient manufacturers.
Market Restraints
- Feed cost volatility:Alfalfa and soybean meal price swings compress margin pools for Egyptian and Moroccan dairy processors lacking long-term forage contracts.
- Import dependency concentration:New Zealand and EU whey stream dominance creates supply security exposure for Gulf nutraceutical formulators during ocean freight disruptions.
- Technical substitution pressure:Pea and rice protein isolates achieve functional parity in select beverage applications, eroding dairy protein exclusivity in plant-forward formulation segments.
Strategic Opportunities
- Qatar state-backed infrastructure:Baladna Food Industries' scaled casein production creates regional export hub potential for North African infant formula manufacturers.
- Clean-label functional foods:South African retail channels reward milk protein isolate positioning in high-protein dairy alternatives and medical nutrition segments.
- Enzymatic hydrolysis convergence:Combination of membrane filtration and targeted proteolysis enables premium allergen-reduced ingredient tiers for sensitive pediatric applications.
Industry Challenges
- ISO 17025 accreditation timelines:Laboratory certification delays for protein assay validation extend product qualification cycles by six to twelve months for new market entrants.
- Halal supply chain integrity:Cross-border documentation of animal welfare and slaughter compliance creates audit complexity for multi-origin whey processors.
- Skill scarcity in membrane operations:Ultrafiltration and diafiltration expertise shortages limit operational uptime for mid-scale Egyptian and Kenyan dairy ingredient ventures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Dairy Protein Ingredients Market |
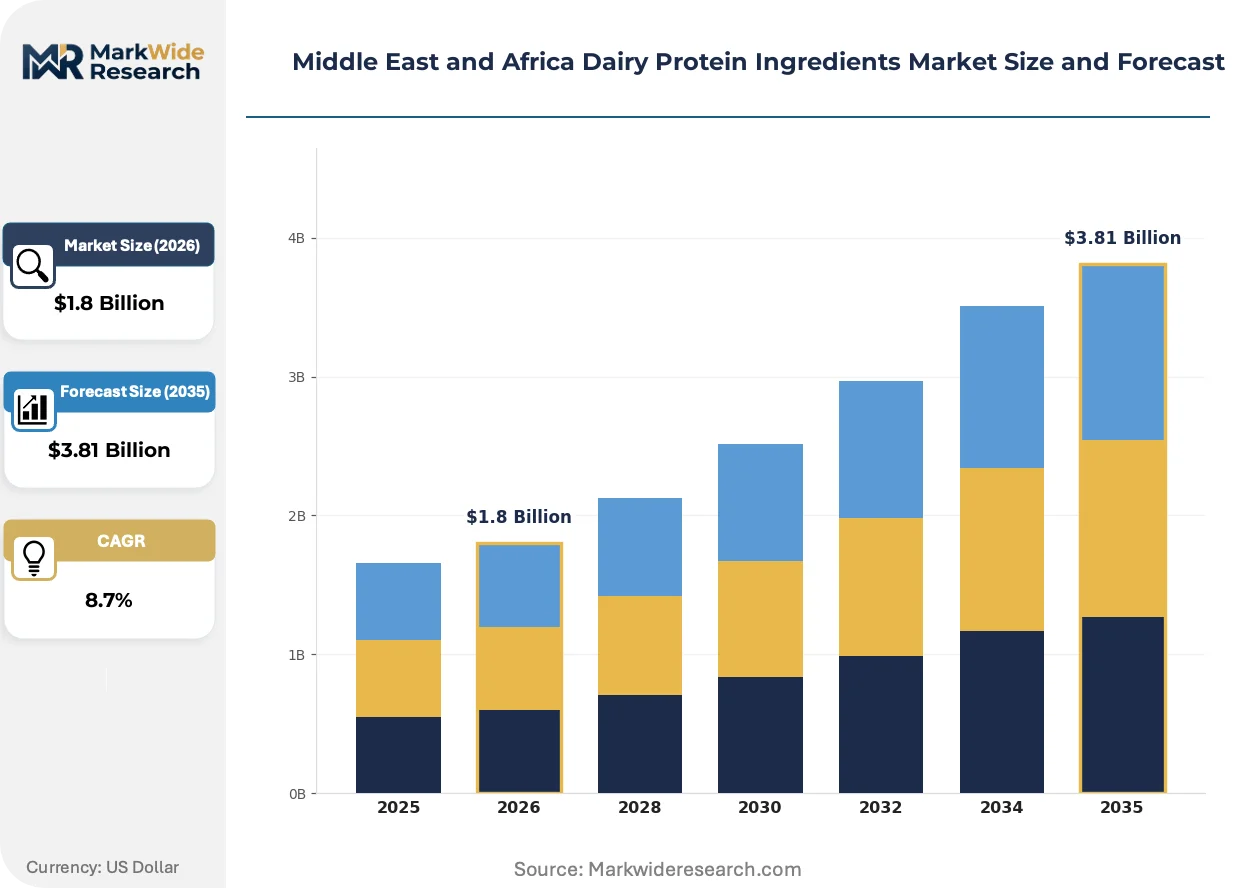
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Concentrate, Casein Protein, Hydrolyzed Whey, Milk Protein Isolate End User: Dairy Manufacturers, Nutraceutical Companies, Food & Beverage Industry, Sports Nutrition Application: Protein Supplements, Functional Foods, Infant Formula, Bakery Products Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Almarai Company, Fonterra Co-operative Group, Lactalis Ingredients, Arla Foods Ingredients Group P/S, Kerry Group, Glanbia plc, Clover Industries Limited, Saudi Dairy & Foodstuff Company (SADAFCO), Baladna Food Industries, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Dairy Protein Ingredients Market Shifts & Advancements
Processing technology convergence and regulatory stringency are compressing traditional supply hierarchies while opening premium tiers for verified-clean ingredients across Middle Eastern and African markets.
Membrane filtration cascades with integrated chromatography polishing are supplanting conventional whey protein concentration methods. South African functional food manufacturers adopt these systems to achieve 90%+ protein purity with reduced lactose carryover. The structural consequence is margin compression for legacy spray-dried concentrate suppliers while enabling clean-label positioning in UAE retail channels.
Saudi Food and Drug Authority nutrition claims enforcement tightens protein content declaration tolerances for imported ingredients. Industrial consequence includes batch-level testing cost absorption and supplier qualification narrowing. Infant formula and sports nutrition segments in Riyadh and Jeddah procurement offices respond by consolidating vendor bases toward ISO 17025-accredited sources.
Direct procurement relationships between Gulf nutraceutical brands and New Zealand cooperative processors are shortening traditional trader-mediated channels. Large-scale gym chains and e-commerce platforms in Dubai and Abu Dhabi now contract volume directly, displacing regional distributor markups. This pattern concentrates most visibly in whey protein isolate categories where traceability documentation supports premium positioning.
Middle East and Africa Dairy Protein Ingredients Market Segmentation
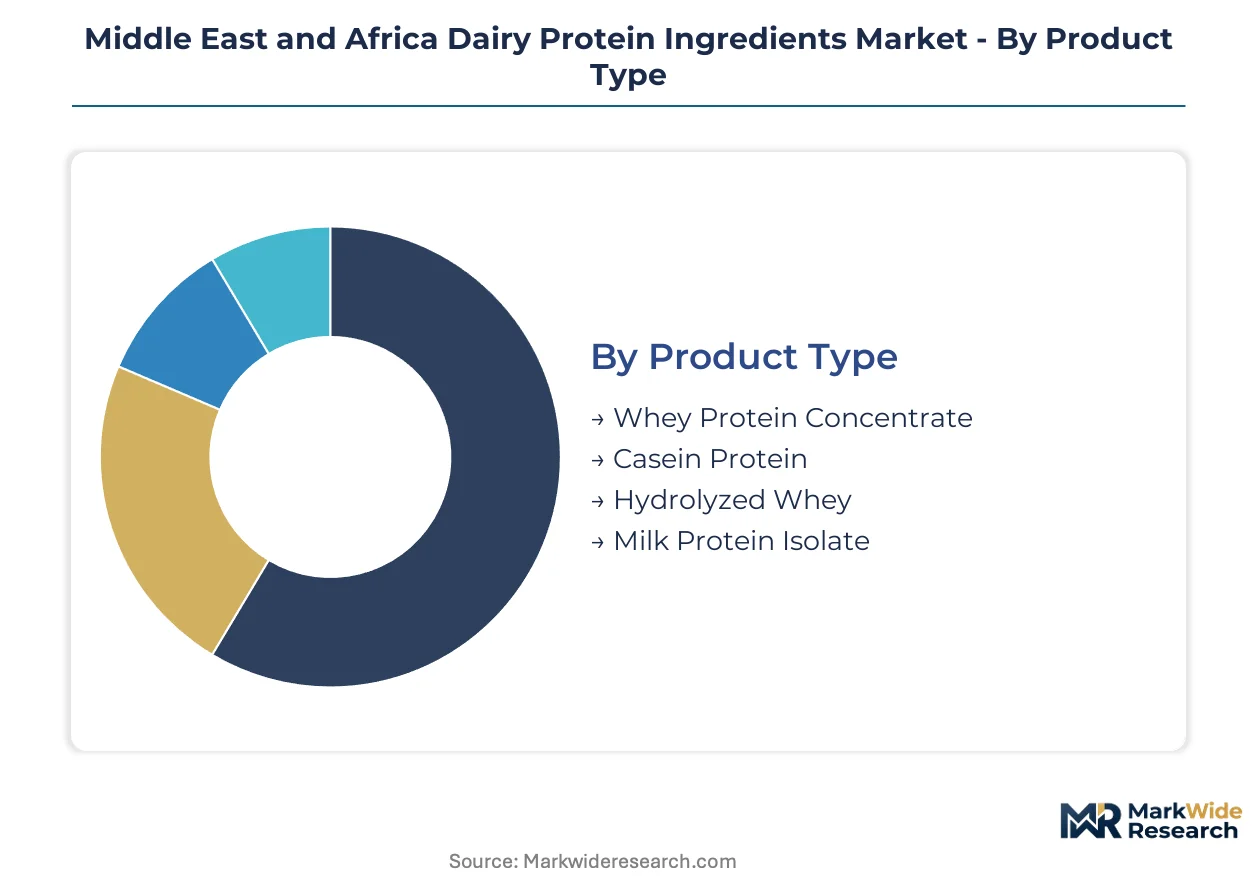
Segmentation in the Middle East and Africa Dairy Protein Ingredients Market reveals how regulatory stringency and supply chain configuration concentrate margin pools across distinct product tiers. Understanding these divisions enables stakeholders to align certification investments with channel access requirements.
Product Type:
SFDA protein labeling enforcement and halal certification protocols from Emirates Authority for Standardization and Metrology differentiate acceptable tiers for Gulf market entry.
- Whey Protein Concentrate:Contains 35-80% protein with residual lactose and fat fractions, produced through ultrafiltration and diafiltration of cheese whey. Gym chains and e-commerce platforms across Dubai and Riyadh absorb volume for sports nutrition applications, though import dependency on New Zealand streams creates supply security exposure during freight disruptions.
- Hydrolyzed Whey:Enzymatically predigested protein with reduced allergenic epitopes, achieving rapid absorption kinetics. Infant formula manufacturers in South Africa's functional food corridor pay premiums for SFDA-compliant batches that support reduced-allergen pediatric claims in Saudi retail channels.
- Casein Protein:Slow-digesting micellar protein from skim milk coagulation, valued for sustained amino acid release. Baladna Food Industries in Qatar leverages state-backed dairy infrastructure for regional export to North African formulators.
- Milk Protein Isolate:Combined casein and whey fractions at 90%+ protein purity, enabling clean-label dairy positioning. UAE retail channels reward this tier for high-protein dairy alternatives and medical nutrition segments.
Whey Protein Concentrate handles the majority of throughput; Hydrolyzed Whey is expanding most quickly on share.
End User:
Cost tier differentiation separates integrated processors with captive milk supplies from import-dependent traders serving formulation niches.
- Sports Nutrition:Branded gym chains and direct-to-consumer platforms in Abu Dhabi and Jeddah contract volume for whey protein isolate, consolidating vendor bases toward ISO 17025-accredited sources with full traceability documentation.
- Nutraceutical Companies:Gulf-based formulators of medical nutrition and weight management products source hydrolyzed grades for allergen-sensitive positioning, absorbing batch-level testing costs for SFDA compliance.
- Dairy Manufacturers:Regional processors fortify fluid milk and fermented products with milk protein isolate to meet South African Department of Health protein fortification mandates.
- Food & Beverage Industry:Bakery and beverage formulators in Egypt and Morocco face margin compression from feed cost volatility when sourcing whey concentrates for protein enrichment.
Sports Nutrition commands the steepest expansion trajectory; Dairy Manufacturers anchor current volume absorption.
Application:
Application maturity correlates with regulatory qualification burden, where pediatric and medical claims demand the most intensive certification infrastructure.
- Infant Formula:Pediatric nutrition manufacturers prioritize hydrolyzed whey with documented halal supply chain integrity, facing extended ISO 17025 accreditation timelines for protein assay validation.
- Functional Foods:South African retail channels reward milk protein isolate positioning in high-protein dairy alternatives, with clean-label claims supporting premium shelf placement.
- Protein Supplements:Sports nutrition powders and ready-to-drink formats dominate UAE and Saudi gym channel procurement, with direct contracting displacing traditional distributor markups.
- Bakery Products:Egyptian and Moroccan processors incorporate whey concentrates for protein fortification, constrained by alfalfa and soybean meal price volatility affecting domestic dairy output.
Protein Supplements handle current volume leadership; Functional Foods is gaining share fastest.
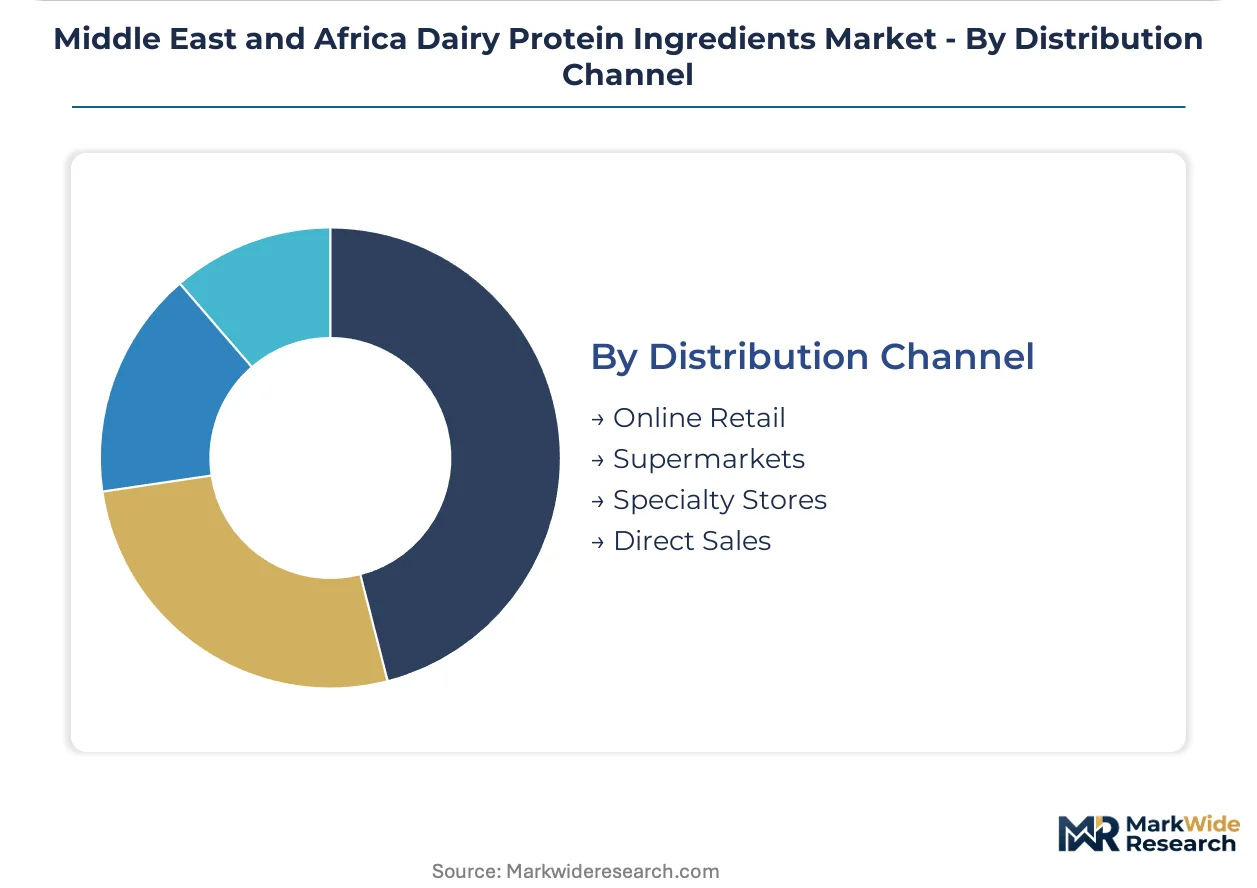
Distribution Channel:
Channel concentration reflects procurement pattern shifts, with large-scale buyers shortening traditional trader-mediated supply hierarchies.
- Direct Sales:Gulf nutraceutical brands and New Zealand cooperative processors establish volume contracts bypassing regional distributors, concentrating in whey protein isolate categories where documentation supports premium positioning.
- Online Retail:E-commerce platforms in Dubai and Riyadh aggregate gym chain and consumer demand for sports nutrition products, filtering toward accredited suppliers with SFDA-compliant labeling.
- Specialty Stores:Nutrition-focused retailers serve medical nutrition and pediatric formula segments requiring consultation-heavy purchasing.
- Supermarkets:Mass retail channels distribute fortified dairy and bakery applications with lower certification thresholds.
Direct Sales anchors procurement volume for premium tiers; Online Retail shows the steepest channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances define regional dynamics, with Gulf states sourcing whey streams from New Zealand and Europe while North African processors depend on regional casein flows. South Africa's functional food manufacturing anchors sub-Saharan absorption. Regulatory divergence between SFDA enforcement and South African fortification mandates fragments compliance pathways.
Saudi Arabia
Gym chain proliferation in Riyadh and Jeddah drives whey protein concentrate absorption through e-commerce and direct procurement channels. SFDA protein labeling standards enforce batch-level verification, filtering non-compliant imports and consolidating vendor bases toward accredited suppliers. Almarai Company's captive milk supplies across the Kingdom enable backward integration into milk protein isolate production.
United Arab Emirates
Dubai and Abu Dhabi host direct contracting between nutraceutical brands and New Zealand cooperative processors, displacing traditional trader markups. Emirates Authority for Standardization and Metrology halal certification protocols open Gulf Cooperation Council procurement channels for compliant ingredient manufacturers. The emirates' logistics infrastructure positions the country as a re-export hub for regional sports nutrition distribution.
South Africa
The Department of Health protein fortification mandates accelerate industrial demand from dairy manufacturers and functional food formulators. Cape Town and Johannesburg corridors concentrate clean-label milk protein isolate positioning for high-protein dairy alternatives and medical nutrition segments. ISO 17025 accreditation requirements extend product qualification cycles for new market entrants.
Qatar
State-backed dairy infrastructure supports Baladna Food Industries' scaled casein protein output for regional export to North African infant formula manufacturers. The country's strategic food security investments reduce import dependency for domestic dairy protein supply. Doha-based procurement offices prioritize halal supply chain integrity documentation for pediatric nutrition applications.
Egypt
Alfalfa and soybean meal price volatility compresses margin pools for domestic dairy processors lacking long-term forage contracts. Cairo and Alexandria bakery and beverage formulators incorporate whey concentrates for protein enrichment under constrained feed cost conditions. The country's central dairy regulator enforces quality standards that parallel Gulf technical barriers.
Middle East and Africa Dairy Protein Ingredients Market Competitive Landscape
Concentration sits with integrated dairy processors possessing captive milk supplies, while import-dependent traders occupy formulation niches requiring flexible sourcing. Saudi and Qatari processors leverage backward integration into upstream milk production, securing margin pools that trader-mediated channels cannot replicate. Two strategic archetypes dominate: cooperative-backed international suppliers with traceable New Zealand whey streams, and state-supported regional processors with scaled domestic infrastructure. Competitive moves center on direct procurement relationship-building and ISO 17025 accreditation investments that filter market access.
Within the cooperative-backed supplier tier, Fonterra Co-operative Group exemplifies the New Zealand-sourced whey stream archetype, anchoring supply security for Gulf nutraceutical customers through traceability documentation. Almarai Company and Baladna Food Industries represent the integrated regional processor archetype, with the former sustaining captive milk supplies across Saudi Arabia and the latter leveraging Qatar's state-backed dairy infrastructure for casein protein export positioning. Kerry Group and Glanbia plc occupy positions within the ingredient solutions segment, serving formulation customers across multiple application tiers.
| Leading Market Players |
|---|
| Almarai Company |
| Fonterra Co-operative Group |
| Lactalis Ingredients |
| Arla Foods Ingredients Group P/S |
| Kerry Group |
| Glanbia plc |
| Clover Industries Limited |
| Saudi Dairy & Foodstuff Company (SADAFCO) |
| Baladna Food Industries |
| Others |
Supply & Pricing Matrix
Baladna Food Industries' state-backed scale economies in Qatar compress unit costs for casein protein output while simultaneously anchoring regional price floors that smaller Egyptian processors cannot match. This capacity-utilization advantage concentrates margin pools with integrated Gulf producers and forces import-dependent traders into certification-differentiated premium tiers where documentation costs inflate delivered prices.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Middle East and Africa Dairy Protein Ingredients Market. Price differentiation separates ISO 17025-accredited batches from standard-grade imports, with halal certification from Emirates Authority for Standardization and Metrology commanding additional premiums. Cost compression in whey protein concentrate tiers is intensifying because New Zealand-sourced feedstock volatility transmits directly to Gulf nutraceutical formulators. Dairy manufacturers in South Africa exhibit highest price sensitivity due to Department of Health fortification mandates constraining formulation budgets, while infant formula manufacturers absorb premium pricing for hydrolyzed grades with reduced allergen documentation.
Supply Chain Analysis
New Zealand and the European Union anchor whey stream production for Gulf nutraceutical customers, while Qatar and Saudi Arabia sustain regional casein and milk protein isolate output through state-backed dairy infrastructure. Raw material dependencies center on alfalfa and soybean meal for North African processor feed rations, ocean freight capacity for transoceanic whey concentrate movements, and chromatography resins for membrane filtration polishing stages. Single-source vulnerability concentrates in New Zealand cooperative processor relationships that Gulf gym chains and e-commerce platforms draw from for traceability documentation. Distribution runs through direct procurement contracts displacing traditional trader-mediated channels, with Dubai logistics hubs enabling re-export to Saudi Arabia and Qatar.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Dairy Protein Ingredients Market is recovering from feed cost volatility compression, with alfalfa and soybean meal price stabilization enabling margin restoration for Egyptian and Moroccan processors. This cyclical recovery is anchored in forage contract normalization and freight rate moderation across ocean lanes serving Gulf import demand.
For Market Incumbents: Fortify backward integration into captive milk supplies across Saudi Arabia and Qatar to defend against pea and rice protein isolate substitution threats in beverage applications. Almarai Company and Baladna Food Industries should expand ISO 17025 accreditation investments to filter competitor access to SFDA-compliant procurement channels. Channel control through direct contracting with Dubai gym chains and e-commerce platforms protects premium positioning against trader-mediated price erosion.
For New Entrants and Emerging Players: Emirates Authority for Standardization and Metrology halal certification fast-track opens Gulf Cooperation Council procurement channels for compliant ingredient manufacturers lacking established presence. The most penetrable white-space sits in enzymatic hydrolysis capabilities for allergen-reduced pediatric applications, where extended accreditation timelines currently constrain incumbent capacity. A go-to-market angle targeting South African functional food manufacturers with clean-label milk protein isolate positioning bypasses saturated sports nutrition competition in UAE and Saudi Arabia.
For Investors and Strategic Acquirers: Mid-scale Egyptian processors with membrane filtration expertise but constrained working capital represent acquisition targets where feed cost volatility has compressed valuations. Long-term viability across the analysis window hinges on Gulf dairy self-sufficiency targets redirecting import dependency patterns and state-backed infrastructure investments in Qatar and Saudi Arabia. The signal to watch is SFDA enforcement tightening on protein content verification, which would accelerate vendor base consolidation toward accredited suppliers and strand non-compliant trader inventories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Milk Supply | Almarai Company's Saudi Arabia infrastructure secures margin pools traders cannot replicate. |
| ISO 17025 Accreditation Investment | Batch-level testing capability opens SFDA-compliant procurement channels in Riyadh and Jeddah. |
| Enzymatic Hydrolysis Capability Buildout | Membrane filtration convergence enables premium allergen-reduced tiers for pediatric formula manufacturers. |
| Direct Procurement Relationship Establishment | Gulf nutraceutical brands contracting New Zealand processors displace regional distributor markups. |
| Halal Supply Chain Integrity Documentation | Emirates Authority for Standardization and Metrology protocols unlock Gulf Cooperation Council market access. |
Research Methodology
Desk research of customs and trade databases, dairy processor SEC filings, and Gulf regulatory gazettes preceded structured interviews with ingredient procurement managers at Saudi nutraceutical formulators, membrane filtration technology suppliers, and South African functional food R&D directors. Primary fieldwork with SFDA compliance officers and Emirates Authority for Standardization and Metrology certification auditors combined with secondary validation against ISO 17025 laboratory accreditation records. Bottom-up volume modeling across whey protein concentrate, hydrolyzed whey, casein, and milk protein isolate tiers triangulated with top-down macroeconomic absorption estimates.
Variance decomposition across product type, end user, application, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling incorporating sports nutrition expansion rates, infant formula fortification mandates, and functional food clean-label adoption patterns. Industry-specific forecast inputs included alfalfa and soybean meal price volatility indices, ocean freight rate movements, and halal certification timeline distributions.
Underlying assumptions cover feed cost stabilization, SFDA enforcement continuity, and Gulf dairy self-sufficiency target progression, with deviation risk concentrated in New Zealand whey stream supply disruptions and pea protein isolate functional parity advances. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Phytosterols Market
Ingredients
South America Malt Ingredient Market
Ingredients
Vegan Ingredients Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
China Corn Glucose Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
Malted Barley Flour Market
Ingredients
Egg Membrane Powder Market
Ingredients
Banana Flour Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
Food Grade L-Arabinose Market
Ingredients
North America Prebiotic Ingredients Market
Ingredients
Blackcurrant Concentrate Market
Ingredients
Textured Milk Protein Market
Ingredients
Cold Pressed Oil Market