
 Agar Market | 2026-2036
Agar Market Size, Share, and Industry Trends Forecast 2026-2036
Agar Market Analysis
Skilled seaweed harvester availability is unwinding as coastal labor migrates toward aquaculture and tourism, tightening raw material flows for processors. PT Agarindo Bogatama leverages its Indonesian harvesting base to sustain consistent feedstock access. CP Kelco anchors North American supply through controlled distribution networks. Hispanagar specializes in high-purity laboratory and pharmaceutical grades, competing on certification depth rather than volume scale.
Agar denotes a heterogeneous polysaccharide complex extracted primarily from red algae of the Rhodophyta phylum, composed of alternating β-1,3-linked D-galactose and α-1,4-linked 3,6-anhydro-L-galactose units, with gelation temperatures typically between 32°C and 45°C depending on source species and extraction method. Its primary commercial purpose centers on thermoreversible gel formation for food matrices, microbial culture media, and biopharmaceutical encapsulation. Food-grade agar dominates volume flows through bakery, confectionery, and dairy alternatives, while laboratory-grade commands premium pricing through stringent endotoxin and clarity specifications. Powder form leads distribution efficiency, though gel and capsule formats are expanding in cosmetics and nutraceutical applications.
FDA GRAS status and EFSA food additive codes shape formulation eligibility and import clearance for agar derivatives across major consuming regions. ISO 9001 and HACCP certifications function as baseline qualifiers for microbiology-grade supply contracts to diagnostic and research institutions. Stakeholders must monitor evolving EU Green Deal sourcing requirements and marine sustainability certifications, as traceability standards tighten for wild-harvested seaweed inputs.
Market Dynamics
Seaweed harvester labor migration toward aquaculture and tourism is tightening raw material flows, forcing processors to secure captive supply chains or absorb higher procurement costs.
Growth Catalysts
- EU Green Deal traceability mandates:Marine sustainability certifications are creating preferential market access for compliant Indonesian and Philippine suppliers, accelerating consolidation around certified harvesting cooperatives.
- Plant-based dairy alternatives:Formulators in bakery and confectionery segments are substituting animal-derived gelling agents with food-grade agar to meet clean-label positioning requirements.
- Biopharmaceutical encapsulation:Thermoreversible gel properties are enabling novel drug delivery matrices, with endotoxin-controlled grades penetrating preclinical research workflows.
Market Restraints
- Wild-harvest supply concentration:Indonesian and Philippine coastal regions account for the majority of Gracilaria and Gelidium biomass, exposing processors to climate-driven harvest volatility and export licensing friction.
- Carrageenan substitution pressure:Cost-sensitive food manufacturers in emerging markets are pivoting toward lower-priced hydrocolloids for standard gelling applications.
- Extraction energy intensity:Conventional alkali pre-treatment and hot-water extraction protocols consume substantial thermal energy, compressing margins against electromechanical alternatives.
Strategic Opportunities
- Cell-cultured meat scaffolding:High-purity agarose derivatives are penetrating cellular agriculture R&D pipelines as biocompatible substrate materials for myoblast proliferation.
- Indian nutraceutical expansion:FSSAI food additive approvals for agar in capsule and tablet formulations are opening distribution channels through ayurvedic and dietary supplement manufacturers.
- ISO 9001-HACCP bundled certification:Integrated quality management systems are reducing audit burden for laboratory-grade suppliers targeting diagnostic institution procurement frameworks.
Industry Challenges
- Skilled harvester attrition:Coastal labor pools in Sulawesi and Mindanao are shrinking as younger workers migrate to urban service sectors, forcing processors to mechanize collection or fund retention premiums.
- Endotoxin certification timelines:LAL testing protocols and USP-NF documentation requirements for pharmaceutical-grade supply contracts extend qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agar Market |
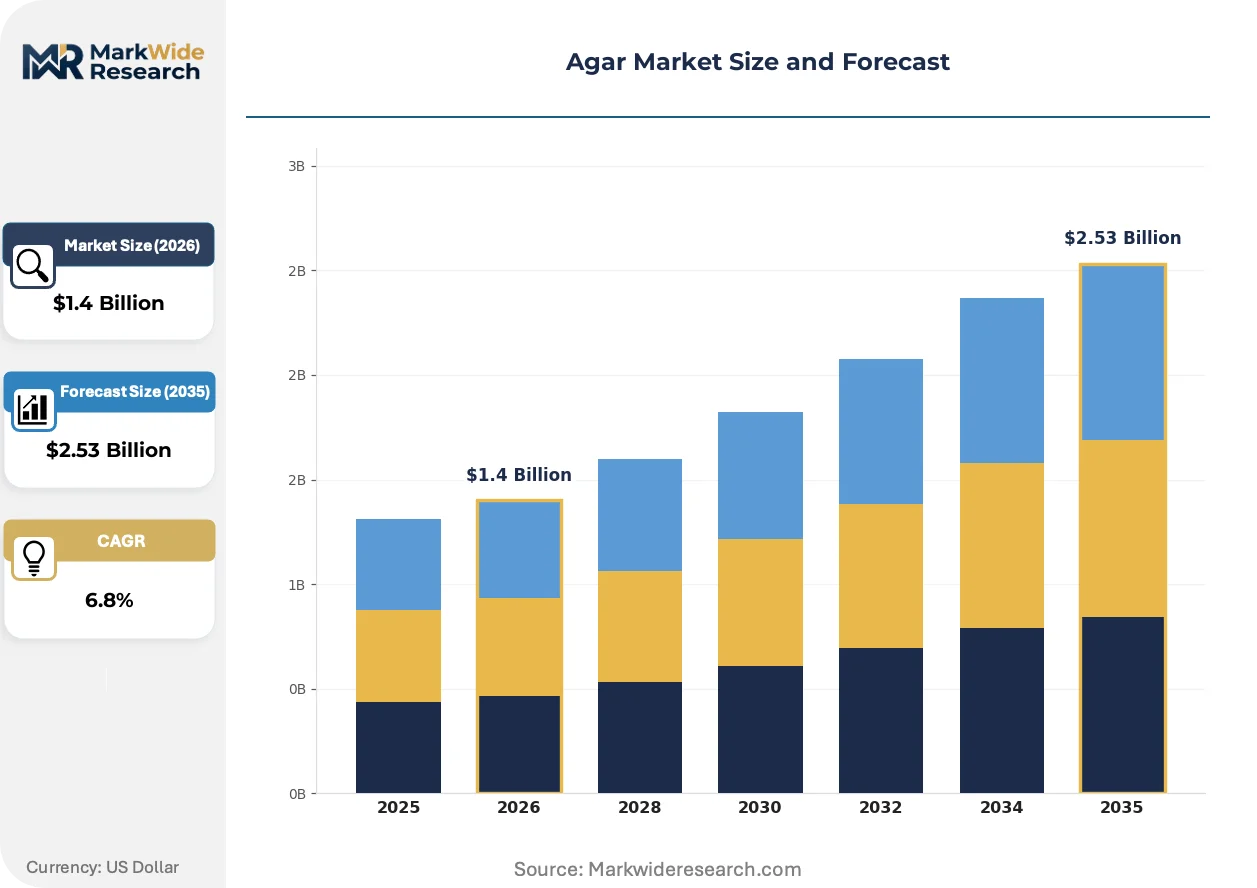
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Laboratory Grade, Pharmaceutical Grade, Industrial Grade Application: Food Industry, Microbiology, Biotechnology, Cosmetics Form: Powder, Sheets, Capsules, Gels Distribution Channel: Online Retailers, Distributors, Wholesalers, Supermarkets |
| Companies Covered | Agarmex, PT Agarindo Bogatama, CP Kelco, Meron Group, Marine Science Co., Ltd, HiMedia Laboratories, Industrias Roko, Qingdao Global Seaweed Group, Hispanagar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agar Market Emerging Trajectories
Process intensification and purity-grade differentiation are reshaping competitive positioning, with extraction technology and regulatory compliance emerging as primary vectors of value capture.
Enzyme-assisted extraction protocols are replacing conventional alkali pre-treatment in pilot-scale facilities, reducing thermal energy consumption and preserving native gel strength in sensitive applications. Specialty chemical producers in Japan and South Korea are licensing these bioprocesses to secure pharmaceutical-grade supply contracts. The technology is miniaturizing extraction footprints, enabling distributed processing nodes closer to harvest sites.
EFSA food additive re-evaluation cycles and EU Green Deal marine sourcing requirements are tightening documentation standards for wild-harvested seaweed inputs. Processors must now maintain chain-of-custody records from harvest coordinates through final extraction batches to maintain formulation eligibility. European laboratory-grade distributors are responding by dual-sourcing from certified Indonesian cooperatives and Chilean aquaculture operations.
Diagnostic institutions and contract research organizations are consolidating vendor lists around suppliers offering bundled ISO 9001, HACCP, and USP-NF documentation, compressing qualification overhead. This certification-driven preference shift favors mid-scale processors with dedicated quality infrastructure over commodity traders. The pattern is most visible in German and Swiss pharmaceutical corridors, where procurement frameworks now mandate endotoxin certificates with every lot delivery.
Agar Market Segmentation
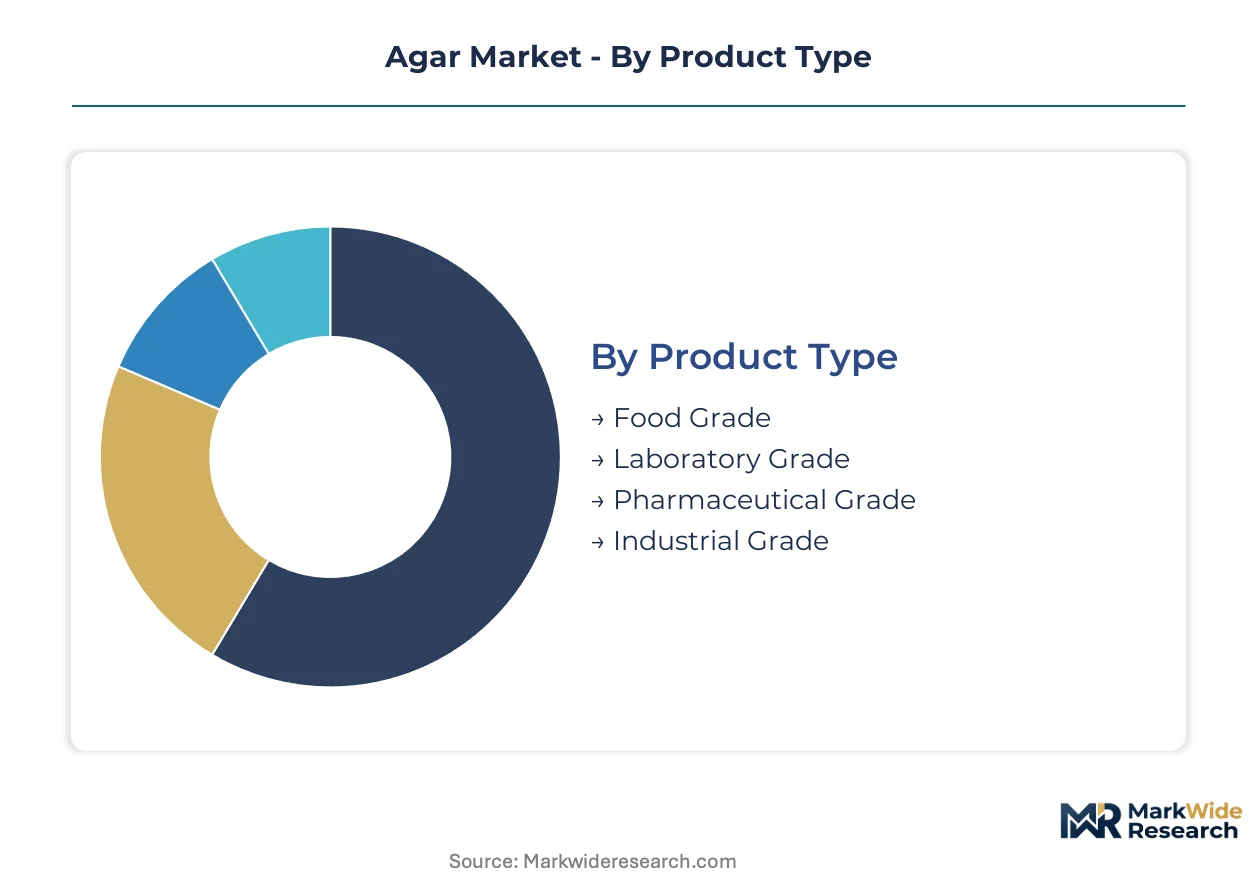
Agar's heterogeneous polysaccharide structure creates distinct value pools across purity grades and end-use specifications. Segmentation reveals how thermoreversible gelation properties command premium pricing in pharmaceutical and laboratory applications while food-grade volumes anchor procurement scale.
Product Type:
Margin pools concentrate in certification-intensive grades where endotoxin control and USP-NF documentation create defensible pricing power.
- Food Grade:Standardized gelling strength between 600-1100 g/cm² serves bakery, confectionery, and plant-based dairy formulations. Demand concentrates in Indonesia and the Philippines where Gracilaria harvesting cooperatives supply raw biomass to regional processors.
- Laboratory Grade:Low-endotoxin specifications below 0.5 EU/g with optical clarity requirements for microbial culture media. German and Swiss diagnostic institutions are consolidating procurement around bundled ISO 9001-HACCP certification, compressing vendor lists.
- Pharmaceutical Grade:USP-NF compliant agarose derivatives for biopharmaceutical encapsulation and drug delivery matrices.
- Industrial Grade:Lower-purity extracts for textile sizing and adhesive applications with minimal regulatory documentation.
The dominant share belongs to Food Grade, while Laboratory Grade is closing the gap fastest through diagnostic institution vendor consolidation.
Application:
Volume concentration tracks regulatory approval pathways, with food additive codes and GRAS status determining formulation eligibility across geographies.
- Food Industry:Thermoreversible gel formation in confectionery, dairy alternatives, and bakery applications. EFSA food additive re-evaluations and clean-label positioning in European and North American markets are accelerating substitution from animal-derived gelling agents.
- Microbiology:Solid culture media for diagnostic and research workflows requiring stringent endotoxin and clarity specifications. Procurement frameworks in German pharmaceutical corridors now mandate certificates with every lot delivery.
- Biotechnology:Agarose substrates for electrophoresis and cell-cultured meat scaffolding in cellular agriculture R&D pipelines.
- Cosmetics:Gelling agent for masks, creams, and encapsulation formats in premium skincare formulations.
Food Industry maintains the largest volume position, though Biotechnology applications are expanding most quickly through cellular agriculture investment.
Form:
Distribution efficiency favors powder logistics, while specialized formats capture value in nutraceutical and cosmetic channels.
- Powder:Dominant distribution format with standardized mesh sizes for industrial-scale food processing and laboratory reconstitution. Indonesian processors are optimizing spray-drying protocols to preserve native gel strength for export markets.
- Sheets:Traditional format for East Asian confectionery applications and artisanal food production.
- Capsules:Pre-measured dosing units for dietary supplements and ayurvedic formulations in Indian nutraceutical channels following FSSAI additive approvals.
- Gels:Ready-to-use matrices for cosmetic applications and clinical culture media preparation.
Powder commands the prevailing share, yet Capsules are gaining share fastest through Indian dietary supplement distribution expansion.
Distribution Channel:
Channel selection reflects customer scale and documentation requirements, with large processors favoring direct distributor relationships over fragmented retail.
- Distributors:Primary channel for laboratory and pharmaceutical grades requiring chain-of-custody documentation and technical support. European distributors are dual-sourcing from certified Indonesian cooperatives and Chilean aquaculture to meet EU Green Deal traceability mandates.
- Online Retailers:Growing channel for small-scale research institutions and artisanal food producers seeking transparent pricing and rapid fulfillment.
- Wholesalers:Bulk volume aggregation for food manufacturers in emerging markets with cost-sensitive formulation requirements.
- Supermarkets:Direct consumer access for specialty food-grade agar in premium and ethnic product lines.
Distributors hold the dominant position, while Online Retailers are climbing the fastest through procurement decentralization in research institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's GRAS designation anchors North American formulation eligibility while EFSA's additive codes govern European market access. Indonesian and Philippine coastal regions supply the majority of raw Gracilaria and Gelidium biomass. Processing infrastructure concentrates near harvest sites to minimize feedstock degradation.
Indonesia
Gracilaria harvesting cooperatives in Sulawesi and South Sulawesi provinces supply regional processors with raw biomass. The national food and drug regulator maintains export licensing frameworks for hydrocolloid derivatives. PT Agarindo Bogatama leverages captive coastal harvesting networks to sustain consistent feedstock flows amid tightening labor availability.
United States
FDA GRAS status enables clean-label positioning in plant-based dairy and confectionery formulations. Diagnostic institutions and contract research organizations consolidate procurement around bundled ISO 9001-HACCP documentation. CP Kelco anchors North American supply through controlled distribution networks serving food and laboratory segments.
Germany
EFSA food additive re-evaluations and EU Green Deal traceability mandates tighten documentation standards for wild-harvested seaweed inputs. Pharmaceutical corridors in Baden-Württemberg and Bavaria mandate endotoxin certificates with every lot delivery. Laboratory-grade distributors dual-source from certified Indonesian cooperatives and Chilean aquaculture operations.
Japan
METI supports enzyme-assisted extraction technology licensing to specialty chemical producers. Traditional sheet-format agar maintains demand in artisanal confectionery applications. Pilot-scale facilities in coastal prefectures are replacing conventional alkali pre-treatment with bioprocesses to reduce thermal energy consumption.
India
FSSAI food additive approvals for agar in capsule and tablet formulations open distribution through ayurvedic and dietary supplement manufacturers. Capsule-format agar gains share fastest through nutraceutical channels. Maharashtra and Gujarat-based formulators integrate agar into clean-label positioning for domestic and export markets.
Agar Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with Indonesian harvester-processors and North American distributors occupying distinct vertical positions. The structure fragments across certification intensity rather than scale alone. Three archetypes dominate: captive-supply harvester-processors, certification-intensive laboratory-grade specialists, and distribution-anchored regional suppliers. Competitive moves concentrate on backward integration into harvesting cooperatives and bundled quality certification to reduce procurement audit burden.
Within the integrated harvester-processor tier, PT Agarindo Bogatama exemplifies captive-supply positioning through Indonesian coastal networks. CP Kelco occupies the distribution-anchored archetype in North American channels. Hispanagar represents the certification-intensive specialist model, competing on documentation depth for pharmaceutical and laboratory segments rather than volume scale.
| Leading Market Players |
|---|
| Agarmex |
| PT Agarindo Bogatama |
| CP Kelco |
| Meron Group |
| Marine Science Co., Ltd |
| HiMedia Laboratories |
| Industrias Roko |
| Qingdao Global Seaweed Group |
| Hispanagar |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Indonesian extraction facilities shapes both supply concentration and price floors for food-grade agar, with coastal processing clusters absorbing harvest volatility through captive cooperative networks while laboratory-grade specialists defend premiums via endotoxin certification depth.
Pricing Analysis
Geographic price spreads between Indonesian food-grade output and European pharmaceutical-grade supply exceed threefold, with Sulawesi-sourced Gracilaria extracts trading at commodity benchmarks while German laboratory distributors command premiums for USP-NF bundled documentation. Pricing stratifies across pharmaceutical, laboratory, food, and industrial tiers, with certification level and gel strength specifications as primary differentiation drivers. Cost compression in food-grade segments is intensifying because carrageenan substitution pressure from cost-sensitive Asian manufacturers erodes volume premiums. Emerging market food manufacturers exhibit highest price sensitivity, while German diagnostic institutions demonstrate lowest sensitivity due to mandated endotoxin compliance.
Supply Chain Analysis
Sulawesi Strait maritime transit underwrites raw biomass flows from Indonesian harvesting cooperatives to regional extraction facilities, creating logistical chokepoint exposure during monsoon disruptions. Supply concentrates in Indonesia, the Philippines, and Chile, with Gracilaria and Gelidium seaweed species as dominant raw material inputs alongside alkali pre-treatment chemicals and thermal energy. Single-source vulnerability runs through Indonesian coastal labor pools, where harvester migration toward aquaculture and tourism threatens feedstock continuity. Distribution runs through distributor networks for laboratory and pharmaceutical grades, direct processor relationships for food manufacturers, and online channels for small-scale research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-cultured meat scaffolding applications represent a high-growth disruption vector, with enzyme-assisted extraction technology and EU Green Deal traceability mandates creating dual inflection points for certification-intensive suppliers.
For Market Incumbents: Secure captive harvesting cooperatives in Sulawesi and Mindanao through retention premiums or mechanization investment, defending against skilled labor attrition that threatens feedstock continuity. Deepen backward integration into certified aquaculture operations to meet EU Green Deal chain-of-custody requirements and reduce wild-harvest climate exposure. For New Entrants and Emerging Players: Diagnostic institution procurement consolidation in German pharmaceutical corridors presents a service-layer gap where mid-scale processors can displace commodity traders through bundled ISO 9001-HACCP-USP-NF documentation. Target Indian nutraceutical capsule distribution through FSSAI-compliant formulation partnerships, leveraging ayurvedic manufacturer channel access as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzyme-assisted extraction specialists with pilot-scale licensing revenue from Japanese and South Korean specialty chemical producers. Five-to-ten year viability hinges on pharmaceutical-grade margin sustainability against electromechanical hydrocolloid alternatives. Acquisition target archetype: mid-scale Indonesian processors with dedicated quality infrastructure and existing EU marine sustainability certification. The signal to watch is endotoxin testing protocol standardization timelines extending qualification cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Harvesting Cooperatives | PT Agarindo Bogatama's captive Sulawesi networks demonstrate feedstock security against labor migration. |
| Enzyme-Assisted Extraction Technology Licensing | METI-supported Japanese bioprocesses reduce thermal energy consumption while preserving native gel strength. |
| EU Green Deal Marine Sustainability Certification | European distributors now dual-source from certified Indonesian cooperatives and Chilean aquaculture operations. |
| Indian Nutraceutical Capsule Format Expansion | FSSAI approvals enable distribution through Maharashtra and Gujarat ayurvedic manufacturers. |
| Bundled ISO 9001-HACCP-USP-NF Quality Certification | German diagnostic institutions consolidate procurement around integrated documentation reducing audit burden. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with Indonesian harvesting cooperative managers, Philippine extraction facility operators, German laboratory procurement directors, Indian nutraceutical formulators, and Japanese specialty chemical licensing executives. Secondary validation drew from EFSA additive re-evaluation documentation, FDA GRAS designation records, FSSAI approval filings, EU Green Deal marine sourcing requirements, and customs trade data for hydrocolloid derivatives. Bottom-up volume estimates from grade-specific consumption patterns were triangulated against top-down market sizing from processor capacity assessments.
Across the analysis window, the forecasting framework modeled segmentation dimensions including purity grade tier, end-use application, physical form factor, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for technology adoption curves and regulatory approval timelines. Industry-specific inputs incorporated enzyme-assisted extraction scale-up trajectories, cell-cultured meat R&D investment flows, and endotoxin certification penetration rates in diagnostic procurement frameworks.
Underlying assumptions cover sustained EU Green Deal traceability enforcement, stable FSSAI regulatory pathways for Indian nutraceutical applications, and gradual enzyme-assisted extraction cost parity attainment, with deviation risk concentrated in climate-driven harvest volatility and carrageenan substitution acceleration in cost-sensitive emerging markets. Practitioners should keep alternative scenarios live as marine sustainability certification standards and cellular agriculture commercialization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
Phytogenic Market
Ingredients
United States Wheat Protein Market
Ingredients
Apple Extract Market
Ingredients
Corn-Based Ingredients Market
Ingredients
Asia Pacific Vegetable Oil Market
Ingredients
Food Grade L-Arabinose Market
Ingredients
Europe Potato Protein Market
Ingredients
Potato Fiber Market
Ingredients
Marine Ingredients Market
Ingredients
Cocoa Powder Market
Ingredients
Chewing Gum Base Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Cocoa Solids Market
Ingredients
Protein Ingredients Market