
 Camellia Oil Market | 2026-2036
Camellia Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Camellia Oil Market Analysis
Hunan province's crush capacity is hardening as the dominant supply base for cold-pressed camellia oil. Hunan Shanrun Camellia Oil Technology & Development Co., LTD anchors downstream distribution through integrated refining assets. Wilmar International Limited leverages its oilseed trading infrastructure to secure raw material flows across Asia. JiangXi YouNiBao Agricultural Science and Technology Co., LTD specializes in organic certification tiers for export-bound cosmetic grades.
Camellia oil is a triglyceride-rich lipid extracted from Camellia oleifera seeds, typically cold-pressed at temperatures below 60 degrees Celsius to preserve oleic acid concentrations exceeding 80 percent. The oil serves cosmetic formulators seeking oxidative stability and food manufacturers requiring high smoke-point cooking mediums. Cold-pressed product types command premium positioning in skincare and haircare applications where unrefined nutrient profiles justify higher shelf prices. Refined grades dominate culinary volumes through supermarket and online retail channels, though organic certification segments extract superior margins from specialty store and pharmacy distribution.
China's SAMR enforces GB standards for edible oil labeling and safety thresholds that constrain small-scale producers without laboratory verification capacity. The EU REACH framework and ECHA substance evaluations shape export eligibility for cosmetic-grade camellia oil entering European formulation supply chains. Stakeholders must monitor regulatory divergence between food-grade and cosmetic-grade specifications as dual-use positioning becomes more common across manufacturer end user segments.
Market Dynamics
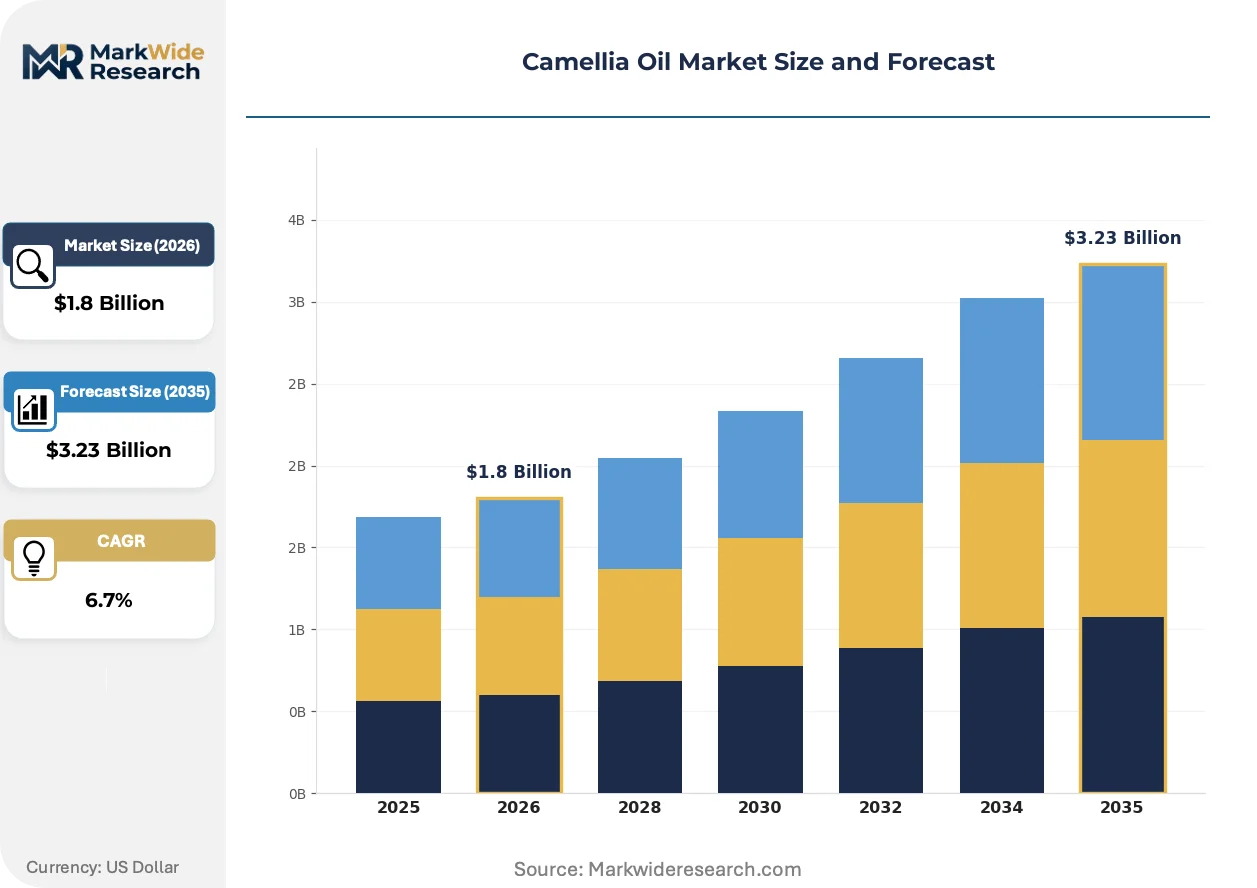
Hunan province's processing clusters now dictate global cold-pressed camellia oil availability, with crush capacity expansion outpacing seed cultivation in neighboring regions. SAMR enforcement of GB standards for edible oil labeling is compressing small-producer participation and consolidating distribution around integrated refiners.
Growth Catalysts
- EU REACH cosmetic-grade compliance:ECHA substance evaluations create export eligibility pathways for cold-pressed grades entering European formulation supply chains. Cosmetic manufacturers in Germany and France now specify REACH-certified oleic acid profiles above 80 percent.
- South Korean skincare brand premiumization:K-beauty formulators are absorbing higher input costs for unrefined nutrient profiles in anti-aging serums and hair repair masks. Seoul-based distributors maintain dedicated procurement desks in Changsha.
- Supercritical CO2 extraction adoption:This solvent-free processing technology preserves heat-sensitive bioactives while eliminating hexane residue concerns. Pilot installations in Jiangxi province are validating commercial scalability.
Market Restraints
- Seed supply concentration in subtropical China:Camellia oleifera cultivation remains geographically locked to Hunan, Jiangxi, and Guangxi provinces. Climate vulnerability and aging orchard stock create harvest volatility that propagates through pricing.
- Hexane-refined palm olein substitution:Industrial food manufacturers in Southeast Asia default to lower-cost high-oleic alternatives for frying applications. Camellia oil's smoke point advantage fails to overcome three-to-one cost differentials at volume.
- Laboratory verification capacity scarcity:GB standards for heavy metal and aflatoxin testing require capital equipment beyond township-level processors. SAMR inspection frequency is accelerating consolidation.
Strategic Opportunities
- Organic certification tier expansion:EU 2018/848 and USDA NOP standards enable 40-60 percent price premiums in pharmacy and specialty retail channels. Jiangxi producers are securing multi-year conversion contracts with French distributors.
- Direct-to-consumer subscription models:Cold-pressed cosmetic grades bypass traditional wholesale markups through brand-owned digital channels. South Korean and Japanese consumers demonstrate 18-month retention rates for facial oil subscriptions.
- Dual-use food-cosmetic positioning:SAMR and MFDS harmonization discussions could streamline cross-border labeling for ingestible skincare formulations. Early movers in Seoul and Shanghai are testing regulatory arbitrage strategies.
Industry Challenges
- Cold-press technician skill scarcity:Sub-60 degree Celsius extraction requires experienced operators to manage screw press torque and moisture content. Hunan's vocational pipeline produces fewer than 200 certified technicians annually.
- Organic certification timeline compression:Three-year conversion periods for EU 2018/848 compliance lock working capital in non-revenue orchards. Jiangxi cooperatives face liquidity strain during transition windows.
- Refining-cosmetic grade batch segregation:Shared crush infrastructure creates cross-contamination risks that void organic claims. Dedicated line investments exceed mid-producer balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camellia Oil Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold-Pressed, Refined, Organic, Cosmetic Application: Skincare, Haircare, Culinary, Aromatherapy End User: Beauty Salons, Food Industry, Household, Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Hunan Shanrun Camellia Oil Technology & Development Co., LTD, Waltt Products Co.,Ltd, Hunan Jinhao Camellia Oil Corp., Ltd, Laozhiqing, Shanrun, Wilmar International Limited, JiangXi YouNiBao Agricultural Science and Technology Co., LTD, Runxinoil, Hunan Guitaitai Camellia Oil Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camellia Oil Market Emerging Trajectories
Processing technology and procurement models are restructuring how cold-pressed grades reach end-users. Three developments are compressing traditional channel structures while opening premium positioning pathways.
Supercritical CO2 extraction systems are expanding into mid-scale camellia oil production, replacing hexane refining for cosmetic-grade output. German and Italian equipment suppliers have installed pilot units in Changsha and Nanchang processing clusters. This technology enables oleic acid retention above 85 percent while eliminating solvent residue testing burdens under REACH.
China's SAMR is tightening GB 2716 edible oil labeling enforcement, requiring origin disclosure and pressing method specification on retail packaging. Small processors without in-house testing laboratories face delisting from e-commerce platforms. Refined culinary grades are absorbing compliance costs through supermarket channel consolidation, while cold-pressed cosmetic grades bypass retail labeling through B2B formulation supply chains.
Ingredient procurement by South Korean and Japanese cosmetic houses is rotating toward long-term offtake contracts with named orchards. Seoul-based formulators now specify harvest batch and pressing date for premium serum lines. This traceability requirement is displacing commodity spot purchasing in the high-oleic acid segment, compressing trader margins while securing revenue visibility for integrated Hunan producers.
Camellia Oil Market Segmentation
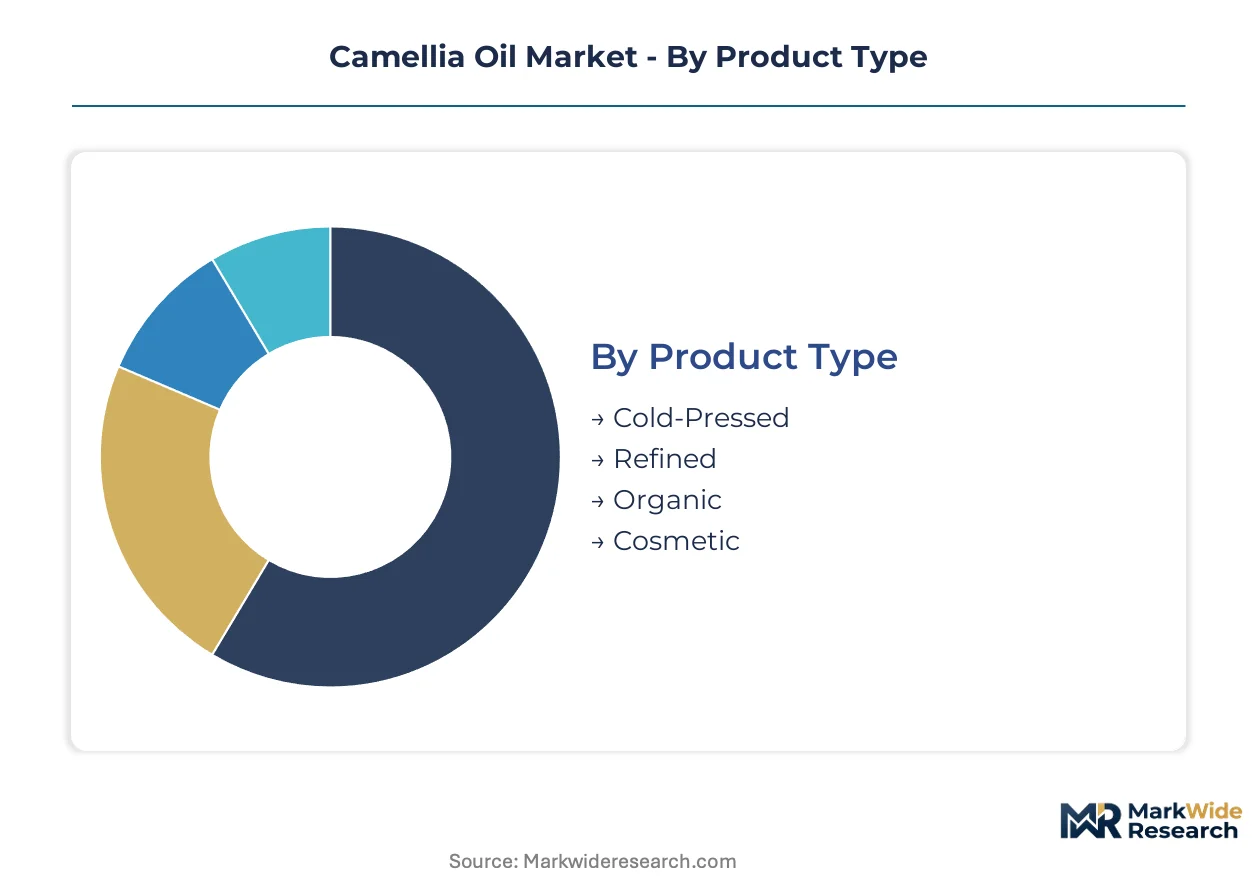
Camellia oil segmentation reflects divergent certification burdens across food and cosmetic regulatory regimes. Product grades carry distinct approval requirements that reshape manufacturing infrastructure and channel economics.
Product Type:
Cold-pressed grades require REACH cosmetic-grade compliance for EU export eligibility, while refined culinary variants face SAMR GB 2716 labeling enforcement. Organic certification demands EU 2018/848 or USDA NOP validation across three-year conversion timelines.
- Cold-Pressed:Sub-60 degree Celsius extraction preserves oleic acid concentrations above 80 percent. South Korean skincare formulators in Seoul specify harvest batch traceability for anti-aging serum lines, absorbing premium input costs for unrefined nutrient profiles.
- Refined:Hexane or supercritical CO2 processing eliminates heat-sensitive bioactives for high smoke-point culinary applications. Southeast Asian food manufacturers default to palm olein substitution despite camellia's thermal stability advantage, constrained by three-to-one cost differentials at volume.
- Organic:EU 2018/848 and USDA NOP standards enable pharmacy and specialty retail premiums. Jiangxi cooperatives face liquidity strain during three-year orchard conversion windows.
- Cosmetic:REACH framework compliance with ECHA substance evaluations shapes European formulation supply chain entry. German and French manufacturers specify oleic acid profiles above 80 percent.
Refined grades sit at the top of the volume ranking, with organic certification climbing the fastest.
Application:
Application segments stratify by margin structure and customer acquisition cost, with cosmetic uses commanding sustained pricing power against commoditized culinary volumes.
- Skincare:K-beauty anti-aging serums and facial oils specify cold-pressed grades with documented oleic acid retention. Japanese consumers demonstrate 18-month retention rates for subscription-based facial oil programs.
- Haircare:Repair masks and scalp treatments absorb unrefined nutrient profiles at premium positioning. Seoul-based distributors maintain dedicated procurement desks in Changsha for direct orchard sourcing.
- Culinary:High smoke-point cooking mediums compete against high-oleic palm olein in Southeast Asian frying applications. Supermarket channel consolidation absorbs GB 2716 compliance costs.
- Aromatherapy:Carrier oil applications for essential oil blending require solvent-free extraction credentials. Supercritical CO2 installations in Jiangxi province validate commercial scalability for this segment.
Culinary applications retain volume leadership, though skincare is expanding most quickly.
End User:
End user concentration determines batch size economics and inventory risk, with industrial manufacturers demanding contractual volume commitments absent in household spot purchasing.
- Beauty Salons:Professional treatment protocols specify consistent oleic acid profiles across service menus. South Korean salon chains negotiate multi-year offtake contracts with named Hunan orchards.
- Food Industry:Industrial frying and packaged food manufacturing prioritize cost-stable supply over unrefined nutrient preservation. Hexane-refined palm olein substitution pressures volume margins.
- Household:Direct-to-consumer digital channels bypass wholesale markups for cold-pressed cosmetic grades. Retention metrics favor subscription models in Tokyo and Seoul metropolitan areas.
- Manufacturers:Cosmetic formulators and food processors require segregated crush infrastructure to prevent organic claim contamination. Dedicated line investments exceed mid-producer balance sheet capacity.
Food industry procurement dominates volume, with beauty salons gaining share fastest.
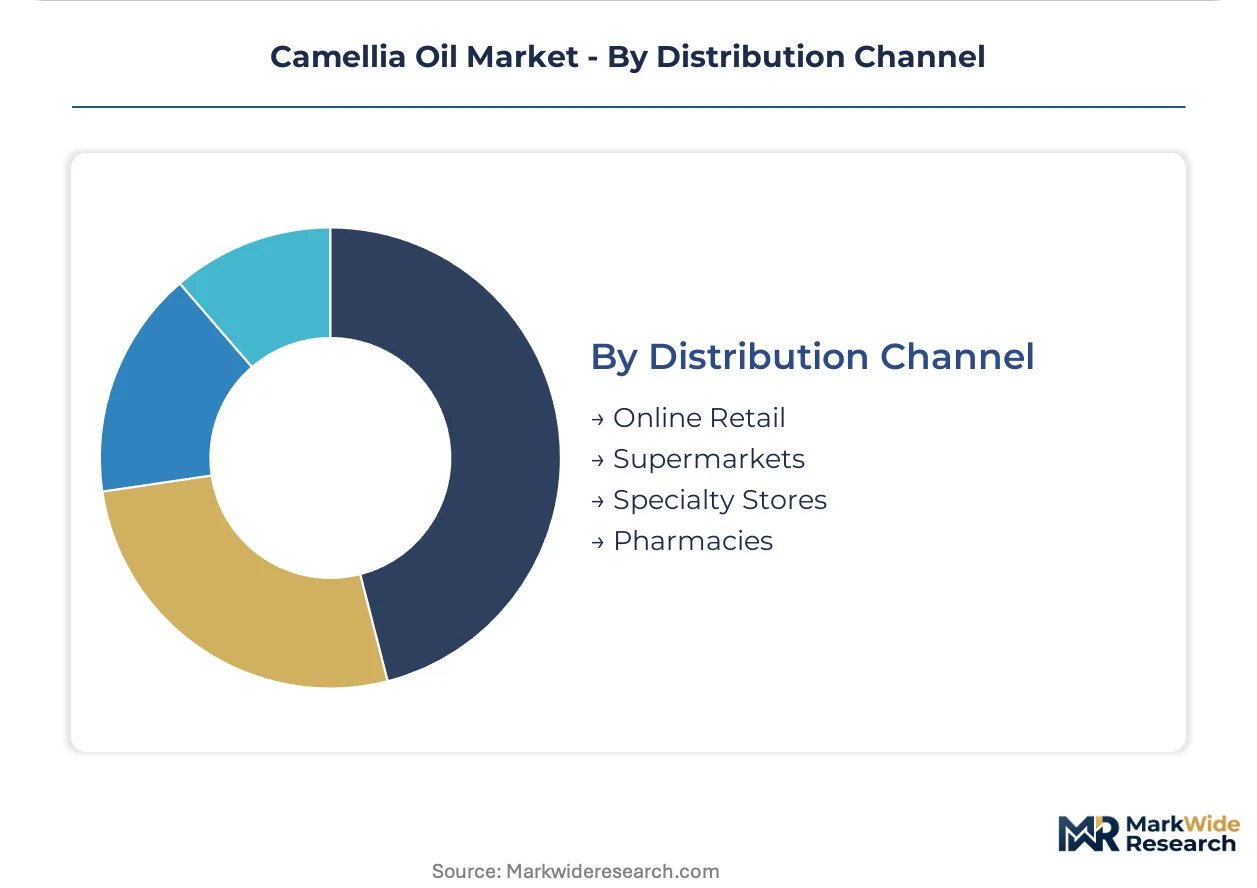
Distribution Channel:
Channel selection reflects certification visibility requirements and customer education burdens, with premium grades bypassing retail labeling through B2B formulation supply chains.
- Online Retail:E-commerce platforms enforce SAMR GB 2716 origin disclosure and pressing method specification. Small processors without laboratory verification face delisting.
- Supermarkets:Refined culinary grades absorb compliance costs through consolidated procurement. Price competition with palm olein alternatives constrains shelf positioning.
- Specialty Stores:Organic certification tiers extract 40-60 percent premiums through educated consumer self-selection. French distributors secure multi-year conversion contracts with Jiangxi producers.
- Pharmacies:Ingestible skincare formulations require MFDS and SAMR harmonization for cross-border labeling. Early movers in Seoul and Shanghai test regulatory arbitrage strategies.
Supermarkets maintain volume leadership, with specialty stores on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating cold-pressed camellia oil production in Chinese provinces with lower compliance costs, while EU REACH certification requirements pull cosmetic-grade refining toward German and Italian equipment hubs. SAMR enforcement of GB standards is compressing small-producer participation in township-level processing clusters.
China
Hunan province's crush capacity anchors global cold-pressed supply, with Changsha processing clusters absorbing seed flows from Jiangxi and Guangxi orchards. SAMR's GB 2716 edible oil labeling rules now require origin disclosure and pressing method specification, delisting small processors lacking laboratory verification capacity. Integrated refiners in Hunan province consolidate distribution through captive refining assets.
South Korea
Seoul-based K-beauty formulators drive premium absorption for unrefined nutrient profiles in anti-aging serums and hair repair masks. MFDS cosmetic safety standards shape import specifications for oleic acid concentrations exceeding 80 percent. Distributors maintain dedicated procurement desks in Changsha for direct orchard sourcing and harvest batch traceability.
Japan
Tokyo metropolitan consumers demonstrate 18-month retention rates for subscription-based facial oil programs. METI guidelines for cosmetic ingredient safety influence import testing protocols for cold-pressed grades. Osaka-based formulators negotiate long-term offtake contracts with named Hunan orchards, displacing commodity spot purchasing.
Germany
ECHA substance evaluations under REACH framework create export eligibility pathways for Chinese cosmetic-grade producers. Frankfurt and Hamburg distributors specify oleic acid profiles above 80 percent for formulation supply chains. German equipment suppliers have installed supercritical CO2 pilot units in Changsha and Nanchang processing clusters.
France
Paris-based cosmetic houses secure multi-year organic conversion contracts with Jiangxi cooperatives under EU 2018/848 standards. ANSM cosmetic safety regulations align with ECHA REACH requirements for solvent-free extraction credentials. Pharmacy channel premiums extract 40-60 percent price advantages for certified organic tiers.
Camellia Oil Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue organic certification and supercritical extraction technology licensing. The market structures around three archetypes: integrated Hunan refiners with captive crush capacity, trading houses leveraging oilseed infrastructure for raw material flows, and Jiangxi-based organic specialists serving export cosmetic channels. Competitive moves concentrate on backward integration into orchard control and dedicated line investments to prevent cross-contamination between refining and cosmetic grades.
Within the integrated refiner tier, Hunan Shanrun Camellia Oil Technology & Development Co., LTD and Hunan Jinhao Camellia Oil Corp., Ltd exemplify province-based consolidation through downstream refining assets. Wilmar International Limited occupies a position among trading-oriented participants leveraging oilseed infrastructure across Asia. JiangXi YouNiBao Agricultural Science and Technology Co., LTD anchors the organic-specialist archetype, securing EU 2018/848 and USDA NOP certifications for export-bound cosmetic grades.
| Leading Market Players |
|---|
| Hunan Shanrun Camellia Oil Technology & Development Co., LTD |
| Waltt Products Co.,Ltd |
| Hunan Jinhao Camellia Oil Corp., Ltd |
| Laozhiqing |
| Shanrun |
| Wilmar International Limited |
| JiangXi YouNiBao Agricultural Science and Technology Co., LTD |
| Runxinoil |
| Hunan Guitaitai Camellia Oil Technology Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
EU 2018/848 organic conversion mandates gate both qualified supply access and premium-tier pricing power, compressing uncertified Jiangxi cooperatives into commodity spot markets while enabling certified Hunan producers to extract pharmacy-channel premiums. SAMR laboratory verification requirements for GB 2716 compliance further bifurcate the supply base, concentrating pricing leverage among integrated refiners with captive testing infrastructure.
Pricing Analysis
Distributor margin layers absorb 15-25 point markups between Changsha processing clusters and Seoul formulation houses, with direct-to-consumer subscription models bypassing wholesale structures entirely. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and oleic acid documentation, with EU REACH-compliant cosmetic grades commanding the widest spreads. Cost compression in refined culinary tiers intensifies because palm olein substitution erodes volume margins, while household consumers in Tokyo and Seoul metropolitan areas demonstrate lowest price sensitivity for documented harvest-batch traceability.
Supply Chain Analysis
Dual-sourcing requirements from South Korean and Japanese cosmetic houses now mandate named-orchard qualification alongside secondary Hunan supplier validation, compressing single-source trader margins. Geographic supply concentration centers on China, with seed flows from Jiangxi and Guangxi feeding Changsha and Nanchang crush clusters. Raw material dependencies rest on Camellia oleifera seed availability, hexane or supercritical CO2 processing inputs, and REACH-certified laboratory verification capacity. Single-source vulnerability propagates through climate-exposed subtropical orchard stock. Distribution runs through B2B formulation supply chains for cosmetic grades and consolidated supermarket procurement for refined culinary volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on supercritical CO2 extraction adoption, which eliminates solvent residue testing burdens while preserving premium-tier oleic acid credentials that justify subscription pricing.
For Market Incumbents: Cement backward integration into named-orchard control to secure harvest batch traceability that Seoul formulators now mandate, while deploying dedicated crush lines to prevent organic claim contamination from shared refining infrastructure. Hexane-refined palm olein substitution in Southeast Asian food manufacturing threatens volume-tier margins, making certification investment the priority defensive lever. For New Entrants and Emerging Players: Capture white-space in EU pharmacy-channel organic certification, where Jiangxi cooperatives face liquidity strain during three-year conversion windows and French distributors seek multi-year supply contracts. Direct-to-consumer digital channels in Tokyo demonstrate 18-month retention rates for facial oil subscriptions, offering the most penetrable go-to-market angle for solvent-free extraction credentials. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale organic specialists because SAMR enforcement is delisting township-level processors without laboratory verification capacity, creating fragmented acquisition targets with stranded orchard assets. Long-term viability across the analysis window favors integrated Hunan refiners with REACH export eligibility. The signal to watch is MFDS-SAMR harmonization progress on ingestible skincare labeling, which would unlock cross-border regulatory arbitrage for early movers.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Licensing | German and Italian equipment suppliers validate commercial scalability for REACH-compliant cosmetic grades in Changsha clusters. |
| Named-Orchard Backward Integration | Long-term offtake contracts with Hunan orchards displace commodity spot purchasing by Seoul-based K-beauty formulators. |
| EU 2018/848 Organic Certification | Three-year conversion contracts with French distributors extract 40-60 percent pharmacy-channel premiums for Jiangxi producers. |
| Dedicated Line Infrastructure Investment | Segregated crush capacity prevents cross-contamination risks that void organic claims for cosmetic-grade batch segregation. |
| Direct-to-Consumer Subscription Launch | Brand-owned digital channels bypass wholesale markups for cold-pressed cosmetic grades in Tokyo and Seoul metropolitan areas. |
Methodological Framework
Multiple input streams — primary interviews with cold-press technicians, cosmetic formulation directors, and SAMR compliance officers, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged Hunan province crush facility operators, Seoul-based K-beauty procurement desks, and EU 2018/848 certification auditors. Secondary sources included ECHA REACH substance evaluation databases, SAMR GB 2716 enforcement bulletins, and EU organic conversion registry records. Cross-referencing between trade flow data from Chinese customs records and South Korean MFDS import inspection reports anchored volume estimates.
Data-stream reconciliation across product type, application, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory modeling. Industry-specific forecast inputs incorporated supercritical CO2 extraction adoption curves and organic certification timeline compression effects on Jiangxi cooperative working capital.
Climate volatility in subtropical China, REACH substance evaluation revision schedules, and MFDS-SAMR harmonization delays are the dominant revision risks for camellia oil supply and demand assumptions. Deviation in EU 2018/848 enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Fresh Fruits and Vegetables Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Aegle Marmelos Market
Fruits and Vegetables
Jicama Market
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Passion Fruit Extract Market
Fruits and Vegetables
Middle East and Africa Shiitake Mushroom Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
Global Hass Avocado Market
Fruits and Vegetables
Yellow Oyster Mushroom Market