
 Buckwheat Groat Flour Market | 2026-2036
Buckwheat Groat Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Buckwheat Groat Flour Market Outlook
China's expanding buckwheat processing corridor is reconfiguring raw material flows for Western millers. Bob's Red Mill Natural Foods leverages its vertically integrated stone-milling infrastructure to sustain consistent supply to North American health food channels. Birkett Mills anchors its position through specialized groat-to-flour processing technology that controls protein degradation rates. Archer Daniels Midland Company competes via bulk procurement networks spanning Inner Mongolian growing regions.
Buckwheat groat flour consists of milled endosperm and embryo fractions from Fagopyrum esculentum seeds, typically retaining 9-13% protein content and exhibiting amylograph peak viscosities below 400 BU due to absent gluten-forming proteins. The flour functions primarily as a viscoelastic binder substitute in wheat-free bakery matrices and as a flavor-dense coating medium in traditional savory applications. Organic buckwheat flour commands premium positioning through certified supply chains, while gluten-free buckwheat flour extends into allergen-controlled manufacturing environments where cross-contamination protocols determine facility eligibility. Dark buckwheat flour, with its higher hull inclusion rate, occupies niche applications in Eastern European and East Asian heritage food production where color intensity signals authenticity.
FDA gluten-free labeling rules and USDA organic certification requirements govern product claims and import eligibility for buckwheat groat flour entering the United States. The EU's REACH framework and EFSA novel food assessments shape ingredient approval pathways for processed buckwheat derivatives in European formulations. Stakeholders must monitor evolving F-Gas Regulation impacts on drying energy costs and track ESG disclosure mandates under CSRD that will expose supply chain provenance gaps in buckwheat sourcing networks.
Market Dynamics
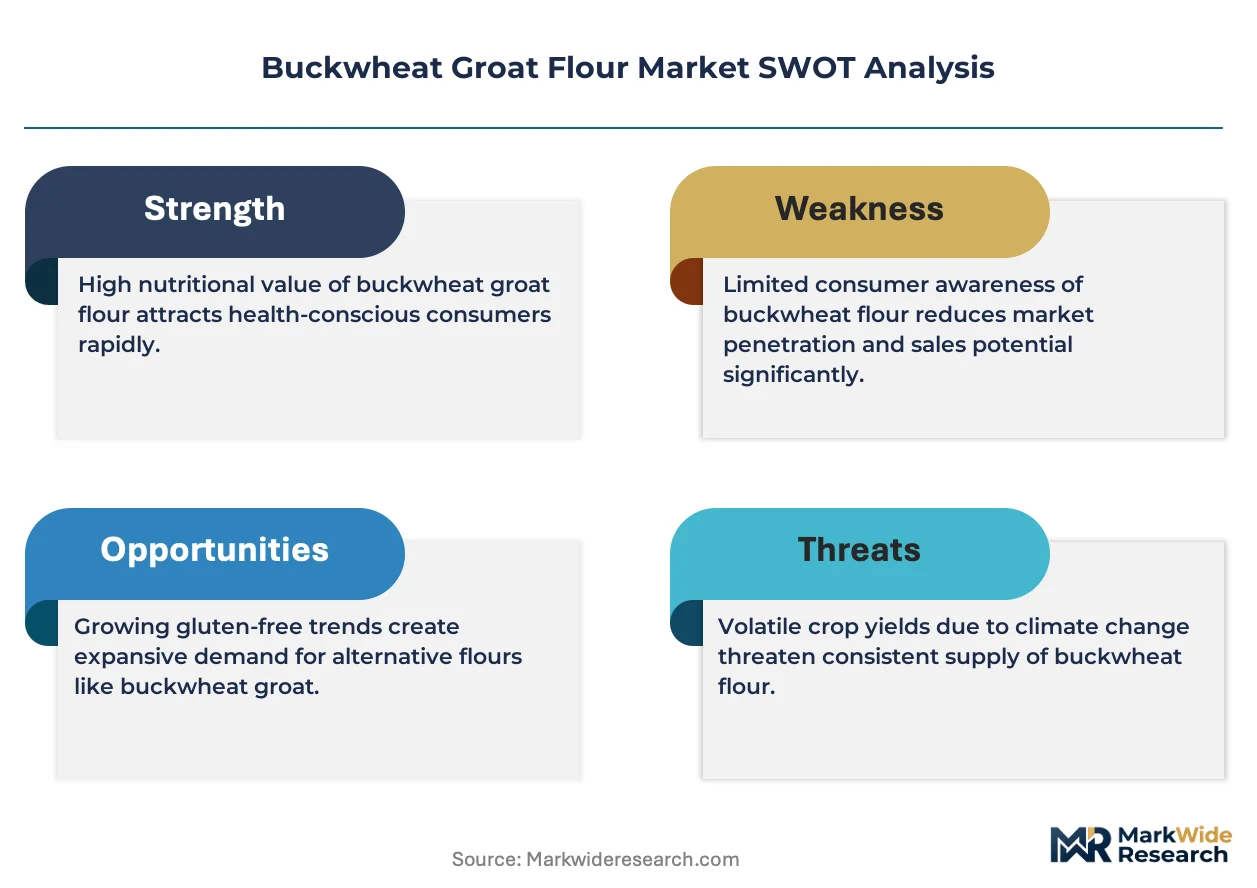
EU F-Gas Regulation compliance costs are restructuring drying energy economics for buckwheat millers, forcing capital allocation toward low-carbon thermal processing infrastructure and reshaping procurement priorities across Western European supply chains.
Growth Catalysts
- Gluten-free bakery expansion:FDA labeling rules for wheat-free claims are expanding shelf-space allocation for buckwheat-based formulations in US retail channels.
- REACH-driven clean-label migration:ECHA substance restrictions on synthetic additives are accelerating buckwheat flour substitution in European processed foods.
- Brittany heritage authentication:French AOC-equivalent standards for traditional galette production are sustaining premium-grade groat demand in specialized milling operations.
Market Restraints
- Inner Mongolian supply concentration:Raw buckwheat sourcing dependence on China's northern growing belt exposes millers to climate volatility and export quota shifts.
- Protein stability limitations:Buckwheat's 9-13% protein content degrades rapidly under conventional milling heat, constraining shelf-life extension for industrial bakeries.
- Substitution by quinoa and teff:Competing ancient grains with higher amino acid completeness are capturing functional food positioning in North American health channels.
Strategic Opportunities
- CSRD supply-chain disclosure mandates:EU corporate sustainability reporting requirements are creating first-mover advantage for traceable organic buckwheat networks.
- Stone-milling technology convergence:Cold-grind systems paired with optical hull-sorting are enabling protein retention above 12% in dark flour grades.
- East Asian heritage food export:Japanese soba and Korean makguksang demand are opening premium positioning for high-hull-inclusion buckwheat flour in Seoul and Tokyo specialty channels.
Industry Challenges
- Cross-contamination certification timelines:Gluten-free facility accreditation under BRC and FSSC 22000 protocols requires 12-18 month validation cycles that delay market entry.
- Optical sorting capex intensity:Precision hull-removal equipment for light flour production demands $2-4 million per processing line, concentrating investment capacity among scaled operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buckwheat Groat Flour Market |
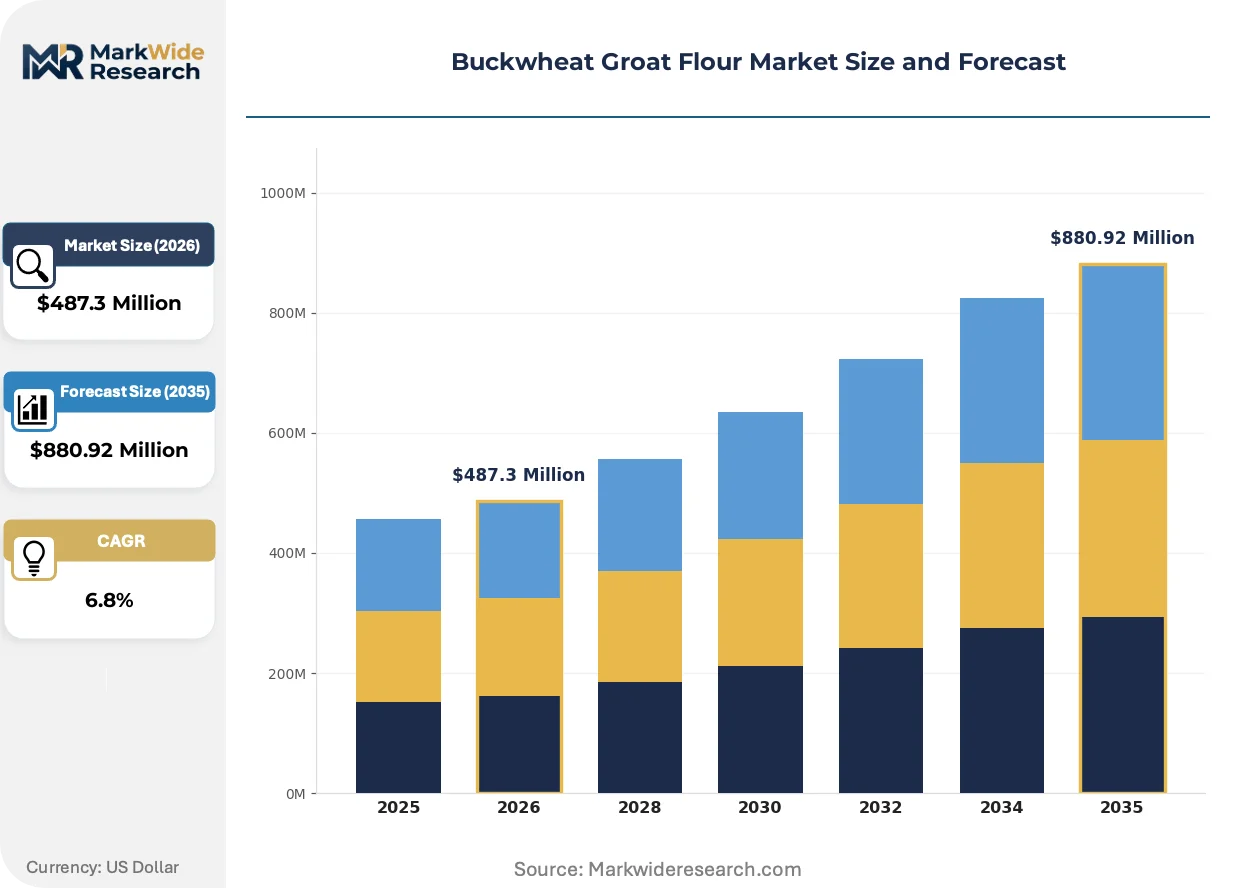
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Buckwheat Flour, Conventional Buckwheat Flour, Gluten-Free Buckwheat Flour, Dark Buckwheat Flour End User: Bakeries, Food Manufacturers, Health Food Stores, Restaurants Packaging Type: Bags, Bulk Containers, Retail Packs, Vacuum-Packed Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Archer Daniels Midland Company, Bob's Red Mill Natural Foods, Hain Celestial Group, Birkett Mills, Scoular, Galinta IR Partneriai, Homestead Organics, Doves Farm Foods, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buckwheat Groat Flour Market Strategic Shifts
Processing technology and regulatory disclosure requirements are converging to redefine competitive advantage in buckwheat groat flour, with thermal efficiency and provenance verification emerging as distinct value-creation axes.
Near-infrared spectroscopy for real-time protein monitoring is collapsing quality-assurance timelines from batch sampling to continuous inline verification. Artisanal millers in France and Japan are adopting these systems to maintain AOC and JAS certification thresholds without production slowdowns. The compression of testing cycles is enabling just-in-time milling contracts that were previously uneconomical for small-batch heritage flour production.
CSRD scope 3 emissions disclosure rules are mandating granular supply-chain documentation for EU-headquartered food manufacturers sourcing buckwheat derivatives. ESG audit requirements are forcing procurement teams to map groat origins to specific Inner Mongolian county-level cooperatives. French and German bakery chains are responding by consolidating supplier relationships with vertically integrated millers capable of field-level traceability.
Direct-to-bakery procurement platforms are disintermediating traditional grain distributors for certified organic buckwheat flour in North American urban markets. Specialty bakeries in Portland, Montreal, and Brooklyn are contracting directly with stone mills for scheduled delivery of specified protein and ash content grades. This channel shift is most pronounced in coastal metropolitan areas where gluten-free and heritage-claim positioning commands retail price premiums.
Buckwheat Groat Flour Market Segmentation
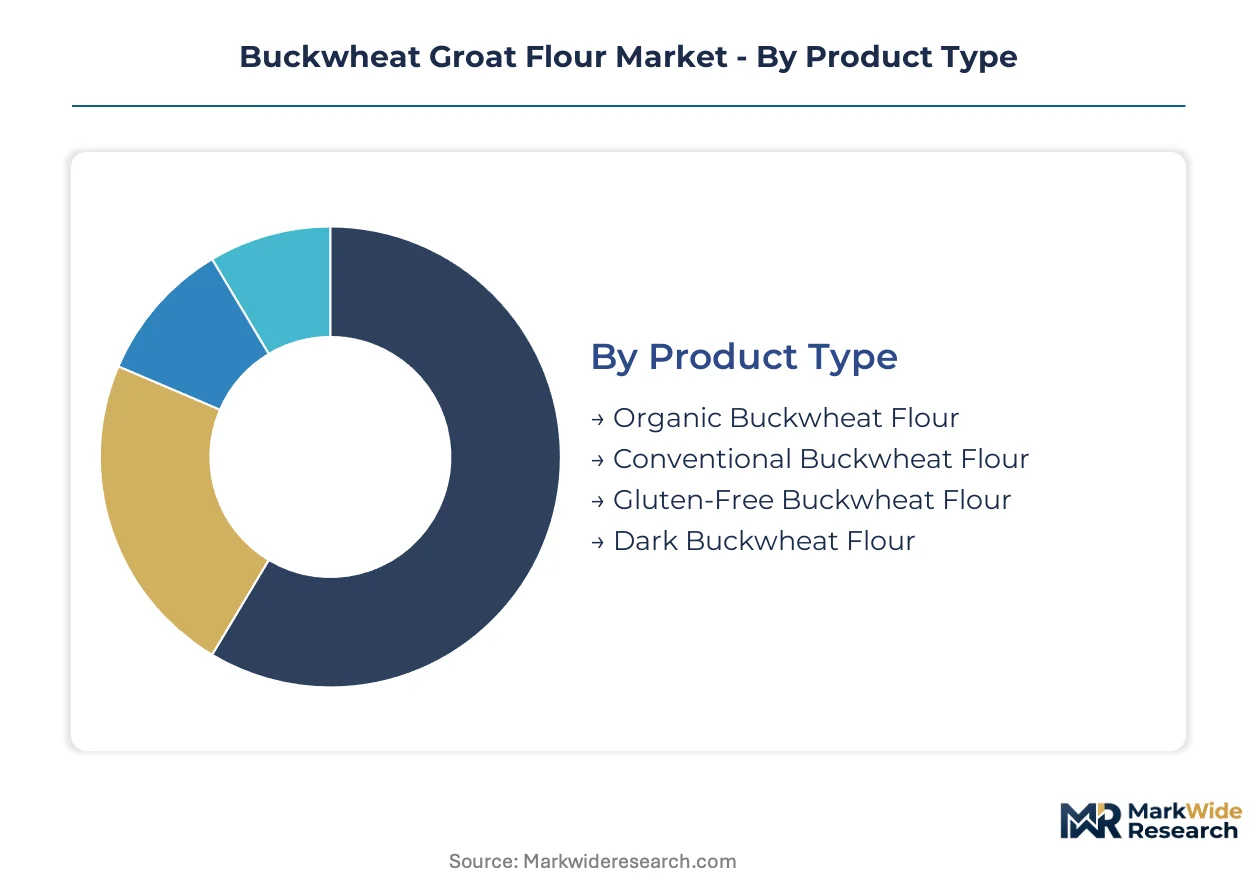
Buckwheat groat flour demand fragments across certification tiers, end-use specifications, and channel economics. Each segmentation axis reveals distinct margin structures and procurement protocols that shape supplier positioning.
Product Type:
Use-case spectrum spans heritage authenticity claims to allergen-controlled manufacturing environments.
- Organic Buckwheat Flour:Certified supply chains with field-level traceability command premium positioning in French AOC galette production and Japanese JAS-certified soba milling. Brittany's traditional bakeries and Tokyo specialty channels sustain demand concentration despite 15-20% price premiums over conventional grades.
- Gluten-Free Buckwheat Flour:Dedicated facility processing under BRC and FSSC 22000 protocols eliminates cross-contamination risk for wheat-allergen populations. North American health food retail and EU celiac-certified bakeries drive volume, though 12-18 month accreditation timelines constrain supplier entry.
- Dark Buckwheat Flour:Higher hull inclusion rates (15-25%) deliver intense color and fiber content for Eastern European and East Asian heritage applications.
- Conventional Buckwheat Flour:Standard milling grades serve cost-sensitive industrial bakeries and bulk food service procurement.
Established volume favors conventional milling; emerging adoption favors gluten-free certification.
End User:
Customer type determines specification stringency and contract structure.
- Bakeries:Artisanal producers in France, Japan, and coastal North American cities specify protein content (9-13%) and ash thresholds for fermentation performance. Direct-to-mill procurement platforms are disintermediating distributors in Portland, Montreal, and Brooklyn.
- Food Manufacturers:Industrial scale users require consistent amylograph viscosity below 400 BU for wheat-free matrix binding. REACH-compliant clean-label substitution in EU processed foods accelerates buckwheat inclusion.
- Health Food Stores:Organic and gluten-free claims dominate shelf-space allocation with consumer-facing certification labeling.
- Restaurants:Heritage-menu positioning in Korean makguksang and Japanese soba houses drives premium dark flour demand.
Contract reliability favors food manufacturers; margin expansion favors artisanal bakery direct sales.
Packaging Type:
Volume scale and shelf-life requirements dictate format selection.
- Bulk Containers:Industrial bakeries and food manufacturers procure 500kg totes for just-in-time milling integration. CSRD scope 3 disclosure mandates favor reusable container programs with field-level traceability documentation.
- Vacuum-Packed:Oxygen exclusion extends protein stability for premium organic grades distributed through specialty channels. Japanese soba houses and French AOC producers specify nitrogen-flushed packaging for 18-month shelf life.
- Bags:Standard 25-50kg woven polypropylene serves conventional milling and food service.
- Retail Packs:Consumer-facing 1-5kg formats for health food and supermarket channels.
Procurement efficiency favors bulk containers; brand premiumization favors vacuum-packed certification.
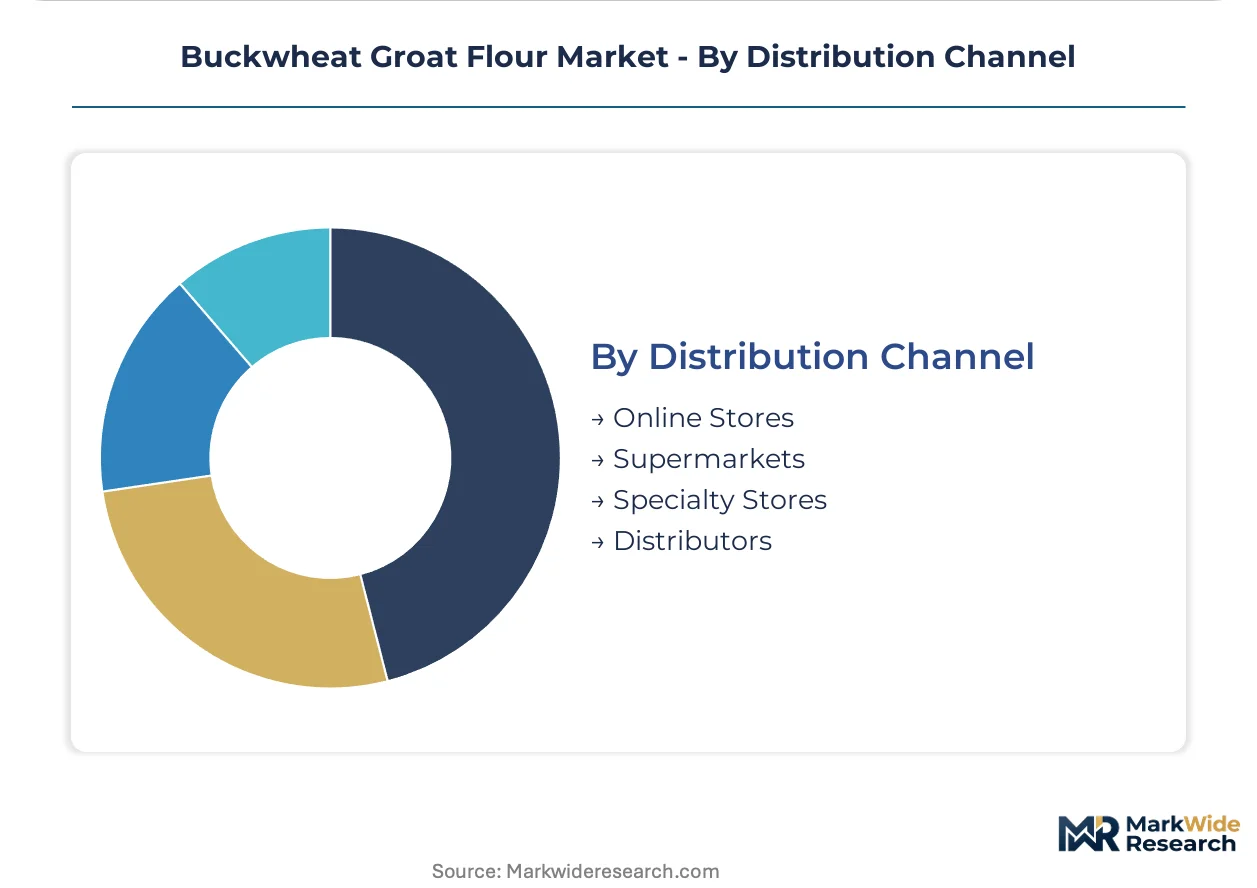
Distribution Channel:
Channel selection reflects customer scale and geographic concentration.
- Specialty Stores:Dedicated gluten-free and organic retailers in France, Germany, and coastal US cities consolidate certified buckwheat sourcing. ESG audit requirements under CSRD favor supplier relationships with documented Inner Mongolian cooperative provenance.
- Online Stores:Direct-to-bakery platforms enable scheduled delivery of specified protein grades, collapsing traditional distributor margins in North American urban markets.
- Supermarkets:Mass retail placement requires FSSC 22000 certification and consistent supply for private-label programs.
- Distributors:Traditional grain merchants retain relevance for smaller bakeries lacking procurement scale.
Relationship depth favors specialty stores; cost compression favors online direct procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food assessments and EU F-Gas Regulation compliance are reshaping sourcing protocols for buckwheat groat flour across Western European milling operations. Demand clusters in France, China, Japan, and the United States reflect distinct heritage food traditions and regulatory frameworks.
France
Brittany's traditional galette production sustains premium-grade buckwheat milling with AOC-equivalent standards enforcing protein and ash specifications. REACH substance restrictions on synthetic additives accelerate clean-label buckwheat substitution in processed foods. Rennes and Quimper anchor specialized groat-to-flour processing corridors serving artisanal bakeries.
China
Inner Mongolian growing regions supply raw buckwheat to Western millers, though climate volatility and export quota shifts create procurement uncertainty. SAMR food safety standards govern flour import eligibility and cross-border trade documentation. Hohhot processing corridors are expanding capacity to capture value from domestic groat production.
Japan
JAS-certified soba houses in Tokyo and Nagoya specify nitrogen-flushed packaging for 18-month protein stability in premium dark flour grades. METI agricultural standards regulate organic certification thresholds for heritage food export channels. Kanto region specialty mills maintain cold-grind systems for authentic soba production.
United States
FDA gluten-free labeling rules expand shelf-space allocation for buckwheat-based formulations in Portland, Brooklyn, and Montreal retail channels. USDA organic certification requirements govern import eligibility for processed derivatives. Pacific Northwest stone mills are disintermediating traditional distributors through direct-to-bakery procurement platforms.
Germany
CSRD scope 3 emissions disclosure mandates force procurement teams to map groat origins to specific county-level cooperatives for ESG audit compliance. ECHA restrictions on food contact substances favor buckwheat flour in clean-label manufacturing. Bavarian bakery chains are consolidating supplier relationships with vertically integrated millers capable of field-level traceability.
Buckwheat Groat Flour Market Competitive Environment
Stone-milling specialists and bulk commodity traders split the buckwheat groat flour market between premium heritage positioning and cost-driven industrial supply. The vendor base concentrates among three strategic archetypes: vertically integrated natural foods companies with cold-grind infrastructure, regional millers serving AOC and JAS certification channels, and agricultural conglomerates leveraging procurement networks across Inner Mongolian growing belts. Competitive moves center on optical sorting technology licensing for protein retention and direct-to-bakery platform development to collapse distributor margins.
Among North American natural foods specialists, Bob's Red Mill Natural Foods and Birkett Mills exemplify the heritage-milling archetype through stone-grind infrastructure and certification maintenance. Archer Daniels Midland Company anchors the commodity-procurement tier with bulk sourcing networks. These three entities represent the dominant competitive positions without exhaustive market coverage.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Bob's Red Mill Natural Foods |
| Hain Celestial Group |
| Birkett Mills |
| Scoular |
| Galinta IR Partneriai |
| Homestead Organics |
| Doves Farm Foods |
| Cargill |
| Others |
Value Chain & Pricing Dynamics
Inner Mongolian processing corridors in Hohhot anchor raw groat availability, with capacity expansion there directly conditioning downstream pricing power for Western European and North American millers facing REACH compliance cost absorption.
Pricing Analysis
Price spreads between Brittany AOC-certified organic grades and conventional industrial milling runs exceed fifteen percentage points, with certification maintenance and nitrogen-flushed packaging constituting the primary differentiation drivers. Three-tier pricing structure across premium organic, certified gluten-free, and conventional economy levels is compressing at the mid-tier as stone-milling technology diffusion erodes heritage premiums. Price erosion runs through standard conventional grades as Inner Mongolian export quota volatility forces spot-market sourcing. Industrial bakeries exhibit highest price sensitivity, while Tokyo soba houses and French AOC producers accept substantial premiums for documented provenance.
Supply Chain Analysis
Raw buckwheat groat flows draw from Inner Mongolian growing belts, Ukrainian black-soil regions, and Canadian prairie provinces, with Chinese supply dominating volume for Western millers. Milling equipment, optical hull-sorting systems, and nitrogen-flushing packaging constitute critical input dependencies. Single-source vulnerability concentrates in Hohhot processing corridors where climate volatility and export licensing shifts disrupt contracted flows. Distribution runs through vertically integrated miller-direct platforms for artisanal bakery segments, while industrial procurement maintains traditional grain distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CSRD scope 3 disclosure mandates are disrupting established procurement patterns, creating first-mover advantage for traceable supply networks that can document field-level cooperative provenance across the analysis window.
For Market Incumbents: Pre-empt optical sorting technology licensing agreements to secure protein retention above twelve percent in dark flour grades before equipment capex barriers consolidate advantage among scaled operators. Defend against direct-to-bakery platform disintermediation by consolidating backward integration into Inner Mongolian county-level cooperatives for ESG audit readiness.
For New Entrants and Emerging Players: Establish a beachhead in vacuum-packed organic certification for Japanese JAS and French AOC channels where eighteen-month shelf-life specifications command sustainable premium capture. Target Portland, Montreal, and Brooklyn metropolitan clusters through scheduled protein-grade contracting that collapses traditional distributor margins.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors stone-milling specialists with cold-grind infrastructure and existing certification maintenance capabilities over commodity traders lacking traceability depth. Long-term viability hinges on CSRD compliance readiness; acquisition screening should prioritize millers with documented Inner Mongolian cooperative relationships. The signal to watch is EU F-Gas Regulation enforcement intensity affecting thermal processing cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Technology Licensing | Protein retention above twelve percent enables premium dark flour positioning in Tokyo and Seoul heritage channels. |
| Direct-to-Bakery Platform Development | Scheduled protein-grade delivery collapses distributor margins in Portland, Brooklyn, and Montreal metropolitan markets. |
| Backward Integration into Cooperative Sourcing | Field-level traceability documentation satisfies CSRD scope 3 disclosure mandates for EU-headquartered food manufacturers. |
| Cold-Grind Infrastructure Expansion | Thermal processing below conventional heat thresholds extends shelf-life for nitrogen-flushed premium packaging specifications. |
| Gluten-Free Facility Accreditation | BRC and FSSC 22000 certification unlocks twelve to eighteen month market entry timelines for celiac-controlled manufacturing environments. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with stone mill operators, procurement leads at French and German bakery chains, gluten-free facility certification auditors, and specialty grain distributors; alongside secondary validation through EU F-Gas Regulation implementation documents, EFSA novel food assessment records, FDA gluten-free labeling guidance, and customs trade flows for buckwheat groat movements. Bottom-up volume modeling across certification tiers and end-use segments was triangulated against top-down macroeconomic indicators.
Forecast inputs considered product type segmentation across organic, gluten-free, dark, and conventional grades; end-user differentiation between artisanal bakeries, industrial food manufacturers, health food retail, and restaurant channels; and packaging format economics from bulk containers through vacuum-packed premium formats. CAGRs were derived through regression analysis of historical volume trajectories adjusted for regulatory inflection points and technology adoption curves, with protein stability limitations and substitution dynamics by quinoa and teff incorporated as demand-side constraints.
Stress conditions across Inner Mongolian climate volatility, EU F-Gas Regulation enforcement intensity, and optical sorting equipment capex availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification timeline trajectories and heritage food export channel expansion. Cross-checking against ESG audit requirement implementation timelines and stone-milling technology diffusion rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Potato & Yam Derivatives Market
Ingredients
Cheese Ripening Enzymes Market
Ingredients
Glucomannan Market
Ingredients
Lupin Flour Market
Ingredients
Bromelain Ingredient Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Compressed Yeast Market
Ingredients
Textural Food Ingredients Market
Ingredients
North America Lipid Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
China Gelatin Market
Ingredients
Valerian Root Oil Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
Pea Starch Market
Ingredients
Savory Ingredients Market
Ingredients
Hen Egg White Protein Market