
 Millet Protein Market | 2026-2036
Millet Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Millet Protein Market Analytics
Bakery product applications is expanding as gluten-free formulations replace wheat-based alternatives in commercial and artisan channels. Cargill Incorporated leverages its grain handling infrastructure to secure millet supply chains across North American growing regions. Archer Daniels Midland Company sustains R&D programs focused on protein extraction efficiency from minor cereals. Nestlé S.A. anchors its plant-based portfolio development on ancient grain ingredient platforms including millet isolates.
Millet protein denotes protein fractions extracted from Panicum miliaceum, Setaria italica, or related species, typically yielding 65-75% protein concentration in isolate form through aqueous or alkaline extraction followed by isoelectric precipitation. Manufacturers refine these concentrates into functional ingredients that emulsify, bind moisture, and provide complete amino acid profiles for food systems requiring allergen-free protein fortification. Protein isolate commands premium positioning due to higher purity thresholds and superior functionality in beverage and supplement matrices, while gluten-free product applications capture accelerating demand as celiac diagnoses and voluntary wheat avoidance expand consumer bases. Puffed millet retains utility in snack and cereal bar segments where texture differentiation rather than protein load drives purchasing decisions.
The FDA oversees allergen labeling and GRAS determinations for novel protein ingredients entering U.S. food channels, while the USDA regulates organic certification pathways that many millet suppliers pursue for premium market access. India's FSSAI enforces standards for protein content claims on nutraceutical packaging, directly affecting how domestic processors position isolate products for export. EFSA's evolving stance on ancient grain health claims within EU member states shapes formulation decisions by European food manufacturers sourcing millet ingredients. Stakeholders must monitor regulatory divergence on protein fortification thresholds across destination markets to avoid reformulation costs or entry barriers.
Market Dynamics
Supply concentration in India's processing corridor is reshaping competitive positioning across the millet protein value chain, as the PLI scheme for millet value-addition consolidates domestic capacity and export-oriented ingredient sourcing.
Growth Catalysts
- FSSAI protein content standards:India's enforcement of nutraceutical packaging claims is compelling domestic processors to upgrade isolate purity, creating quality benchmarks that facilitate premium export positioning into North American and European channels.
- Sports nutrition procurement:Plant-based protein powder formulators are expanding millet-derived isolate volumes as whey alternatives face sustainability scrutiny and allergen liability exposure in commercial formulations.
- Celiac diagnosis expansion:Voluntary wheat avoidance and clinical gluten intolerance detection are compressing bakery product substitution cycles, with gluten-free millet formulations capturing shelf space in artisan and commercial channels.
Market Restraints
- Raw material volatility:Pearl millet and foxtail millet harvest yields fluctuate with monsoon patterns across Maharashtra and Karnataka, exposing processors to input cost instability and margin compression during deficit cycles.
- Extraction efficiency ceiling:Aqueous and alkaline protein recovery methods from minor cereals plateau at 65-75% isolate concentration, limiting functional performance in high-protein beverage matrices versus soy or pea alternatives.
- GRAS determination timelines:The FDA's novel protein ingredient review process imposes 18-24 month entry barriers for new millet isolate suppliers seeking U.S. food channel access, favoring incumbents with established dossiers.
Strategic Opportunities
- Infant nutrition penetration:Hypoallergenic protein fortification demand in pediatric formulations represents underexploited white space, with millet isolates offering complete amino acid profiles absent from common allergen sources.
- EU health claim authorization:EFSA's evolving stance on ancient grain nutritional benefits is creating regulatory tailwinds for European manufacturers seeking differentiated positioning in functional food segments.
- Puffed texture innovation:Extrusion technology convergence with protein fortification is enabling snack and cereal bar developers to merge texture differentiation with measurable protein load in single-ingredient solutions.
Industry Challenges
- Organic certification timelines:USDA-accredited organic millet supply chains require 36-month transition periods and third-party audit complexity, constraining rapid scaling for premium-positioned isolate products.
- Specialized protein chemist scarcity:Minor cereal extraction expertise concentrates in Indian agricultural universities and European research institutes, limiting workforce availability for new processing facility commissioning.
- Legacy equipment retrofit costs:Existing grain handling infrastructure designed for wheat and corn requires substantial capital reconfiguration to accommodate millet's smaller seed size and distinct hulling characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Millet Protein Market |
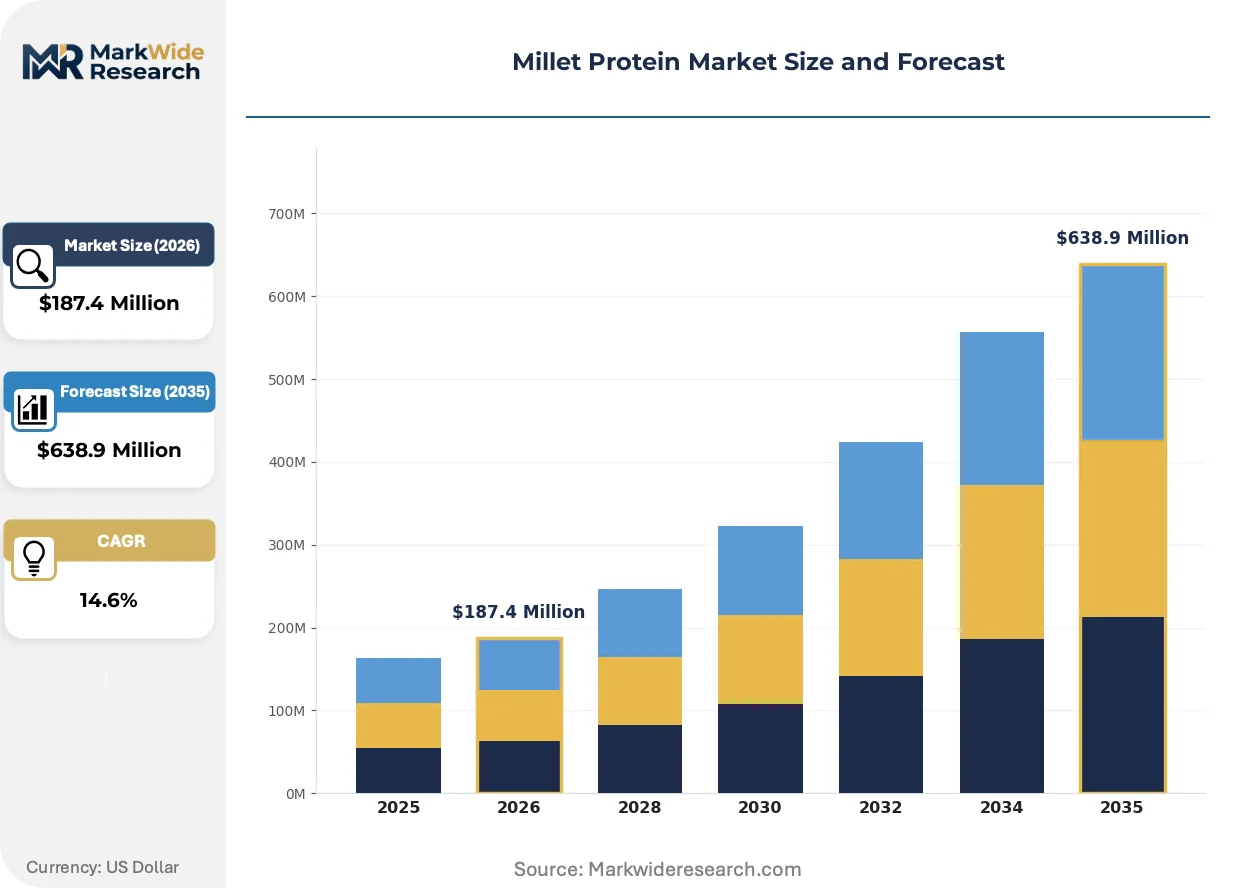
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grain, Flour, Protein Isolate, Puffed Millet End User: Food & Beverage, Nutraceuticals, Animal Feed, Bakery Products Form: Powder, Granules, Whole Seeds, Cooked Form Application: Protein Supplements, Gluten-Free Products, Snacks, Cereal Bars |
| Companies Covered | Nestlé S.A., Archer Daniels Midland Company, Cargill Incorporated, NOW Foods, Sresta Natural Bioproducts, Sunburst Superfoods, Golden Prairie Millet, Manini's LLC, Elementa Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Millet Protein Market Evolving Landscape
Technology convergence between extraction efficiency and functional protein design is compressing development cycles and enabling novel application expansion beyond traditional cereal and snack categories.
Alkaline-isoelectric precipitation hybrid systems are unifying protein recovery rates with functional attribute preservation. Sports nutrition formulators in North American markets are adopting these systems at accelerated cadence. The technology is unifying what previously required separate concentration and functionality enhancement steps, reducing capital intensity for mid-scale processors.
REACH registration requirements for novel protein isolates entering European cosmetic and nutraceutical channels are tightening substance documentation obligations. Industrial consequence includes accelerated investment in toxicology dossier preparation by Indian export-oriented suppliers. Cosmetic-grade millet protein applications face the most pronounced compliance burden, with formulators delaying launch timelines pending full registration clearance.
Direct-procurement relationships between sports nutrition brands and Indian processing cooperatives are displacing traditional ingredient distributor intermediaries. This channel compression is most visible in North American plant-based supplement verticals, where traceability demands and margin pressure converge. Buyers now require farm-level documentation that commodity traders cannot provide, restructuring sourcing architecture toward bilateral agreements.
Millet Protein Market Segmentation
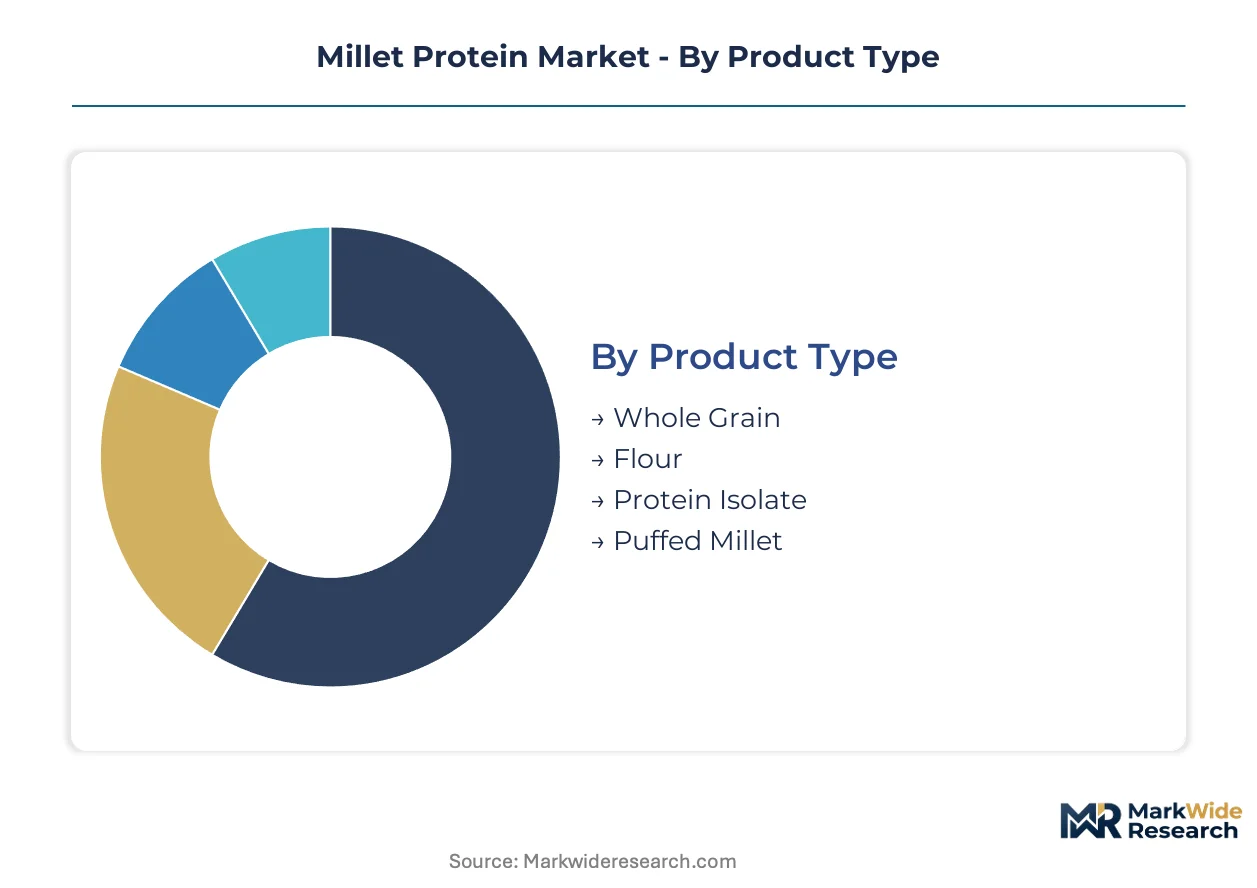
Millet protein segmentation reveals how extraction technology and formulation requirements create divergent value pools across food systems. Product type differentiation separates commodity grain handlers from specialized isolate processors, while end-user fragmentation demands distinct regulatory compliance and functional performance specifications.
Product Type:
Standardization dominates commodity grain formats, while isolate production requires intensive customization for protein concentration and functional attributes.
- Whole Grain:Unprocessed Panicum miliaceum or Setaria italica seeds retain hull integrity and native starch-protein matrices. Demand concentrates in Indian domestic consumption and export markets serving ethnic food channels, constrained by limited shelf stability versus processed alternatives.
- Protein Isolate:Aqueous or alkaline extraction yields 65-75% protein concentrates through isoelectric precipitation, enabling complete amino acid fortification in beverage and supplement matrices. Sports nutrition brands in the United States are expanding procurement volumes as whey alternatives face sustainability scrutiny.
- Flour:Milled endosperm fractions serve gluten-free bakery substitution applications with moderate protein retention.
- Puffed Millet:Extrusion-processed whole grains deliver texture differentiation in snack and cereal bar segments where protein load remains secondary to sensory properties.
Leading the category by volume: Whole Grain. Growing fastest: Protein Isolate.
End User:
Margin structure varies sharply across customer types, with nutraceutical buyers accepting premium pricing for certified isolate purity while animal feed processors prioritize cost minimization.
- Food & Beverage:Mass-market manufacturers incorporate millet protein for clean-label positioning and ancient grain marketing claims. Formulation teams at Cargill Incorporated and Archer Daniels Midland Company are developing standardized ingredient specifications for beverage fortification.
- Nutraceuticals:Dietary supplement brands require FSSAI-compliant protein content certifications for export positioning into Indian and North American channels. India's PLI scheme for millet value-addition is consolidating domestic processing capacity to serve this high-margin vertical.
- Animal Feed:Pearl millet protein fractions compete with soybean meal in poultry and aquaculture rations, constrained by amino acid profile limitations versus oilseed alternatives.
- Bakery Products:Artisan and commercial gluten-free formulators substitute millet flour for wheat in bread and pastry applications, driven by celiac diagnosis expansion and voluntary wheat avoidance trends.
Nutraceuticals command the steepest price premiums. Bakery Products are climbing the fastest as gluten-free shelf space expands.
Form:
Physical state determines handling infrastructure requirements and application flexibility across manufacturing environments.
- Powder:Spray-dried or milled protein concentrates enable precise dosing in supplement and beverage matrices. Indian processors are investing in fluidized bed drying capacity to meet sports nutrition brand specifications for dispersibility and solubility.
- Whole Seeds:Raw grain requires specialized hulling equipment due to smaller seed size versus wheat or corn, limiting processor switching flexibility.
- Granules:Intermediate particle sizes serve extruded snack and cereal applications where partial gelatinization improves texture.
- Cooked Form:Pre-gelatinized millet reduces preparation time for ready-to-eat meal manufacturers targeting convenience-positioned consumer segments.
Powder formats dominate value creation. Whole Seeds face the slowest expansion due to infrastructure retrofit requirements.
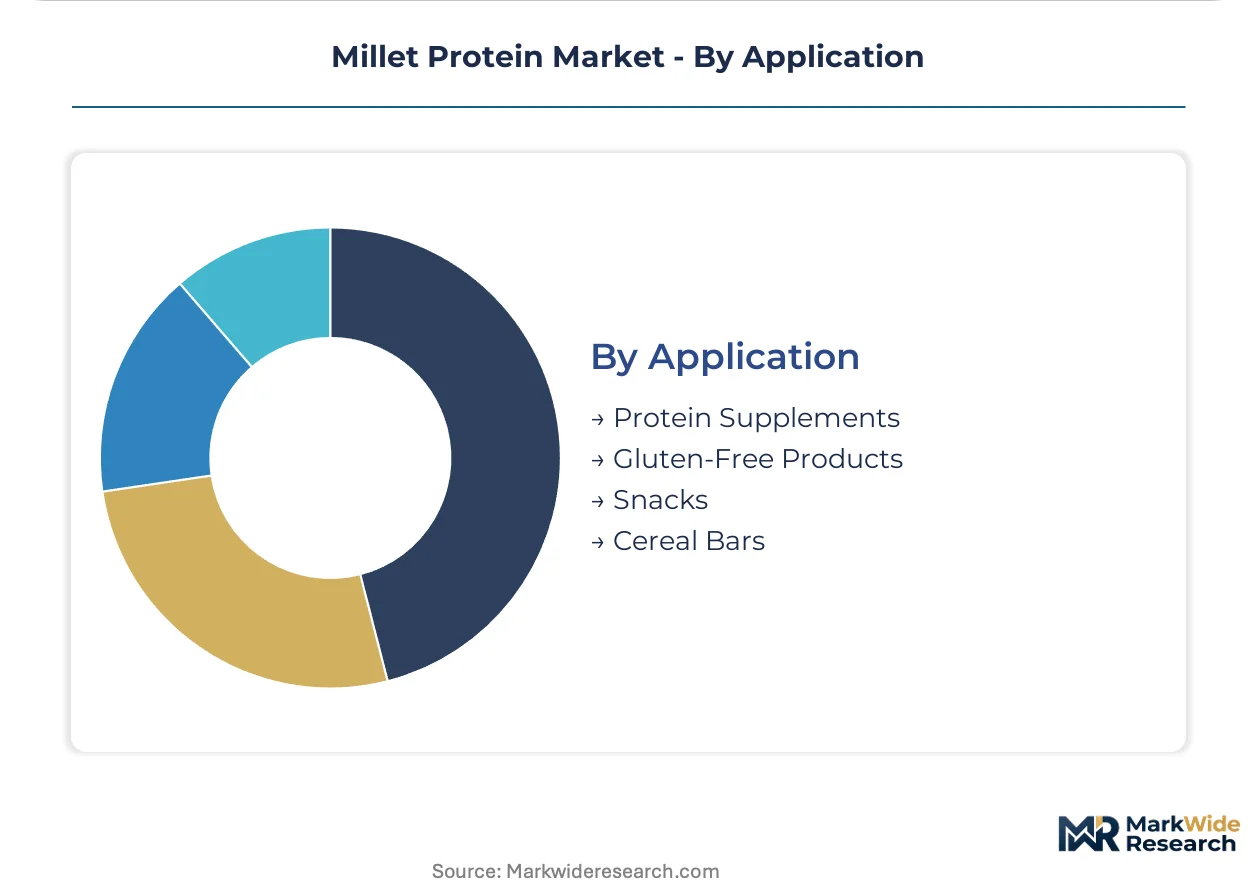
Application:
Functional performance requirements separate high-protein fortification targets from texture-driven snack applications with minimal protein loading.
- Gluten-Free Products:Millet flour and isolate enable wheat-free bakery and pasta formulations for celiac and non-celiac gluten sensitive consumers. FDA allergen labeling guidance is accelerating compliance investments by U.S. formulators seeking clean-label positioning.
- Protein Supplements:Isolate-based powders compete with pea and soy in plant-based sports nutrition, constrained by 65-75% concentration ceilings versus alternative protein sources. Nestlé S.A. anchors portfolio development on ancient grain platforms including millet-derived ingredients.
- Snacks:Puffed and extruded formats prioritize crunch texture and visual differentiation over nutritional density.
- Cereal Bars:Binding and moisture retention properties of millet protein support cohesive bar structure in high-fiber formulations.
Gluten-Free Products capture the largest volume base. Protein Supplements are expanding most quickly as dairy alternatives face supply scrutiny.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production-Linked Incentive scheme for millet value-addition has concentrated processing capacity in designated agro-industrial zones across Maharashtra and Karnataka, drawing export-oriented ingredient suppliers into tax-advantaged manufacturing corridors.
United States
Sports nutrition brands in California and Colorado are expanding procurement of millet-derived isolates for plant-based protein powders. The FDA's updated guidance on allergen labeling for ancient grains is accelerating compliance investments by domestic formulators. Minneapolis-St. Paul anchors North American grain handling infrastructure where Cargill Incorporated secures millet supply chains across regional growing areas.
India
Domestic processors in Maharashtra and Karnataka are upgrading isolate purity to meet FSSAI protein content standards for nutraceutical packaging claims. The PLI scheme for millet value-addition is consolidating processing capacity and export-oriented ingredient sourcing. Hyderabad and Bangalore host the primary R&D clusters where extraction efficiency improvements are being commercialized for North American and European channels.
Germany
European food manufacturers are monitoring EFSA's evolving stance on ancient grain health claims for differentiated positioning in functional food segments. REACH registration requirements for novel protein isolates entering cosmetic and nutraceutical channels are tightening substance documentation obligations. Hamburg and Frankfurt concentrate the toxicology dossier preparation capabilities that Indian export-oriented suppliers must access for EU market clearance.
Canada
Health Canada regulates protein fortification thresholds for plant-based supplements entering domestic retail channels, affecting how international suppliers position isolate products. Prairie provinces including Saskatchewan and Alberta are developing organic millet cultivation capacity to serve North American demand for certified ingredients. Winnipeg and Regina host the grain handling infrastructure being retrofitted for smaller-seed cereal processing.
United Kingdom
London-based sports nutrition distributors are compressing supply chains through direct-procurement relationships with Indian processing cooperatives, displacing traditional ingredient trader intermediaries. The Food Standards Agency enforces allergen labeling requirements that align with evolving FDA guidance. Manchester and Birmingham concentrate the formulation R&D facilities where gluten-free bakery applications are being developed for retail channel expansion.
Millet Protein Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium isolate production concentrating among firms with captive extraction technology while commodity grain handling remains fragmented. The vendor base spans three strategic archetypes: diversified agribusiness conglomerates with legacy grain infrastructure, specialized natural ingredient suppliers focused on organic certification, and mid-scale regional processors serving ethnic food channels. Competitive moves center on backward integration into Indian supply bases and capacity expansion in spray-dried isolate formats for sports nutrition applications.
Within the diversified agribusiness tier, Nestlé S.A. and Cargill Incorporated exemplify multinational scale advantages in grain procurement and formulation R&D. Archer Daniels Midland Company occupies a position among the integrated processors sustaining extraction efficiency programs for minor cereals. Among specialized natural ingredient suppliers, NOW Foods represents the branded supplement channel's demand for certified organic isolates. Sresta Natural Bioproducts anchors the India-based export-oriented processing segment serving North American and European nutraceutical formulators.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| NOW Foods |
| Sresta Natural Bioproducts |
| Sunburst Superfoods |
| Golden Prairie Millet |
| Manini's LLC |
| Elementa Ingredients |
| Others |
Value Network & Pricing Analysis
Alkaline-isoelectric precipitation hybrid systems are compressing production timelines while simultaneously concentrating cost advantages among processors with captive extraction technology, reshaping how isolate purity translates into pricing power across North American and European procurement channels.
Pricing Analysis
Short lead-time premiums command substantial markups in sports nutrition procurement, where formulation teams pay elevated rates for certified organic isolates with farm-level traceability documentation. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-certified export-grade isolates from domestic food-grade concentrates and commodity whole grain. Cost compression in standard-tier concentrates is intensifying because Indian PLI scheme beneficiaries are expanding capacity faster than brand offtake growth. Nutraceutical formulators exhibit lowest price sensitivity, while animal feed processors drive aggressive spot-market negotiations.
Supply Chain Analysis
Container freight rate volatility between Mumbai and Hamburg is amplifying landed cost differentials for European cosmetic-grade isolate shipments, forcing Indian exporters to absorb margin erosion or risk contract losses. Supply concentrates in India, Canada, and the United States, with Maharashtra and Karnataka anchoring global isolate production. Raw material flows draw from pearl millet harvests across Maharashtra, foxtail millet cultivation in Karnataka, and emerging organic acreage in Saskatchewan. Single-source vulnerability concentrates in monsoon-dependent Indian growing regions. Distribution runs through direct-procurement relationships displacing traditional commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into Indian growing regions has become the decisive competitive lever, as processors securing captive organic supply chains capture margin premiums unavailable to spot-market dependent competitors.
For Market Incumbents: Cement supply security through long-term offtake agreements with Maharashtra and Karnataka farming cooperatives, insulating against monsoon-driven raw material volatility. Deepen extraction efficiency advantages by commissioning continuous-flow alkaline-isoelectric systems that smaller competitors cannot finance. Defend against emerging contract manufacturers in Bangalore by accelerating FSSAI certification timelines for export-grade isolate production.
For New Entrants and Emerging Players: Pediatric nutrition formulators represent the most penetrable buyer archetype, with hypoallergenic protein fortification demand outpacing established supply from soy and dairy alternatives. Target EU cosmetic-grade isolate channels where REACH registration requirements have delayed Indian incumbent launches. Pursue co-manufacturing partnerships with established spray-drying facilities rather than greenfield capacity investment.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified agribusiness conglomerates seeking ancient grain platform expansion. Long-term viability hinges on processors demonstrating sustained FSSAI compliance and organic certification maintenance across multi-year contract cycles. Acquisition targets should show captive supply agreements rather than spot-market procurement dependence. Monitor EFSA health claim authorization timelines as inflection indicator for European demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Supply | Captive acreage in Maharashtra secures FSSAI-compliant raw material streams against monsoon volatility. |
| Continuous-Flow Extraction Technology Deployment | Alkaline-isoelectric hybrid systems at Bangalore R&D clusters compress isolate purity upgrade cycles. |
| Direct-Procurement Channel Establishment | Bilateral agreements with California sports nutrition brands displace distributor intermediaries and capture traceability premiums. |
| REACH Dossier Preparation Acceleration | Toxicology documentation investment unlocks Hamburg and Frankfurt cosmetic-grade isolate offtake. |
| Pediatric Nutrition Formulation Partnership | Hypoallergenic protein fortification collaborations with European infant food manufacturers open premium positioning. |
Research Methodology
Trade databases, FSSAI regulatory filings, and agricultural ministry harvest statistics formed the secondary backbone, supplemented by primary interviews with extraction technology specialists, sports nutrition procurement directors, Indian processing facility operators, and organic certification auditors. Bottom-up and top-down triangulation validated volume estimates across isolate, concentrate, and whole grain product tiers.
Bottom-up modeling anchored forecasts in individual processor capacity expansions and brand offtake commitments, while top-down analysis cross-checked against ancient grain protein substitution trends in dairy alternatives. Segmentation dimensions included product purity grade, end-use application, certification status, and regional regulatory cluster. CAGRs were derived from weighted capacity-addition timelines and buyer procurement intention surveys. Forecast inputs incorporated monsoon pattern variability and FDA GRAS determination pipeline status.
Revisions become necessary when FSSAI enforcement intensity shifts, EFSA health claim authorizations accelerate or stall, or container freight rate volatility disrupts Indian-European trade economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Aroma Ingredients Market
Ingredients
Encapsulated Salt Market
Ingredients
Omega Ingredients Market
Ingredients
Cocoa Market
Ingredients
Calendula Oil Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
North America Feed Yeast Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Low Calorie Oil Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Soybean Oil Market
Ingredients
Carrot Fiber Market
Ingredients
Egg Yolk Powder Market
Ingredients
Immunity Support Ingredients Market
Ingredients
Instant Starches Market