
 Lime Seed Oils Market | 2026-2036
Lime Seed Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Lime Seed Oils Market Foresight
Specialty ingredient distribution is fragmenting as regional distributors lose ground to direct procurement platforms serving mid-size cosmetics manufacturers. Cargill Corp leverages its agricultural origination network to secure lime seed supply chains across subtropical growing belts. Symrise AG anchors European flavor and fragrance demand through integrated botanical extraction capabilities. Young Living Essential Oils competes in the premium wellness channel with vertically controlled distillation and quality certification programs.
Lime seed oils comprise triglyceride-rich lipids cold-pressed from Citrus aurantiifolia seeds, typically yielding 20-35% oil content with elevated linoleic acid and antioxidant profiles for oxidative stability in topical and ingestible applications. Cold-pressed grades command premium positioning in clean-label cosmetics, while refined variants sustain volume throughput in mass-market food flavoring. Organic certification creates margin concentration in personal care supply chains, whereas aromatherapy applications occupy specialized wholesale channels with higher per-unit economics.
FDA food additive regulations and EPA pesticide residue limits govern US market access for lime seed oil imports, while REACH registration requirements in Europe mandate full toxicological dossiers for cosmetic-grade volumes. ISO 17025 laboratory accreditation increasingly determines supplier eligibility for pharmaceutical and nutraceutical contracts. Stakeholders must monitor evolving EU Green Deal bio-based content thresholds and calibrate sourcing strategies between certified organic and conventional supply tiers.
Market Dynamics
Specialty ingredient procurement is fragmenting as cosmetics formulators abandon traditional distribution tiers for direct sourcing platforms, compressing margin capture across midstream intermediaries while elevating supplier certification requirements.
Growth Catalysts
- EU Green Deal bio-based thresholds:Mandatory sustainable content benchmarks in European cosmetics are pulling cold-pressed organic grades into premium formulations, accelerating farm-to-formulator traceability investments.
- Aromatherapy channel expansion:Wellness retail networks in Germany and France are absorbing higher per-unit volumes of therapeutic-grade lime seed oils for diffuser and topical applications.
- Clean-label emollient substitution:Synthetic silicone replacement programs in California personal care manufacturing are redirecting formulation budgets toward plant-derived lipid alternatives with comparable oxidative stability profiles.
Market Restraints
- Subtropical supply concentration:Lime seed origination clusters in Mexico, Brazil, and Vietnam create weather-linked volume volatility and quality inconsistency across harvest cycles.
- REACH registration cost barriers:Full toxicological dossier requirements for cosmetic-grade volumes in Europe exclude small-batch artisanal producers from formal market access.
- Refined palm oil substitution:Mass-market food flavoring applications face persistent cost pressure from higher-volume tropical oil alternatives with established supply infrastructure.
Strategic Opportunities
- Indian ayurvedic export channel:Underpenetrated penetration of lime seed oil into traditional medicine formulations offers first-mover positioning ahead of BIS standard harmonization.
- Pharmaceutical lipid excipient certification:ISO 17025 laboratory accreditation unlocks contract manufacturing opportunities for oral drug delivery systems requiring oxidative-stable carrier oils.
- Direct-to-manufacturer platform scaling:Digital procurement infrastructure is collapsing traditional distributor tiers, enabling mid-size cosmetics producers to secure certified organic grades at reduced intermediation cost.
Industry Challenges
- Cold-press technician scarcity:Skilled operators for low-temperature extraction equipment are concentrated in established Mediterranean and Californian processing clusters, limiting geographic expansion of premium production capacity.
- Organic certification timeline compression:Multi-year conversion requirements for conventional orchards strain working capital for suppliers targeting EU and North American premium segments.
- Cross-border phytosanitary documentation:Seed oil shipments face inconsistent EPA pesticide residue documentation demands across US port-of-entry jurisdictions, creating customs clearance friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lime Seed Oils Market |
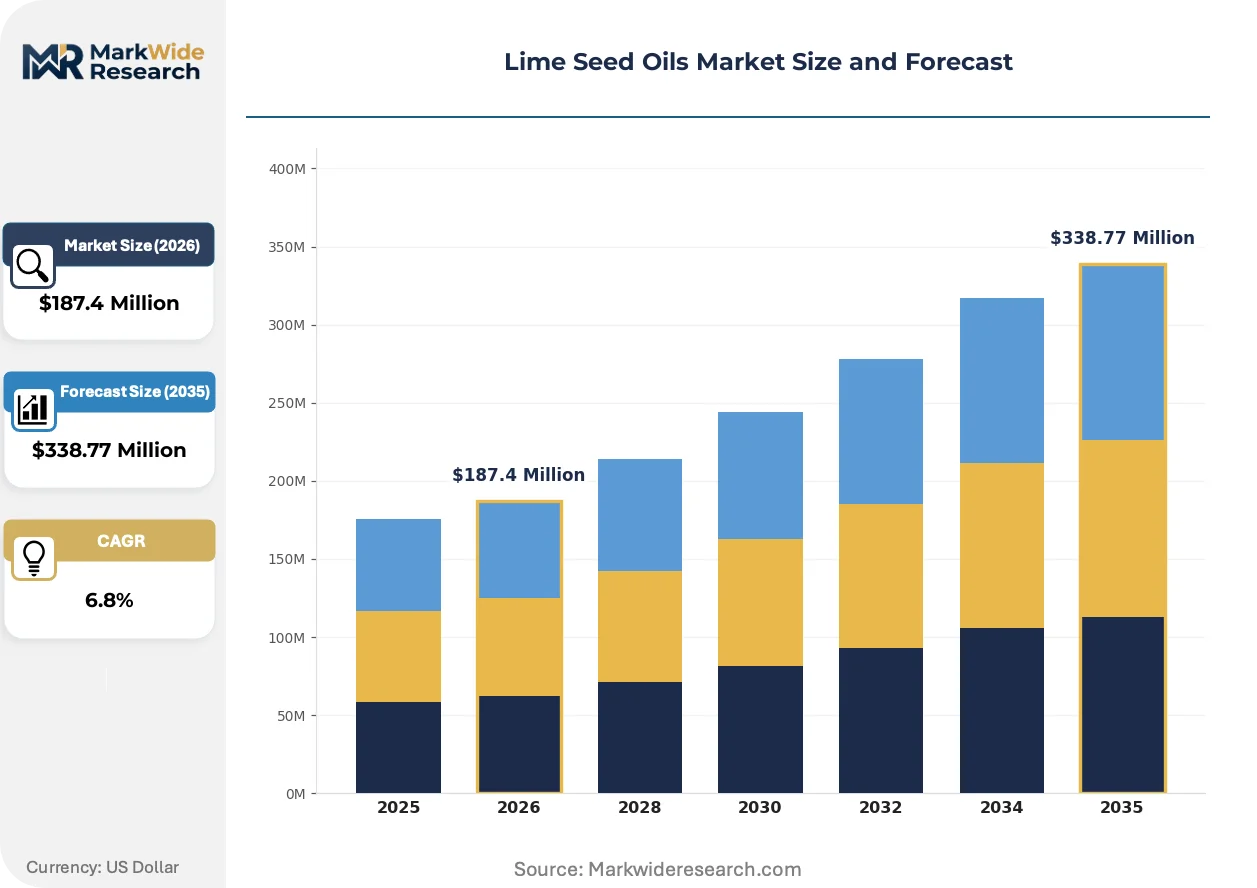
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold-Pressed, Refined, Essential, Organic Application: Cosmetics, Food Flavoring, Aromatherapy, Nutraceuticals End User: Personal Care, Food & Beverages, Pharmaceutical, Spa & Wellness Distribution Channel: Online Retail, Specialty Stores, Wholesale, Supermarkets |
| Companies Covered | Cargill Corp, Symrise AG, Young Living Essential Oils, Stan Chem International Limited, Phoenix Aromas & Essential Oils, Citromax Flavors, Ultra International, doTERRA International, Olam International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lime Seed Oils Market Shifts & Advancements
Digital traceability infrastructure and extraction technology refinements are compressing quality assurance timelines while regulatory frameworks in major consumption markets harden disclosure requirements for botanical ingredient provenance.
Supercritical CO2 extraction is virtualizing traditional cold-press capacity constraints by enabling precise temperature control that preserves heat-sensitive antioxidant compounds while accelerating throughput. German and French cosmetics contract manufacturers are adopting these systems to meet compressed delivery schedules for organic-certified formulations. The technology is virtualizing regional production bottlenecks by allowing temperate-climate facilities to process imported seed stock with tropical-equivalent quality retention.
REACH Annex XVII restrictions on residual solvent content in cosmetic-grade botanical extracts are forcing extraction technology upgrades across European supplier networks. The regulation mandates sub-ppm detection thresholds for hexane and petroleum ether residues, eliminating conventional refined oil pathways for premium personal care applications. German formulators are responding by qualifying suppliers with in-house supercritical capabilities or third-party ISO 17025 verification protocols.
Ingredient provenance verification has become a primary selection criterion for North American clean beauty brands, displacing price-based supplier rotation with multi-year contractual partnerships anchored to farm-level transparency. Direct platform procurement is consolidating purchase volumes among vertically integrated producers capable of blockchain-documented chain-of-custody reporting. California and New York-based formulators are driving this behavioral shift, embedding traceability requirements into RFP specifications ahead of anticipated FDA cosmetic labeling rulemakings.
Lime Seed Oils Market Segmentation
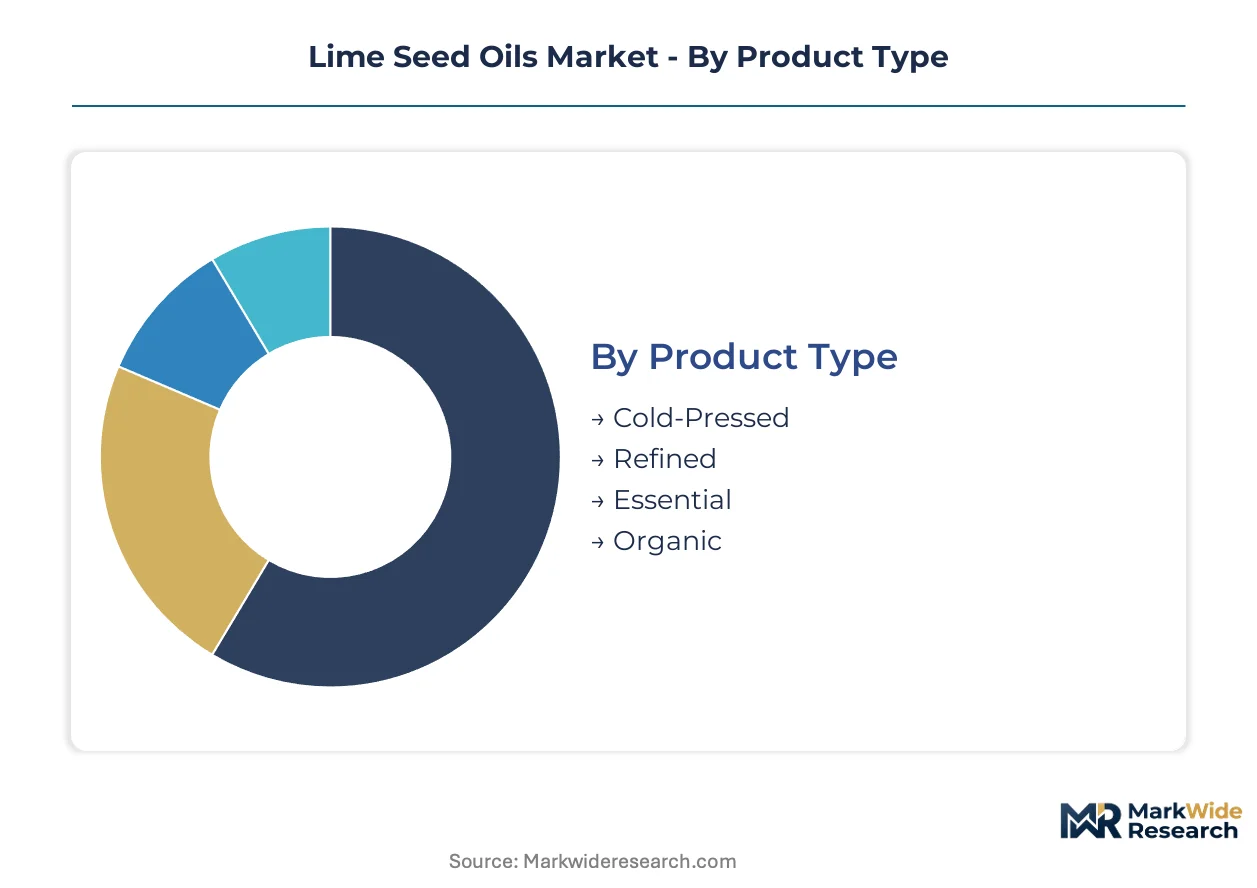
Lime seed oil procurement patterns diverge sharply across extraction methods and purity grades. Formulators select product types based on oxidative stability requirements, regulatory thresholds, and end-use certification demands.
Product Type:
Cold-pressed grades anchor premium personal care formulations, while refined variants sustain mass-market throughput.
- Cold-Pressed:Low-temperature extraction preserves linoleic acid concentrations and antioxidant activity for topical applications. California and German cosmetics manufacturers specify this grade for silicone-replacement emollient programs targeting clean-label positioning.
- Organic:Certified supply chains command margin concentration through farm-level traceability and EU Green Deal bio-based compliance. French and German aromatherapy channels absorb disproportionate volumes for therapeutic-grade applications.
- Refined:Bleached and deodorized oils meet FDA food additive specifications for commercial flavoring operations.
- Essential:Distilled aromatic fractions serve specialized wellness retail networks with elevated per-unit economics.
Established volume favors Refined; emerging adoption favors Organic.
Application:
End-use concentration varies by regulatory intensity and formulation complexity across consumption markets.
- Cosmetics:Natural emollient demand from North American and European formulators drives cold-pressed procurement for clean-label skincare. REACH Annex XVII solvent restrictions are eliminating conventional refined pathways for premium personal care.
- Aromatherapy:Therapeutic-grade specifications require supercritical CO2 extraction capabilities concentrated in German and French processing facilities.
- Food Flavoring:Mass-market applications face persistent substitution pressure from higher-volume tropical oils with established supply infrastructure.
- Nutraceuticals:ISO 17025 laboratory accreditation unlocks pharmaceutical lipid excipient contracts for oxidative-stable carrier oil applications.
Cosmetics captures the steepest expansion trajectory; Food Flavoring holds the largest installed base.
End User:
Customer procurement sophistication ranges from commodity spot purchasing to multi-year contractual partnerships with traceability requirements.
- Personal Care:Mid-size cosmetics manufacturers are bypassing traditional distributors for direct platform procurement of certified organic grades.
- Spa & Wellness:German and French wellness retail networks specify therapeutic-grade oils for diffuser and topical applications with elevated per-unit margins.
- Pharmaceutical:Oral drug delivery systems require oxidative-stable carrier oils with full toxicological dossiers for EMA compliance.
- Food & Beverages:Commercial flavoring operations prioritize cost-competitive refined grades with established FDA food additive clearance.
Personal Care leads platform-driven procurement transformation; Spa & Wellness delivers the highest margin realization.
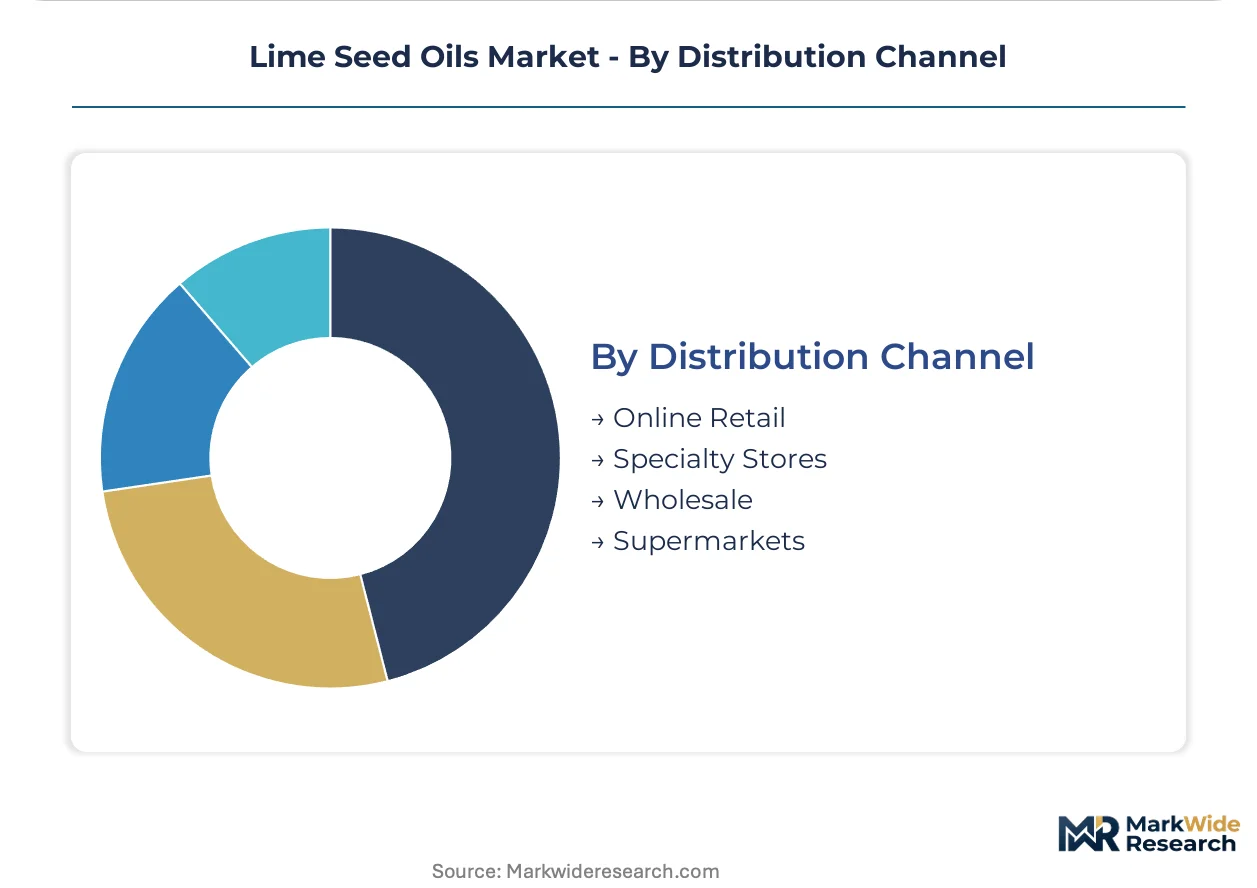
Distribution Channel:
Channel selection determines certification visibility and intermediation cost for suppliers targeting premium segments.
- Online Retail:Digital procurement infrastructure enables mid-size cosmetics producers to secure certified organic grades with blockchain-documented chain-of-custody reporting.
- Specialty Stores:Aromatherapy and wellness retail networks in Germany and France absorb higher per-unit volumes through curated therapeutic-grade assortments.
- Wholesale:Traditional intermediaries face margin compression as formulators abandon distribution tiers for direct sourcing platforms.
- Supermarkets:Mass-market food flavoring applications rely on established supply infrastructure for cost-competitive refined grades.
Wholesale retains the deepest volume footprint; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium cold-pressed grades command 40-60% price premiums in Germany and France versus mass-market refined throughput in Vietnam and Mexico, concentrating margin capture in European formulation clusters while Latin American and Southeast Asian suppliers absorb commodity price volatility.
United States
California personal care manufacturers drive cold-pressed procurement for silicone-replacement emollient programs targeting clean-label positioning. FDA cosmetic labeling rulemakings and EPA pesticide residue documentation demands at port-of-entry jurisdictions create compliance friction for imported seed oils. Los Angeles and New York Metro formulation clusters anchor premium organic grade absorption for mid-size cosmetics producers bypassing traditional distribution tiers.
Germany
German wellness retail networks absorb disproportionate volumes of therapeutic-grade oils for diffuser and topical applications with elevated per-unit margins. REACH Annex XVII restrictions on residual solvent content mandate sub-ppm detection thresholds for hexane and petroleum ether residues, eliminating conventional refined pathways for premium personal care. Bavarian and North Rhine-Westphalian cosmetics contract manufacturers adopt supercritical CO2 extraction systems to meet compressed delivery schedules for organic-certified formulations.
France
French aromatherapy channels specify supercritical CO2 extraction capabilities concentrated in established processing facilities. EU Green Deal bio-based content thresholds pull cold-pressed organic grades into premium formulations, accelerating farm-to-formulator traceability investments. Provence-Alpes-Côte d'Azur and Île-de-France formulation clusters anchor therapeutic-grade oil specification for wellness retail networks.
Vietnam
Vietnamese lime seed origination clusters face weather-linked volume volatility and quality inconsistency across harvest cycles, constraining reliable premium grade supply. The country's national agricultural regulator maintains phytosanitary documentation requirements for export-bound seed oil shipments. Mekong Delta processing facilities concentrate conventional grade throughput for mass-market food flavoring applications facing refined palm oil substitution pressure.
Mexico
Mexican subtropical growing belts anchor lime seed supply chain origination for North American market access. The country's national food safety regulator governs additive specifications for cross-border refined grade shipments. Veracruz and Chiapas agricultural clusters supply conventional seed stock to California and Texas processing facilities, though cold-press technician scarcity limits geographic expansion of premium production capacity.
Lime Seed Oils Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in extraction technology and farm-level origination. The vendor base stratifies across agricultural conglomerates with captive supply networks, integrated flavor and fragrance houses with botanical extraction capabilities, and vertically controlled wellness brands with quality certification programs. Two strategic archetypes dominate: scale-driven agricultural originators securing subtropical growing belt access, and premium-tier specialists with in-house supercritical processing and organic certification infrastructure. Competitive moves concentrate on direct-to-manufacturer platform scaling and extraction technology upgrades to meet REACH solvent restriction compliance.
Within the agricultural originator tier, Cargill Corp and Olam International represent scale-driven supply chain anchoring across subtropical growing belts in Mexico, Brazil, and Vietnam. Symrise AG exemplifies the integrated extraction archetype through European flavor and fragrance demand servicing with botanical processing capabilities. Young Living Essential Oils occupies a position in the premium wellness channel with vertically controlled distillation and quality certification programs. These three anchors illustrate the competitive divergence between commodity-grade volume throughput and certified organic premium positioning.
| Leading Market Players |
|---|
| Cargill Corp |
| Symrise AG |
| Young Living Essential Oils |
| Stan Chem International Limited |
| Phoenix Aromas & Essential Oils |
| Citromax Flavors |
| Ultra International |
| doTERRA International |
| Olam International |
| Others |
Supply & Pricing Matrix
REACH registration cost barriers determine both the premium spread between artisanal and certified grades and the geographic shape of supplier networks, compressing small-batch producers from formal European market access while concentrating margin capture among dossier-capable processors.
Pricing Analysis
The customization-premium spread separates configured-to-order organic certifications from spot-market conventional throughput. Three-tier pricing structure across premium, standard, and economy levels anchors on cold-pressed organic grades, refined food-grade volumes, and commodity flavoring inputs. Price differentiation hinges on EU Green Deal bio-based compliance and ISO 17025 laboratory accreditation. Cost compression in refined food-grade tiers intensifies because refined palm oil alternatives undercut lime seed positioning. Mass-market food flavoring buyers exhibit highest price sensitivity; German aromatherapy channels demonstrate lowest.
Supply Chain Analysis
Extended payment terms from European cosmetics formulators strain working capital for Vietnamese and Mexican originators, forcing supply-chain finance facility adoption among mid-tier processors. Geographic supply concentration centers on Mexico, Brazil, and Vietnam for seed origination, with German and Californian facilities anchoring premium extraction. Raw material dependencies include subtropical lime orchard output, cold-press equipment spares, and supercritical CO2 solvent supply. Single-source vulnerability runs through Mekong Delta harvest volatility. Distribution runs through direct-to-manufacturer platforms collapsing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct procurement platform adoption fragments established distribution hierarchies, creating entry niches for certified-organic specialists capable of farm-level traceability documentation.
For Market Incumbents: Harden supply chain origination through backward integration into Mexican and Brazilian subtropical growing belts before emerging agricultural conglomerates lock exclusive orchard contracts. Invest in supercritical CO2 extraction capacity to meet REACH Annex XVII solvent restrictions eliminating conventional refined pathways for premium personal care.
For New Entrants and Emerging Players: Indian ayurvedic export channels offer first-mover positioning ahead of BIS standard harmonization, with traditional medicine formulations absorbing therapeutic-grade volumes at elevated per-unit economics. Target pharmaceutical lipid excipient certification through ISO 17025 laboratory accreditation to unlock contract manufacturing for oral drug delivery systems. Pursue digital platform partnerships with mid-size California cosmetics producers bypassing traditional distributors.
For Investors and Strategic Acquirers: Supercritical-equipped organic processors with captive supply networks represent the optimal acquisition archetype, combining extraction technology differentiation with farm-level traceability infrastructure. Long-term viability rests on EU Green Deal bio-based threshold enforcement and FDA cosmetic labeling rulemakings embedding provenance requirements into procurement specifications. Monitor REACH registration timeline compression as inflection indicator for artisanal producer exclusion accelerating consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Subtropical Orchards | Cargill Corp leverages agricultural origination networks to secure Mexican and Brazilian lime seed supply chains. |
| Supercritical CO2 Extraction Upgrade | German cosmetics contract manufacturers adopt these systems to meet REACH Annex XVII solvent restrictions. |
| ISO 17025 Laboratory Accreditation | Unlocks pharmaceutical lipid excipient contracts for oxidative-stable carrier oil applications. |
| Direct-to-Manufacturer Platform Scaling | Mid-size California cosmetics producers secure certified organic grades at reduced intermediation cost. |
| EU Organic Certification Investment | French and German aromatherapy channels absorb disproportionate volumes for therapeutic-grade applications. |
Research Methodology
A spread of perspectives from cosmetics formulators, cold-press equipment operators, organic certification auditors, and pharmaceutical contract manufacturers converged on the working assumptions underpinning volume and value estimates. Primary interviews with extraction technology specialists and farm-level suppliers combined with secondary validation from ECHA registration databases, FDA food additive filings, EU Green Deal policy documents, and customs trade records. Bottom-up orchard yield modeling and top-down personal care formulation demand analysis provided triangulation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning extraction method, certification grade, end-use application, and regional regulatory cluster. CAGRs derived from compounded annual trajectory analysis against baseline volume estimates. Industry-specific forecast inputs included REACH registration cost escalation curves and silicone-replacement program adoption rates in California personal care manufacturing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by agricultural conglomerates into captive orchard ownership would shift outcomes beyond modeled parameters. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
US Choline Bitartrate Market
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
Pea Starch Market
Ingredients
North America Soybean Oil Market
Ingredients
Starch Market
Ingredients
North America Agar Market
Ingredients
Casein Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
Tomato Concentrate Market
Ingredients
Edible Fiber Market
Ingredients
Interesterified Fats Market
Ingredients
Coconut Cream Powder Market
Ingredients
Pork Skin Gelatin Market
Ingredients
Corn Starch Market
Ingredients
Specialty Malt Market