
 Specialty Fats and Oils Market | 2026-2036
Specialty Fats and Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Fats and Oils Market Analysis
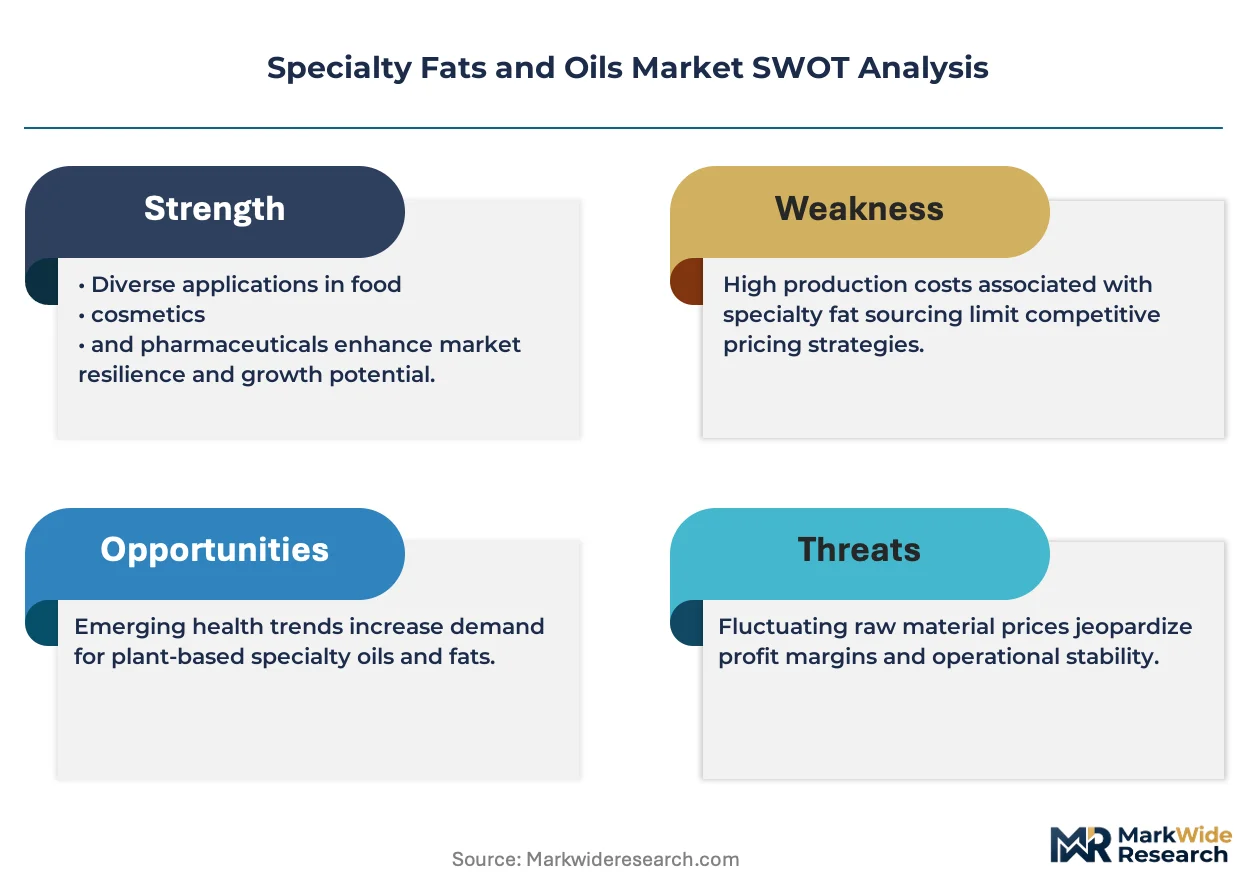
EU Deforestation Regulation is consolidating compliance burdens across European supply chains, forcing smaller traders to exit or sell. Cargill Incorporated leverages its integrated crush-refine-distribute footprint to absorb traceability costs directly. Wilmar International Limited anchors Southeast Asian palm oil origination through controlled plantation and port assets. Bunge Limited competes in South American soybean oil specialization with backward integration into crushing.
Specialty fats and oils comprise refined, fractionated, or interesterified lipid formulations engineered for specific melting profiles, oxidative stability, and mouthfeel in processed foods. Interesterification rearranges fatty acid positions on triglyceride backbones to tailor functional properties without hydrogenation. Cocoa butter equivalents within the Product Type category command premium positioning due to cocoa price volatility and confectionery demand. Bakery and Confectionery applications within the Application dimension concentrate volume, while Snacks represents a faster-growing outlet for high-stability frying mediums.
FDA nutrition labeling rules and EFSA novel food assessments shape product formulation pathways on opposite sides of the Atlantic. REACH chemical registration and EU Green Deal due diligence requirements compound compliance complexity for imported palm and coconut derivatives. Stakeholders must monitor regulatory divergence between trans-fat limits and sustainability certification mandates to preserve market access across jurisdictions.
Market Dynamics
EU Deforestation Regulation enforcement is consolidating compliance burdens across specialty fats supply chains, forcing upstream refiners to absorb traceability costs or exit European procurement programs entirely.
Growth Catalysts
- Clean-label bakery expansion:Southeast Asian bakery chains are mandating non-hydrogenated shortenings and interesterified alternatives, pulling formulation demand toward premium lipid fractions.
- REACH chemical registration pathways:Streamlined novel lipid assessments under ECHA guidance are accelerating product approval timelines for European food manufacturers.
- Cocoa butter equivalent substitution:Confectionery producers facing cocoa price volatility are reformulating with shea and palm mid-fractions to stabilize input costs.
Market Restraints
- Crude palm oil price volatility:Weather-driven supply swings in Indonesia and Malaysia transmit directly to specialty fraction costs, compressing blender margins.
- Upstream refining concentration:Over 70% of global crude palm oil refining capacity sits within Indonesian and Malaysian state-linked processors, creating single-origin dependency.
- Trans-fat labeling thresholds:FDA and EFSA divergent definitions of "zero trans-fat" complicate unified product platform development for multinational food brands.
Strategic Opportunities
- Indian bakery modernization:Organized retail expansion in Mumbai and Bangalore is creating first-mover advantage for structured lipid suppliers offering pre-mix solutions.
- EU Green Deal due diligence:Mandatory sustainability certification for palm-derived inputs creates premium positioning for RSPO-segregated supply chains.
- High-oleic sunflower convergence:Breeding advances combining oxidative stability with clean-label positioning are opening snack frying applications previously dominated by palm olein.
Industry Challenges
- Interesterification technician scarcity:Food lipid processing expertise concentrates among retiring specialists in European and Southeast Asian refineries, constraining capacity expansion.
- Multi-jurisdiction certification timelines:Simultaneous FDA GRAS self-affirmation, EFSA novel food dossier preparation, and BIS FSSAI alignment extend product launch cycles.
- Legacy hydrogenation asset stranding:Trans-fat phase-out deadlines in multiple markets leave installed hardstock capacity underutilized, burdening balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Fats and Oils Market |
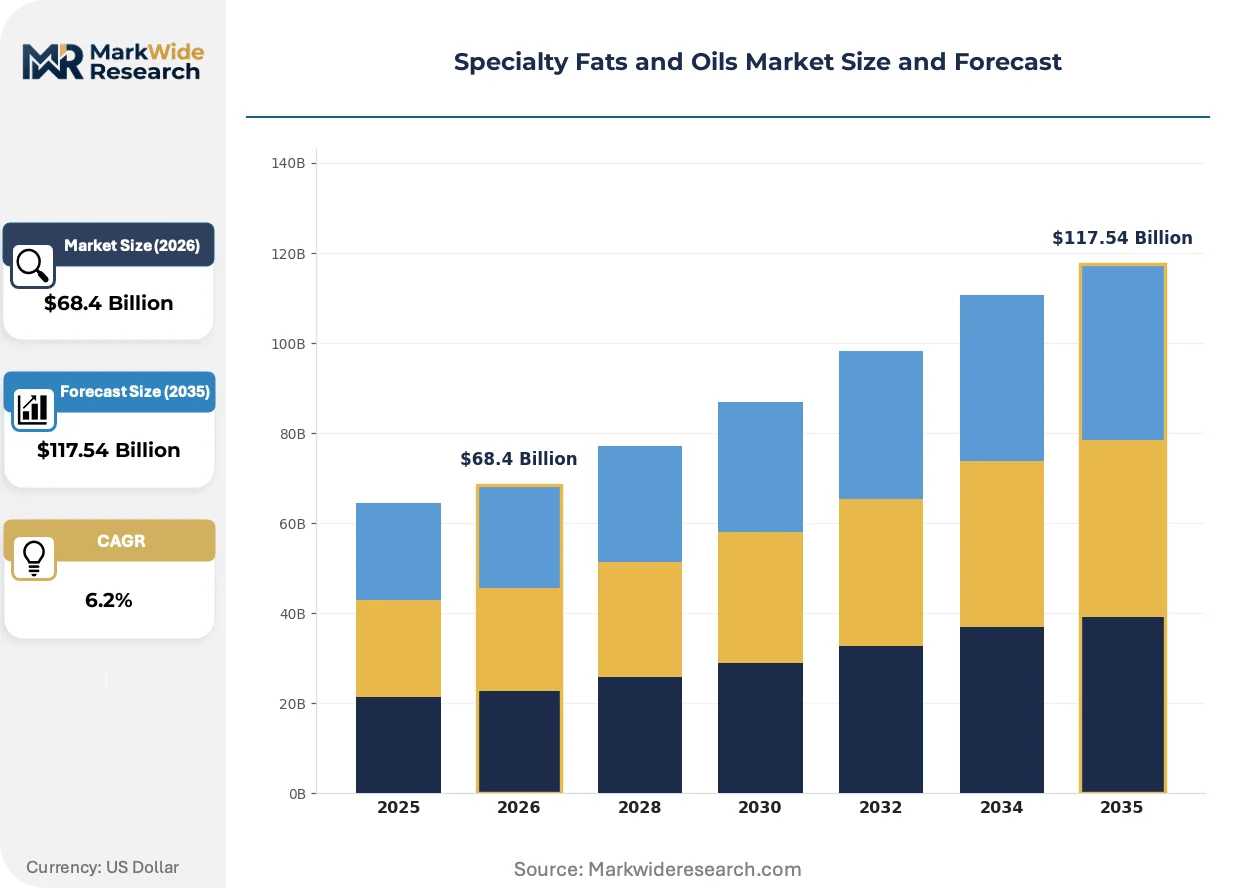
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Margarine, Shortening, Cocoa Butter Application: Bakery, Confectionery, Snacks, Dairy Products Source: Vegetable Oils, Animal Fats, Palm Oil, Coconut Oil Form: Liquid, Semi-Solid, Solid, Powdered |
| Companies Covered | Cargill Incorporated, Wilmar International Limited, Bunge Limited, Archer Daniels Midland, IOI Corporation Berhad, AAK AB, FUJI OIL CO., LTD., Mewah Group, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Fats and Oils Market Emerging Trajectories
Enzymatic interesterification is displacing chemical processing as the dominant restructuring technology, while regulatory divergence between trans-fat limits and sustainability mandates forces parallel formulation tracks.
Enzymatic interesterification is consolidating market share among premium confectionery and bakery fat producers. European and Japanese chocolate manufacturers have adopted lipase-catalyzed processes for cocoa butter equivalent production, achieving tighter triglyceride specificity than chemical routes. The technology is consolidating high-margin product categories under suppliers with captive enzyme production or tolling partnerships.
REACH registration requirements for novel food lipids are tightening dossier standards for imported palm and coconut derivatives. ECHA's expanded substance evaluation criteria now demand full supply chain mass-balance documentation for fractionated products. European importers are responding by pre-qualifying Southeast Asian refiners with certified sustainability credentials before contract negotiation.
Direct refiner-to-bakery procurement contracts are compressing traditional distributor layers in Southeast Asian markets. Malaysian and Indonesian bakery chains with 50+ outlet networks now negotiate annual volume agreements with Wilmar and Cargill refining divisions, bypassing regional traders. This pattern is most visible in Jakarta and Bangkok, where consolidated retail baking is displacing fragmented artisanal supply.
Specialty Fats and Oils Market Segmentation
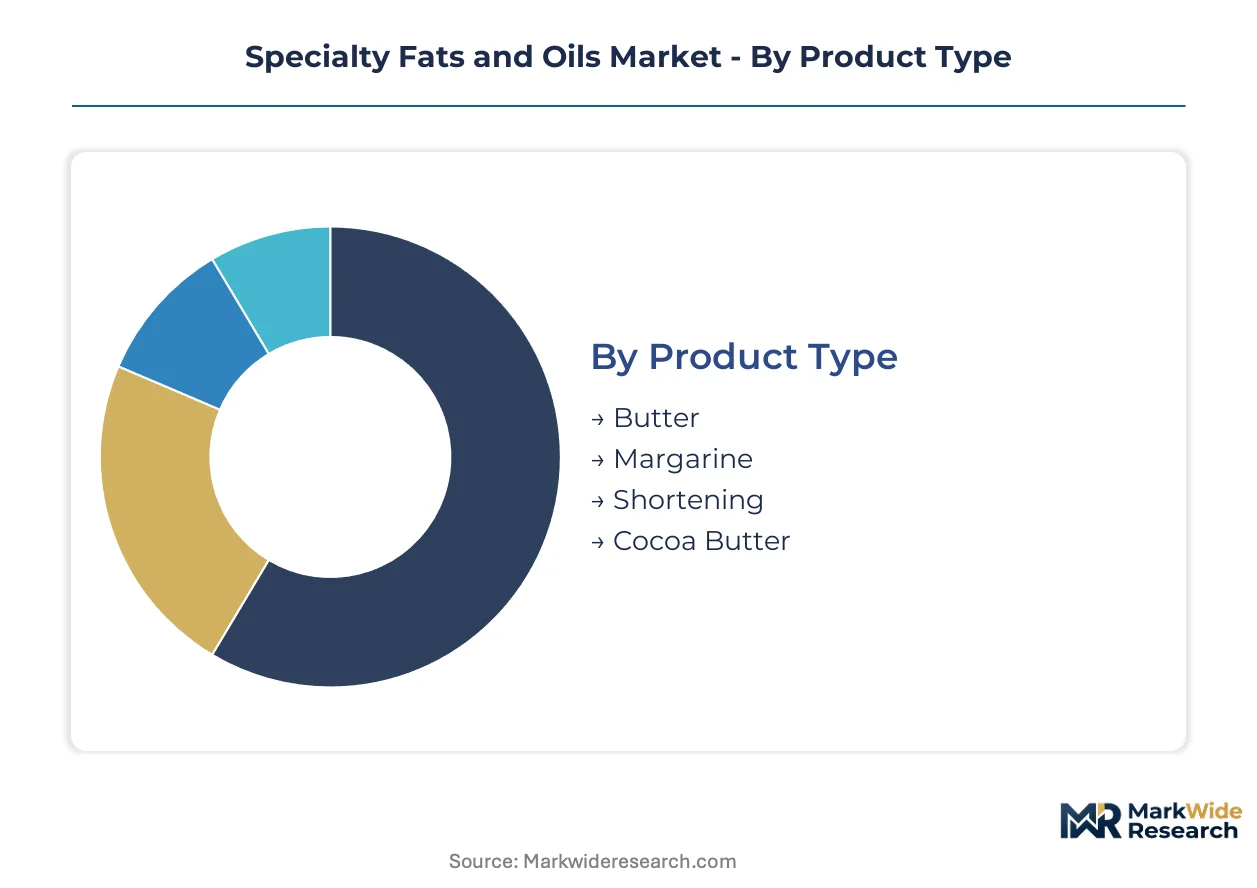
Specialty fats and oils segment along functional, compositional, and application dimensions that determine melting behavior, oxidative stability, and regulatory compliance pathways. Each category reflects distinct upgrade cycles driven by clean-label reformulation, trans-fat phase-out mandates, and sustainability certification requirements.
Product Type:
Replacement cycles accelerate where hydrogenated legacy formulations face regulatory sunset dates and bakery chains demand performance-matched alternatives.
- Shortening:Interesterified and fractionated palm-based shortenings deliver tailored solid fat indices for laminated doughs and cake batters without partial hydrogenation. Southeast Asian bakery chains in Jakarta and Bangkok are mandating non-hydrogenated shortenings for clean-label procurement programs, pulling volume toward premium lipid fractions.
- Cocoa Butter:Cocoa butter equivalents and replacers combine shea stearin with palm mid-fractions to mimic polymorphic crystallization for chocolate tempering. Confectionery producers facing cocoa price volatility are reformulating with structured lipids to stabilize input costs while maintaining snap and gloss.
- Butter:Anhydrous milk fat concentrates serve premium bakery and confectionery applications requiring authentic dairy flavor profiles.
- Margarine:Table and industrial margarines blend vegetable oils with emulsifier systems for spreadability and creaming functionality.
Volume placements concentrate in Shortening; the faster expansion belongs to Cocoa Butter.
Application:
Cost tier differentiation separates commodity frying operations from premium confectionery and clean-label bakery procurement.
- Bakery:Laminated pastries, cakes, and bread formulations demand plastic fat ranges from 15°C to 35°C for dough handling and oven spring. Organized retail expansion in Mumbai and Bangalore is creating first-mover advantage for structured lipid suppliers offering pre-mix solutions to modernizing Indian bakery chains.
- Confectionery:Chocolate, coatings, and fillings require precise melting profiles and polymorphic stability for shelf appeal and mouthfeel.
- Snacks:High-oleic sunflower and palm olein fractions supply extended fry life for potato chips and extruded snacks.
- Dairy Products:Coffee whiteners, ice cream, and filled milk applications utilize vegetable fat blends for cost optimization and texture control.
Margin capture is strongest in Confectionery; steepest volume gains are occurring in Snacks.
Source:
Supply concentration shapes sourcing risk profiles and sustainability certification requirements across upstream origination.
- Palm Oil:Fractionated palm oil, palm kernel oil, and their derivatives provide cost-effective solid fat functionality through natural saturation and crystallization behavior. Indonesian and Malaysian state-linked processors control over 70% of global crude palm oil refining capacity, creating single-origin dependency that EU Green Deal due diligence requirements are forcing importers to address through RSPO-segregated supply chains.
- Vegetable Oils:Soybean, sunflower, rapeseed, and high-oleic variants offer liquid oil functionality with varying oxidative stability profiles.
- Coconut Oil:Lauric-rich fractions deliver sharp melting characteristics for confectionery and cosmetic applications.
- Animal Fats:Tallow and lard serve niche applications in traditional bakery and pet food formulations.
Procurement scale concentrates in Palm Oil; clean-label positioning is expanding fastest in Vegetable Oils.
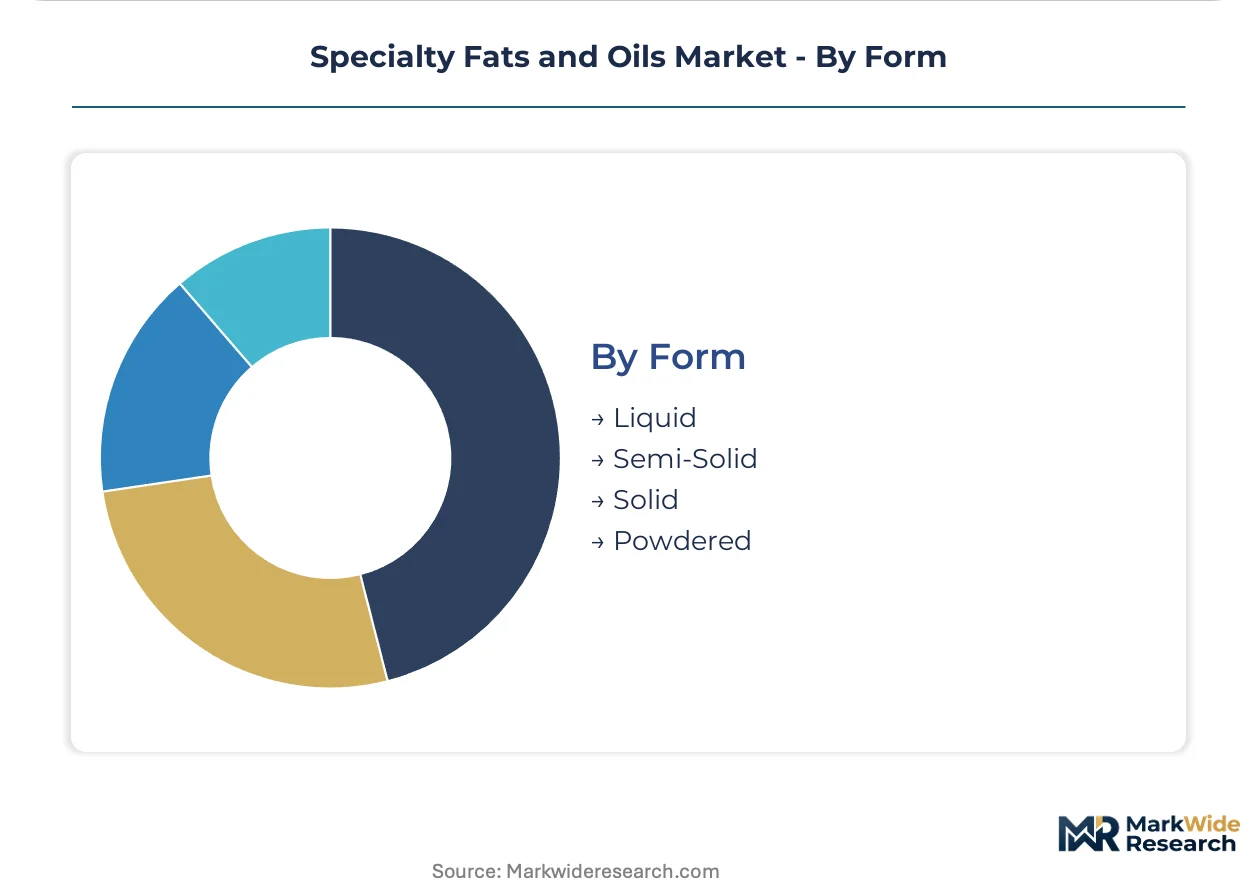
Form:
Customer type and handling infrastructure determine form selection across industrial, foodservice, and retail channels.
- Semi-Solid:Plasticized shortenings and margarines in tub or block form provide ready-to-use functionality for artisanal and industrial bakers. Direct refiner-to-bakery procurement contracts in Malaysian and Indonesian markets are compressing distributor layers, with 50+ outlet chains negotiating annual volume agreements that specify semi-solid delivery formats.
- Liquid:Pourable oils and fluid shortenings suit high-volume frying and spray applications.
- Solid:Fully saturated flakes and beads enable precise dosing in automated manufacturing lines.
- Powdered:Encapsulated and spray-dried fats serve dry mix, beverage, and convenience food applications.
Industrial throughput favors Semi-Solid; Powdered formats are climbing the fastest in convenience food channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for specialty fats and oils concentrates in confectionery and bakery manufacturing clusters across four major economies. Each market exhibits distinct regulatory pressures and supply chain configurations that shape procurement patterns and formulation requirements.
United States
Chocolate manufacturers and industrial bakeries in Chicago and Pennsylvania drive formulation demand for cocoa butter equivalents and interesterified shortenings. FDA nutrition labeling rules enforce trans-fat disclosure thresholds that compel reformulation away from partial hydrogenation. The Midwest dairy-bakery corridor spanning Wisconsin and Illinois anchors domestic shortening consumption for laminated dough applications.
Germany
Confectionery producers in Cologne and Hamburg prioritize shea-based cocoa butter alternatives to hedge against cocoa price volatility. EFSA novel food assessments and REACH chemical registration requirements govern lipid ingredient approvals for European distribution. The North Rhine-Westphalia industrial belt concentrates refining and blending capacity serving Central European bakery chains.
Indonesia
State-linked processors control upstream crude palm oil refining capacity that feeds both domestic bakery expansion and export fractionation. EU Green Deal due diligence requirements are forcing RSPO-segregated supply chain investments for European market access. Jakarta and Surabaya host direct refiner-to-bakery procurement contracts that bypass traditional distributor layers.
India
Organized retail expansion in Mumbai and Bangalore creates first-mover opportunity for structured lipid suppliers offering pre-mix solutions to modernizing bakery chains. FSSAI alignment requirements extend product launch timelines for multinational ingredient entrants. The Maharashtra-Gujarat industrial corridor concentrates domestic margarine and shortening manufacturing for quick-service restaurant supply.
Japan
Premium chocolate manufacturers in Tokyo and Osaka have adopted enzymatic interesterification for cocoa butter equivalent production requiring tight triglyceride specificity. METI industrial standards and PMDA food additive assessments shape lipid processing technology adoption. The Kanto region anchors high-margin confectionery fat consumption for domestic and export confectionery markets.
Specialty Fats and Oils Market Vendor Landscape
Southeast Asian plantation-integrated processors anchor one tier; European and North American formulation specialists hold differentiated positions in premium confectionery and clean-label bakery segments. Market structure exhibits dual consolidation: upstream crude palm oil refining concentrates among Indonesian and Malaysian state-linked entities, while downstream specialty fat blending fragments across regional tolling networks. Three archetypes dominate: plantation-integrated refiners with captive origination, toll processors with enzymatic restructuring capabilities, and brand-house formulators with direct bakery relationships. Competitive intensity centers on sustainability certification procurement and enzymatic interesterification capacity expansion.
Within the plantation-integrated tier, Wilmar International Limited and IOI Corporation Berhad represent upstream origination archetypes with controlled port and refining assets. Cargill Incorporated exemplifies the crush-refine-distribute integrated model spanning multiple oilseed origins. Among European specialists, AAK AB occupies a position in shea and palm fraction value-added processing for confectionery applications. Fuji Oil Co., Ltd. anchors Japanese enzymatic processing expertise for premium chocolate fat formulations. These named entities illustrate strategic positioning across origination, processing technology, and geographic market access rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Wilmar International Limited |
| Bunge Limited |
| Archer Daniels Midland |
| IOI Corporation Berhad |
| AAK AB |
| FUJI OIL CO., LTD. |
| Mewah Group |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Sovereign-linked plantation groups in Indonesia and Malaysia anchor upstream origination, compressing margin capture for independent refiners while enforcing long-term offtake discipline across European and Asian procurement programs. Their state-backed financing structures absorb traceability investment burdens that private toll processors cannot shoulder, concentrating pricing power among integrated origination-refining platforms.
Pricing Analysis
Short lead-time premiums for RSPO-segregated palm mid-fractions run 15-25% above spot bulk olein, reflecting EU Green Deal compliance urgency and constrained certified supply pools. Three-tier pricing structure across premium, standard, and economy levels separates mass-balance certified shipments from segregated identity-preserved and uncertified commodity grades. Cost compression in standard-tier bakery shortenings is intensifying because Indonesian state processors are absorbing margin pressure to defend European market share. Small Southeast Asian bakery chains exhibit highest price sensitivity, while premium chocolate manufacturers in Japan and Germany show lowest elasticity due to formulation lock-in costs.
Supply Chain Analysis
Dual-sourcing mandates from EU-based confectionery houses now require simultaneous qualification of Indonesian and Malaysian refiners with segregated RSPO certification, eliminating single-origin dependency. Geographic concentration centers on Indonesia, Malaysia, and India for crude palm oil refining and fractionation capacity. Raw material flows draw from crude palm oil, shea nuts, and high-oleic sunflower seed as primary lipid feedstocks. Single-origin vulnerability persists where over 70% of global crude palm oil refining rests with Indonesian and Malaysian state-linked processors. Distribution runs through direct refiner-to-bakery annual volume agreements in Jakarta and Bangkok, bypassing traditional regional trader networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Deforestation Regulation enforcement is accelerating consolidation, forcing smaller traders without traceability infrastructure to exit or sell to integrated plantation-refining platforms capable of absorbing compliance costs.
For Market Incumbents: Acquire enzymatic interesterification capacity and captive lipase production to lock in premium confectionery supply relationships before Japanese and European specialists expand tolling footprints. Backward integration into shea fractionation in West Africa hedges against cocoa butter equivalent input volatility. Defend margin position by pre-qualifying Southeast Asian refiners with RSPO-segregated credentials before contract negotiation windows close. For New Entrants and Emerging Players: Enzymatic restructuring technology offers entry wedge into premium chocolate fat segments where chemical processing incumbents lack triglyceride specificity capabilities. Target organized retail bakery modernization in Mumbai and Bangalore with pre-mix shortening solutions tailored to Indian quick-service restaurant specifications. Partner with Malaysian port-integrated refiners for toll processing arrangements that bypass upstream plantation ownership requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Southeast Asian toll processors with enzymatic capacity and stranded hydrogenation assets in secondary European locations. Five-to-ten-year viability hinges on RSPO certification penetration rates and trans-fat phase-out completion timelines across major import jurisdictions. Watch for inflection where EU customs authorities begin rejecting non-compliant palm derivative shipments at Rotterdam and Hamburg entry points.| Strategic Initiative | Industry Significance |
|---|---|
| RSPO-Segregated Supply Chain Investment | EU Green Deal due diligence mandates create premium positioning for certified palm derivative suppliers. |
| Enzymatic Interesterification Capacity Expansion | Lipase-catalyzed processes displace chemical routes in cocoa butter equivalent production for Japanese chocolate manufacturers. |
| Direct Refiner-to-Bakery Procurement Contracts | Malaysian and Indonesian bakery chains with 50+ outlets now negotiate annual volume agreements bypassing distributor layers. |
| Shea Fractionation Backward Integration | West African shea stearin sourcing hedges confectionery input costs against cocoa price volatility. |
| High-Oleic Sunflower Breeding Partnerships | Oxidative stability advances open snack frying applications previously dominated by palm olein fractions. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this specialty fats and oils assessment, cross-referenced with structured interviews across refinery operations managers, bakery chain procurement directors, confectionery formulation technologists, and sustainability certification auditors. Primary fieldwork combined plant-level capacity verification in Indonesian and Malaysian processing clusters with downstream demand validation from European and Japanese chocolate manufacturers. Secondary sources included RSPO certification databases, ECHA REACH registration dossiers, FDA GRAS notification filings, and FSSAI product approval records. Bottom-up volume modeling triangulated against top-down value estimates from trade flow analysis.
Granularity-level modeling operated at product type, application, source origin, and geographic market dimensions, with enzymatic versus chemical processing technology treated as a cross-cutting segmentation layer. CAGRs derived from year-over-year growth rate averaging across the projection horizon, calibrated to historical volume trajectories in bakery and confectionery end-use categories. Forecast inputs incorporated RSPO certification adoption curves, trans-fat regulatory phase-out schedules, and crude palm oil price volatility assumptions.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts, plantation disease outbreaks, and breakthrough synthetic lipid technologies. Forecasts reflect documented assumptions about regulatory enforcement consistency and certification scheme integrity. Deviation in EU Deforestation Regulation implementation timelines or Indonesian export levy structures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Roasted Grain Ingredients Market
Ingredients
Savory Ingredients Market
Ingredients
Fluid Lecithin Market
Ingredients
Phytosterols Market
Ingredients
Home Baking Ingredients Market
Ingredients
Potato Starch Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
Bleached Flour Market
Ingredients
Omega 9 Market
Ingredients
United States Avocado Oil Market
Ingredients
Malted Barley Flour Market
Ingredients
Psyllium Husk Powder Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Algae-Based Ingredients Market
Ingredients
All Purpose Flour Market
Ingredients
Sunflower Oil Market