
 White Wheat Malt Market | 2026-2036
White Wheat Malt Market Size, Share, and Industry Trends Forecast 2026-2036
White Wheat Malt Market Analytics
European malting cooperatives is broadening their specialty wheat programs to serve premium brewing contracts. Simpsons Malt Limited leverages its UK heritage to anchor supply relationships with craft distillers seeking traceable grain. Briess Malt & Ingredients Co. sustains its North American footprint through dedicated wheat malting lines and technical service teams. Viking Malt competes across Nordic and Baltic territories with consistent protein specifications and cold-chain logistics.
White wheat malt consists of germinated and kilned wheat grains with enzymatic activity typically measured in degrees Lintner, supplying fermentable sugars and body to finished beverages without the husk material found in barley. The kilning regimen determines color development, with lighter curing preserving the delicate bread-crust aromatics prized in German-style Weissbier. Base Malt commands the largest volume position as the foundational grist component for wheat beer styles, while Specialty Malt captures margin pools through roasted and caramelized variants that command premium pricing from experimental craft brewers. Adjunct Malt serves distilling clients seeking neutral fermentable substrates, with Food Manufacturers representing an emerging outlet for malted wheat in artisan bread formulations.
The EU Green Deal and REACH frameworks govern agricultural input traceability and chemical residue limits across European malting supply chains, directly influencing supplier qualification protocols for breweries exporting into the single market. The FDA and USDA oversee grain safety and organic labeling claims in the United States, creating parallel compliance tracks for maltsters serving transatlantic customers. Stakeholders must monitor how carbon accounting rules reshape sourcing economics and whether regional brewing traditions can sustain premium positioning against alternative grain spirits and hop-forward styles.
Market Dynamics
The EU Green Deal's carbon accounting mandates are restructuring malting economics, forcing wheat malt suppliers to document farm-level emissions and kilning energy use while craft brewers demand verified sustainability credentials alongside enzymatic specifications.
Growth Catalysts
- REACH chemical traceability:European malting cooperatives now qualify for premium brewing contracts by documenting input residue limits, creating competitive separation from non-compliant imports.
- Weissbier portfolio expansion:Craft breweries across Bavaria, Belgium, and Wisconsin are adding dedicated wheat beer lines, pulling specialty white wheat malt volumes into new production facilities.
- Distilling adjunct demand:Neutral-flavor white wheat malt is displacing corn in premium vodka mash bills as distillers seek traceable, gluten-removed grain substrates for clean-label positioning.
Market Restraints
- Protein specification volatility:Wheat protein content swings with annual growing conditions, forcing malsters to blend across crop years and compressing margin predictability.
- Single-region sourcing concentration:Premium white wheat malting varieties remain concentrated in Central European breeding programs, exposing buyers to climate and currency risk.
- Hop-forward style displacement:Hazy IPAs and West Coast pale ales are capturing tap handles from traditional wheat beers in North American craft markets.
Strategic Opportunities
- Artisan bread ingredient pivot:Food manufacturers in France and Italy are sourcing malted wheat flour for sourdough formulations, opening non-beverage revenue streams.
- Organic certification premium:USDA organic and EU organic labels command pricing separation in specialty brewing, rewarding early conversion of malting wheat acreage.
- Cold-chain logistics integration:Nordic maltsters are building temperature-controlled distribution networks to preserve enzymatic stability for remote craft distilleries.
Industry Challenges
- Kilning energy retrofit costs:Natural gas and electric kiln conversions require seven-figure capital outlays that strain mid-cap malting operations.
- Master maltster talent scarcity:Wheat-specific kilning expertise—distinct from barley—remains concentrated among aging specialists in traditional European malting houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Wheat Malt Market |
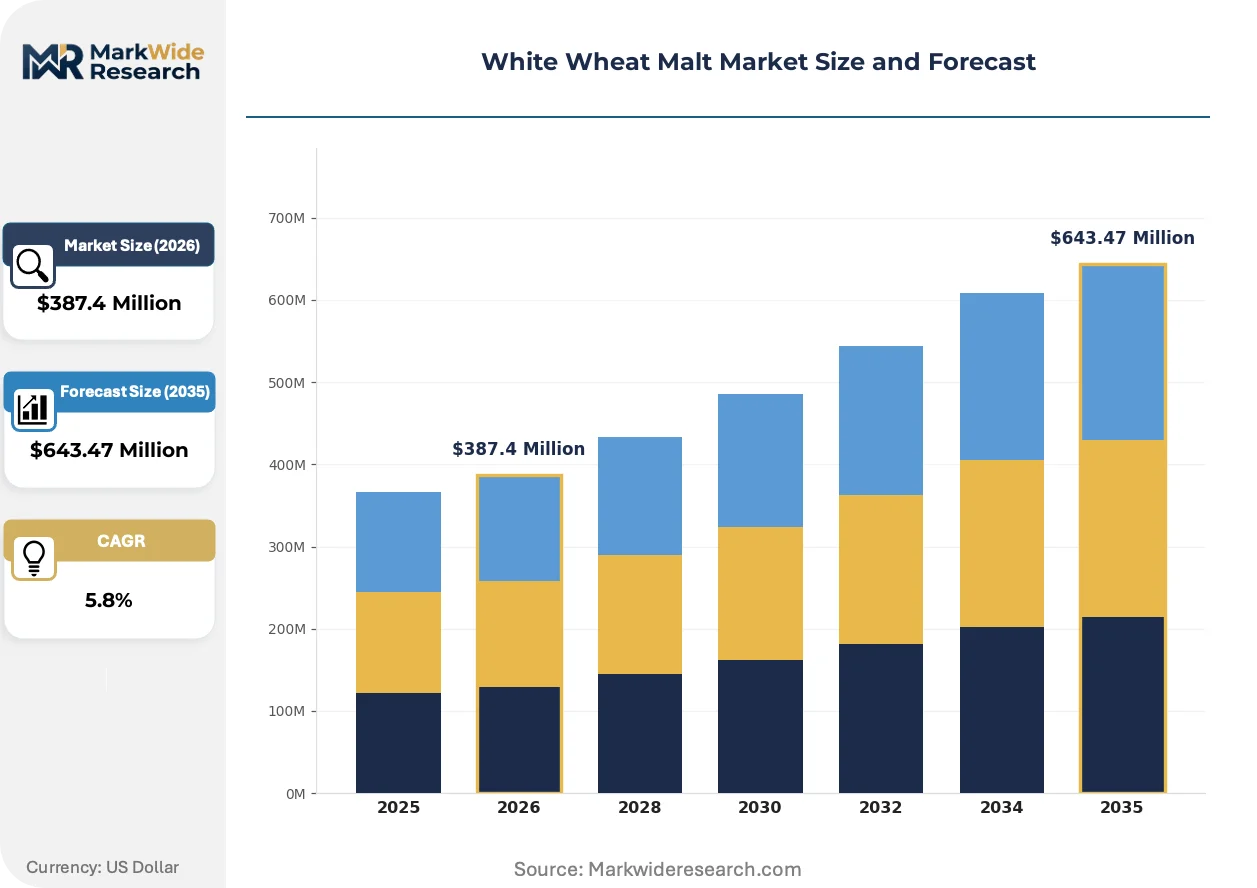
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $643.47 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Malt, Specialty Malt, Adjunct Malt, Caramel Malt Application: Brewing, Distilling, Baking, Food Products End User: Craft Breweries, Commercial Breweries, Bakeries, Food Manufacturers Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Cargill Incorporated, Simpsons Malt Limited, Briess Malt & Ingredients Co., Gladfield Malt, Great Western Malting, Viking Malt, MaltEurope, Malteurop, Rahr Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Wheat Malt Market Evolving Landscape
Digital traceability platforms and precision kilning controls are converging to reshape how wheat malt quality is verified and priced, while sustainability metrics migrate from marketing claims to contractual specifications.
Precision kilning automation is decentralizing quality control away from centralized laboratory testing. Craft breweries in Colorado and Oregon now receive real-time moisture and color data via IoT sensors embedded in bulk malt shipments. This transparency is compressing the traditional specification-negotiation cycle and enabling direct farmer-to-brewer contracting.
REACH substance authorization updates are tightening residue limits for pesticides used on malting wheat across European supply chains. Malting cooperatives in Germany and Belgium are responding by mandating farm-level integrated pest management certification from their contracted growers. The compliance burden falls heaviest on smaller wheat farms lacking agronomic advisory support.
Direct contracting between craft distillers and specialty malters is displacing traditional distributor-mediated procurement in North American markets. Small-batch whiskey producers in Kentucky and Tennessee now specify wheat variety, protein range, and kilning curve in purchase agreements. This disintermediation is most pronounced among distilleries producing estate-labeled spirits requiring documented grain provenance.
White Wheat Malt Market Segmentation
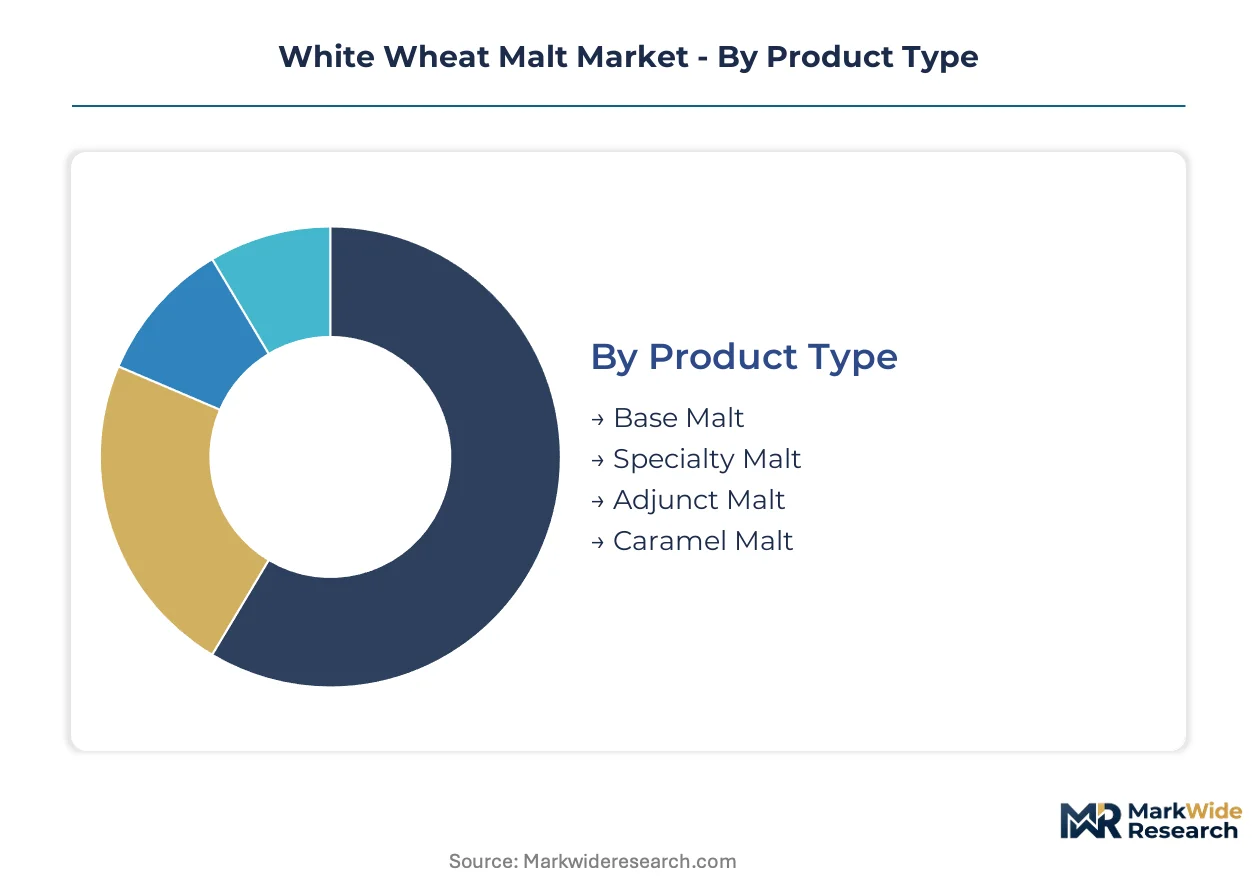
White wheat malt buyers segment procurement by enzymatic performance, kilning intensity, and end-use specifications. Distinct quality tiers command pricing separation based on protein stability, color development, and traceability documentation. Understanding these divides reveals where margin pools concentrate and which supply relationships offer defensive positioning.
Product Type:
Cost tier separates buyers seeking foundational grist components from those purchasing differentiated flavor and color modifiers.
- Base Malt:Germinated and lightly kilned wheat with enzymatic activity measured in degrees Lintner, supplying the fermentable sugar backbone for Weissbier and wheat ale formulations. Bavarian craft breweries in Munich and surrounding brewing clusters anchor volume demand, with kilning energy documentation now required under EU Green Deal carbon accounting mandates for export qualification.
- Specialty Malt:Extended kilning or roasting regimens develop caramelized and toasted flavor profiles ranging from honey to chocolate. Experimental craft brewers in Oregon and Colorado drive premium pricing for small-lot roasted variants, accepting longer lead times for custom kilning curves that displace traditional distributor procurement.
- Adjunct Malt:Neutral-flavor, low-protein wheat malt serving distillers seeking fermentable substrates without competing aromatics. Kentucky whiskey producers specify protein ranges below 11% for clean vodka mash bills.
- Caramel Malt:Crystal wheat varieties produced through stewing and kilning sequences that develop unfermentable dextrins and toffee notes. Artisan bakers in France source small volumes for sourdough color enhancement.
Base Malt leads volumes today; Specialty Malt is gaining share fastest.
Application:
Volume concentration varies by enzymatic stability requirements and regulatory exposure across beverage versus food processing.
- Brewing:Primary outlet leveraging wheat malt's protein haze and mouthfeel contribution to traditional German-style Weissbier and Belgian witbier. Wisconsin craft breweries expanding dedicated wheat lines pull specialty volumes into new production facilities.
- Distilling:Neutral substrate demand from premium vodka and estate-labeled whiskey producers requiring documented grain provenance. Direct contracting between Tennessee distillers and specialty malters displaces traditional distributor mediation.
- Baking:Malted wheat flour incorporation into sourdough and artisan bread formulations. Italian food manufacturers source enzymatically active flour for crust browning enhancement.
- Food Products:Cereal, snack, and nutritional applications utilizing malted wheat for natural sweetness and label-friendly ingredient positioning.
Brewing commands current volume leadership; Distilling climbs the fastest as clean-label spirits displace corn-based formulations.
End User:
Customer type determines specification stringency, with craft producers demanding traceability that commercial operations treat as optional.
- Craft Breweries:Small-batch producers specifying variety, protein range, and kilning curve in direct purchase agreements. Colorado and Oregon operations receive real-time moisture data via IoT-enabled bulk shipments.
- Commercial Breweries:Large-scale Weissbier manufacturers in Germany and Belgium optimizing for batch consistency and supply security through malting cooperative contracts.
- Bakeries:Artisan sourdough specialists in France and Italy sourcing malted wheat flour for enzymatic crust development and fermentation acceleration.
- Food Manufacturers:Industrial processors integrating malted wheat into cereal and snack formulations for natural sweetness and clean-label positioning.
Commercial Breweries anchor current procurement volumes; Craft Breweries are expanding most quickly as wheat beer portfolios multiply.
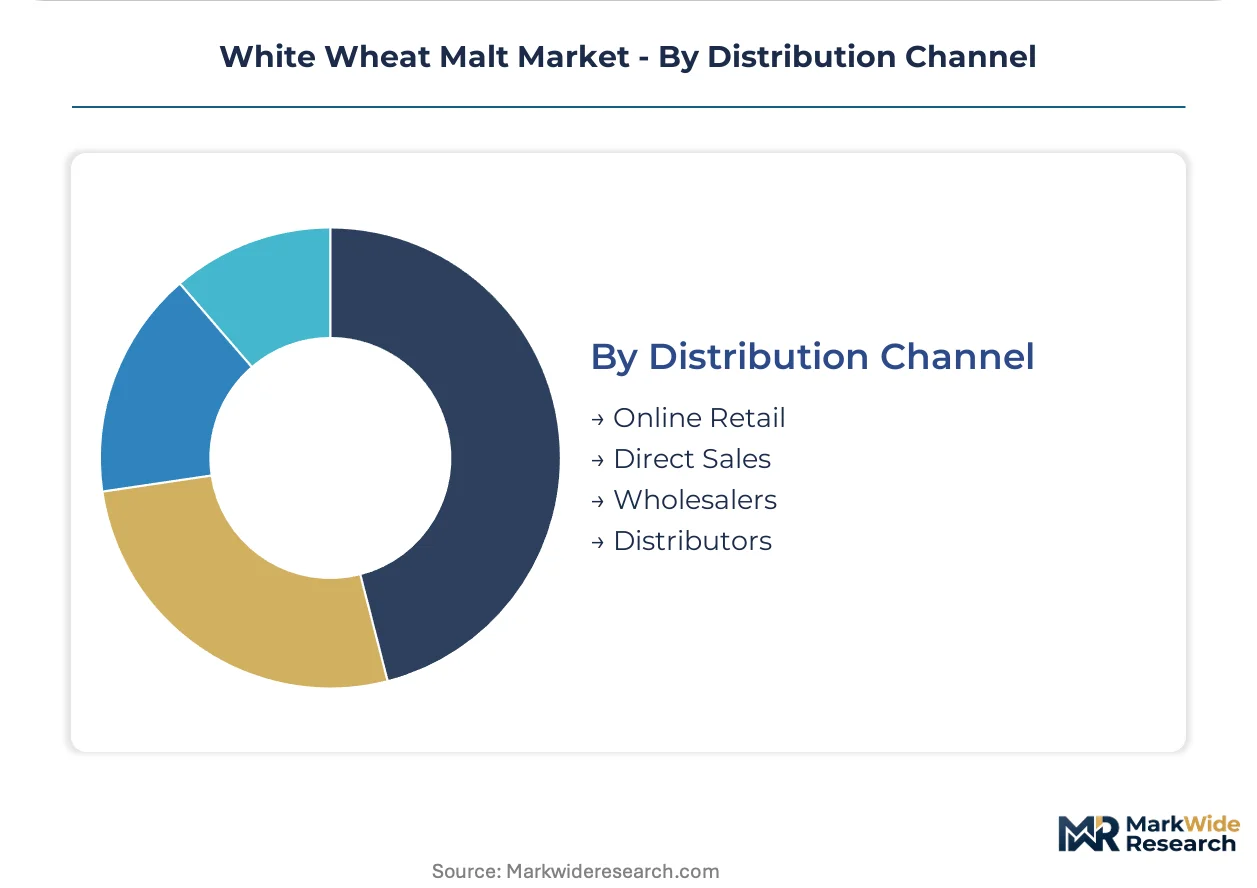
Distribution Channel:
Supply chain configuration determines price realization and specification control, with direct relationships capturing margin from disintermediated procurement.
- Direct Sales:Malting houses contracting directly with craft distillers and breweries for specified variety and kilning parameters. Kentucky and Tennessee whiskey producers now mandate documented grain provenance through farmer-to-producer agreements.
- Distributors:Traditional malt supply intermediaries serving commercial breweries with standardized specifications and volume commitments across Central European brewing clusters.
- Wholesalers:Regional grain merchants consolidating small-lot orders for bakeries and food manufacturers lacking direct malting relationships.
- Online Retail:E-commerce platforms enabling homebrewers and small bakeries to access specialty wheat malt in sub-ton quantities with technical documentation.
Distributors handle the largest tonnage today; Direct Sales is gaining share fastest as provenance documentation becomes contractual.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping malting geography as EU Green Deal carbon accounting raises compliance costs in Europe, pushing specialty wheat malt investment toward North American production bases with lower documented emissions thresholds.
Germany
Bavarian craft breweries in Munich and surrounding brewing clusters anchor continental demand for traditional Weissbier production. EU Green Deal mandates now require farm-level emissions documentation and kilning energy disclosure for export qualification into single markets. Master maltster expertise remains concentrated in traditional Franconian malting houses, though aging specialist demographics threaten knowledge transfer.
United States
Wisconsin craft breweries expanding dedicated wheat beer lines pull specialty volumes into new production facilities across the Great Lakes region. FDA and USDA oversight of grain safety and organic labeling creates parallel compliance tracks for maltsters serving transatlantic customers. Colorado and Oregon operations receive real-time moisture data via IoT-enabled bulk shipments, compressing specification-negotiation cycles.
Belgium
Traditional witbier producers in Flemish brewing clusters sustain demand for lightly kilned wheat malt with delicate spice-compatible aromatics. REACH substance authorization updates tighten residue limits for pesticides used on malting wheat, forcing farm-level integrated pest management certification. Malting cooperatives in the Scheldt River basin now mandate documented sustainability credentials alongside enzymatic specifications.
United Kingdom
Craft distillers in Scotland and England seek traceable grain substrates for estate-labeled spirits requiring documented provenance. Simpsons Malt Limited leverages UK heritage to anchor supply relationships with premium brewing and distilling contracts. Yorkshire and East Anglia malting facilities face kilning energy retrofit costs requiring seven-figure capital outlays for natural gas and electric conversions.
France
Artisan bakers in Paris and Lyon source malted wheat flour for sourdough formulations, opening non-beverage revenue streams for regional maltsters. ANSM and national food safety frameworks govern agricultural input traceability across French malting supply chains. Alsatian brewing traditions near the German border sustain cross-border wheat malt procurement with specialized protein specifications.
White Wheat Malt Market Competitive Landscape
European malting cooperatives anchor one tier; North American specialists hold capacity advantages in wheat-specific kilning infrastructure. Market structure tilts toward consolidated procurement relationships between large-scale malting houses and commercial breweries, with fragmented craft-distiller direct contracting emerging as a counter-trend. Three archetypes dominate: heritage European cooperatives with master maltster knowledge, North American scale players with dedicated wheat lines, and Nordic logistics specialists with cold-chain capabilities. Competitive moves concentrate on sustainability certification acquisition and direct-to-producer disintermediation.
Within the heritage cooperative tier, Simpsons Malt Limited and Viking Malt exemplify geographic specialization strategies—UK and Nordic anchoring respectively—while Briess Malt & Ingredients Co. occupies a position among North American scale players with dedicated wheat malting infrastructure. These three represent contrasting responses to EU Green Deal compliance pressure: European-origin players face embedded retrofit costs, while US-based operations capture investment flows seeking lower carbon-accounting thresholds.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Simpsons Malt Limited |
| Briess Malt & Ingredients Co. |
| Gladfield Malt |
| Great Western Malting |
| Viking Malt |
| MaltEurope |
| Malteurop |
| Rahr Corporation |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon accounting mandates gate qualified supply access and premium-tier pricing power for malting houses serving export-facing breweries. Compliance documentation requirements compress margin pools for non-certified operators while concentrating pricing leverage among early sustainability adopters.
Pricing Analysis
Distributor margins compress as direct-to-distiller contracting accelerates across North American markets. Three-tier pricing structure across premium organic, standard specialty, and economy base malt levels stratifies by certification grade and volume commitment. Pricing pressure stems from kilning energy retrofit costs forcing mid-cap malters to absorb margin erosion. Craft distillers exhibit lowest price sensitivity due to provenance documentation requirements, while commercial breweries negotiate aggressively on standard specifications.
Supply Chain Analysis
EU organic and REACH certification gates supplier qualification for breweries exporting into single markets. Geographic concentration centers on Germany, Belgium, and the United States for premium malting wheat varieties. Raw material dependencies include specific wheat breeding stocks, natural gas or electric kiln energy, and integrated pest management inputs. Single-region sourcing concentration in Central European breeding programs exposes buyers to climate volatility. Distribution runs through malting cooperative networks serving commercial breweries alongside direct farmer-to-producer channels for craft distillers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where craft distiller demand for documented grain provenance shifts procurement toward premium specifications with traceability premiums.
For Market Incumbents: Anchor defensive positioning through backward integration into certified wheat acreage and master maltster knowledge transfer programs. Invest in cold-chain logistics infrastructure to preserve enzymatic stability for remote craft customers. Threats from hop-forward style displacement in North American craft markets demand portfolio diversification into distilling adjunct supply. For New Entrants and Emerging Players: Capture white-space opportunity in organic-certified specialty malt for estate-labeled spirits and artisan bread ingredient supply. The most penetrable segment lies in Nordic and Baltic craft distiller markets lacking local malting capacity. Go-to-market execution should leverage direct contracting with documented sustainability credentials as the primary wedge. For Investors and Strategic Acquirers: Roll-up economics work for regional malting specialists with certified organic wheat supply relationships because fragmented craft-distiller procurement patterns favor consolidated technical service capabilities. Long-term viability hinges on sustainability certification moats and kilning expertise scarcity. Watch for inflection signals in carbon accounting rule harmonization between EU and US regulatory frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Acreage Conversion | EU Green Deal compliance secures premium brewing contracts with Bavarian craft producers. |
| Precision Kilning Automation Investment | IoT-enabled quality data compresses specification cycles for Colorado and Oregon breweries. |
| Cold-Chain Distribution Buildout | Temperature-controlled logistics preserve enzymatic stability for remote Nordic distilleries. |
| Direct Farmer Contracting Programs | Documented grain provenance satisfies Kentucky estate-labeled whiskey requirements. |
| Master Maltster Apprenticeship Expansion | Wheat-specific kilning expertise transfer addresses aging specialist demographic risk. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged malting house technical directors, craft brewery procurement managers, distillery sourcing leads, and agricultural cooperative agronomists. Secondary validation drew from EU ETS emissions databases, USDA organic certification records, REACH substance authorization updates, and customs trade flows for malting wheat varieties. Bottom-up volume estimates from facility-level capacity triangulated against top-down demand projections from brewing and distilling output data.
Segment-weighting applied product type, application, end user, and distribution channel dimensions across the modeling period. CAGRs derived from regression analysis of historical pricing and volume trajectories, adjusted for regulatory phase-in schedules and sustainability certification adoption curves. Forecast inputs incorporated kilning energy cost trajectories, wheat protein yield volatility patterns, and craft distiller direct contracting penetration rates.
Regulatory enforcement variance, wheat crop yield disruption, and craft beer style preference shifts are the dominant revision risks. Deviation in EU carbon accounting implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
India Starch and Starch Derivative Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
Oat Fiber Market
Ingredients
Global Amaranth Oil Market
Ingredients
Low Calorie Cooking Oil Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Microbial Food Ingredients Market
Ingredients
Banana Essence Market
Ingredients
Spain Fermentation Ingredients Market
Ingredients
Africa Food Ingredients Market
Ingredients
Chickpea Flour Market
Ingredients
Soy Flour Market
Ingredients
Organic Edible Oil Market
Ingredients
Hibiscus Extract Market
Ingredients
Fermented Ingredients Market
Ingredients
Agar Agar Flakes Market